
 Solar Components Recycling Market | 2026-2036
Solar Components Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Components Recycling Market Analysis
End-of-life module processing revenue is reshaping competitive positioning across the solar value chain. First Solar leverages its vertically integrated thin-film manufacturing to anchor closed-loop cadmium telluride recovery operations in Ohio and Malaysia. Veolia Environment competes through industrial-scale glass and aluminum separation infrastructure serving European decommissioning projects. Aurubis AG specializes in copper and silver recovery from crystalline silicon cells, extending its non-ferrous metals expertise into photovoltaic waste streams.
Solar components recycling encompasses the collection, dismantling, and material recovery of decommissioned photovoltaic systems, typically processing modules containing 65-75% glass, 10-15% polymer encapsulants, and trace quantities of silver, copper, and semiconductor-grade silicon. Mechanical shredding followed by thermal delamination remains the dominant industrial method for separating laminate layers, though chemical etching achieves higher semiconductor purity for resale to wafer manufacturers. Solar panels constitute the largest product type segment by volume, reflecting the sheer mass of crystalline silicon modules approaching end-of-life across early-adopter markets. Chemical recycling represents the fastest-expanding technology category, as hydrometallurgical routes recover higher-value metals with lower energy intensity than pyrometallurgical alternatives.
The EPA regulates photovoltaic waste under the Resource Conservation and Recovery Act, while the EU's WEEE Directive and REACH framework impose extended producer responsibility and restricted substance thresholds on module imports. California's DTSC has advanced panel-specific universal waste rules that reduce hazardous classification burdens for collectors. Stakeholders must monitor how China's evolving solid waste import bans and domestic circular economy mandates redirect Asian recycling capacity and material flows.
Market Dynamics
The first wave of crystalline silicon installations from the 2010s is reaching end-of-life simultaneously across Germany, Italy, and California, forcing recyclers to scale mechanical shredding and thermal delamination capacity ahead of chemical etching maturation.
Growth Catalysts
- EU WEEE Directive amendments:Producer-financed take-back schemes now mandate module collection across member states, redirecting capital toward recycling infrastructure.
- Silver recovery economics:Hydrometallurgical routes extract semiconductor-grade silver from crystalline cells at yields that justify processing costs for utility-scale decommissioning contractors.
- Ohio and Malaysia:These clusters anchor thin-film closed-loop operations that recover cadmium telluride for wafer remanufacturing.
Market Restraints
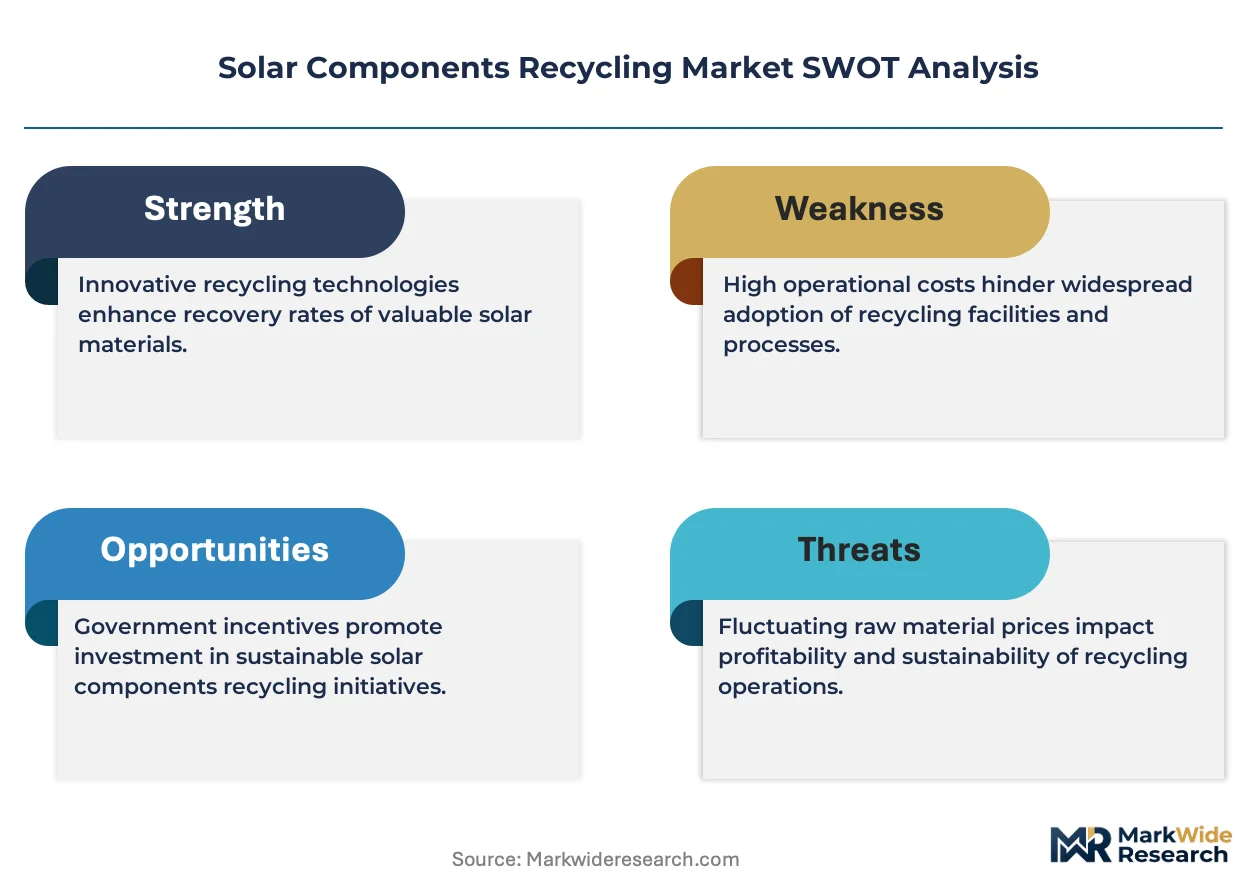
- Polymer encapsulant separation costs:Thermal delamination of ethylene-vinyl acetate layers consumes 40% of processing energy, compressing margins for mechanical recyclers.
- Chinese domestic circular economy mandates:Beijing's solid waste import bans have stranded Asian capacity, forcing European operators to absorb regional volume spikes without corresponding infrastructure expansion.
- Semiconductor-grade silicon purity gaps:Pyrometallurgical recovery achieves 99.5% purity against 99.9999% wafer specifications, limiting resale channels to lower-value aluminum alloying.
Strategic Opportunities
- India's CEA decommissioning guidelines:Draft rules for photovoltaic waste classification create first-mover positioning for hydrometallurgical technology licensors.
- Glass-to-glass recycling:Direct furnace feed from shredded module fronts bypasses container glass contamination penalties, opening construction aggregate substitution markets.
- Chemical etching convergence with battery recycling:Shared lithium-ion and silicon cell acid recovery infrastructure spreads capital intensity across dual waste streams.
Industry Challenges
- EPA RCRA hazardous classification uncertainty:State-by-state variance in photovoltaic universal waste rules forces multi-jurisdictional compliance architectures.
- Semiconductor process engineering talent scarcity:Recovery facilities compete with wafer manufacturers for chemical etching specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Components Recycling Market |
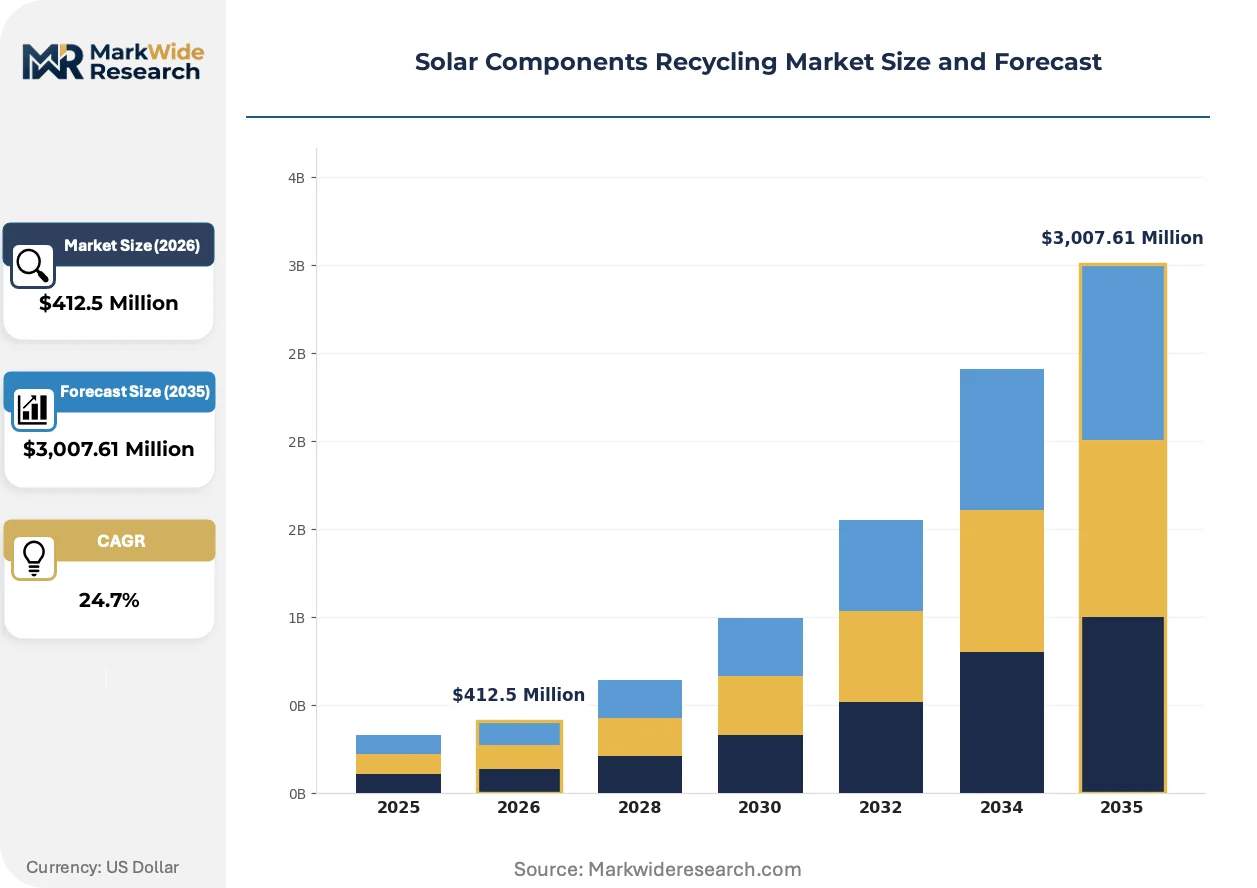
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,007.61 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Cells, Inverters, Solar Panels, Batteries Technology: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Biochemical Recycling End User: Manufacturers, Waste Management Companies, Government, Research Institutions Application: Material Recovery, Energy Production, Waste Reduction, Sustainability Initiatives |
| Companies Covered | First Solar, Reiling GmbH & Co. KG, SOLARCYCLE, Inc., Veolia Environment, Aurubis AG, Reclaim PV Recycling, Rinovasol Global Services B.V., SILCONTEL LTD, Echo Environmental, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Components Recycling Market Emerging Trajectories
Processing technology is bifurcating between high-volume mechanical routes for glass and aluminum recovery versus precision chemical systems targeting semiconductor resale. This divergence is reshaping facility economics and geographic placement.
Robotic dismantling systems equipped with near-infrared polymer identification are digitizing sort-line throughput for mixed-waste facilities. German decommissioning contractors deploy these units to separate encapsulant grades before thermal treatment. The digitization of material tracking enables real-time purity certification for downstream glass buyers.
California's DTSC universal waste rules reduce hazardous classification burdens for collectors handling crystalline silicon modules. The regulation shifts liability upstream to original manufacturers under extended producer responsibility frameworks. Utility-scale solar farm operators in the state now consolidate end-of-life inventory for bulk shipment to permitted processors rather than on-site storage.
Long-term service contracts bundled with decommissioning guarantees are displacing spot-market module collection for European utility portfolios. Asset owners in France and Italy negotiate 25-year take-back clauses with original suppliers. This contractualization concentrates volume with vertically integrated manufacturers and marginalizes independent mechanical recyclers lacking backward integration into module production.
Solar Components Recycling Market Segmentation
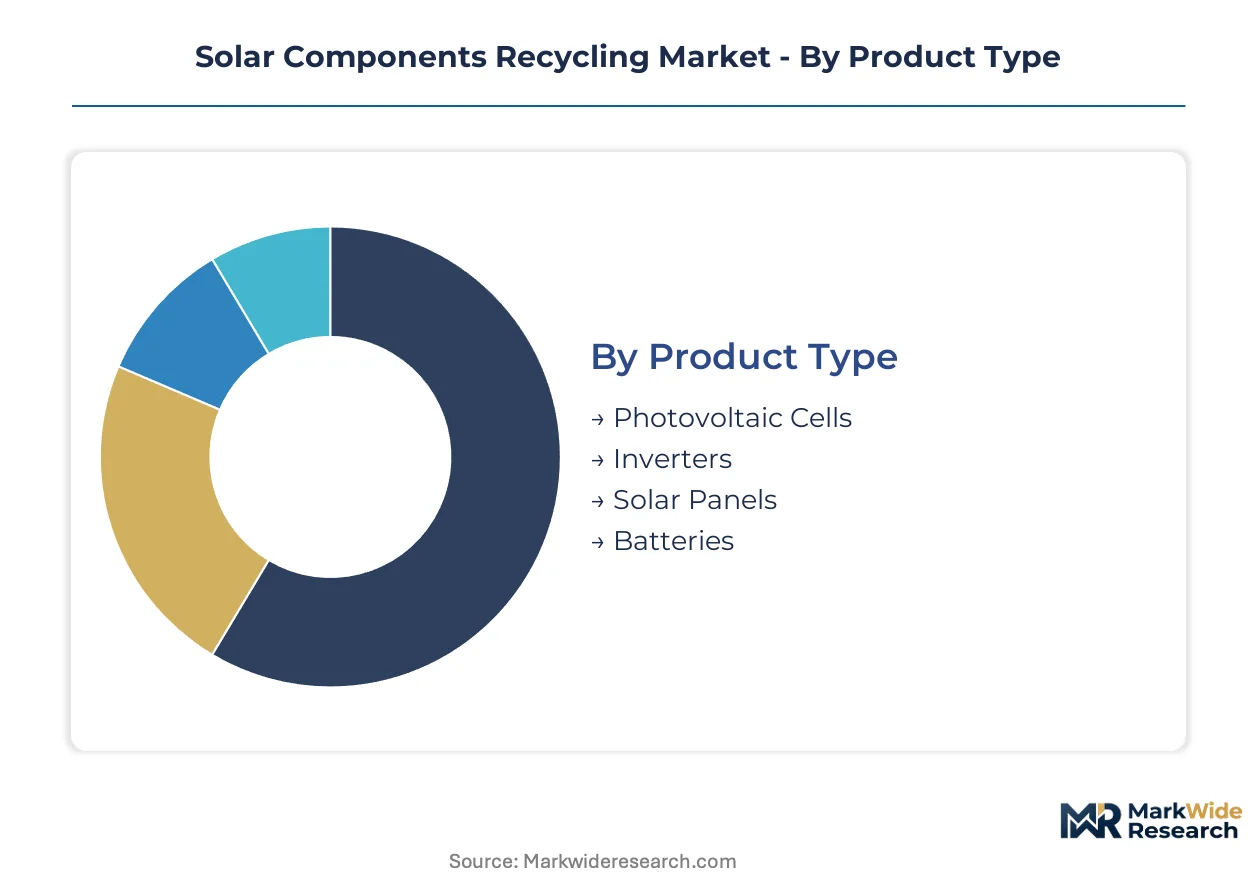
Module retirement waves arrive unevenly across component categories, forcing recyclers to match processing capacity with distinct material lifecycles and recovery economics. Understanding segment turnover patterns separates mechanical commodity operators from precision chemical recovery specialists.
Product Type:
Cycle times diverge sharply: solar panels and batteries reach end-of-life within 25-30 years of installation, while inverters fail and recycle faster at 10-15 year intervals, and photovoltaic cells from manufacturing scrap turn over continuously.
- Solar Panels:Crystalline silicon modules contain 65-75% glass, 10-15% polymer encapsulants, and recoverable silver traces. German and Italian decommissioning contractors concentrate demand here as early-adopter utility-scale installations age out simultaneously.
- Photovoltaic Cells:Semiconductor-grade silicon wafers and thin-film cadmium telluride layers require hydrometallurgical or chemical etching routes. Ohio and Malaysia host closed-loop recovery operations that remanufacture telluride for First Solar's thin-film production.
- Inverters:Power electronics containing copper windings, aluminum heat sinks, and circuit boards recycle through standard e-waste infrastructure. Shorter replacement cycles generate steadier feedstock than module decommissioning.
- Batteries:Lithium-ion storage systems from residential and utility installations demand specialized thermal runaway containment and cobalt-lithium separation. Shared acid recovery infrastructure with silicon cell processing spreads capital intensity.
Solar panels anchor the volume base while photovoltaic cells gain share at the steepest rate.
Technology:
Cost tiers separate commodity glass-aluminum recovery from premium semiconductor resale, with mechanical routes dominating capital deployment and chemical systems capturing margin expansion.
- Mechanical Recycling:Shredding and density separation recover bulk glass and aluminum at lowest unit cost. European decommissioning projects rely on this route for utility-scale volume, though thermal delamination of ethylene-vinyl acetate consumes 40% of processing energy.
- Chemical Recycling:Hydrometallurgical etching achieves 99.9999% silicon purity for wafer remanufacturing and extracts silver at yields justifying processing costs. India's CEA draft guidelines create first-mover positioning for technology licensors.
- Thermal Recycling:Pyrometallurgical smelting recovers copper and silver at 99.5% purity, limiting resale to aluminum alloying rather than semiconductor channels. Aurubis AG extends non-ferrous metals expertise through this route.
- Biochemical Recycling:Microbial leaching of rare earth elements and specialty metals remains pre-commercial, with pilot operations targeting lower energy intensity than acid-based alternatives.
Mechanical recycling dominates installed capacity while chemical recycling climbs the fastest.
End User:
Customer type determines contract structure, with manufacturers seeking closed-loop feedstock security and waste management companies competing for spot-market decommissioning volumes.
- Manufacturers:First Solar and crystalline silicon producers anchor closed-loop cadmium telluride and semiconductor silicon recovery. Long-term service contracts bundle decommissioning guarantees with original equipment sales.
- Waste Management Companies:Veolia Environment and industrial-scale operators compete for European decommissioning project tenders. Glass-to-glass recycling bypasses container glass contamination penalties for construction aggregate substitution.
- Government:EU member states implement producer-financed take-back schemes under WEEE Directive amendments, redirecting capital toward recycling infrastructure.
- Research Institutions:National laboratories and universities pilot biochemical leaching and robotic dismantling systems equipped with near-infrared polymer identification.
Waste management companies concentrate spot-market volume while manufacturers expand share through contractualization.
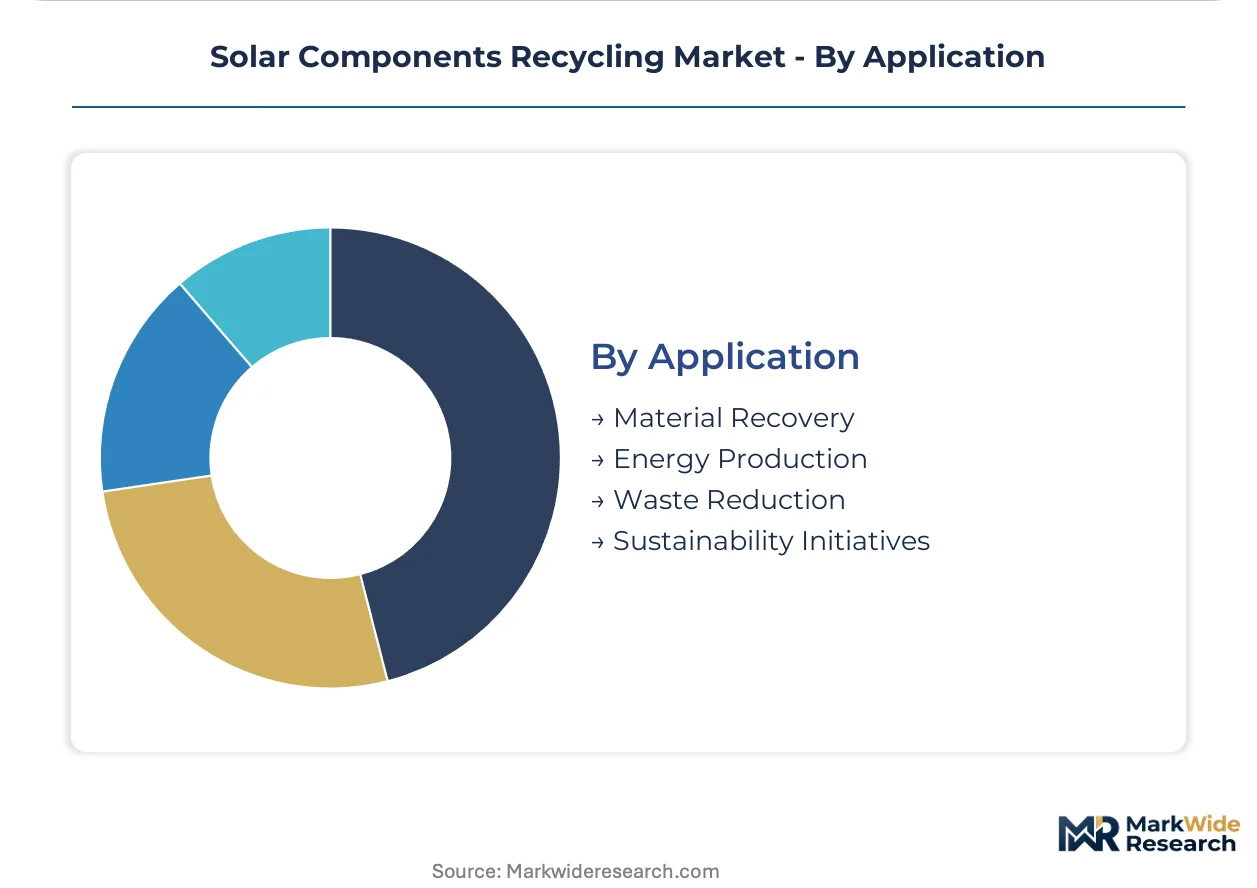
Application:
Application focus separates commodity revenue streams from strategic positioning, with material recovery generating immediate cash flow and sustainability initiatives driving regulatory compliance and brand value.
- Material Recovery:Glass, aluminum, copper, silver, and semiconductor-grade silicon resale constitute primary revenue. California's DTSC universal waste rules reduce hazardous classification burdens for collectors handling crystalline silicon modules.
- Waste Reduction:Landfill diversion metrics satisfy extended producer responsibility frameworks and ESG reporting requirements under EU CSRD.
- Energy Production:Thermal treatment of polymer encapsulants and backsheet materials generates process heat for co-located industrial facilities.
- Sustainability Initiatives:Circular economy certification and carbon footprint reduction support original manufacturers' green marketing and regulatory compliance.
Material recovery anchors revenue while sustainability initiatives expand fastest as regulatory drivers intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
End-of-life processing economics diverge sharply across geographies. Germany and Italy prioritize high-purity semiconductor recovery, while the United States emphasizes bulk glass-aluminum commodity streams and China scales pyrometallurgical capacity under domestic circular economy mandates.
Germany
Utility-scale decommissioning contractors process crystalline silicon modules from 2010s installations reaching end-of-life simultaneously. The country's national environmental regulator enforces extended producer responsibility under amended WEEE Directive frameworks. North Rhine-Westphalia hosts industrial-scale mechanical shredding infrastructure serving cross-border volume from France and the Netherlands.
United States
California's DTSC universal waste rules reduce hazardous classification burdens for collectors handling crystalline silicon modules. The EPA regulates photovoltaic waste under the Resource Conservation and Recovery Act with state-by-state variance. Ohio anchors thin-film closed-loop operations that recover cadmium telluride for wafer remanufacturing.
China
Domestic circular economy mandates redirect Asian recycling capacity toward internal volume as solid waste import bans strand regional processing infrastructure. The Ministry of Ecology and Environment advances producer responsibility pilots for photovoltaic waste classification. Jiangsu and Zhejiang provinces concentrate pyrometallurgical smelting capacity for copper and silver recovery.
India
Draft decommissioning guidelines from the Central Electricity Authority create first-mover positioning for hydrometallurgical technology licensors. The Bureau of Indian Standards develops photovoltaic waste classification protocols aligned with circular economy objectives. Gujarat and Rajasthan concentrate early recycling infrastructure investment adjacent to solar park clusters.
France
Asset owners negotiate 25-year take-back clauses with original suppliers, concentrating volume with vertically integrated manufacturers. ANSM and environmental regulators enforce REACH framework restricted substance thresholds on module imports. The Provence-Alpes-Côte d'Azur region hosts glass-to-glass recycling operations bypassing container glass contamination penalties.
Solar Components Recycling Market Vendor Landscape
Capability concentration sits with chemical recovery specialists; scale advantage sits with industrial waste operators. The market structures around three tiers: vertically integrated thin-film manufacturers controlling closed-loop material flows, industrial-scale mechanical processors capturing utility decommissioning volume, and non-ferrous metals specialists extending expertise into photovoltaic waste streams. Dominant competitive moves include long-term service contract bundling and geographic clustering near early-adopter installation bases.
Among Germany-based specialists, Reiling GmbH & Co. KG exemplifies industrial-scale glass and aluminum separation infrastructure. First Solar, an Ohio-based thin-film manufacturer, anchors closed-loop cadmium telluride recovery operations. Aurubis AG, a German non-ferrous metals processor, occupies a position extending copper and silver recovery expertise into crystalline silicon cell processing.
| Leading Market Players |
|---|
| First Solar |
| Reiling GmbH & Co. KG |
| SOLARCYCLE, Inc. |
| Veolia Environment |
| Aurubis AG |
| Reclaim PV Recycling |
| Rinovasol Global Services B.V. |
| SILCONTEL LTD |
| Echo Environmental, LLC |
| Others |
Supply Flow & Price Mechanics
German and Italian mechanical shredding infrastructure concentrates upstream capacity for ethylene-vinyl acetate thermal delamination, anchoring margin pools with European decommissioning contractors who control long-term service contract pricing. This geographic supply clustering forces downstream buyers into volume-commitment structures that insulate processors from spot-market volatility.
Pricing Analysis
Long-term service contracts bundled with decommissioning guarantees dominate crystalline silicon module processing, displacing spot-market collection for utility-scale portfolios. Price differentiation rests on semiconductor purity grade and WEEE Directive compliance certification, with hydrometallurgical routes commanding premiums over mechanical shredding. Cost compression in thermal delamination operations is intensifying because ethylene-vinyl acetate separation consumes disproportionate energy inputs. Independent mechanical recyclers exhibit highest price sensitivity, while vertically integrated thin-film manufacturers with captive telluride recovery absorb cost fluctuations through closed-loop economics.
Supply Chain Analysis
Extended payment terms from European decommissioning contractors to shredding equipment suppliers reveal supply-chain finance concentration in German and Italian processing clusters. Raw material flows draw from Ohio and Malaysia for cadmium telluride, Jiangsu and Zhejiang provinces for pyrometallurgical smelting capacity, and North Rhine-Westphalia for cross-border glass separation. Single-source vulnerability sits with semiconductor-grade silicon etching chemical suppliers concentrated in East Asian specialty chemical production. Distribution runs through permitted waste processors under EPA RCRA and EU WEEE regulatory frameworks, with liability shifting upstream to original manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among European utility-scale asset owners negotiating 25-year take-back clauses, fragmenting volume access for independent processors and reshaping contract economics across the recycling value chain.
For Market Incumbents: Build regulatory compliance moats through WEEE Directive certification investment and REACH framework restricted substance management systems. First Solar's closed-loop cadmium telluride recovery in Ohio and Malaysia demonstrates how backward integration into thin-film manufacturing insulates against hydrometallurgical technology licensors. Incumbents must add thermal delamination capacity in Germany and Italy ahead of chemical etching maturation, as polymer encapsulant separation costs compress margins for mechanical-only operators. For New Entrants and Emerging Players: Establish a beachhead in India's hydrometallurgical technology licensing market where CEA draft decommissioning guidelines create first-mover positioning before formal photovoltaic waste classification. The most penetrable segment sits with biochemical recycling pilot operations targeting lower energy intensity than acid-based alternatives for rare earth element recovery. Go-to-market execution should emphasize shared lithium-ion and silicon cell acid recovery infrastructure that spreads capital intensity across dual waste streams. For Investors and Strategic Acquirers: Capital is best deployed toward chemical recovery specialists with semiconductor-grade silicon purity capabilities, as pyrometallurgical alternatives face 99.5% purity ceilings against wafer specifications. Long-term viability across the analysis window favors facilities with robotic dismantling systems equipped with near-infrared polymer identification for digitized sort-line throughput. The signal to monitor is EPA RCRA hazardous classification harmonization, which would eliminate state-by-state variance compliance costs and revalue permitted processor networks.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Material Recovery | First Solar's Ohio and Malaysia telluride remanufacturing secures captive semiconductor supply against spot-market volatility. |
| Robotic Dismantling Deployment | German contractors deploy near-infrared polymer identification to digitize throughput for mixed-waste facilities. |
| Hydrometallurgical Licensing | India's CEA draft guidelines position technology licensors for first-mover advantage in formal regulation. |
| Glass-to-Glass Recycling Infrastructure | Provence-Alpes-Côte d'Azur operations bypass container glass contamination penalties for construction aggregate markets. |
| Dual-Stream Acid Recovery | Shared lithium-ion and silicon cell infrastructure spreads capital intensity across battery and photovoltaic waste. |
Methodological Framework
Desk research of EPA RCRA regulatory filings, EU WEEE Directive amendments, and national circular economy mandates preceded structured interviews with decommissioning contractors, photovoltaic waste processors, and thin-film manufacturing operations heads. Secondary validation drew from customs and trade data for module import flows, SEC 10-K disclosures for vertically integrated manufacturers, and national environmental regulator enforcement patterns. Bottom-up capacity modeling triangulated against top-down revenue estimates from mechanical shredding and chemical etching facility operators.
Assumptions held fixed include WEEE Directive extended producer responsibility enforcement intensity and China's solid waste import ban continuity, while technology cost curves and silver recovery yields were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, processing technology, end-user category, and application focus across the projection horizon. CAGRs were derived from installed base retirement curves and capacity expansion timelines, with semiconductor-grade purity thresholds and thermal delamination energy costs as key forecast inputs.
Sensitivities concentrate around EPA hazardous classification harmonization, EU CSRD circular economy disclosure requirements, and hydrometallurgical technology maturation timelines. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost trajectories. Macroeconomic contraction, regulatory deviation, or breakthrough biochemical leaching commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market