
 Battery Recycling Market | 2026-2036
Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Recycling Market Analysis
Collection infrastructure for spent lithium-ion cells is narrowing as regional processors consolidate logistics networks. Umicore leverages its integrated smelter-refinery complex in Belgium to recover cobalt and nickel at battery-grade purity. Glencore anchors African copper-cobalt feedstock flows into European refining circuits. Cirba Solutions specializes in North American collection and preprocessing, operating one of the continent's largest battery sorting facilities.
Battery recycling recovers valuable metals from end-of-life electrochemical cells through pyrometallurgical or hydrometallurgical extraction, yielding cobalt sulfate, nickel sulfate, and lithium carbonate for cathode precursor resynthesis. The process requires controlled dismantling to prevent thermal runaway, followed by selective leaching that achieves over 95% metal recovery rates in advanced facilities. Lithium-ion batteries dominate feedstock volumes as electric vehicle retirement curves steepen, while lead-acid recycling remains structurally mature with compressed margins. Hydrometallurgy attracts capital for its lower carbon intensity and direct recovery of battery-grade salts, whereas pyrometallurgy retains scale advantages for mixed-metal feeds.
The EU Battery Regulation and ECHA REACH framework mandate minimum recycled content ratios and restrict hazardous substance thresholds, compelling OEMs to secure qualified recycling partnerships. The US EPA and state-level extended producer responsibility programs shape collection network economics through fee structures and landfill bans. Stakeholders must monitor regulatory calibration timelines and feedstock availability gaps as first-generation EV batteries reach end-of-life at scale.
Market Dynamics
Automotive OEMs now mandate closed-loop cathode material supply chains, forcing recyclers to secure battery-grade purity certifications ahead of first-generation EV retirement curves. This structural pressure compresses qualification timelines while concentrating processing capacity among integrated smelter-refinery operators.
Growth Catalysts
- EU Battery Regulation recycled content thresholds:Mandatory minimums for lithium, cobalt, and nickel in new batteries compel OEMs to offtake from qualified recyclers rather than primary miners.
- Electric vehicle retirement acceleration:Early Tesla Model S and Nissan Leaf battery packs reaching end-of-life create immediate feedstock volume for hydrometallurgical processors.
- Hydrometallurgy's carbon intensity advantage:Direct recovery of battery-grade salts without high-temperature smelting attracts ESG-linked capital and OEM offtake agreements.
Market Restraints
- African copper-cobalt supply concentration:DRC and Zambian ore flows dominate feedstock for European refiners, exposing circuits to export duty volatility and logistics disruption.
- Lithium carbonate price cyclicality:Spodumene and brine price crashes compress black mass payables and recycler margin structures.
- Collection infrastructure fragmentation:Sparse dismantling capacity outside China, Germany, and South Korea forces long-haul transport of hazardous cells.
Strategic Opportunities
- North American preprocessing scale-up:The US EPA's emerging extended producer responsibility frameworks and state landfill bans create regulatory tailwinds for domestic sorting and black mass production.
- Solid-state battery feedstock preparation:Sulfide and oxide solid electrolyte chemistries require novel separation protocols that first-mover recyclers can patent.
- Direct recycling technology convergence:Cathode relithination paired with hydrometallurgical purification offers closed-loop precursor resynthesis without full elemental decomposition.
Industry Challenges
- Battery-grade purity certification timelines:OEM qualification protocols for recycled cobalt sulfate and nickel sulfate extend 18-24 months, delaying revenue recognition.
- Thermal runaway containment capex:Inert atmosphere dismantling lines and cryogenic shredding require capital intensity that strains mid-scale processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Recycling Market |
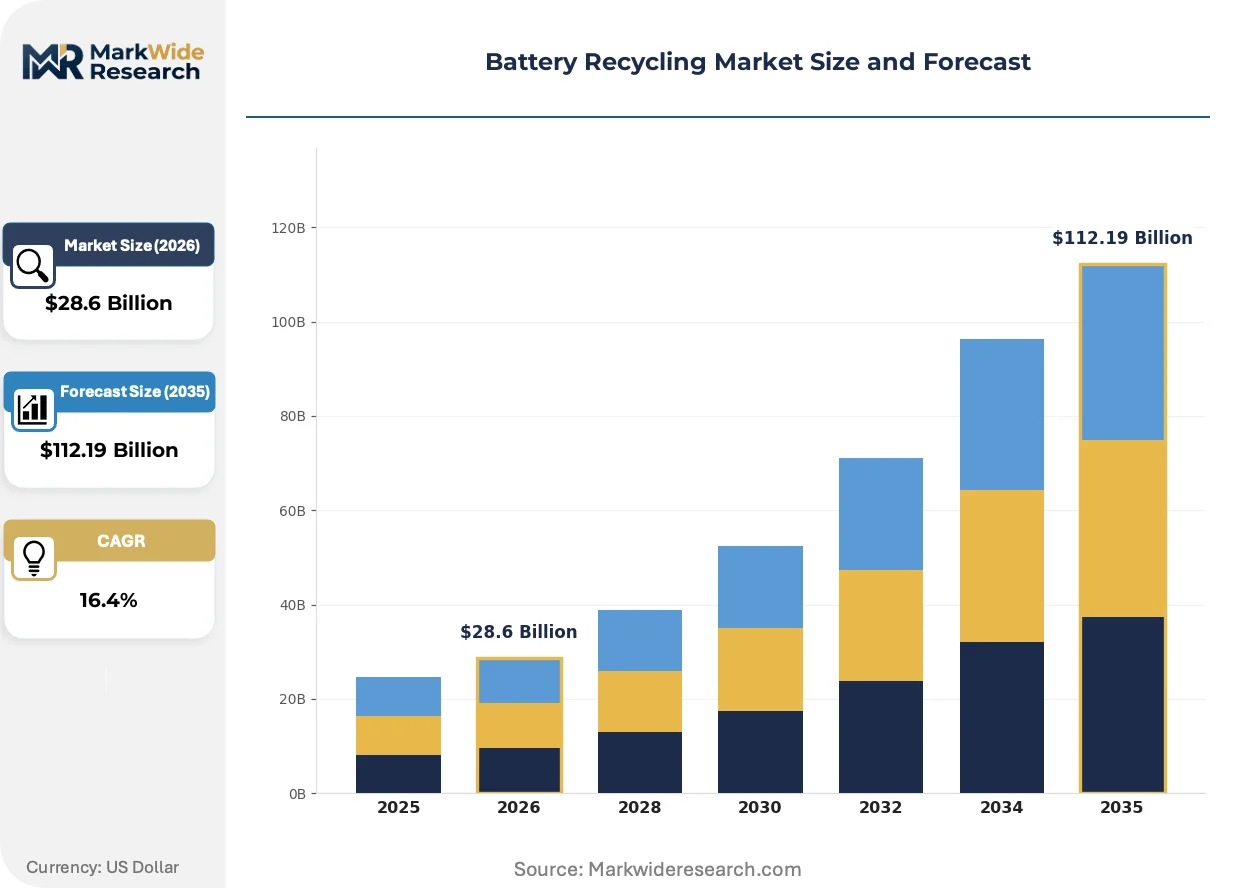
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Drop-off Centers, Mobile Collection, Retail Partnerships, Curbside Collection Battery Type: Lead-acid, Lithium-ion, Nickel-cadmium, Alkaline End User: Manufacturers, Automotive, Electronics, Government Recycling Process: Hydrometallurgy, Pyrometallurgy, Direct Recycling, Mechanical Recycling |
| Companies Covered | Umicore, Li-Cycle Holdings Corp., GEM Co. Ltd., Glencore, Call2Recycle, Cirba Solutions, Contemporary Amperex Technology Co. Limited, Ecobat, Fortum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Recycling Market Emerging Trajectories
Direct cathode recycling is compressing traditional hydrometallurgical flowsheets by preserving crystalline structures rather than dissolving and reprecipitating metals. This shift reconfigures processor economics around relithination yield rather than elemental recovery rates alone.
Direct cathode recycling regenerates spent lithium iron phosphate and nickel-manganese-cobalt cathodes through relithiation and thermal reconditioning. BMW and Volkswagen pilot programs are adopting these flowsheets for in-house pilot lines. The technology is rendering obsolete full hydrometallurgical dissolution for high-value cathode chemistries where structure preservation proves economically superior.
REACH authorization requirements under ECHA now restrict hazardous substance thresholds in recycled content destined for European battery manufacturing. Industrial consequence includes mandatory supply chain due diligence documentation from black mass through precursor. Cathode precursor producers serving European automotive OEMs face the steepest compliance burden and are consolidating qualified recycler partnerships.
Automotive OEMs now unbundle recycling services from cell procurement contracts, creating spot-market mechanisms for black mass and recovered salts. Tier-1 battery manufacturers respond by building captive recycling capacity to retain material control. Germany and South Korea exhibit the most advanced contract structuring, with US OEMs lagging in procurement model sophistication.
Battery Recycling Market Segmentation
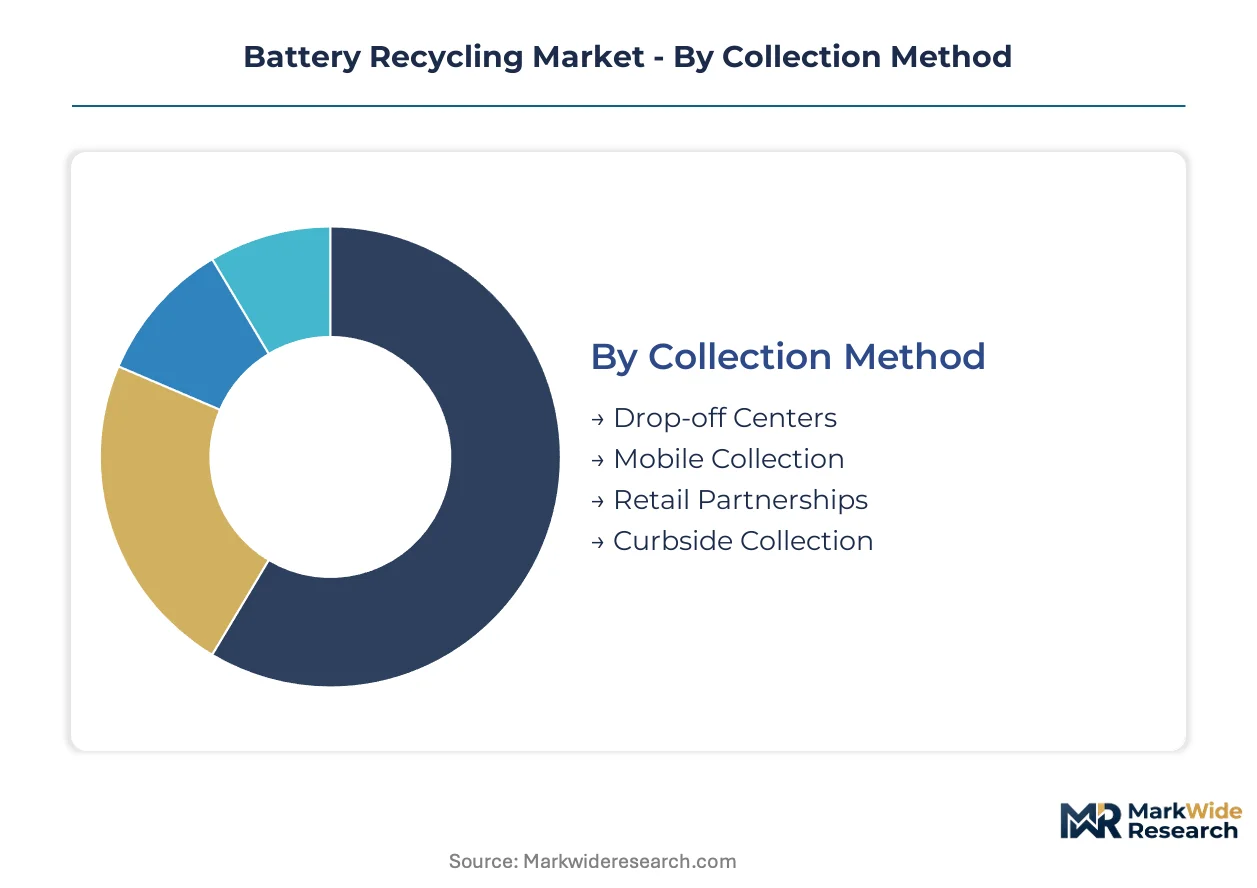
Segmentation in battery recycling determines logistics economics, processing technology selection, and regulatory compliance pathways. Collection density and battery chemistry heterogeneity drive fundamentally different capital deployment strategies across processor tiers.
Collection Method:
After-sales service intensity peaks in collection networks requiring reverse logistics coordination and hazardous material handling certification at scale.
- Drop-off Centers:Fixed facilities at retail locations or municipal sites aggregate consumer and small commercial volumes. Germany's dual collection system and California's CalRecycle network demonstrate how density mandates shape facility placement economics.
- Mobile Collection:Fleet-based retrieval services target industrial generators and remote automotive service centers. The US EPA's universal waste regulations enable transporter consolidation without full hazardous waste manifesting, compressing cost per kilogram for dispersed feedstock.
- Retail Partnerships:Big-box electronics chains and auto parts distributors serve as aggregation nodes. These arrangements transfer liability upstream while capturing consumer convenience premiums.
- Curbside Collection:Municipal solid waste integration remains rare due to thermal runaway risks and contamination with household refuse. Pilot programs in South Korean metropolitan districts test containerized segregation protocols.
By volume, Drop-off Centers leads. By growth pace, Mobile Collection is expanding most quickly.
Battery Type:
Cost tier stratification separates commodity-scale lead-acid recovery from high-value lithium-ion processing requiring advanced separation technology.
- Lithium-ion:Cobalt, nickel, and lithium recovery from EV and consumer electronics cells commands premium pricing for battery-grade sulfates and carbonates. Hydrometallurgical investments concentrate on NMC and LFP chemistries as automotive retirement curves steepen.
- Lead-acid:Mature smelting infrastructure achieves near-total lead recovery at compressed margins. The chemistry dominates recycling tonnage through automotive starter battery replacement cycles.
- Nickel-cadmium:Industrial backup power and aviation applications generate concentrated but declining volumes. Cadmium toxicity triggers stringent REACH and EPA manifesting requirements.
- Alkaline:Consumer primary cells yield marginal metal value; collection serves landfill diversion goals rather than material recovery economics.
By revenue contribution, Lithium-ion leads. By tonnage throughput, Lead-acid retains dominance.
End User:
Application-specific purity requirements and contract structuring differentiate procurement behavior across customer categories.
- Automotive:OEM closed-loop mandates and EU Battery Regulation recycled content thresholds create qualified supplier scarcity. Volkswagen, BMW, and Hyundai Motor Group negotiate long-term offtake with processor certification timelines.
- Manufacturers:Cathode precursor producers and cell makers source recovered cobalt sulfate and nickel sulfate to hedge primary metal price volatility. Qualification protocols extend 18-24 months for battery-grade certification.
- Electronics:Consumer device brands face extended producer responsibility frameworks in EU member states and emerging US state legislation. Black mass payables track lithium carbonate spot markets.
- Government:Defense and grid storage procurement emphasizes supply chain security over unit cost, creating premium pricing tiers for domestic processing.
By contract value concentration, Automotive leads. By procurement model innovation, Manufacturers are gaining share fastest.
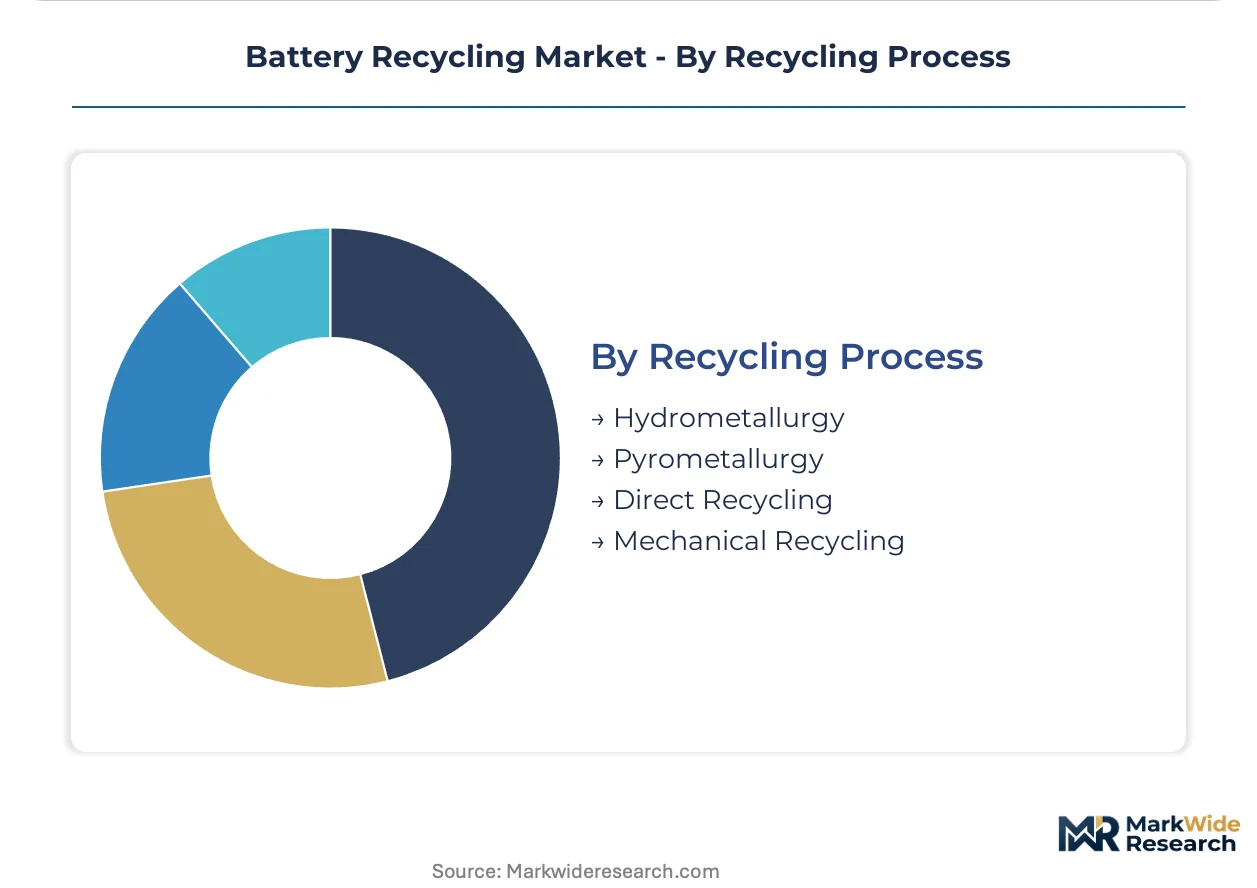
Recycling Process:
Technology maturity curves and carbon intensity profiles segment processor competitive positioning.
- Hydrometallurgy:Selective acid leaching and solvent extraction recover battery-grade salts at lower carbon intensity than smelting. Capacity concentrates in China, Germany, and South Korea where chemical engineering labor pools and environmental permitting align.
- Direct Recycling:Cathode relithiation preserves crystalline structures, eliminating full elemental dissolution. BMW and Volkswagen pilot programs test economic viability against conventional hydrometallurgical flowsheets.
- Pyrometallurgy:High-temperature smelting retains scale advantages for mixed-metal feeds and contaminated black mass. Integrated smelter-refinery complexes achieve cobalt and nickel recovery at battery-grade purity.
- Mechanical Recycling:Physical shredding and separation produces black mass for downstream refining or lower-grade metal concentrates. Preprocessing economics depend on dismantling automation and thermal runaway containment.
By installed capacity, Hydrometallurgy leads. By capital inflow velocity, Direct Recycling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment (MEE) anchors the dominant geography through dual carbon goals and battery recycling mandates that concentrate hydrometallurgical capacity in the Yangtze River Delta and Pearl River Delta clusters.
China
Domestic EV retirement curves and CATL's captive recycling network drive feedstock volumes. MEE regulations mandate producer responsibility for new energy vehicle batteries. Jiangsu and Guangdong provinces host the majority of integrated black mass-to-salt processing complexes.
Germany
Automotive OEM closed-loop mandates from Volkswagen and BMW create qualified recycler scarcity. The EU Battery Regulation and KBA certification requirements shape processor qualification timelines. North Rhine-Westphalia's industrial corridor concentrates hydrometallurgical refineries serving European cathode precursor producers.
United States
State-level extended producer responsibility programs in California and emerging landfill bans reshape collection economics. EPA universal waste regulations enable transporter consolidation without full hazardous waste manifesting. Michigan and Ohio's automotive belt hosts preprocessing facilities targeting domestic black mass production.
South Korea
Hyundai Motor Group and LG Energy Solution's vertical integration strategies drive captive recycling investments. MFDS hazardous material handling standards and carbon border adjustment preparedness guide technology selection. The Seoul Capital Area and Busan-Ulsan corridor concentrate mechanical dismantling and hydrometallurgical refining capacity.
Belgium
Umicore's integrated smelter-refinery complex anchors European cobalt and nickel recovery at battery-grade purity. REACH authorization requirements under ECHA mandate supply chain due diligence documentation. The Port of Antwerp cluster handles African copper-cobalt feedstock flows into European refining circuits.
Battery Recycling Market Vendor Landscape
Integrated smelter-refinery operators and specialized hydrometallurgical processors split the market between scale-driven pyrometallurgy and carbon-efficient direct salt recovery. The competitive terrain concentrates among three archetypes: diversified mining-houses with refining assets, pure-play recycling technology licensors, and automotive-captive processors. Capacity expansion and strategic offtake partnerships dominate competitive moves as OEM qualification timelines compress.
Within the integrated refining tier, Umicore and Glencore exemplify the mining-house archetype through their control of African feedstock flows and European processing infrastructure. Li-Cycle Holdings Corp. occupies the pure-play technology position focused on North American hydrometallurgical scale-up. These three entities represent the spectrum from upstream resource control to dedicated recycling technology deployment.
| Leading Market Players |
|---|
| Umicore |
| Li-Cycle Holdings Corp. |
| GEM Co. Ltd. |
| Glencore |
| Call2Recycle |
| Cirba Solutions |
| Contemporary Amperex Technology Co. Limited |
| Ecobat |
| Fortum |
| Others |
Supply Flow & Price Mechanics
African copper-cobalt supply concentration determines both battery-grade black mass payables and the geographic routing of European refining circuits. DRC export duty volatility compresses margin structures for hydrometallurgical processors while simultaneously forcing long-haul logistics configurations that inflate delivered cost tiers.
Pricing Analysis
Configured-to-order pricing for battery-grade cobalt sulfate commands substantial premiums over standard black mass spot transactions. Pricing stratifies across premium, standard, and economy tiers based on OEM qualification status and volume scale commitments. Cost compression in standard-grade black mass is intensifying because lithium carbonate spot market cyclicality erodes recycler margins. Automotive OEMs exhibit the least price sensitivity due to closed-loop mandate compliance requirements, while secondary traders and commodity brokers face acute margin pressure.
Supply Chain Analysis
Extended payment terms from European cathode precursor producers are reshaping working capital requirements for African feedstock suppliers. Supply concentrates in the Democratic Republic of Congo, Zambia, and Indonesia for cobalt and nickel raw material flows. Processing capacity draws from China, Germany, and South Korea where hydrometallurgical engineering labor pools anchor chemical refining investments. Single-source vulnerability in DRC ore exports exposes European refiners to logistics disruption. Distribution runs through integrated smelter-refinery complexes in Belgium and Germany before reaching cathode precursor manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery recycling is approaching a platform-economics inflection as automotive OEMs unbundle recycling services from cell procurement contracts, creating spot-market mechanisms that reward interoperability across black mass sorting and salt recovery protocols.
For Market Incumbents: Entrench qualification timelines as a competitive moat by accelerating OEM certification protocols for recycled cobalt sulfate and nickel sulfate ahead of first-generation EV retirement curves. Invest in thermal runaway containment capex at dismantling facilities to defend processing capacity against mid-scale entrants. Backward integration into African copper-cobalt feedstock flows secures margin control against export duty volatility. For New Entrants and Emerging Players: Build out North American preprocessing capacity to capture regulatory tailwinds from EPA extended producer responsibility frameworks and state landfill bans. Target mobile collection services and dispersed automotive service centers as the most penetrable white-space segment underserved by fixed drop-off infrastructure. Partner with regional logistics networks to compress cost per kilogram for hazardous cell transport. For Investors and Strategic Acquirers: EU Battery Regulation recycled content thresholds reshape the acquisition landscape by creating qualified supplier scarcity for cathode precursor producers serving European automotive OEMs. Long-term viability centers on processors with demonstrated battery-grade purity certification and integrated black mass-to-salt capabilities. Watch for direct recycling technology convergence as the signal indicating economic displacement of full hydrometallurgical dissolution flowsheets.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Integrated smelter-refinery complexes in Belgium and Germany secure battery-grade cobalt and nickel recovery for European OEMs. |
| Backward Integration | African copper-cobalt feedstock control insulates European refiners from DRC export duty volatility and logistics disruption. |
| Technology Licensing | Direct cathode recycling patents for relithiation protocols create defensible IP positions against conventional hydrometallurgical competitors. |
| Long-term Supply Agreement | OEM offtake contracts with 18-24 month qualification timelines lock in revenue recognition ahead of EV retirement curve acceleration. |
| Joint Venture | Automotive-captive recycling partnerships with Hyundai Motor Group and LG Energy Solution consolidate processing capacity in South Korea's Busan-Ulsan corridor. |
Methodological Framework
The analysis maps hydrometallurgical processing, direct cathode recycling, pyrometallurgical smelting, and mechanical preprocessing sub-sectors, each validated through recycler operations directors, cathode precursor procurement leads, automotive OEM sustainability officers, and hazardous materials logistics coordinators. Primary interview findings were cross-referenced against secondary sources including EU Battery Regulation implementation guidance, EPA universal waste regulatory filings, MEE producer responsibility mandates, and customs trade data for African copper-cobalt flows. Bottom-up capacity modeling and top-down OEM demand projections were triangulated to derive market sizing.
Assumptions regarding EU Battery Regulation recycled content threshold enforcement timelines, lithium carbonate price cyclicality bands, and first-generation EV battery retirement curve slopes were held fixed across scenario runs while feedstock availability and hydrometallurgical capacity expansion rates were varied. Segmentation dimensions modeled include collection method density, battery chemistry heterogeneity, end-user purity requirements, and recycling process carbon intensity. CAGRs were derived from installed capacity buildout schedules mapped against OEM offtake contract volumes.
Stress conditions across DRC export duty volatility, lithium carbonate spot market crashes, and thermal runaway containment capex inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory calibration timelines and feedstock availability gaps. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Solar Components Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market