
 India Battery Recycling Market | 2026-2036
India Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
India Battery Recycling Market Insights
Buyer concentration among automotive OEMs is realigning procurement flows toward certified recyclers with proven recovery yields. Tata Chemicals leverages its integrated chemical complex in Gujarat to control reagent supply for hydrometallurgical lines. Amara Raja Energy & Mobility anchors its reverse logistics through dedicated collection partnerships with southern India's dealership networks. Attero Recycling competes on cobalt and lithium recovery rates that meet international smelter specifications.
India battery recycling encompasses the systematic dismantling, shredding, and chemical extraction of spent cells to recover cobalt, lithium, nickel, and lead with purity exceeding 99.5% for re-entry into cathode active material production. The process serves India's domestic cell manufacturing ambitions under the PLI scheme by reducing import dependence on critical minerals. Lead acid batteries occupy the largest volume share due to India's massive automotive and telecom backup installed base, though margin pools are compressing as smelter capacity expands. Lithium-ion batteries represent the fastest-expanding segment as electric two-wheeler and three-wheeler fleets generate end-of-life feedstock at accelerating rates. Hydrometallurgical processes attract capital inflows for their lower emissions profile and higher recovery precision versus pyrometallurgical alternatives.
The Ministry of Environment's Battery Waste Management Rules enforce extended producer responsibility targets and mandate minimum recovery percentages for lead, lithium, and cobalt. BIS certification requirements for recycled content in new batteries create compliance-driven demand for formal sector recyclers with traceable output. The Central Pollution Control Board's monitoring of informal sector dismantling operations in urban clusters is tightening market access for unregistered operators. Stakeholders must track how EPCO's state-level enforcement variations and evolving GST treatment of recycled materials reshape facility location decisions across India's industrial corridors.
Market Dynamics
The Battery Waste Management Rules are compressing informal sector participation while mandating minimum recovery thresholds, forcing capital reallocation toward hydrometallurgical infrastructure and traceable reverse logistics networks.
Growth Catalysts
- PLI Scheme for ACC:The production-linked incentive scheme for advanced chemistry cells creates captive demand for domestically recovered lithium, cobalt, and nickel, pulling investment toward integrated recycling-smelting complexes in Gujarat and Tamil Nadu.
- Extended Producer Responsibility Mandates:BIS certification requirements for recycled content in new batteries lock OEM procurement to formal recyclers with documented recovery yields, accelerating dealer-network collection partnerships.
- Electric Fleet Expansion:Maharashtra and Gujarat electric two-wheeler and three-wheeler fleet operators are generating concentrated end-of-life feedstock, enabling recycler-processor offtake agreements at scale.
Market Restraints
- Reagent Cost Volatility:Sulfuric acid and sodium hydroxide price swings compress hydrometallurgical margins, particularly for mid-scale operators without captive chemical production.
- Informal Sector Entrenchment:Unregistered dismantlers in Delhi-NCR urban clusters capture 60-70% of lead-acid feedstock through unregulated collection channels, constraining formal sector volume access.
- Grid Power Reliability:Intermittent electricity supply in industrial corridors outside Gujarat raises smelter downtime risk and backup diesel costs.
Strategic Opportunities
- Northeast Industrial Corridors:Assam and West Bengal offer underpenetrated collection territory with proximity to ASEAN export routes for recovered metals.
- Second-Life Battery Applications:Stationary energy storage for telecom towers and rural microgrids creates a refurbishment tier before chemical recycling, extending value extraction per cell.
- DGFT Export Incentives:Duty drawbacks on recovered critical minerals are enabling Indian recyclers to supply cathode material producers in Japan and South Korea.
Industry Challenges
- Skilled Technician Scarcity:Battery dismantling and hydrometallurgical process engineering require specialized training that vocational institutes have not yet scaled to match facility buildout timelines.
- Capex Intensity for Emissions Compliance:Flue gas treatment and effluent neutralization systems add 25-30% to greenfield project costs, stretching payback periods for independent operators.
- BIS Certification Timelines:Six-to-nine-month approval windows for recycled-content verification delay contract finalization with automotive OEMs facing EPR deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Battery Recycling Market |
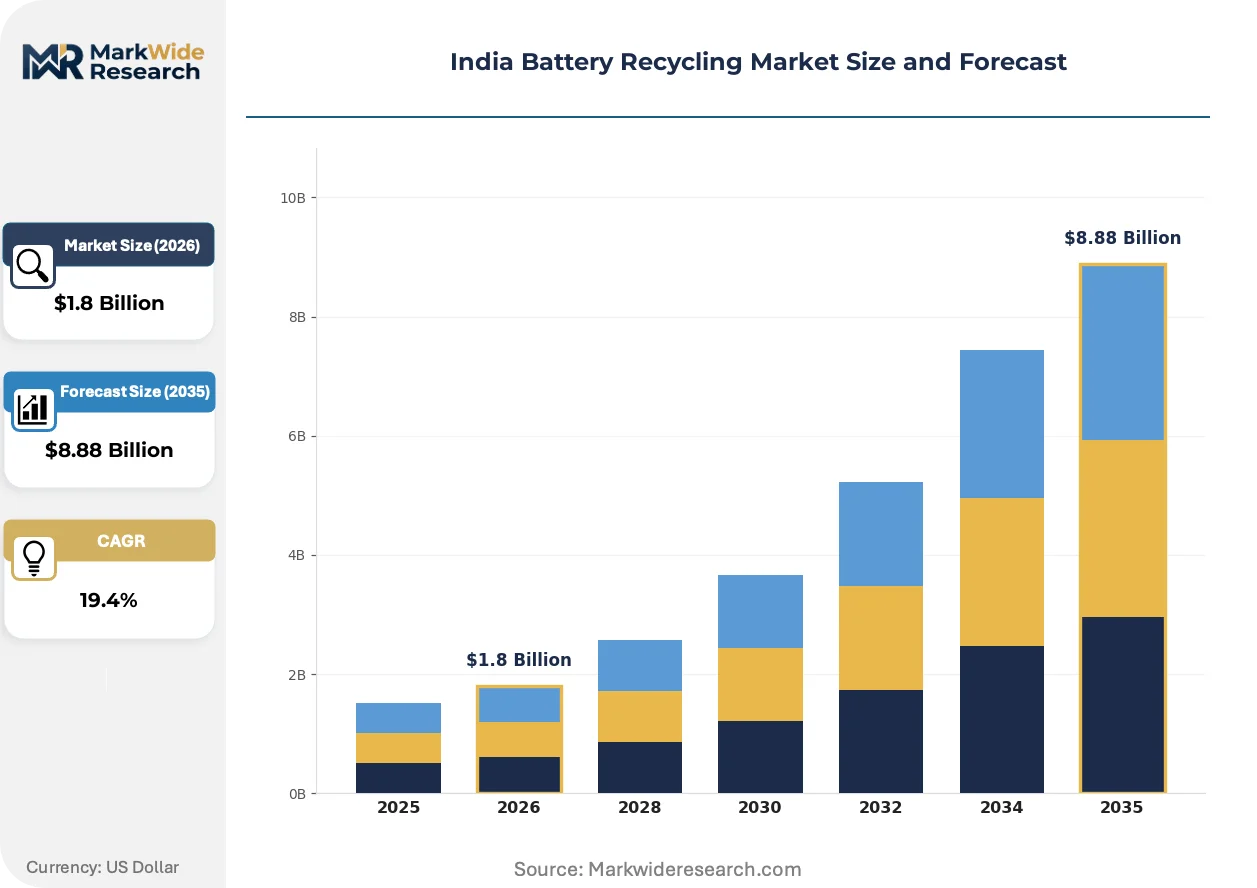
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid Batteries, Lithium-ion Batteries, Nickel Cadmium Batteries, Others End User: Automotive OEMs, Electronics Manufacturers, Renewable Energy Providers, Retail Consumers Recycling Process: Hydrometallurgical, Pyrometallurgical, Biotechnological, Mechanical Distribution Channel: Direct Sales, Online Platforms, Retail Stores, Collection Centers |
| Companies Covered | Tata Chemicals, Amara Raja Energy & Mobility, Attero Recycling, BatX Energies, Eco Recycling, Lohum Cleantech, Exide Technologies, Nile, Gravita India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Battery Recycling Market Trends and Innovations
Direct recycling technologies and modular hydrometallurgical units are redrawing facility economics, while regulatory tightening around traceability is forcing data infrastructure investments across the value chain.
Direct cathode regeneration is decentralizing the economics of lithium-ion recovery by preserving crystalline structure without full elemental dissolution, cutting reagent consumption by half. Mid-scale recyclers in Tamil Nadu and Karnataka are piloting containerized units that bypass centralized smelter dependence. This technology is decentralizing competitive advantage away from integrated chemical complexes toward distributed, fleet-adjacent processing nodes.
BIS certification requirements for recycled-content traceability are mandating blockchain-linked material passports from collection through refining. The Central Pollution Control Board's digital monitoring of informal dismantling operations is tightening documentation standards for EPR compliance. Automotive OEMs in Maharashtra are responding by requiring QR-code tracking on every collected cell, shifting procurement preference toward recyclers with auditable data infrastructure.
Fleet operators are consolidating reverse logistics under single-recycler contracts rather than fragmented dealer-channel collection. This procurement consolidation is compressing the number of approved suppliers per OEM from dozens to five or six certified processors. The shift is most visible in Gujarat, where electric three-wheeler fleet managers are signing exclusive five-year offtake agreements with integrated recycler-smelters.
India Battery Recycling Market Segmentation
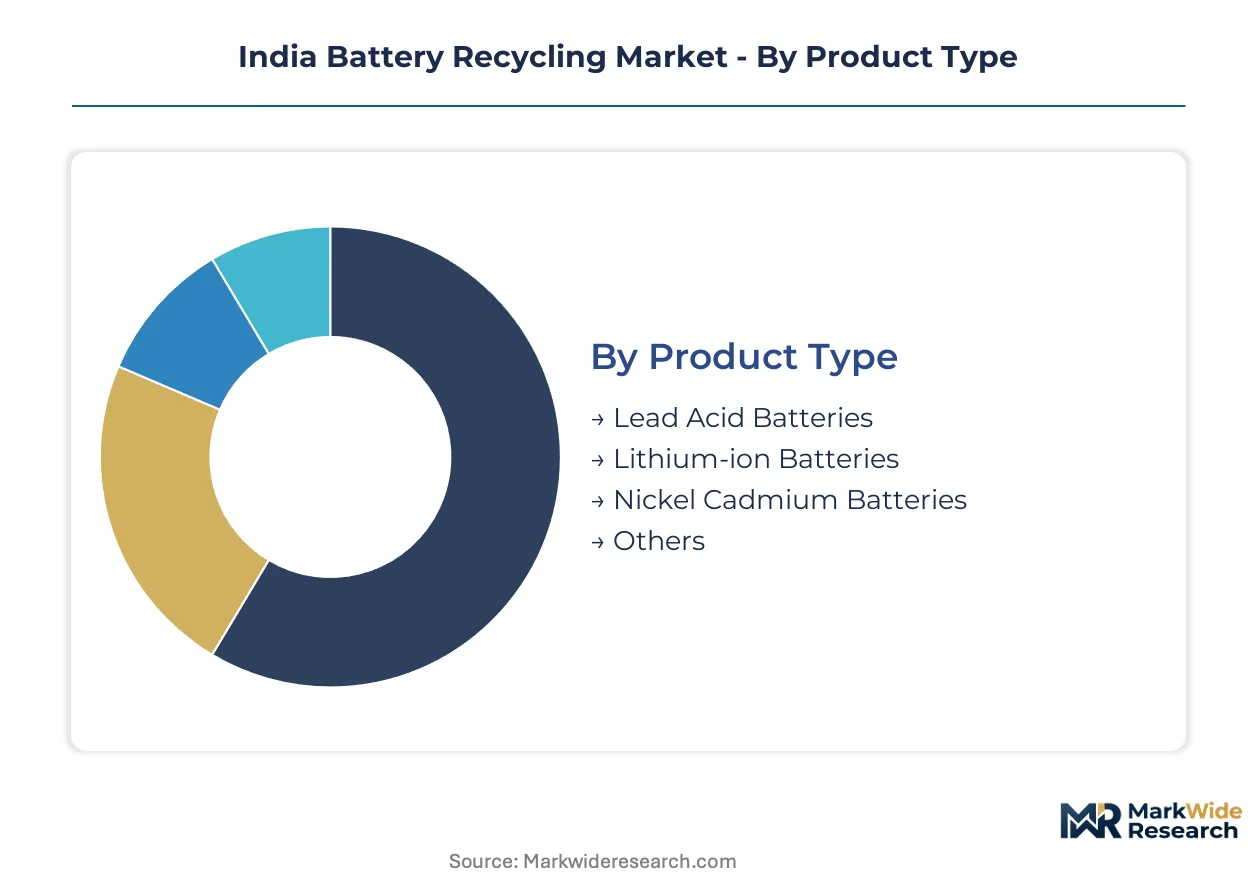
Segmentation in India's battery recycling market reveals how recovery technologies, feedstock chemistry, and procurement channels intersect with regulatory compliance. Each axis shapes capital allocation, facility economics, and competitive positioning across the value chain.
Product Type:
Product chemistry determines recovery yields, reagent requirements, and the sophistication of downstream purification infrastructure.
- Lead Acid Batteries:These cells contain sulfuric acid electrolyte and lead oxide electrodes that smelters reduce to pure lead ingots. Maharashtra's automotive aftermarket and telecom tower operators generate concentrated feedstock volumes, though margin compression intensifies as formal sector smelter capacity expands.
- Lithium-ion Batteries:Cathode chemistries spanning NMC, LFP, and LCO demand hydrometallurgical precision for cobalt, lithium, and nickel separation. Gujarat's electric two-wheeler fleet operators are creating the first wave of end-of-life feedstock, pulling investment toward integrated recycling-smelting complexes.
- Nickel Cadmium Batteries:Aerospace and industrial backup systems in Delhi-NCR supply this toxic-heavy-metal feedstock requiring specialized cadmium recovery lines.
- Others:Primary alkaline cells and button batteries from consumer electronics contribute minor volumes with limited metal recovery economics.
Lead acid batteries lead on scale; lithium-ion batteries lead on momentum.
End User:
Customer procurement patterns range from compliance-driven bulk contracts to fragmented retail collection, reshaping reverse logistics design.
- Automotive OEMs:Extended producer responsibility mandates lock these manufacturers to certified recyclers with documented recovery yields. Maruti Suzuki and Tata Motors are consolidating approved supplier lists to five or six processors with BIS-certified traceability systems.
- Electronics Manufacturers:Mobile phone and laptop assemblers face mounting pressure to close material loops for cobalt and lithium. Dell and HP's India operations are piloting take-back programs with direct recycler partnerships bypassing informal channels.
- Renewable Energy Providers:Solar-plus-storage developers in Rajasthan and Karnataka generate stationary battery waste requiring scheduled replacement cycles.
- Retail Consumers:Scattered individual discards flow through kirana shops and municipal collection points, presenting traceability challenges for EPR compliance.
Automotive OEMs concentrate procurement value; electronics manufacturers are gaining share fastest.
Recycling Process:
Technology selection balances capital intensity, emissions profile, and recovery precision against feedstock chemistry.
- Hydrometallurgical:Aqueous chemical leaching achieves purity exceeding 99.5% for battery-grade lithium and cobalt recovery. Tamil Nadu's mid-scale operators are deploying containerized units that cut reagent consumption through direct cathode regeneration.
- Pyrometallurgical:High-temperature smelting dominates lead acid processing with lower capital barriers but generates SO₂ emissions requiring flue gas treatment. Gujarat's integrated chemical complexes leverage captive energy supply to offset grid reliability risks.
- Biotechnological:Bioleaching using acidophilic bacteria offers emerging low-energy alternatives for niche metal recovery applications.
- Mechanical:Shredding and physical separation provides preliminary feedstock conditioning for downstream chemical refining.
Pyrometallurgical processes lead on installed capacity; hydrometallurgical processes lead on investment inflows.
Distribution Channel:
Channel structure determines collection density, transportation economics, and documentation integrity for regulatory compliance.
- Direct Sales:Fleet operators and OEMs sign exclusive offtake agreements with integrated recyclers, consolidating volume under long-term contracts. Gujarat's electric three-wheeler fleet managers are locking in five-year supply arrangements with single processors.
- Online Platforms:Digital marketplaces connect dispersed battery waste generators with certified recyclers, though weight-based logistics costs limit viability for low-value lead acid units.
- Retail Stores:Automotive parts dealers and electronics retailers serve as informal aggregation points feeding formal sector processors.
- Collection Centers:Dedicated reverse logistics hubs in Delhi-NCR and Mumbai urban clusters integrate informal sector collectors into traceable networks.
Direct sales channels lead on contract value; collection centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's integrated chemical complexes attract recycling investment density that Tamil Nadu's mid-scale operators struggle to match, while Maharashtra's electric fleet operators generate concentrated feedstock volumes unmatched elsewhere in India.
Maharashtra
Electric two-wheeler and three-wheeler fleet operators in Mumbai and Pune generate India's densest end-of-life lithium-ion feedstock. The state's pollution control board enforces Battery Waste Management Rules with stricter documentation requirements than neighboring jurisdictions. Industrial clusters in Thane and Nagpur host formal recycler-smelter partnerships that bypass informal collection channels.
Gujarat
Tata Chemicals anchors hydrometallurgical capacity through its Mithapur integrated complex, controlling captive reagent supply chains. The state's industrial development corporation offers capital subsidies for greenfield recycling facilities under its specialty chemicals policy. Hazira and Dahej industrial corridors concentrate pyrometallurgical lead smelting capacity with grid reliability advantages over central Indian alternatives.
Tamil Nadu
Hosur and Chennai automotive supplier parks generate steady lead-acid battery replacement demand from component manufacturers. The state's electronics manufacturing policy incentivizes recycler partnerships with mobile phone and laptop assemblers for cobalt recovery. Containerized direct recycling pilots in Coimbatore bypass centralized smelter economics for mid-scale operators.
Delhi-NCR
Telecom tower operators and data centers in Gurgaon and Noida generate scheduled replacement cycles for stationary energy storage batteries. The Central Pollution Control Board's digital monitoring of informal dismantling operations in urban clusters tightens market access for unregistered collectors. Formal recyclers integrate informal sector collectors into traceable networks through dedicated collection centers.
Karnataka
Bengaluru's electronics manufacturing and IT hardware sectors generate lithium-ion feedstock from consumer device end-of-life cycles. The state's electric vehicle policy mandates recycler partnerships for fleet operators receiving purchase incentives. Second-life battery refurbishment for rural microgrids extends value extraction before chemical recycling in Hubli-Dharwad industrial areas.
India Battery Recycling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's battery recycling value chain. Tata Chemicals leverages backward integration into chemical reagents while Attero Recycling and Lohum Cleantech build scale through dedicated recovery operations. Three archetypes dominate: integrated chemical majors controlling upstream inputs, pure-play recyclers competing on recovery yields, and lead-acid incumbents expanding into lithium-ion chemistries. Competitive moves center on exclusive offtake agreements with fleet operators and BIS certification investments that lock OEM procurement relationships.
Among diversified industrial groups, Tata Chemicals and Exide Technologies occupy positions anchored by legacy chemical and battery manufacturing operations. Attero Recycling, BatX Energies, and Lohum Cleantech represent the pure-play specialist tier competing on hydrometallurgical precision and traceability infrastructure. Gravita India and Amara Raja Energy & Mobility exemplify lead-acid incumbents pivoting capacity toward lithium-ion feedstock processing. Eco Recycling and Nile sit within the emerging mid-scale tier leveraging modular unit economics.
| Leading Market Players |
|---|
| Tata Chemicals |
| Amara Raja Energy & Mobility |
| Attero Recycling |
| BatX Energies |
| Eco Recycling |
| Lohum Cleantech |
| Exide Technologies |
| Nile |
| Gravita India |
| Others |
Pricing and Supply Chain Analysis
Specialized hydrometallurgical technicians in Tamil Nadu and Gujarat command wage premiums that widen pricing spreads between certified formal recyclers and informal dismantlers. Labor-cost differentials across India's industrial corridors translate into tiered service pricing where BIS-certified recovery commands substantial premiums over unregistered alternatives.
Pricing Analysis
Capacity additions in Gujarat are reshaping price floors for lead-acid smelting as Tata Chemicals' captive reagent supply undercuts independent operators. Contract-based long-term offtake agreements dominate fleet-operator procurement, with price differentiation resting on BIS certification tier and volume scale. Cost compression in lead-acid recovery is intensifying because smelter capacity expansion outpaces feedstock formalization. Fleet operators show highest price sensitivity; automotive OEMs prioritize compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium carbonate and cobalt sulfate imports feeding hydrometallurgical lines in Gujarat and Tamil Nadu. The supply chain draws from China, Australia, and the Democratic Republic of Congo for critical mineral inputs, with sulfuric acid and sodium hydroxide reagents sourced domestically from chemical complexes. Tariff exposure on lithium compounds creates margin volatility for mid-scale operators. Distribution runs through exclusive recycler-fleet partnerships and dealer-network collection points feeding formal processing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India battery recycling market functions as a stable compounder anchored by regulatory mandates that tighten annually and expand addressable feedstock through electric fleet growth.
For Market Incumbents: Extend BIS certification coverage across all cathode chemistries before mid-scale competitors achieve scale. Lock exclusive five-year offtake agreements with Maharashtra and Gujarat fleet operators to preempt feedstock fragmentation. Defensive consolidation through backward integration into reagent production neutralizes margin pressure from chemical price volatility. For New Entrants and Emerging Players: Rural telecom tower operators represent an underserved buyer archetype with scheduled battery replacement cycles and limited incumbent penetration. Target Assam and West Bengal collection territory where formal recycler presence remains sparse and ASEAN export routes offer recovered metal outlets. Deploy containerized direct recycling units to bypass capital barriers of centralized smelter economics. For Investors and Strategic Acquirers: Chemical conglomerates with captive reagent supply are the most active acquirer in this space, seeking hydrometallurgical capabilities to complete vertical integration. Acquisition focus centers on mid-scale operators with BIS certification progress and established fleet-operator relationships. Watch for inflection when informal sector dismantlers face enforcement-driven volume collapse in Delhi-NCR urban clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reagent Supply | Tata Chemicals' captive sulfuric acid production shields hydrometallurgical margins from commodity volatility. |
| BIS Certification Investment | Formal recyclers with documented recovery yields lock automotive OEM procurement under EPR mandates. |
| Fleet Operator Exclusive Offtake | Gujarat electric three-wheeler managers consolidate reverse logistics under single-recycler contracts. |
| Containerized Direct Recycling Deployment | Mid-scale Tamil Nadu operators bypass centralized smelter dependence with modular unit economics. |
| Informal Sector Integration Program | Delhi-NCR formal recyclers absorb unregistered collectors into traceable networks for EPR compliance. |
Research Methodology
Bottom-up fleet-operator feedstock modeling reconciled against top-down smelter capacity tracking forms the analytical core. Primary interviews with hydrometallurgical plant managers, automotive OEM procurement leads, pollution control board enforcement officers, and dealer-network collection coordinators combined with secondary validation from Central Pollution Control Board filings, DGFT trade statistics, BIS certification registries, and state industrial development corporation subsidy disclosures. Triangulation between supply-side capacity announcements and demand-side replacement cycle data ensures consistency.
Input-output matrices map lithium-ion and lead-acid feedstock volumes through recycling process economics across product chemistry, end-user procurement channel, and regional regulatory cluster dimensions. Growth trajectories derive from fleet electrification rates, EPR enforcement intensity, and PLI scheme capacity buildout timelines throughout the projection horizon. Forecast inputs incorporate battery replacement cycle frequencies and informal-to-formal sector transition velocities.
Underlying measurement precision varies by segment; lithium-ion recovery rates carry tighter precision than lead-acid volume estimates given feedstock formalization uncertainty. Forecasts reflect assumptions around regulatory enforcement consistency and grid power reliability in industrial corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Battery Materials Recycling Market