
 Europe Solar Panel Recycling Market | 2026-2036
Europe Solar Panel Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Panel Recycling Market Foresight
Utility-scale solar operators are redrawing procurement priorities for end-of-life panel management. Veolia Environnement S.A. leverages its integrated waste infrastructure across France and neighboring markets. Solar Materials GmbH anchors German processing capacity with specialized mechanical separation lines. ROSI Solar differentiates through advanced hydrometallurgical recovery of high-purity silicon and silver.
Europe solar panel recycling encompasses the collection, dismantling, and material recovery of photovoltaic modules reaching end-of-service, typically after 25-30 years of field operation, with thermal and chemical processes extracting aluminum frames, copper wiring, silver metallization, and semiconductor-grade silicon for reintroduction to manufacturing supply chains. Mechanical recycling dominates current throughput due to lower capital intensity and compatibility with crystalline silicon modules, while hydrometallurgical methods capture fastest-growing investment as bifacial and thin-film panels with complex layer structures enter the waste stream. Thin-film modules concentrate margin pools in specialized pyrometallurgical circuits given cadmium-telluride and copper-indium-gallium-diselenide chemistries.
The EU Waste Framework Directive and national EPR policies shape collection obligations and recycling rate targets across member states, while REACH restricts hazardous substance thresholds in recovered materials destined for reprocessing. Germany's EPR implementation through its national packaging and electrical equipment registry sets enforcement benchmarks that neighboring jurisdictions reference. Stakeholders must monitor regulatory divergence between EU harmonized targets and national transposition timelines to align capacity investments with compliance deadlines.
Market Dynamics
The first wave of crystalline silicon installations from Germany's 2004-2012 feed-in tariff boom is reaching end-of-service, creating an abrupt supply surge that recycling infrastructure must absorb. This volume cliff is compressing planning horizons and forcing capital deployment ahead of revenue visibility.
Growth Catalysts
- EPR Mandates:Germany's national electrical equipment registry and France's extended producer responsibility decrees obligate manufacturers to fund collection networks, guaranteeing feedstock volumes for processors.
- Semiconductor-Grade Silicon Recovery:Hydrometallurgical circuits now extract 99.999% pure silicon from degraded wafers, reintroducing material directly into ingot production.
- Italy's Early Installation Base:The Conto Energia program deployed over 18 GW between 2005-2013, positioning Italian waste streams for immediate processing demand.
Market Restraints
- Pyrometallurgical Energy Costs:Thin-film cadmium-telluride recovery requires sustained 1,000°C+ thermal processing, exposing operators to natural gas price volatility.
- Glass-Encapsulant Bonding:Ethylene-vinyl acetate lamination creates irreversible chemical adhesion with front glass, complicating mechanical separation yields.
- Cross-Border Feedstock Arbitrage:Waste panel trafficking to non-compliant jurisdictions undercuts legitimate recycling economics in Poland and Romania.
Strategic Opportunities
- Spain's Delayed Waste Cliff:The 2008-2012 installation surge enters end-of-life from 2033-2037, offering greenfield capacity placement ahead of volume arrival.
- Silver Metallization Concentration:Bifacial PERC and TOPCon cells carry 20-40% higher silver loadings than legacy designs, expanding precious metal recovery margins.
- EU Critical Raw Materials Act:Domestic silicon and gallium recovery quotas incentivize hydrometallurgical investments that qualify for strategic project financing.
Industry Challenges
- Fluoropolymer Fluorine Handling:Backsheet degradation releases perfluorinated compounds requiring specialized thermal destruction, stretching operator permitting timelines.
- Module Identification Gaps:Missing serial records and manufacturer insolvencies prevent automated sorting by cell chemistry, forcing manual triage that bottlenecks throughput.
- Downstream offtake contracting:Recovered silicon lacks semiconductor-grade certification pathways, leaving processors dependent on spot metallurgical markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Panel Recycling Market |
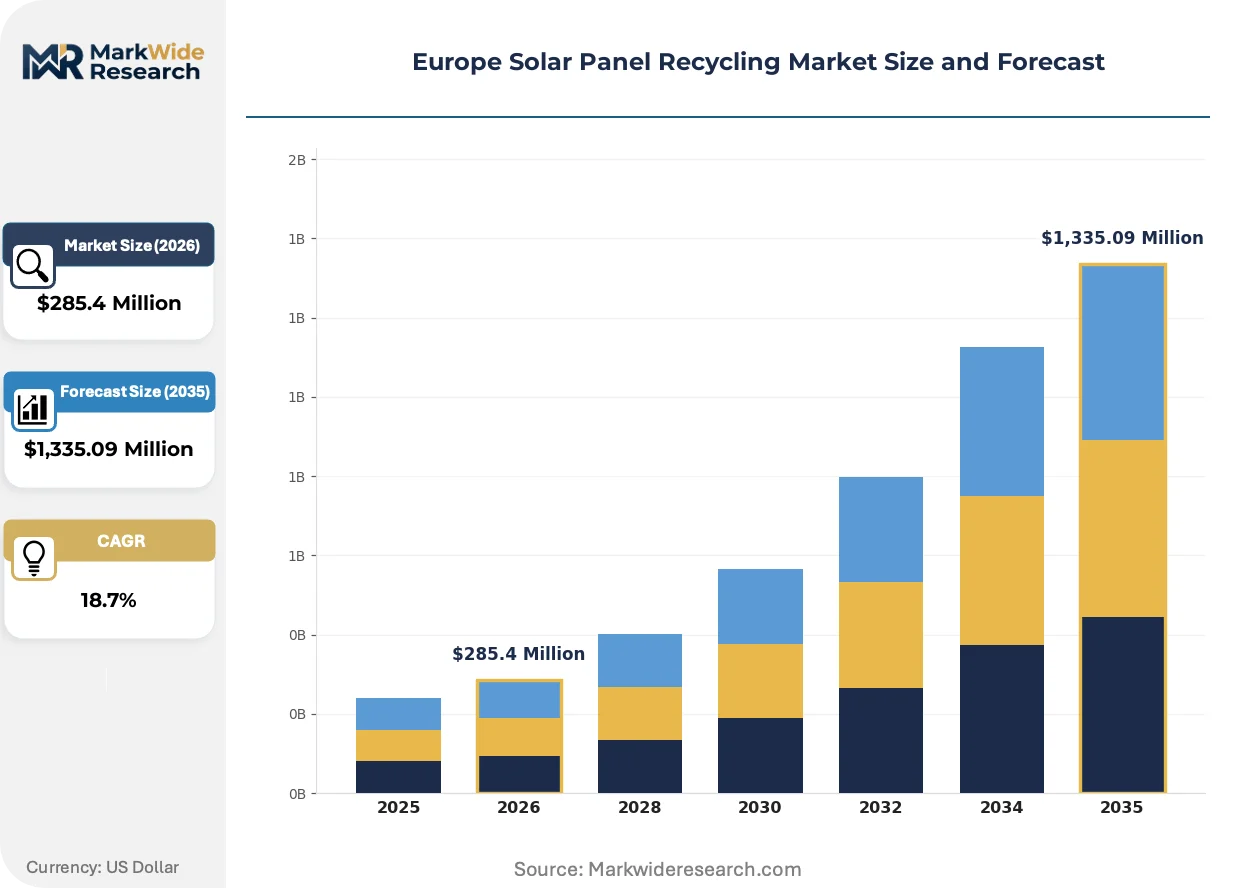
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanical Recycling, Pyrometallurgical, Hydrometallurgical, Bioleaching Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial End User: Manufacturers, Installers, Waste Management Companies, Research Institutions Regulatory Framework: EU Waste Management, National Legislation, EPR Policies, Recycling Targets |
| Companies Covered | PV Cycle, Solar Materials GmbH, Veolia Environnement S.A., Apellix, 9-Tech, Reiling PV-Recycling GmbH, First Solar Inc., Lotus Energy, ROSI Solar, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Panel Recycling Market Shifts & Advancements
Processing technology is pivoting from bulk shredding toward selective layer delamination, driven by the economic premium on intact silicon wafers and silver busbars. This shift is redrawing equipment supplier hierarchies and tightening feedstock quality specifications.
Pyrometallurgical recovery of cadmium and tellurium from thin-film modules is displacing primary mining for these critical raw materials. First Solar's European end-of-life takeback program channels dedicated feedstock to dedicated smelters. The displacement is compressing primary tellurium spot prices and forcing mining operations to accelerate cost reductions.
France's transposition of the EU Waste Framework Directive into national code imposes 85% recycling rate targets with mass-balance verification. Operators must invest in weighbridge integration and blockchain traceability to demonstrate compliance. The enforcement is concentrating processing contracts toward vertically integrated waste groups with existing audit infrastructure.
Utility-scale asset owners are unbundling end-of-life obligations from original EPC contracts and negotiating direct recycling service agreements. This disintermediation transfers liability retention to specialist processors. The pattern is most visible in Germany, where municipal utilities and regional energy cooperatives dominate installed base ownership.
Europe Solar Panel Recycling Market Segmentation
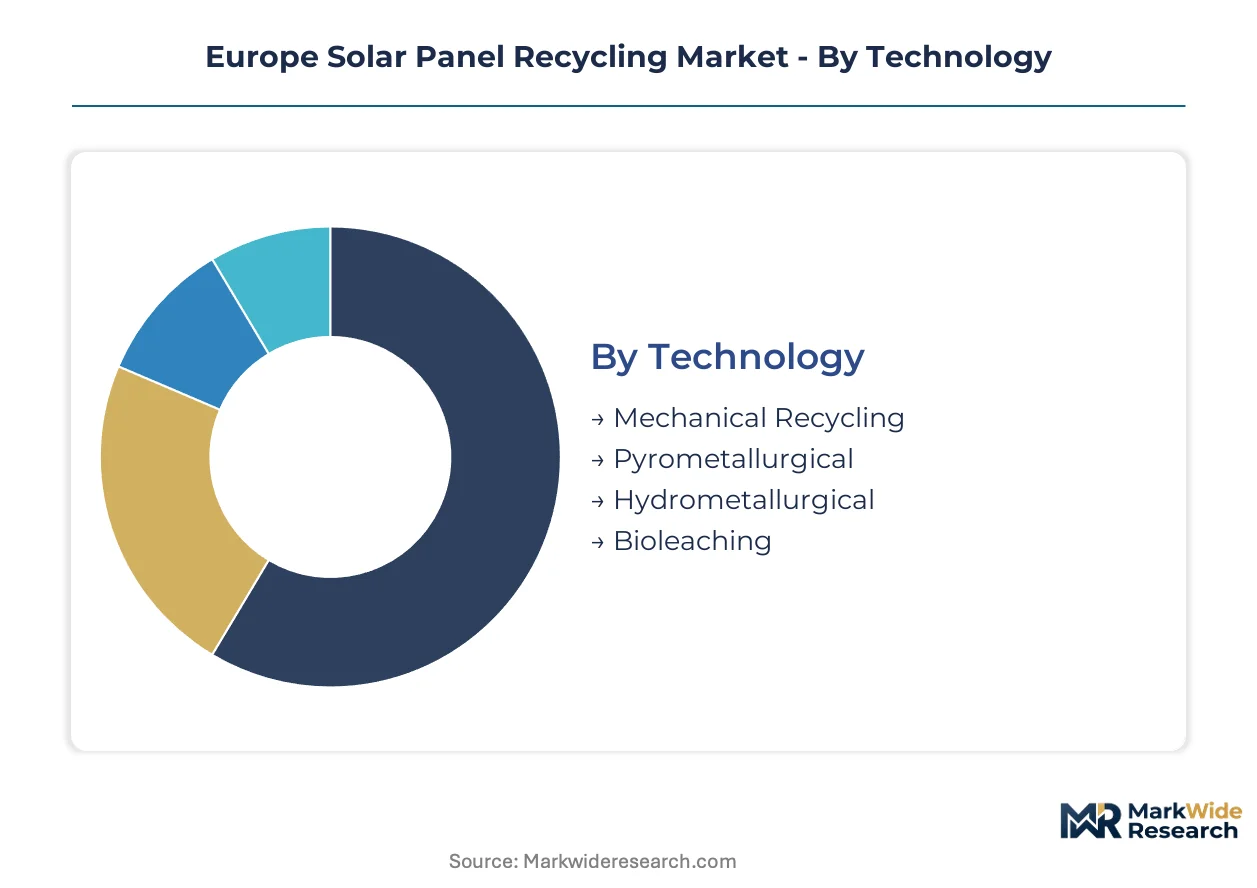
Recycling economics diverge sharply across technology pathways and module chemistries. EPR policy enforcement in Germany and France concentrates feedstock flows toward compliant processors, while regulatory fragmentation across member states creates arbitrage opportunities for non-compliant operators.
Technology:
REACH and the EU Waste Framework Directive impose divergent compliance burdens depending on thermal versus chemical recovery methods, with pyrometallurgical circuits facing stricter emissions thresholds.
- Mechanical Recycling:Shredding and density separation of aluminum frames, glass, and semiconductor materials dominates current European throughput. German operators in Saxony and Bavaria leverage existing automotive shredder infrastructure to process crystalline silicon modules at scale, though glass-encapsulant bonding limits silicon wafer recovery yields.
- Hydrometallurgical:Acid leaching circuits extract 99.999% pure silicon and silver metallization from degraded wafers. French processors near Lyon and Grenoble are deploying these systems to supply ingot manufacturers in the Rhône-Alpes cluster, capitalizing on semiconductor-grade material premiums.
- Pyrometallurgical:High-temperature smelting recovers cadmium and tellurium from thin-film modules. Energy costs at 1,000°C+ operating temperatures expose operators to natural gas price volatility across Central Europe.
- Bioleaching:Microbial extraction of copper and indium from complex layer structures remains pre-commercial. Research consortia in the Netherlands and Belgium are piloting fungal leaching for copper-indium-gallium-diselenide chemistries.
Mechanical recycling handles the majority of throughput; hydrometallurgical is the fastest mover on share.
Product Type:
Module architecture determines recovery economics, with silver loading and wafer thickness driving margin differentiation across processor portfolios.
- Monocrystalline:Higher-purity silicon wafers and elevated silver busbar densities command premium recovery values. Italian waste streams from the Conto Energia deployment wave concentrate in Lombardy and Veneto processing facilities.
- Polycrystalline:Lower-grade silicon and reduced metal content compress recovery margins. Spanish operators anticipate volume surges from 2008-2012 installations entering end-of-life in the mid-2030s.
- Thin-Film:Cadmium-telluride and copper-indium-gallium-diselenide chemistries require specialized pyrometallurgical circuits. First Solar's European takeback program channels dedicated feedstock to dedicated smelters in Germany.
- Bifacial:Dual-glass construction and 20-40% higher silver loadings than legacy designs expand precious metal recovery margins. PERC and TOPCon cell architectures dominate incoming waste streams from German utility-scale assets.
Monocrystalline modules generate the highest recovery revenue per ton; bifacial is expanding most quickly as early installations reach end-of-service.
End User:
Procurement authority is fragmenting across the value chain as asset owners unbundle end-of-life obligations from original EPC contracts.
- Manufacturers:EPR mandates obligate panel producers to fund collection networks. German electrical equipment registry enforcement requires direct financial responsibility for treatment costs.
- Installers:Decommissioning contractors are securing recycling service agreements as a value-add for utility-scale asset owners. French regional energy cooperatives are disintermediating original EPC providers.
- Waste Management Companies:Veolia and Suez leverage integrated infrastructure across France and neighboring markets to capture mass-balance verified recycling contracts.
- Research Institutions:Fraunhofer ISE and CEA-Liten are developing selective layer delamination technologies to improve silicon wafer integrity recovery.
Waste management companies hold the dominant contract share; installers are climbing the fastest as procurement authority shifts downstream.
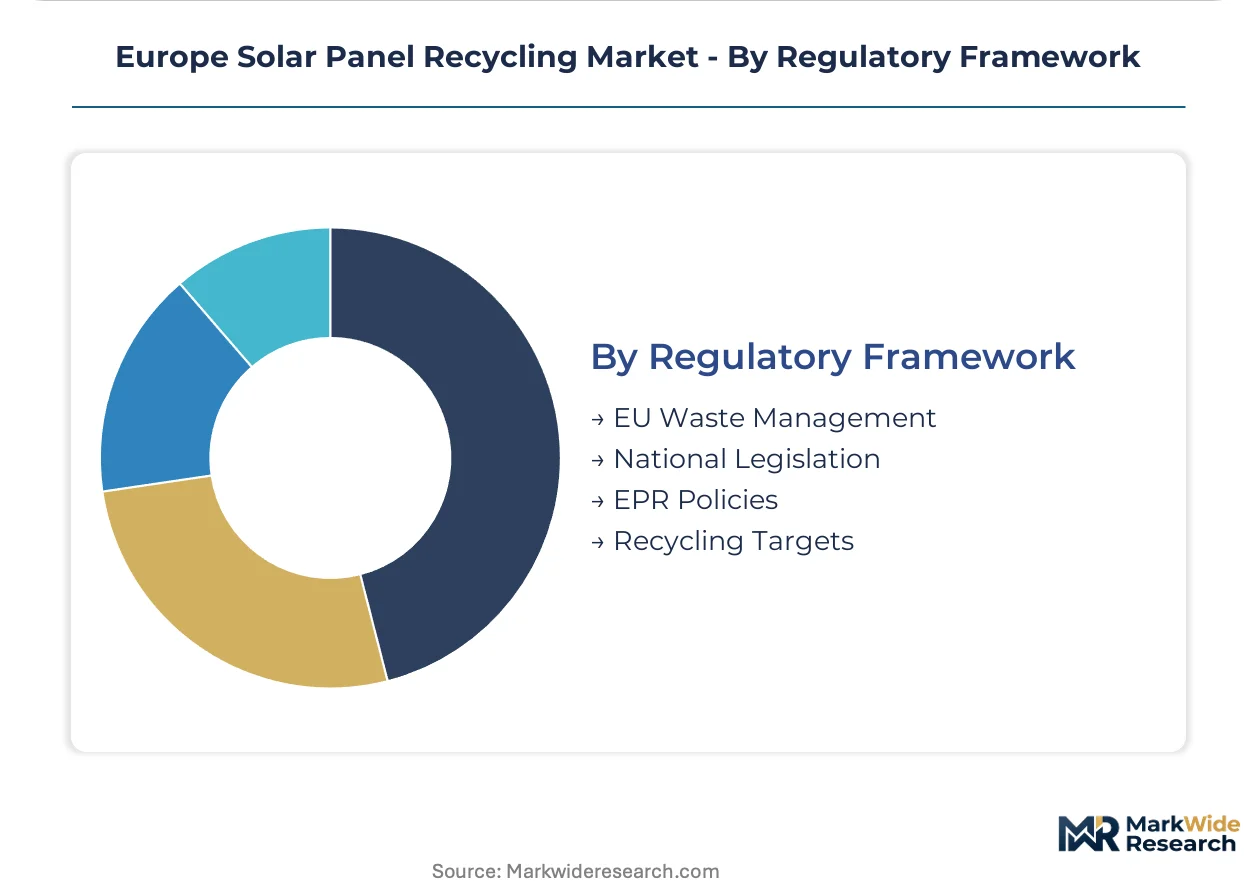
Regulatory Framework:
Compliance architecture varies between harmonized EU targets and national transposition timelines, creating investment timing uncertainty.
- EU Waste Management:The Waste Framework Directive sets baseline collection and recycling obligations. France's 85% recycling rate target with mass-balance verification is tightening audit requirements.
- National Legislation:Germany's electrical equipment registry and Italy's SISTRI waste tracking system impose country-specific operational constraints. Cross-border feedstock movements face divergent documentation standards.
- EPR Policies:Extended producer responsibility decrees in France and transposition statutes in Spain guarantee feedstock volumes for compliant processors. Registration fees fund collection infrastructure deployment.
- Recycling Targets:Mass-balance verification and blockchain traceability requirements are concentrating contracts toward vertically integrated waste groups with existing audit infrastructure.
National legislation governs the majority of operational compliance; EPR policies are gaining share fastest as member states accelerate transposition timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German processors export recovered semiconductor-grade silicon to French ingot manufacturers, establishing a cross-border material corridor that concentrates value capture in the Rhine-Rhône industrial axis.
Germany
The 2004-2012 feed-in tariff boom generated over 40 GW of crystalline silicon installations now reaching end-of-service. Germany's electrical equipment registry under EPR mandates obligates manufacturers to fund collection networks. Saxony and Bavaria host mechanical shredding facilities repurposed from automotive recycling infrastructure.
France
Utility-scale asset owners in Provence-Alpes-Côte d'Azur are unbundling end-of-life obligations from original EPC contracts. France's 85% recycling rate target with mass-balance verification tightens audit requirements. Lyon and Grenoble processors deploy hydrometallurgical circuits to supply the Rhône-Alpes semiconductor cluster.
Italy
The Conto Energia program deployed 18 GW between 2005-2013, positioning Lombardy and Veneto waste streams for immediate processing demand. Italy's SISTRI waste tracking system imposes country-specific documentation standards. Regional energy cooperatives in northern Italy are disintermediating original equipment providers for recycling contracts.
Spain
The 2008-2012 installation surge enters end-of-life from 2033-2037, offering greenfield capacity placement ahead of volume arrival. Spain's EPR transposition statutes guarantee feedstock volumes for compliant processors. Andalusia concentrates early decommissioning activity from desert solar farms with accelerated degradation profiles.
Netherlands
Research consortia in the Randstad region pilot bioleaching technologies for copper-indium-gallium-diselenide chemistries. REACH restrictions on hazardous substance thresholds shape recovered material reprocessing protocols. Eindhoven-area equipment suppliers develop selective layer delamination systems for intact wafer recovery.
Europe Solar Panel Recycling Market Competitive Landscape
Player mix skews toward integrated waste management conglomerates and specialized mechanical processing specialists, with emerging hydrometallurgical pure-plays gaining contract share. The competitive field separates into three archetypes: vertically integrated environmental services groups with existing audit infrastructure, dedicated photovoltaic recycling specialists with proprietary separation lines, and thin-film module manufacturers operating captive takeback programs. Dominant competitive moves include capacity expansion ahead of Spain's delayed waste cliff and strategic partnerships between processors and ingot manufacturers for semiconductor-grade silicon offtake.
Among French-based environmental services groups, Veolia Environnement S.A. occupies a position exemplifying the integrated infrastructure archetype, leveraging cross-border waste logistics to capture mass-balance verified contracts. Solar Materials GmbH and Reiling PV-Recycling GmbH represent the specialized mechanical processing tier, anchoring German capacity with equipment configurations adapted from adjacent recycling verticals. ROSI Solar sits within the emerging hydrometallurgical specialist category, occupying a position tied to advanced chemical recovery investments.
| Leading Market Players |
|---|
| PV Cycle |
| Solar Materials GmbH |
| Veolia Environnement S.A. |
| Apellix |
| 9-Tech |
| Reiling PV-Recycling GmbH |
| First Solar Inc. |
| Lotus Energy |
| ROSI Solar |
| Others |
Supply & Pricing Matrix
Forty-five to sixty days of silicon wafer inventory now separates hydrometallurgical specialists from mechanical shredders, concentrating margin capture in the Rhine-Rhône corridor where French ingot manufacturers bid against spot metallurgical buyers. This inventory banding locks in pricing power for processors with verified semiconductor-grade output while spot-dependent operators absorb feedstock cost volatility.
Pricing Analysis
Mechanical-first versus hydrometallurgical-first pricing gaps now span three technology generations across European processors. Contract-based long-term offtake agreements dominate compliant tier-1 procurement, with price differentiation driven by silicon purity certification and mass-balance audit trails. Cost compression in mechanical shredding is intensifying because glass-encapsulant bonding limits wafer recovery yields. Utility-scale asset owners show least price sensitivity for verified closed-loop silicon, while decommissioning contractors face acute margin pressure on spot-traded polycrystalline feedstock.
Supply Chain Analysis
Inventory positioning at German mechanical facilities runs 30-50% leaner than hydrometallurgical counterparts due to feedstock quality uncertainty. Supply concentrates in Germany, France, and Italy where EPR enforcement guarantees collection volumes. The chain draws from aluminum smelter byproduct streams, acid leaching reagent suppliers, and specialized pyrometallurgical gas infrastructure. Single-source vulnerability sits with natural gas supply for thin-film cadmium-telluride recovery. Distribution runs through vertically integrated waste groups with existing weighbridge and blockchain traceability systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward utility-scale asset owners unbundling end-of-life obligations from original EPC contracts, fragmenting procurement authority away from equipment manufacturers. This disintermediation concentrates contract negotiation leverage with specialist processors who assume direct liability retention.
For Market Incumbents: Secure mass-balance verified recycling contracts ahead of Spain's delayed waste cliff, locking in feedstock volumes before greenfield capacity placement accelerates. Defensive consolidation through hydrometallurgical circuit investments counters the threat of emerging pure-plays capturing semiconductor-grade silicon premiums. Channel control over cross-border logistics infrastructure anchors pricing power against Polish and Romanian arbitrage operators. For New Entrants and Emerging Players: Lead with specialized pyrometallurgical capacity for thin-film cadmium-telluride recovery, where First Solar's captive takeback program channels dedicated feedstock to under-supplied smelters. Spain's 2008-2012 installation surge entering end-of-life from 2033-2037 represents the most penetrable geography for greenfield placement. A go-to-market angle anchored to EU Critical Raw Materials Act qualification unlocks strategic project financing for domestic gallium and tellurium recovery. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated environmental services conglomerates with underutilized mechanical shredding assets in Germany and France. Long-term viability over a 5-10 year window hinges on hydrometallurgical technology maturation and semiconductor-grade silicon certification pathway development. The signal to watch is utility-scale asset owner direct contracting patterns displacing original EPC bundled obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Capacity Expansion | French processors near Lyon deploy acid leaching circuits to supply Rhône-Alpes semiconductor ingot manufacturers. |
| Mass-Balance Verification Investment | Weighbridge integration and blockchain traceability systems satisfy France's 85% recycling rate audit requirements. |
| Cross-Border Feedstock Logistics Control | German-French silicon corridor concentration captures value through Rhine-Rhône industrial axis material flows. |
| Thin-Film Pyrometallurgical Partnership | First Solar's European takeback program channels dedicated cadmium-telluride feedstock to specialized smelters. |
| Spain Greenfield Pre-Positioning | Andalusia desert solar farm decommissioning activity accelerates ahead of 2033-2037 volume arrival. |
Research Methodology
Initial hypotheses were tested against primary input from utility-scale asset managers, EPC decommissioning contractors, waste processing facility operators, and ingot manufacturer procurement leads and refined through secondary validation. Primary fieldwork combined structured interviews with German electrical equipment registry administrators and French extended producer responsibility decree enforcement officers. Secondary sources encompassed EU Waste Framework Directive transposition documents, national SISTRI and packaging registry filings, and REACH hazardous substance threshold determinations. Bottom-up feedstock volume modeling triangulated against top-down EPR registration fee revenue analysis.
Variance decomposition across technology pathway, module chemistry, and national regulatory cluster segmentation anchored the analytical framework. Modeled dimensions spanned mechanical versus hydrometallurgical versus pyrometallurgical recovery methods, monocrystalline versus polycrystalline versus thin-film versus bifacial product architectures, and manufacturer versus installer versus waste management company versus research institution end-user categories. CAGRs were derived from installation vintage retirement curves cross-referenced with EPR-mandated collection rate trajectories. Forecast inputs incorporated natural gas price volatility exposure for thin-film smelters and semiconductor-grade silicon spot market spread dynamics.
The analysis sits within stated boundaries; outcomes outside sustained EPR enforcement intensity or accelerated module degradation profiles would require recalibration. Forecasts reflect documented assumptions regarding national transposition timeline adherence and cross-border waste movement documentation standardization. Regulatory divergence between EU harmonized targets and member state implementation schedules, alongside fluoropolymer fluorine handling permitting delays, constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Global Lead Recycling Battery Market