
 North America Lithium-Ion Battery Recycling Market | 2026-2036
North America Lithium-Ion Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lithium-Ion Battery Recycling Market Analysis
Automotive OEMs are reorganizing procurement priorities around closed-loop battery materials, displacing traditional scrap merchants as the dominant feedstock buyers. Redwood Materials, Inc. leverages its Nevada hub to anchor pyrometallurgical processing capacity for gigafactory adjacent recycling. Li-Cycle Corp competes through hydrometallurgical specialization that sustains higher lithium recovery rates than conventional smelting routes. American Battery Technology Company differentiates via integrated direct recycling research targeting cathode regeneration without full elemental decomposition.
North America Lithium-Ion Battery Recycling encompasses the collection, disassembly, and chemical recovery of spent lithium-ion cells to regenerate battery-grade lithium, cobalt, nickel, and manganese compounds for reuse in new cell manufacturing. The process requires controlled atmosphere shredding, electrolyte neutralization, and selective precipitation to achieve the purity thresholds demanded by cathode precursor synthesis. Hydrometallurgical routes dominate current installed capacity due to lower energy intensity and superior lithium yields compared to pyrometallurgical alternatives. Direct recycling occupies a nascent but strategically critical position as automakers seek to preserve crystalline cathode structures and reduce re-manufacturing costs. End user segmentation reveals automotive manufacturers as the structural demand anchor, with industrial equipment and utilities representing emerging volume pools as stationary storage deployments mature.
The US EPA hazardous waste regulations and the Inflation Reduction Act's critical mineral sourcing thresholds jointly constrain market access for non-compliant recyclers while creating preferential demand channels for domestic material recovery. Health Canada and the Canadian Environmental Protection Act impose parallel tracking requirements for cross-border battery waste movements that shape logistics network design across the Great Lakes corridor. Ontario's extended producer responsibility framework and California's SB 1215 battery recycling mandates add state-provincial layer compliance complexity. Stakeholders must monitor evolving cathode chemistry transitions toward lithium iron phosphate and high-nickel formulations that will alter recovery economics and processing technology selection.
Market Dynamics
The US Inflation Reduction Act's domestic content requirements are forcing automotive OEMs to restructure cathode material sourcing toward North American processing infrastructure, compressing supply chain timelines and displacing Asian-sourced black mass intermediates.
Growth Catalysts
- Critical mineral sourcing thresholds:The IRA's domestic content rules create preferential offtake channels for battery-grade lithium, cobalt, and nickel recovered within North American borders. Automotive OEMs now prioritize closed-loop supply agreements with regional recyclers to secure tax credit eligibility.
- Extended producer responsibility mandates:California's SB 1215 and Ontario's battery stewardship frameworks impose collection quotas on manufacturers, guaranteeing feedstock volumes for processing capacity expansion across the Great Lakes corridor.
- Lithium iron phosphate chemistry transition:The shift toward LFP cathodes in commercial vehicles and stationary storage systems concentrates recovery demand on lithium and phosphate streams, favoring hydrometallurgical routes with superior lithium yields over pyrometallurgical alternatives.
Market Restraints
- Feedstock supply concentration:Spent battery volumes remain concentrated among a limited cohort of early-generation EV fleets and consumer electronics aggregators, creating volume uncertainty for greenfield processing investments in Nevada and Arizona.
- Cross-border hazardous waste friction:Health Canada's tracking requirements under the Canadian Environmental Protection Act impose documentation burdens on Great Lakes logistics networks, elevating compliance costs for US recyclers sourcing Canadian battery waste.
- Electrolyte neutralization complexity:The presence of lithium hexafluorophosphate and organic carbonate solvents in end-of-life cells requires controlled atmosphere infrastructure that elevates capital intensity above comparable metals recycling operations.
Strategic Opportunities
- Stationary storage decommissioning wave:Utility-scale battery installations deployed in California and Texas during the early 2020s will reach end-of-life within the forecast window, creating a concentrated volume pool distinct from automotive feedstock.
- Direct recycling technology maturation:Cathode regeneration without full elemental decomposition preserves crystalline structures and reduces re-manufacturing energy intensity, positioning early movers for premium pricing from automakers seeking circularity credentials.
- Great Lakes industrial corridor clustering:Proximity to Michigan and Ohio gigafactory construction creates captive demand for black mass and precursor materials, enabling toll-processing arrangements that minimize working capital requirements.
Industry Challenges
- Battery passport data interoperability:The absence of standardized digital traceability protocols across US and Canadian jurisdictions complicates feedstock qualification for IRA-compliant material recovery, delaying qualification timelines for cross-border shipments.
- Pyrometallurgical emissions compliance:EPA hazardous waste regulations and state-level air quality permits impose multi-year approval cycles for high-temperature processing capacity, constraining the pace of supply expansion relative to demand growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lithium-Ion Battery Recycling Market |
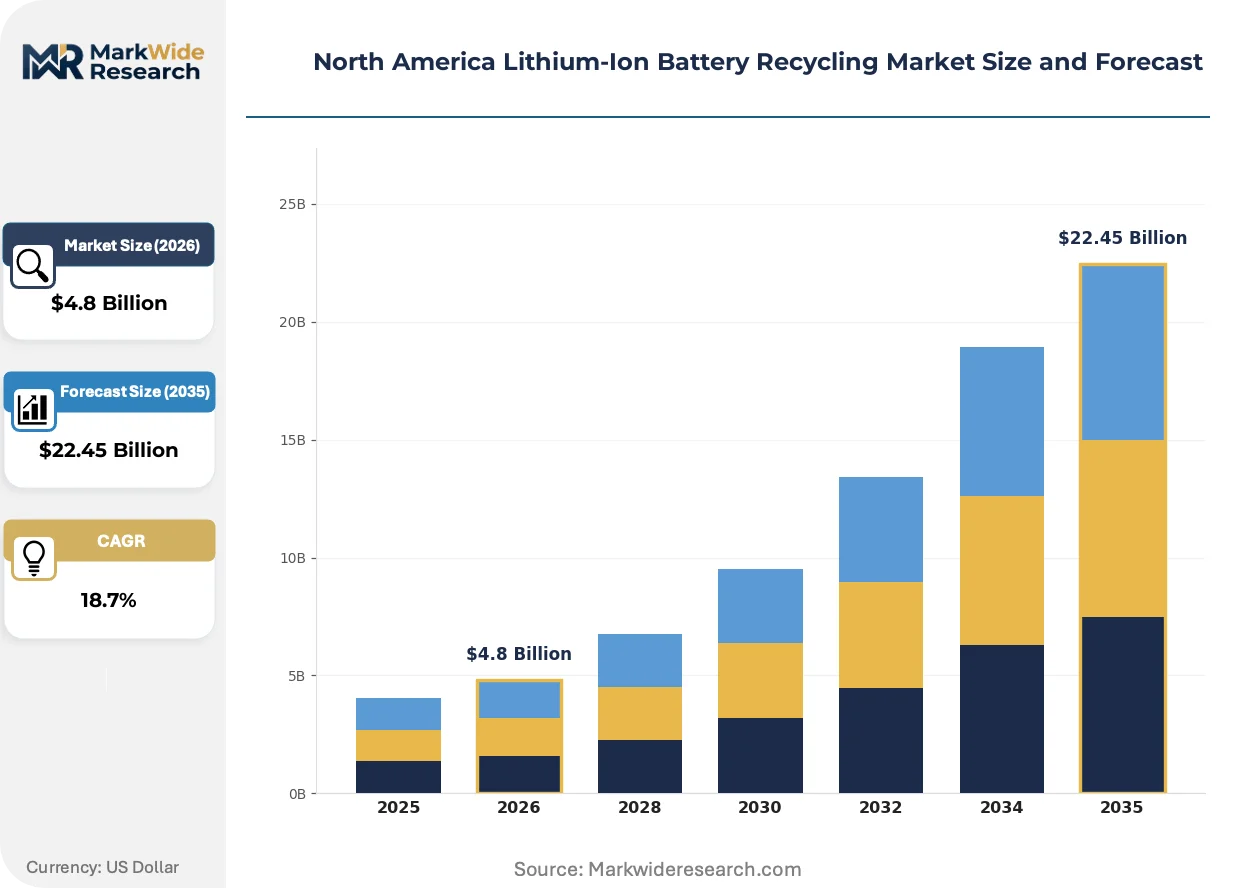
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Type: Retail Collection, Industrial Collection, Drop-off Stations, Incentive Programs Technology: Hydrometallurgical, Pyrometallurgical, Direct Recycling, Biochemical End User: Automotive Manufacturers, Consumer Electronics, Industrial Equipment, Utilities Process Stage: Pre-processing, Refining, Material Recovery, Waste Management |
| Companies Covered | Li-Cycle Corp, Retriev Technologies, American Zinc Recycling, Lithion Recycling Inc., American Manganese Inc., Redwood Materials, Inc., Cirba Solutions, American Battery Technology Company, RecycLiCo Battery Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lithium-Ion Battery Recycling Market Emerging Trajectories
Processing technology selection is bifurcating around feedstock chemistry and end-use purity requirements, with hydrometallurgical routes gaining share for lithium-dominant streams while pyrometallurgy retains cobalt-nickel concentration advantages.
Direct recycling is bifurcating the competitive landscape between elemental recovery specialists and cathode regeneration innovators. Automotive OEMs with in-house cell design capabilities are piloting partnerships that preserve crystalline cathode structures, compressing re-entry timelines for recovered materials into new cell manufacturing. This technology is bifurcating margin structures across the value chain, rewarding integrated players with tolling arrangements over merchant black mass traders.
The US EPA is tightening hazardous waste classification for end-of-life batteries containing electrolyte residues, reclassifying certain lithium-ion formats as universal waste requiring manifest documentation. This regulatory compression is elevating capital requirements for shredder operations and accelerating consolidation among smaller collection aggregators. California and Michigan are responding with state-level permitting fast-tracks for facilities achieving battery passport data interoperability.
Automotive OEMs are consolidating cathode material procurement around closed-loop offtake agreements with named recycling partners, displacing spot-market black mass transactions that dominated early market development. This concentration is compressing margins for traditional scrap merchants and elevating qualification barriers for new processing entrants. The shift is most visible in Michigan and Ohio, where gigafactory-adjacent recycling hubs are securing decade-long supply contracts with volume floors.
North America Lithium-Ion Battery Recycling Market Segmentation
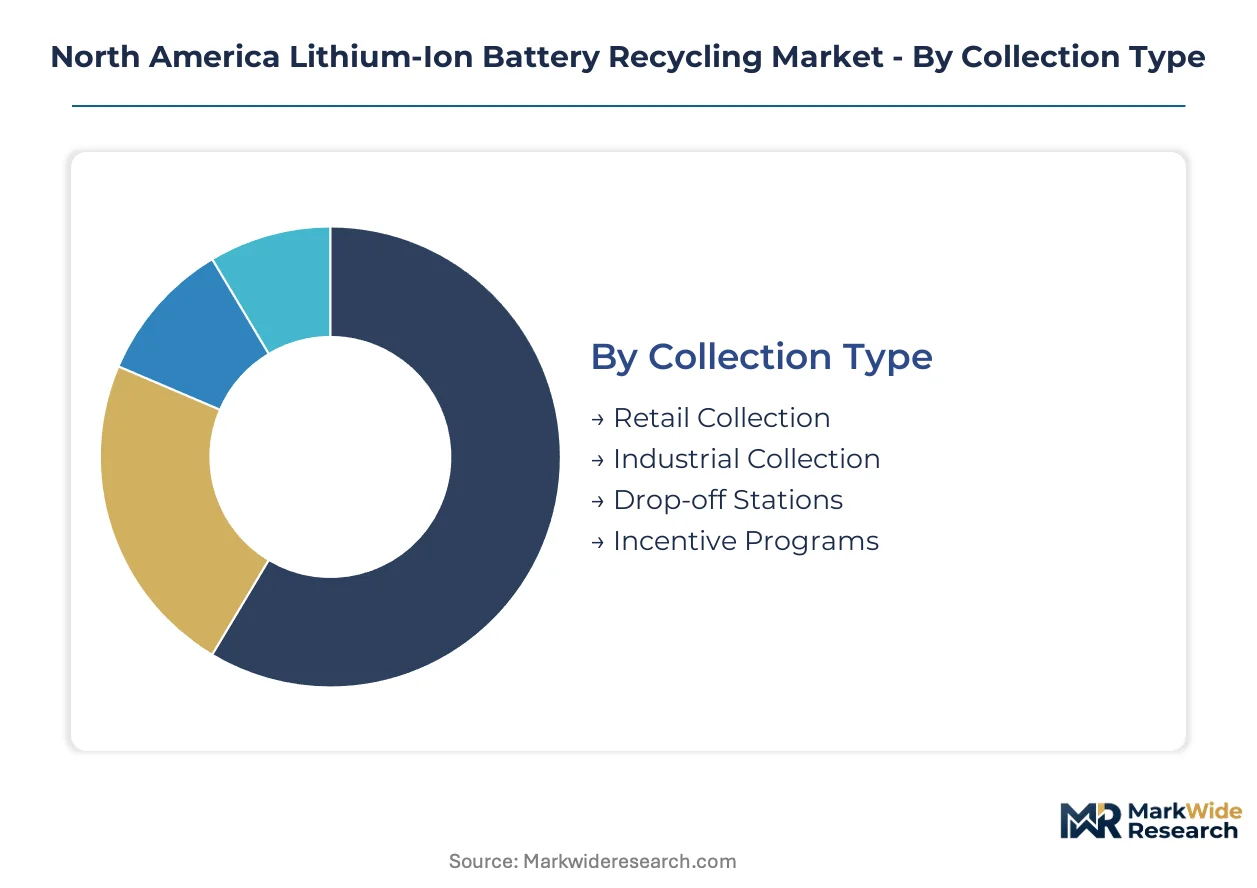
Segmentation in the North America lithium-ion battery recycling market reveals how collection logistics, processing chemistry, and end-use demand create distinct competitive arenas. Each dimension carries specific regulatory footprints and capital requirements that shape operator positioning across the Great Lakes corridor and southwestern processing hubs.
Collection Type:
Domestic feedstock channels concentrate in Michigan and Ohio industrial corridors, while export-oriented collection networks source Canadian battery waste across the Great Lakes.
- Retail Collection:Consumer electronics retailers and auto dealerships serve as aggregation nodes for small-format cells. Demand clusters in California and Ontario where extended producer responsibility mandates guarantee volume floors for regional processors.
- Industrial Collection:Direct contracts with automotive OEMs and gigafactory operators secure high-volume, chemistry-known feedstock streams. This channel anchors procurement for Nevada and Arizona pyrometallurgical hubs seeking IRA-compliant domestic content qualification.
- Drop-off Stations:Municipal and retail-hosted collection points capture dispersed consumer batteries. EPA universal waste classification elevates handling compliance costs for operators managing these fragmented inbound streams.
- Incentive Programs:State-level battery buyback schemes in California and Michigan accelerate consumer participation rates. These programs create predictable volume commitments that de-risk greenfield shredding investments.
Industrial Collection holds the largest share; momentum sits with Incentive Programs as state mandates expand across the Great Lakes corridor.
Technology:
Cost tier stratification separates high-capex pyrometallurgical infrastructure from lower-barrier hydrometallurgical and biochemical alternatives.
- Hydrometallurgical:Aqueous chemical leaching achieves superior lithium recovery rates compared to thermal routes. This technology dominates installed capacity across the Great Lakes corridor where lithium-dominant LFP chemistries from Michigan gigafactories demand maximum lithium yield.
- Pyrometallurgical:High-temperature smelting concentrates cobalt and nickel into alloy intermediates. Nevada-based operators leverage this route for black mass processing adjacent to Tesla and Panasonic cell manufacturing, though EPA air quality permits impose multi-year approval cycles.
- Direct Recycling:Cathode regeneration preserves crystalline structures without full elemental decomposition. Early pilots in Michigan target premium pricing from automakers seeking circularity credentials and compressed re-entry timelines.
- Biochemical:Microbial and enzymatic recovery processes remain pre-commercial but attract research investment for reduced energy intensity. Canadian federal grants support pilot development in Ontario targeting low-carbon processing claims.
Hydrometallurgical commands current installed capacity; Direct Recycling is expanding most quickly as OEM partnerships mature.
End User:
Application-driven demand splits between mobility-focused automotive procurement and stationary storage volumes concentrated in utility procurement cycles.
- Automotive Manufacturers:Closed-loop offtake agreements with named recycling partners now dominate cathode material procurement. Michigan and Ohio gigafactory construction creates captive demand for precursor materials with decade-long contract structures.
- Consumer Electronics:Smartphone and laptop battery aggregation supplies legacy cobalt-lithium chemistries. California's SB 1215 mandates impose collection quotas that guarantee feedstock volumes for regional processors.
- Industrial Equipment:Forklift and warehouse automation batteries contribute nickel-manganese-cobalt streams. This segment gains share as logistics electrification accelerates across US distribution centers.
- Utilities:Stationary storage decommissioning from early-2020s California and Texas deployments will create concentrated volume pools distinct from automotive feedstock within the forecast window.
Automotive Manufacturers anchor structural demand; Utilities represent the steepest expansion trajectory as grid-scale installations mature.
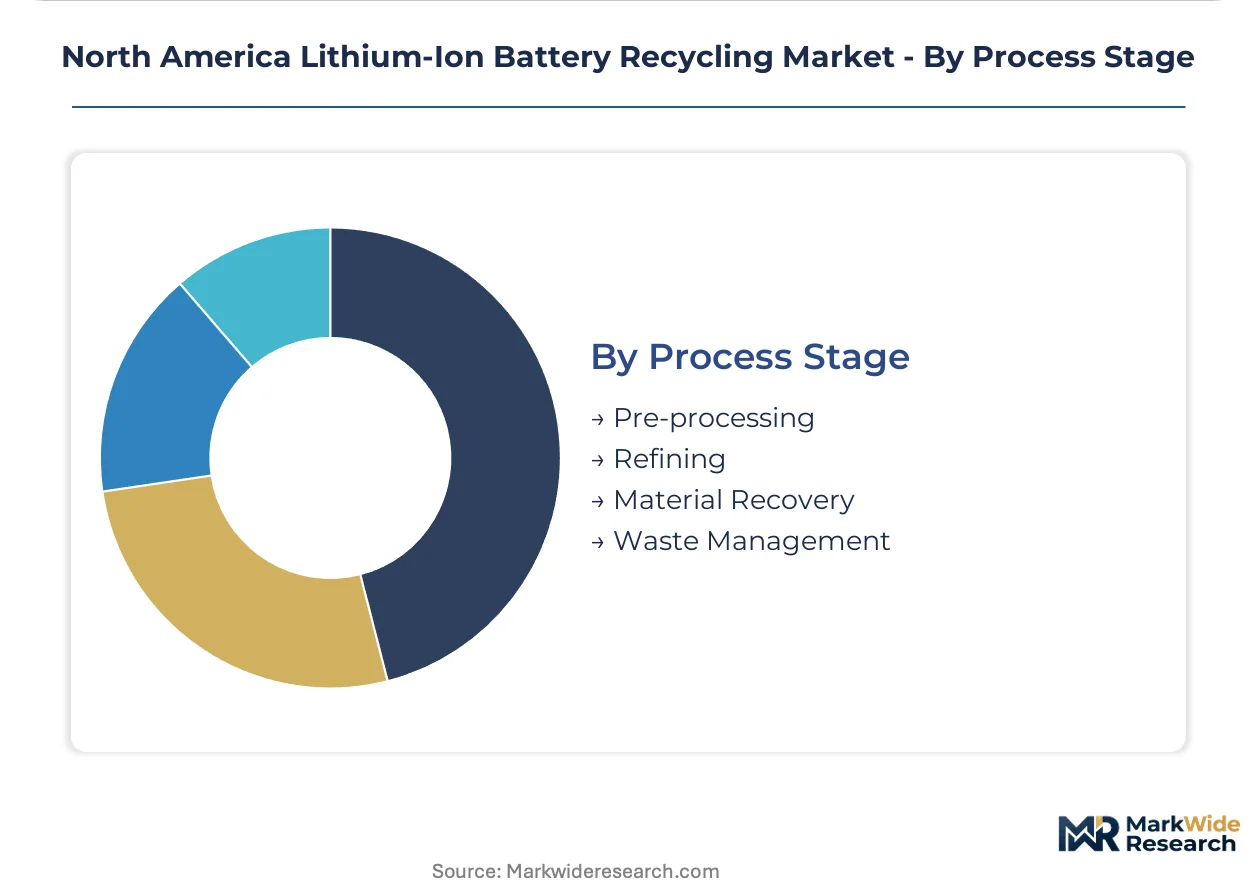
Process Stage:
Margin concentration varies across the value chain, with material recovery commanding premium returns versus commoditized waste management services.
- Pre-processing:Controlled atmosphere shredding and electrolyte neutralization require specialized infrastructure. EPA hazardous waste regulations elevate capital barriers for new entrants in this stage.
- Refining:Black mass upgrading and intermediate purification steps concentrate value capture. Great Lakes corridor operators leverage toll-processing arrangements with Michigan gigafactories to minimize working capital requirements.
- Material Recovery:Battery-grade lithium, cobalt, nickel, and manganese compound production achieves highest purity premiums. IRA domestic content thresholds create preferential demand channels for North American recovery output.
- Waste Management:Residue handling and non-recyclable fraction disposal complete the processing chain. Cross-border hazardous waste friction between US and Canadian jurisdictions elevates compliance costs for integrated operators.
Material Recovery captures the largest value share; momentum concentrates in Refining as tolling arrangements proliferate across the Great Lakes corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian battery waste flows southward across the Great Lakes corridor to feed Michigan and Ohio processing capacity, while Nevada and Arizona hubs draw feedstock from California's early EV fleets and stationary storage decommissioning.
United States
Michigan and Ohio gigafactory construction anchors demand for recovered cathode precursors, with IRA domestic content rules compelling automakers to source battery-grade lithium, cobalt, and nickel from North American recyclers. EPA hazardous waste regulations under the Resource Conservation and Recovery Act impose manifest documentation on cross-state battery shipments, elevating compliance costs for collection networks. Nevada's industrial corridor around Reno hosts pyrometallurgical capacity adjacent to Tesla and Panasonic cell manufacturing, securing decade-long offtake agreements with volume floors.
Canada
Ontario's extended producer responsibility framework guarantees feedstock volumes through manufacturer collection quotas, creating predictable inbound streams for provincial processors. Health Canada's tracking requirements under the Canadian Environmental Protection Act impose documentation burdens on battery waste exports to US refiners, shaping logistics network design across the Great Lakes. The Windsor-Quebec City corridor concentrates shredding and pre-processing infrastructure serving Detroit-area automotive demand.
Mexico
Baja California and Sonora manufacturing zones generate consumer electronics battery waste that feeds into Arizona hydrometallurgical hubs seeking lithium-dominant chemistries. Mexico's environmental regulator SEMARNAT classifies spent lithium-ion cells as hazardous waste requiring licensed transport for cross-border movement to US processing facilities. The Tijuana-San Diego logistics corridor channels small-format battery aggregation toward California's SB 1215 compliance networks.
North America Lithium-Ion Battery Recycling Market Vendor Landscape
Listed leaders compete with private specialists across technology routes and geographic positioning, creating a tiered structure where scale-driven pyrometallurgical operators coexist with hydrometallurgical lithium specialists and direct recycling innovators. The competitive landscape fragments across three strategic archetypes: integrated gigafactory-adjacent hubs securing captive offtake, standalone hydrometallurgical specialists maximizing lithium recovery rates, and direct recycling researchers targeting cathode regeneration without elemental decomposition. Dominant competitive moves include strategic partnerships with automotive OEMs for closed-loop supply agreements and capacity expansion across the Great Lakes corridor to capture IRA-compliant domestic content demand.
Within the integrated hub archetype, Redwood Materials, Inc. and Li-Cycle Corp occupy positions anchoring contrasting technology approaches across the US West and Great Lakes regions. American Battery Technology Company exemplifies the direct recycling research tier, while Retriev Technologies and Cirba Solutions represent established collection and pre-processing specialists feeding downstream refiners. These named entities illustrate how competitive positioning stratifies around technology specialization, geographic proximity to automotive demand clusters, and qualification for IRA-compliant material recovery channels.
| Leading Market Players |
|---|
| Li-Cycle Corp |
| Retriev Technologies |
| American Zinc Recycling |
| Lithion Recycling Inc. |
| American Manganese Inc. |
| Redwood Materials, Inc. |
| Cirba Solutions |
| American Battery Technology Company |
| RecycLiCo Battery Materials Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for black mass intermediates concentrate margin capture among Great Lakes corridor refiners, compressing spot-market liquidity and elevating contract-based offtake premiums for IRA-compliant domestic content. This lead-time structure rewards integrated operators with captive gigafactory relationships while squeezing merchant traders dependent on volatile cross-border feedstock arbitrage.
Pricing Analysis
The technology-generation pricing gap separates hydrometallurgical lithium recovery at premium tiers from pyrometallurgical cobalt-nickel concentrates at standard levels, with direct recycling pilots commanding economy-plus positioning for unproven scale. Contract-based long-term offtake structures dominate, with price differentiation resting on IRA domestic content certification and volume scale commitments. Cost compression in standard-tier pyrometallurgical output is intensifying because EPA air quality permits constrain capacity expansion relative to demand growth. Automotive OEMs demonstrate least price sensitivity for battery-grade lithium compounds, while scrap merchants and spot-market aggregators face acute margin pressure from qualified feedstock scarcity.
Supply Chain Analysis
Inventory concentration in Michigan and Ohio shredding facilities creates working capital intensity that favors toll-processing arrangements over merchant ownership models. Geographic supply concentration centers on the United States, Canada, and Mexico, with Canadian battery waste flows drawing from Ontario's extended producer responsibility quotas. Raw material dependencies rest on spent automotive cells, consumer electronics aggregation, and stationary storage decommissioning streams. Single-source vulnerability from limited qualified pre-processing capacity elevates disruption risk from EPA hazardous waste enforcement actions. Distribution runs through gigafactory-adjacent hubs securing decade-long supply contracts with volume floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
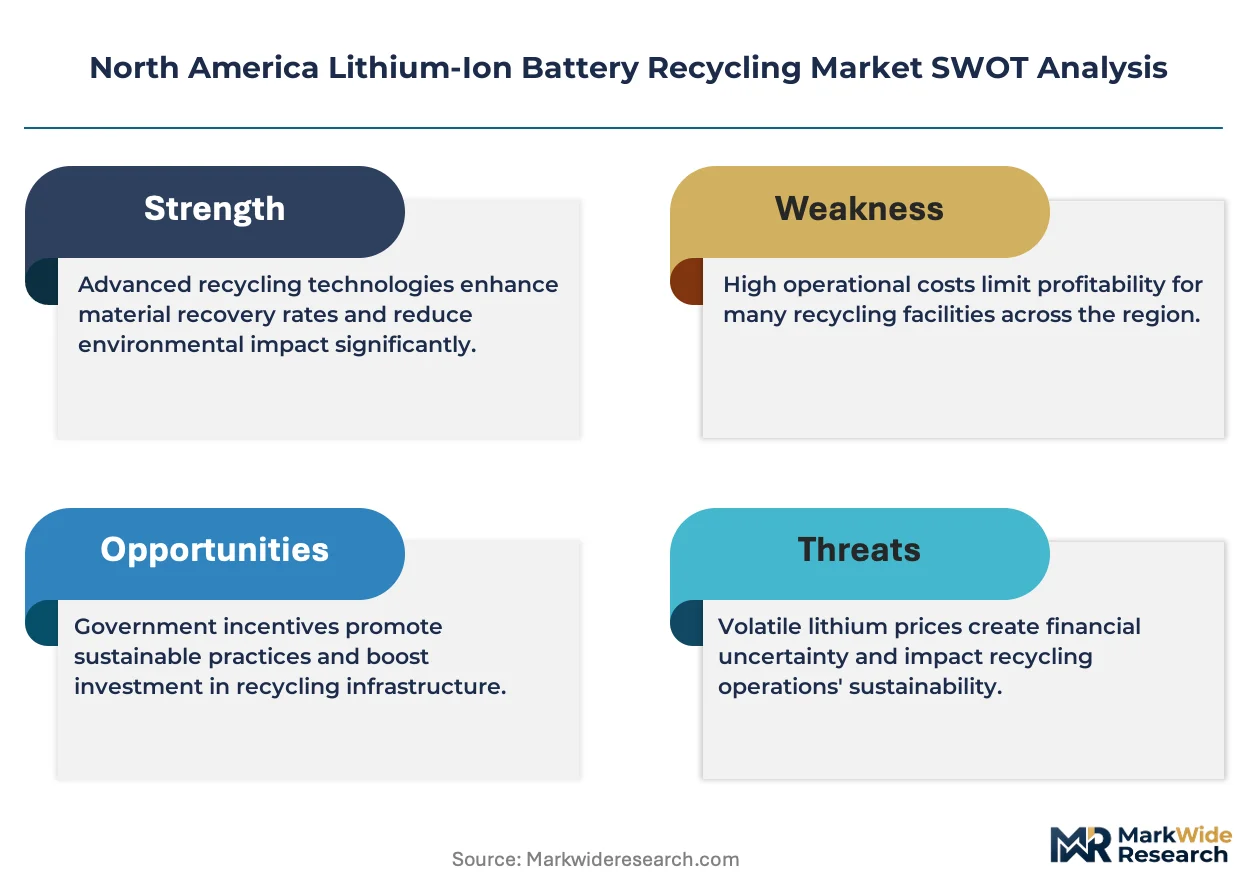
The North America lithium-ion battery recycling market rewards operators with qualified pre-processing infrastructure and IRA-compliant material recovery capabilities, while penalizing fragmented collection networks lacking controlled atmosphere shredding assets. Qualified technical talent for electrolyte neutralization and selective precipitation chemistry remains the binding constraint on capacity expansion timelines.
For Market Incumbents: Consolidate control over Great Lakes corridor collection networks to secure captive feedstock volumes against emerging hydrometallurgical specialists. Deepen backward integration into pre-processing infrastructure to capture margin concentration from EPA hazardous waste compliance barriers. Prioritize certification investment for battery passport data interoperability to accelerate cross-border Canadian feedstock qualification timelines. For New Entrants and Emerging Players: Lead with direct recycling technology partnerships targeting Michigan and Ohio automotive OEMs seeking cathode regeneration without full elemental decomposition. The most penetrable white space sits in utility-scale stationary storage decommissioning from early-2020s California and Texas deployments, a volume pool distinct from automotive feedstock concentration. Pursue toll-processing arrangements with established refiners to minimize working capital requirements while proving technology scale. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded pre-processing assets lacking downstream refining integration. Long-term viability over the next decade hinges on positioning for lithium iron phosphate chemistry transitions that favor hydrometallurgical lithium yields over pyrometallurgical cobalt-nicket concentration. Watch for EPA universal waste reclassification enforcement as the inflection signal accelerating consolidation among sub-scale collection aggregators.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Great Lakes corridor shredding investments capture IRA-compliant feedstock flows from Ontario and Michigan gigafactories. |
| Backward Integration | Controlled atmosphere pre-processing assets secure margin concentration from EPA hazardous waste compliance barriers. |
| Long-term Supply Agreement | Decade-long offtake contracts with volume floors de-risk greenfield hydrometallurgical investments against feedstock uncertainty. |
| Technology Licensing | Direct recycling cathode regeneration partnerships command premium positioning from automakers seeking circularity credentials. |
| Joint Venture | Cross-border Canadian-US processing collaborations navigate Health Canada tracking requirements under the Canadian Environmental Protection Act. |
Methodological Framework
Desk research of EPA regulatory filings, state-level extended producer responsibility mandates, and automotive OEM sustainability disclosures preceded structured interviews with battery recycling plant managers, cathode material procurement leads at gigafactory operators, hazardous waste compliance officers, and hydrometallurgical process engineers. Secondary validation drew from SEC 10-K filings of listed recycling specialists, customs data on cross-border battery waste movements, and IRA domestic content guidance documents. Bottom-up feedstock volume modeling and top-down cathode material demand projections were triangulated against installed capacity announcements across Nevada, Arizona, and the Great Lakes corridor.
Variance decomposition across technology routes, collection channel types, and end-user segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include processing chemistry, feedstock source, process stage, and geographic regulatory cluster. CAGRs were derived from fitted growth curves calibrated to IRA implementation timelines and gigafactory construction schedules. Industry-specific forecast inputs incorporated cathode chemistry transition assumptions toward lithium iron phosphate and high-nickel formulations, plus stationary storage deployment and decommissioning curves from California and Texas utility procurement data.
Underlying assumptions cover IRA domestic content rule continuity, EPA hazardous waste classification stability, and lithium iron phosphate chemistry penetration rates in commercial vehicle segments, with deviation risk concentrated in cross-border regulatory friction between US and Canadian jurisdictions and battery passport data interoperability standardization delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Global Lead-Acid Battery Scrap Market