
 Middle East and Africa Lithium-Ion Battery Recycling Market | 2026-2036
Middle East and Africa Lithium-Ion Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lithium-Ion Battery Recycling Market Foresight
Scarce hydrometallurgical chemists is reorganizing recruitment pipelines across the Middle East and Africa lithium-ion battery recycling sector. Aqua Metals Inc leverages its proprietary AquaRefining technology to differentiate in low-emissions lead and lithium recovery. Umicore N.V. anchors its regional presence through precious metals refining expertise transferred from European operations. Li-Cycle Holdings competes via its spoke-and-hub model adapted for distributed feedstock collection in emerging African markets.
Lithium-ion battery recycling encompasses the collection, dismantling, and chemical recovery of cathode materials containing lithium cobalt oxide, lithium iron phosphate, and nickel-manganese-cobalt compositions from spent cells, typically operating at recovery efficiencies exceeding 95% for cobalt and nickel through hydrometallurgical leaching. The process serves primarily to reintroduce battery-grade metals into cathode precursor manufacturing, reducing virgin mining dependence for electric vehicle and energy storage supply chains. Hydrometallurgical methods dominate margin pools due to lower energy intensity and higher selectivity for lithium recovery compared to pyrometallurgical alternatives. Direct recycling occupies a nascent but expanding position as cell-to-cell regeneration pathways mature for lithium iron phosphate chemistries common in regional renewable energy storage deployments. Mechanical separation sustains volume leadership in consumer electronics feedstock preprocessing where cell heterogeneity complicates chemical routes.
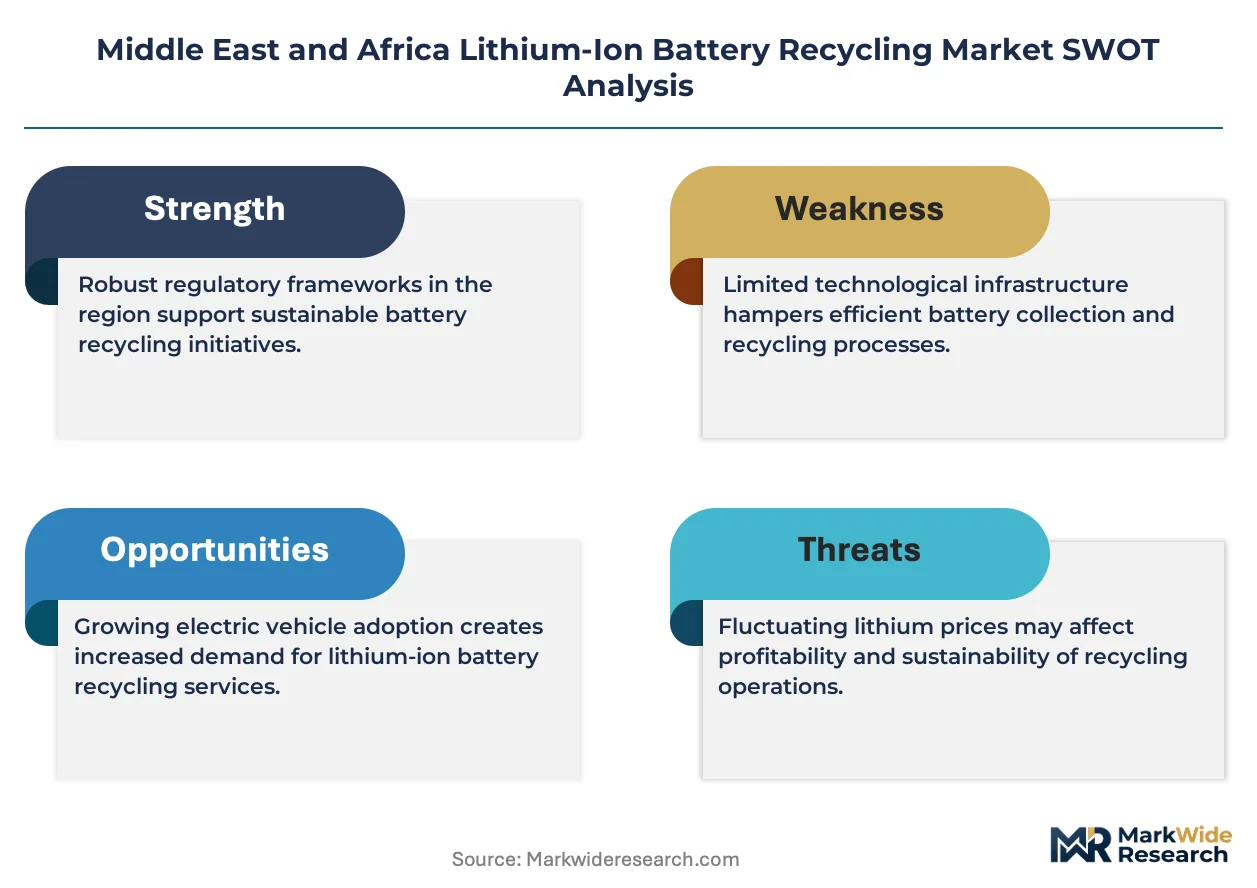
Saudi Arabia's SFDA and the UAE's Ministry of Climate Change and Environment are tightening hazardous waste tracking requirements for cross-border battery shipments, compelling recyclers to localize preprocessing capacity. South Africa's DEFF administers extended producer responsibility regulations that mandate automotive manufacturers to fund collection infrastructure for end-of-life traction batteries. Stakeholders must monitor how Egypt's emerging environmental compliance framework and Morocco's positioning as a phosphate-processing hub reshape regional feedstock flows and technology licensing decisions.
Market Dynamics
Saudi Arabia's gigafactory investments near Jeddah and Dammam are concentrating feedstock supply, forcing recyclers to co-locate preprocessing capacity within industrial city boundaries to secure battery waste streams.
Growth Catalysts
- Extended producer responsibility mandates:South Africa's DEFF regulations compel automotive manufacturers to fund collection infrastructure for end-of-life traction batteries, creating guaranteed feedstock pipelines.
- Hydrometallurgical recovery efficiency:Selective lithium extraction methods now exceed 95% recovery rates for cobalt and nickel, improving unit economics against virgin mining.
- UAE cross-border waste tracking:The Ministry of Climate Change and Environment's hazardous shipment rules are localizing preprocessing capacity to avoid compliance costs.
Market Restraints
- Specialized chemist scarcity:Hydrometallurgical expertise shortages across the region inflate recruitment costs and delay plant commissioning timelines.
- Feedstock concentration risk:Consumer electronics preprocessing dominance in mechanical separation routes locks margins to volatile smartphone and laptop retirement cycles.
- Pyrometallurgical energy intensity:High thermal processing costs disadvantage smelting-based recovery against lower-emission chemical alternatives in markets with rising carbon compliance costs.
Strategic Opportunities
- Egypt's emerging environmental framework:Nascent battery waste regulations create first-mover advantages for recyclers establishing collection networks before compliance mandates harden.
- Direct recycling pathway maturation:Cell-to-cell regeneration for lithium iron phosphate chemistries opens premium pricing in renewable energy storage verticals.
- Morocco phosphate-processing synergies:Existing phosphoric acid infrastructure offers backward integration potential for lithium iron phosphate cathode precursor manufacturing.
Industry Challenges
- Hydrometallurgical talent pipelines:Universities across South Africa and the UAE lack specialized curricula, forcing recyclers to import technical leadership or build in-house training programs.
- Cross-border certification complexity:Divergent hazardous waste classifications between Saudi Arabia's SFDA and UAE regulators create shipment delays and documentation rework.
- Legacy mechanical separation integration:Existing shredding and sorting assets require retrofitting to handle newer cell formats with silicon-anode and solid-state architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lithium-Ion Battery Recycling Market |
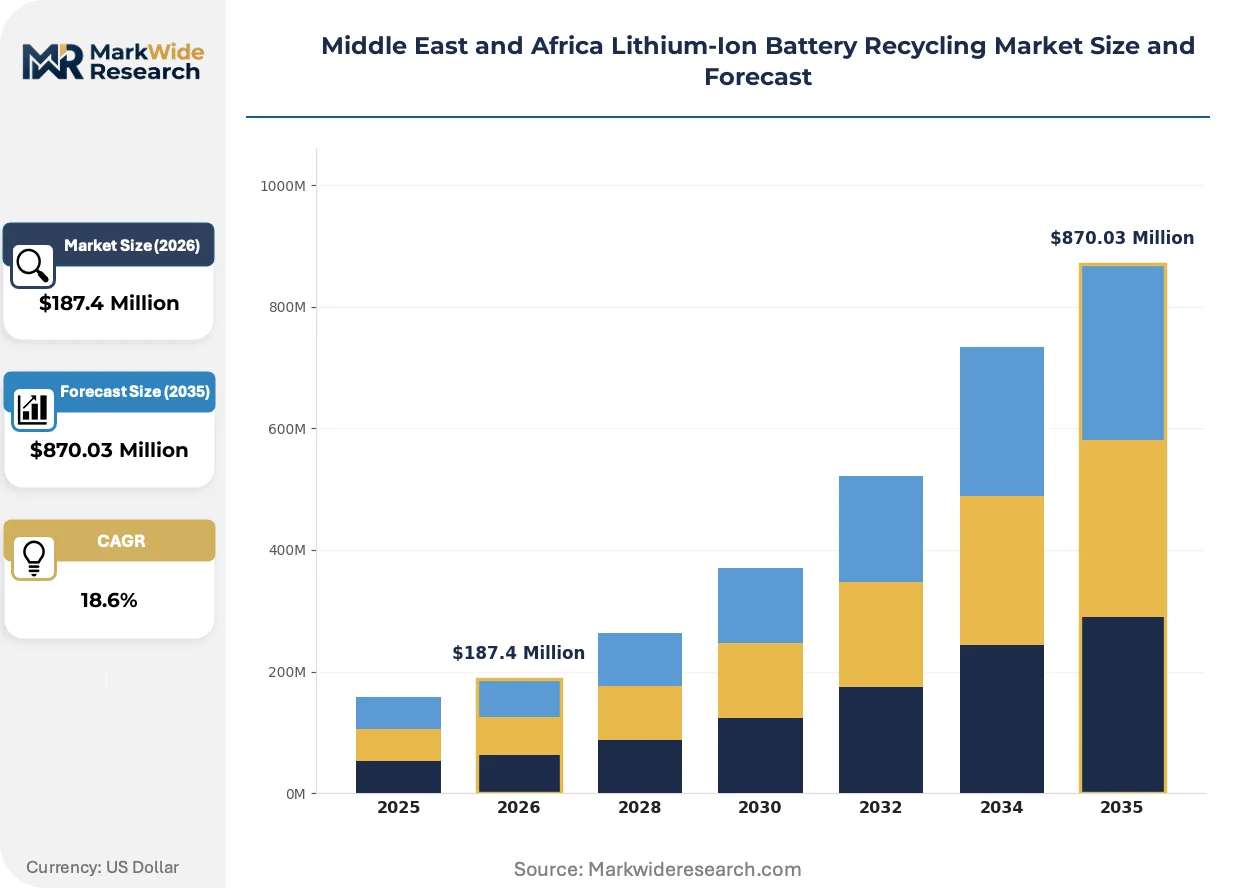
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Industrial Use, Renewable Energy Storage Recycling Method: Hydrometallurgical, Pyrometallurgical, Direct Recycling, Mechanical Separation End User: Automotive Manufacturers, Electronics Producers, Waste Management Firms, Battery Distributors Technological Advancement: Innovation in Recycling Processes, Improvement in Material Recovery, AI in Sorting, Automation in Plant Operations |
| Companies Covered | Ganfeng Lithium Group, Aqua Metals Inc, Umicore N.V., American Battery Technology Company, Cirba Solutions, Li-Cycle Holdings, LG Energy Solution Ltd., Retriev Technologies Inc, Redwood Materials, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lithium-Ion Battery Recycling Market Shifts & Advancements
Technology pathways in Middle East and Africa lithium-ion battery recycling are diverging between high-volume mechanical preprocessing and selective chemical recovery, with regulatory pressure accelerating capital deployment toward lower-emission routes.
Hydrometallurgical leaching is bifurcating competitive positioning between integrated spoke-and-hub operators and standalone preprocessing specialists. Gigafactory developers in Saudi Arabia's industrial cities are prioritizing offtake agreements with recyclers possessing in-house chemical recovery rather than mechanical-only capabilities. This technology split is compressing margins for shredding-dependent operators while enabling premium pricing for closed-loop metal recovery.
The UAE's Ministry of Climate Change and Environment extended producer responsibility guidelines are mandating producer-funded collection infrastructure. Automotive OEMs must now finance reverse logistics networks or face import restrictions on new electric vehicle models. Fleet operators across Dubai and Abu Dhabi are responding by consolidating end-of-life battery volumes to achieve minimum efficient scale for recycler pickup.
Electric vehicle fleet operators are unbundling after-sales service contracts from original equipment manufacturers to negotiate direct recycler relationships. South African logistics and mining fleets are leading this disintermediation, seeking metal credit arrangements that offset replacement battery costs. This procurement evolution is most visible in Johannesburg and Cape Town, where large fleet concentrations enable multi-year offtake agreements with fixed metal pricing clauses.
Middle East and Africa Lithium-Ion Battery Recycling Market Segmentation
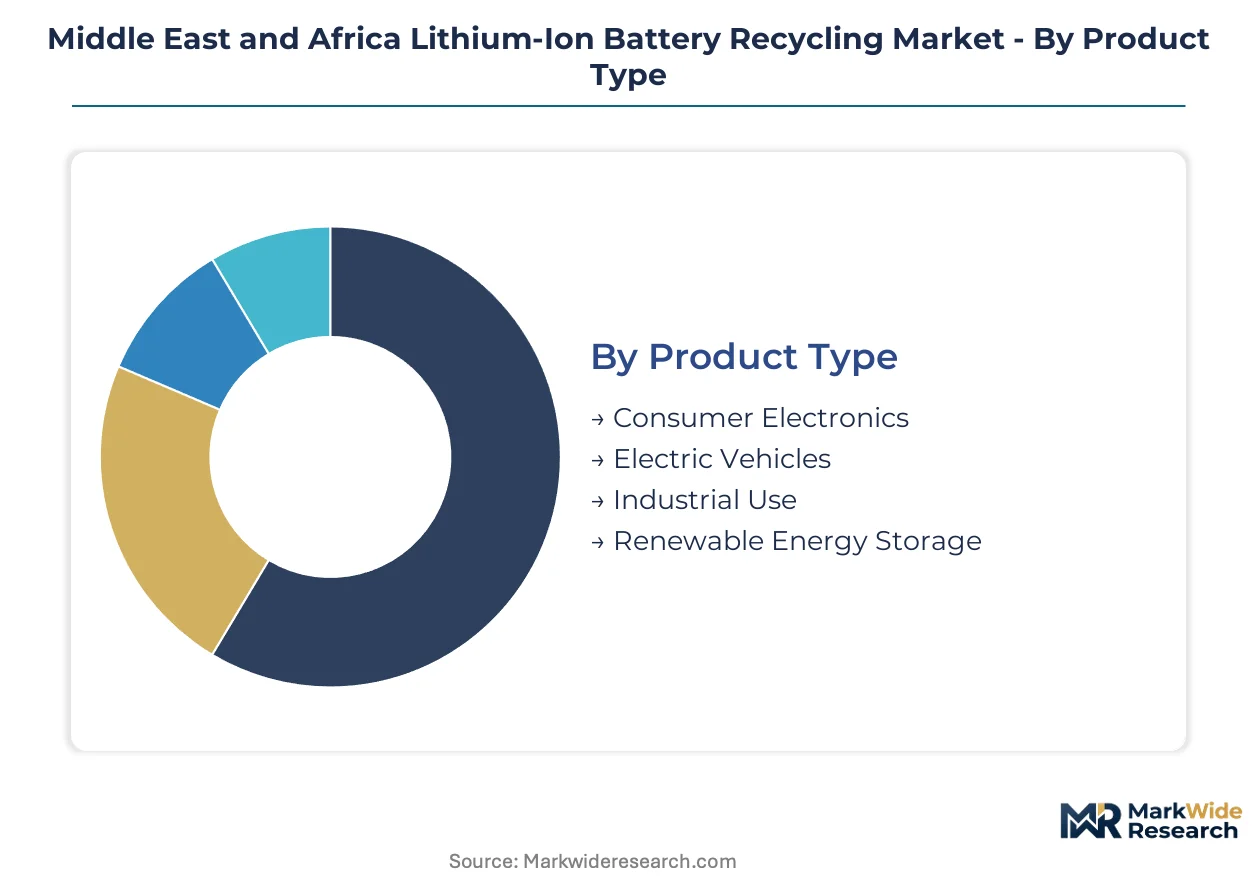
Feedstock heterogeneity across the Middle East and Africa lithium-ion battery recycling market demands precise segmentation to align preprocessing capacity with cell chemistry profiles. Each dimension reveals distinct margin structures and capital deployment priorities for recyclers navigating regional regulatory fragmentation.
Product Type:
Margin pools concentrate where cathode material value density intersects with collection infrastructure maturity.
- Electric Vehicles:Traction batteries with nickel-manganese-cobalt and lithium iron phosphate chemistries command premium recovery economics due to high metal content and standardized formats. Demand clusters near Jeddah and Dammam industrial cities where Saudi gigafactory investments are generating predictable end-of-life volumes.
- Consumer Electronics:Portable device batteries with lithium cobalt oxide compositions offer established collection networks through retail reverse logistics but suffer from cell heterogeneity that complicates automated sorting. South African urban centers dominate preprocessing volumes due to concentrated electronics consumption and existing mechanical separation infrastructure.
- Industrial Use:Forklift and stationary power batteries provide steady feedstock pipelines from mining and logistics operations across Johannesburg and Cape Town.
- Renewable Energy Storage:Grid-scale lithium iron phosphate installations in UAE solar projects are creating emerging retirement cycles with cell-to-cell regeneration potential.
The dominant share belongs to Consumer Electronics, while Electric Vehicles is closing the gap fastest.
Recycling Method:
Technology selection determines access to battery-grade metal offtake agreements with cathode precursor manufacturers.
- Hydrometallurgical:Selective leaching achieves recovery efficiencies exceeding 95% for cobalt and nickel through acid-based dissolution and solvent extraction. The method's lower energy intensity versus thermal alternatives attracts capital in markets where UAE and Saudi regulators are tightening carbon compliance frameworks.
- Pyrometallurgical:High-temperature smelting processes recover base metals through reduction but sacrifice lithium to slag and face escalating energy costs across the region. Plants near Dammam industrial zones leverage existing natural gas infrastructure to partially offset thermal expense disadvantages.
- Direct Recycling:Cell-to-cell regeneration preserves cathode crystal structure for lithium iron phosphate chemistries common in renewable energy storage, enabling premium pricing in closed-loop arrangements.
- Mechanical Separation:Shredding and sorting operations handle preprocessing volume leadership for consumer electronics feedstock where cell diversity complicates chemical routes.
Hydrometallurgical processes capture the value-dense segment, with Direct Recycling expanding most quickly as regeneration pathways mature.
End User:
Procurement authority shapes contract structures from cost-plus service fees to metal credit arrangements.
- Automotive Manufacturers:Extended producer responsibility mandates from South Africa's DEFF and emerging UAE regulations compel OEMs to fund collection infrastructure or face import restrictions. These stakeholders negotiate multi-year offtake agreements with fixed metal pricing clauses to hedge cathode material cost volatility.
- Electronics Producers:Smartphone and laptop manufacturers face fragmented feedstock geography but possess established reverse logistics networks through retail partnerships across Dubai and Johannesburg.
- Waste Management Firms:Municipal and industrial waste handlers are consolidating battery volumes to achieve minimum efficient scale for recycler pickup, particularly in Egyptian urban centers where environmental compliance frameworks are nascent.
- Battery Distributors:Aftermarket suppliers are disintermediating OEM service contracts to negotiate direct recycler relationships and capture metal credit value.
Automotive Manufacturers hold the procurement anchor position, though Battery Distributors are gaining share fastest through fleet operator disintermediation.
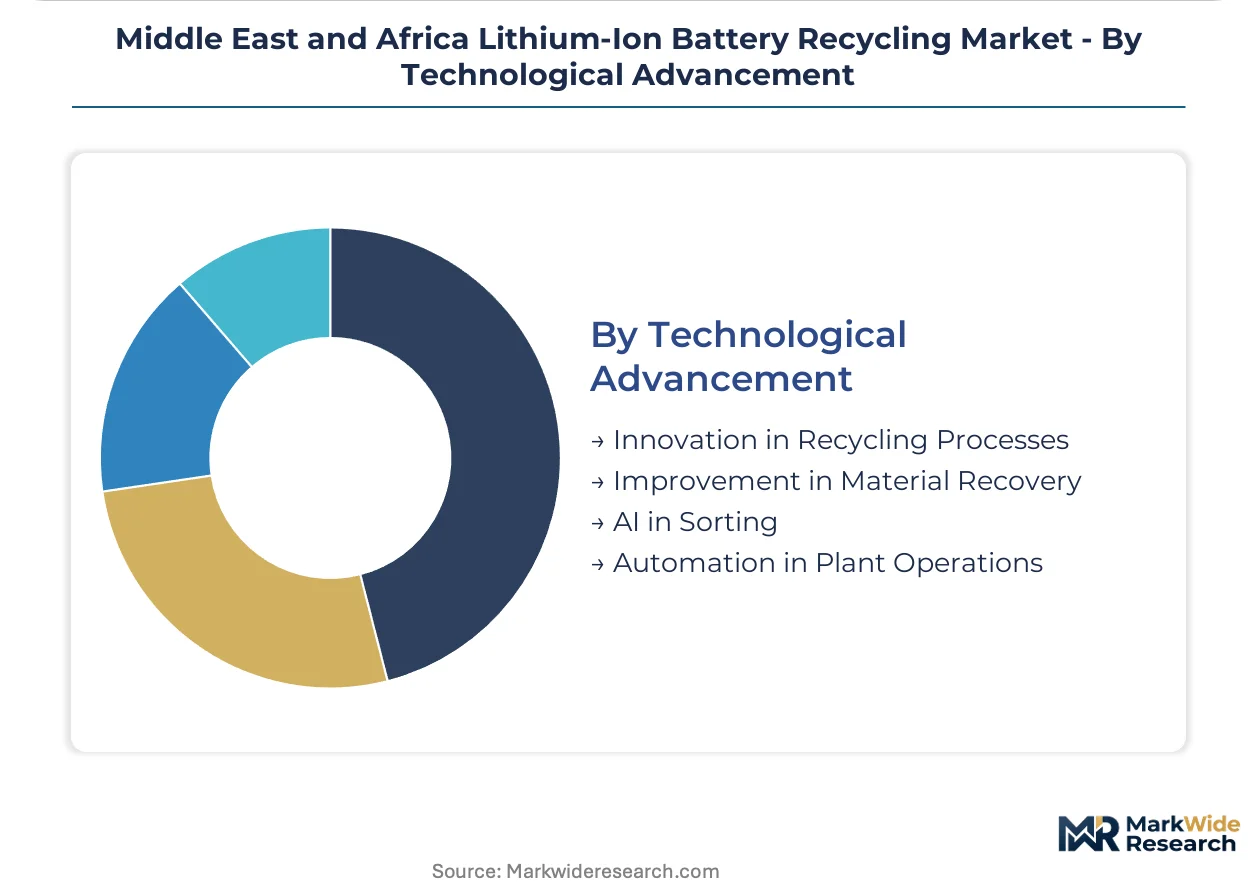
Technological Advancement:
Automation intensity separates capital-efficient mechanical operators from integrated chemical recovery players.
- Innovation in Recycling Processes:Proprietary leaching chemistries and electrochemical regeneration techniques differentiate technology licensors competing for Saudi gigafactory offtake partnerships.
- Improvement in Material Recovery:Advanced separation technologies targeting lithium recovery from pyrometallurgical slag and black mass upgrading are closing efficiency gaps with virgin mining economics.
- AI in Sorting:Machine vision and spectral identification systems handle cell chemistry recognition for mixed feedstock streams, reducing manual preprocessing labor requirements.
- Automation in Plant Operations:Robotic dismantling and conveyor-based sorting lines minimize exposure to hazardous electrolytes and thermal runaway risks in high-volume facilities.
Improvement in Material Recovery commands current investment focus, while AI in Sorting is climbing the fastest as feedstock heterogeneity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes lithium-ion battery recycling capacity through gigafactory-linked preprocessing, while South Africa and the UAE deploy divergent models shaped by fleet operator structures and extended producer responsibility frameworks.
Saudi Arabia
Gigafactory investments near Jeddah and Dammam industrial cities are generating concentrated end-of-life battery volumes from electric vehicle production. The SFDA enforces hazardous waste tracking requirements that compel recyclers to localize preprocessing capacity within industrial city boundaries. Dammam's existing natural gas infrastructure attracts pyrometallurgical operators seeking to offset thermal processing costs against tightening carbon compliance frameworks.
United Arab Emirates
Electric vehicle fleet operators across Dubai and Abu Dhabi are consolidating end-of-life battery volumes to achieve minimum efficient scale for recycler pickup. The Ministry of Climate Change and Environment mandates producer-funded collection infrastructure through extended producer responsibility guidelines that restrict imports of non-compliant electric vehicle models. Industrial preprocessing clusters are forming in Jebel Ali free zone to serve cross-border feedstock flows from neighboring Gulf markets.
South Africa
Logistics and mining fleet operators in Johannesburg and Cape Town are disintermediating original equipment manufacturer service contracts to negotiate direct recycler relationships with metal credit arrangements. The Department of Environment, Forestry and Fisheries administers extended producer responsibility regulations compelling automotive manufacturers to fund collection infrastructure. Pretoria's academic institutions are struggling to supply hydrometallurgical chemists, forcing recyclers to import technical leadership or build in-house training programs.
Egypt
Waste management firms in Cairo and Alexandria are consolidating battery volumes to achieve minimum efficient scale before environmental compliance frameworks harden. The country's emerging environmental regulator is developing battery waste classifications that will reshape regional feedstock flows once implemented. Suez Canal Economic Zone positioning offers potential preprocessing hub status for recyclers seeking Mediterranean access.
Morocco
Existing phosphoric acid infrastructure from phosphate processing offers backward integration potential for lithium iron phosphate cathode precursor manufacturing. Casablanca's industrial zones are attracting technology licensors seeking to leverage chemical process synergies. The country's national environmental regulator is aligning hazardous waste classifications with European standards to facilitate technology transfer agreements.
Middle East and Africa Lithium-Ion Battery Recycling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding premium offtake agreements through in-house chemical recovery capabilities and the latter competing on preprocessing volume and feedstock aggregation. The market structure concentrates margin pools among hydrometallurgical operators capable of battery-grade metal output, while mechanical separation specialists face compression from gigafactory developers prioritizing closed-loop arrangements. Three archetypes dominate: integrated spoke-and-hub operators, standalone preprocessing specialists, and technology licensors. Competitive moves center on co-location partnerships with gigafactory developers and proprietary leaching chemistry licensing to secure feedstock pipelines.
Among technology-integrated operators, Aqua Metals Inc and Li-Cycle Holdings exemplify the capital-intensive archetype pursuing closed-loop metal recovery positioning. Umicore N.V. anchors the precious metals refining specialist tier, leveraging transferable expertise from European operations. These three represent divergent strategic postures: proprietary electrochemical regeneration, distributed spoke-and-hub network deployment, and precious metals refining integration respectively.
| Leading Market Players |
|---|
| Ganfeng Lithium Group |
| Aqua Metals Inc |
| Umicore N.V. |
| American Battery Technology Company |
| Cirba Solutions |
| Li-Cycle Holdings |
| LG Energy Solution Ltd. |
| Retriev Technologies Inc |
| Redwood Materials |
| Others |
Supply & Pricing Matrix
Gigafactory-scale preprocessing clusters near Jeddah and Dammam industrial cities concentrate capital deployment, compressing unit costs for integrated hydrometallurgical operators while elevating price floors for mechanical-only competitors lacking chemical recovery capabilities. This scale dynamic locks in tiered margin structures where closed-loop metal recovery commands premium offtake terms against shredding-dependent volume plays.
Pricing Analysis
Long-term offtake agreements with fixed metal pricing clauses dominate procurement between Saudi gigafactory developers and integrated recyclers, insulating buyers from cobalt and nickel volatility while squeezing spot-market intermediaries. Price differentiation rests on recovery purity grades and SFDA hazardous waste certification tiers, with battery-grade lithium carbonate output capturing substantial premiums over technical-grade alternatives. Cost compression in mechanical preprocessing is intensifying because consumer electronics feedstock heterogeneity erodes automated sorting yields. Fleet operators in South Africa and the UAE demonstrate the highest price sensitivity, negotiating metal credit arrangements that offset replacement battery costs, whereas automotive manufacturers under extended producer responsibility mandates accept cost-plus structures to secure compliance pathways.
Supply Chain Analysis
Strait of Hormuz transit underwrites feedstock security for UAE preprocessing hubs serving cross-border Gulf volumes, while Suez Canal access positions Egyptian consolidators for Mediterranean distribution. Raw material flows draw from South African mining fleet retirements, Saudi gigafactory production scrap, and UAE solar storage installations. Single-source vulnerability concentrates in hydrometallurgical reagent supply chains anchored to European specialty chemical producers. Distribution runs through Jebel Ali free zone bonded warehousing and Dammam industrial city co-location partnerships, with last-mile collection increasingly consolidated by waste management firms achieving minimum efficient scale thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where extended producer responsibility mandates create switching costs that cement incumbent positioning once collection infrastructure achieves critical mass.
For Market Incumbents: Shield feedstock pipelines by deepening co-location partnerships with Saudi gigafactory developers before competitor preprocessing capacity secures industrial city boundaries. Prioritize in-house hydrometallurgical chemist training programs to offset Pretoria's academic supply shortfall and deflect poaching from emerging entrants. Cement channel control through multi-year offtake agreements with fixed metal pricing clauses that lock in automotive OEM compliance spending. For New Entrants and Emerging Players: Fleet operator disintermediation in Johannesburg and Cape Town represents the most penetrable service-layer gap, where incumbent OEM service contracts leave metal credit value unharvested. Egypt's nascent environmental compliance framework offers white-space for pre-regulatory collection network establishment before mandate hardening. Target waste management firms in Cairo and Alexandria with minimum efficient scale aggregation partnerships as the go-to-market angle, bypassing direct automotive OEM sales cycles. For Investors and Strategic Acquirers: Standalone preprocessing specialists with mechanical separation assets and established South African urban collection networks present acquisition targets ripe for hydrometallurgical retrofitting. Long-term viability across the analysis window hinges on regulatory enforcement consistency in extended producer responsibility regimes. Watch for SFDA-UAE hazardous waste classification harmonization as the inflection signal indicating cross-border shipment rationalization and regional consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Capacity Expansion | Captures premium offtake terms from Saudi gigafactory developers prioritizing closed-loop metal recovery. |
| Extended Producer Responsibility Compliance | Locks in guaranteed feedstock pipelines from automotive OEMs facing South African DEFF import restrictions. |
| Direct Recycling Technology Licensing | Enables cell-to-cell regeneration positioning for UAE solar storage verticals with lithium iron phosphate chemistries. |
| Cross-Border Collection Network | Consolidates Egyptian waste management volumes before environmental framework hardening creates first-mover advantages. |
| Backward Integration into Reagent Supply | Reduces European specialty chemical dependency that currently concentrates hydrometallurgical processing risk. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hydrometallurgical plant managers, automotive OEM sustainability officers, UAE waste management executives, and South African fleet operations directors; and secondary validation through Saudi SFDA hazardous waste filings, South African DEFF extended producer responsibility registrations, UAE Ministry of Climate Change and Environment guidelines, customs trade data for cross-border battery shipments, and SEC disclosures from listed recycling technology providers. Bottom-up feedstock volume estimates triangulated against top-down gigafactory production capacity projections.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning cathode chemistry profiles, recycling method technology tiers, end-user procurement authority structures, and geographic regulatory clusters. CAGRs derived from capacity utilization curves, feedstock retirement cycle modeling, and enforcement trajectory assumptions for extended producer responsibility mandates. Industry-specific inputs incorporated hydrometallurgical recovery efficiency improvements and direct recycling pathway maturation timelines for lithium iron phosphate chemistries.
Forecasts assume regulatory continuity in Saudi SFDA hazardous waste tracking and South African DEFF extended producer responsibility regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include hydrometallurgical chemist supply constraints delaying plant commissioning, cross-border certification divergence between Gulf regulators, and pyrometallurgical energy cost spikes. Practitioners should keep alternative scenarios live as gigafactory construction timelines and environmental enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
India Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Europe Solar Panel Recycling Market