
 Electric Vehicle Battery Reuse and Recycling Market | 2026-2036
Electric Vehicle Battery Reuse and Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Reuse and Recycling Market Insights
Direct procurement channels between automakers and recycling specialists is tilting toward long-term offtake agreements with embedded feedstock guarantees. Li-Cycle Corp. leverages its spoke-and-hub network design to secure geographically distributed feedstock access across North America and Europe. Umicore anchors its competitive position through integrated refining capabilities that recover high-purity cobalt, nickel, and lithium for resale to cathode producers. Redwood Materials competes by building co-located collection and processing infrastructure adjacent to major automotive manufacturing corridors.
Electric vehicle battery reuse and recycling encompasses the collection, testing, disassembly, and material recovery of batteries that have reached end-of-first-life in mobility applications, with lithium-ion packs typically retaining 70-80% of initial capacity when retired from automotive duty cycles. The primary industrial purpose centers on extracting valuable transition metals and reconditioning viable cells for secondary deployment in stationary storage or lower-power mobility. Hydrometallurgical processing dominates investment flows due to superior recovery rates for lithium and graphite compared with pyrometallurgical alternatives. Direct recycling approaches are gaining structural traction as the fastest-growing method category, preserving cathode crystal structures and reducing reprocessing energy intensity. End-user demand concentrates most heavily among battery manufacturers seeking certified recycled feedstock to meet emerging regulatory quotas.
The EU Battery Regulation and REACH frameworks mandate minimum recycled content thresholds and full supply chain traceability, compelling recyclers to invest in digital passport systems and mass-balance certification. EPA hazardous waste rules in the United States classify certain end-of-life batteries as universal waste, streamlining interstate transport while imposing strict manifest documentation requirements that favor large-scale centralized processors. China's MIIT and SAMR administer dual carbon goals and GB standards that enforce producer responsibility for new energy vehicle batteries, creating captive recycling demand tied to domestic manufacturing permits. Stakeholders must monitor how divergent national implementations of extended producer responsibility reshape cross-border feedstock flows and processing economics.
Market Dynamics
The EU Battery Regulation's mandatory recycled content quotas are forcing automakers to redesign supply chains around closed-loop material recovery, compressing decades of linear sourcing into a half-decade transition window.
Growth Catalysts
- REACH and EU Battery Regulation thresholds:Automakers must source minimum recycled lithium, cobalt, and nickel by mandated deadlines, creating guaranteed offtake demand for certified recyclers.
- Stationary energy storage operators:These buyers are emerging as the fastest-growing purchaser segment for second-life battery packs, absorbing retired automotive cells at scale.
- Hydrometallurgical processing:Superior recovery rates for lithium and graphite compared with pyrometallurgical alternatives are attracting capital investment toward wet-chemistry refining infrastructure.
Market Restraints
- Feedstock supply concentration:End-of-life battery availability clusters in Germany, China, and the United States, leaving processors in other geographies feedstock-constrained.
- Cobalt and lithium price volatility:Raw material input swings compress recycler margins when spot prices diverge from long-term offtake contract terms.
- Pyrometallurgical lock-in:Existing smelter infrastructure cannot economically recover lithium, forcing stranded asset risk on operators with sunk capital in high-temperature processing.
Strategic Opportunities
- Direct recycling technology convergence:Methods preserving cathode crystal structures are reducing reprocessing energy intensity, opening cost advantages over conventional hydrometallurgy.
- Digital passport systems:Mass-balance certification platforms enable premium pricing for fully traceable recycled content, differentiating compliant operators.
- India's PLI scheme extension:Battery manufacturing incentives are creating captive recycling demand tied to domestic cell production permits.
Industry Challenges
- Battery passport data interoperability:Divergent national implementations of extended producer responsibility are fragmenting traceability standards across EU member states.
- Disassembly automation capex:Pack-to-cell dismantling requires robotics investment that mid-scale processors cannot amortize at current feedstock volumes.
- Cell chemistry heterogeneity:Proliferating cathode formulations complicate sorting and preprocessing, reducing economies of scale in batch processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Reuse and Recycling Market |
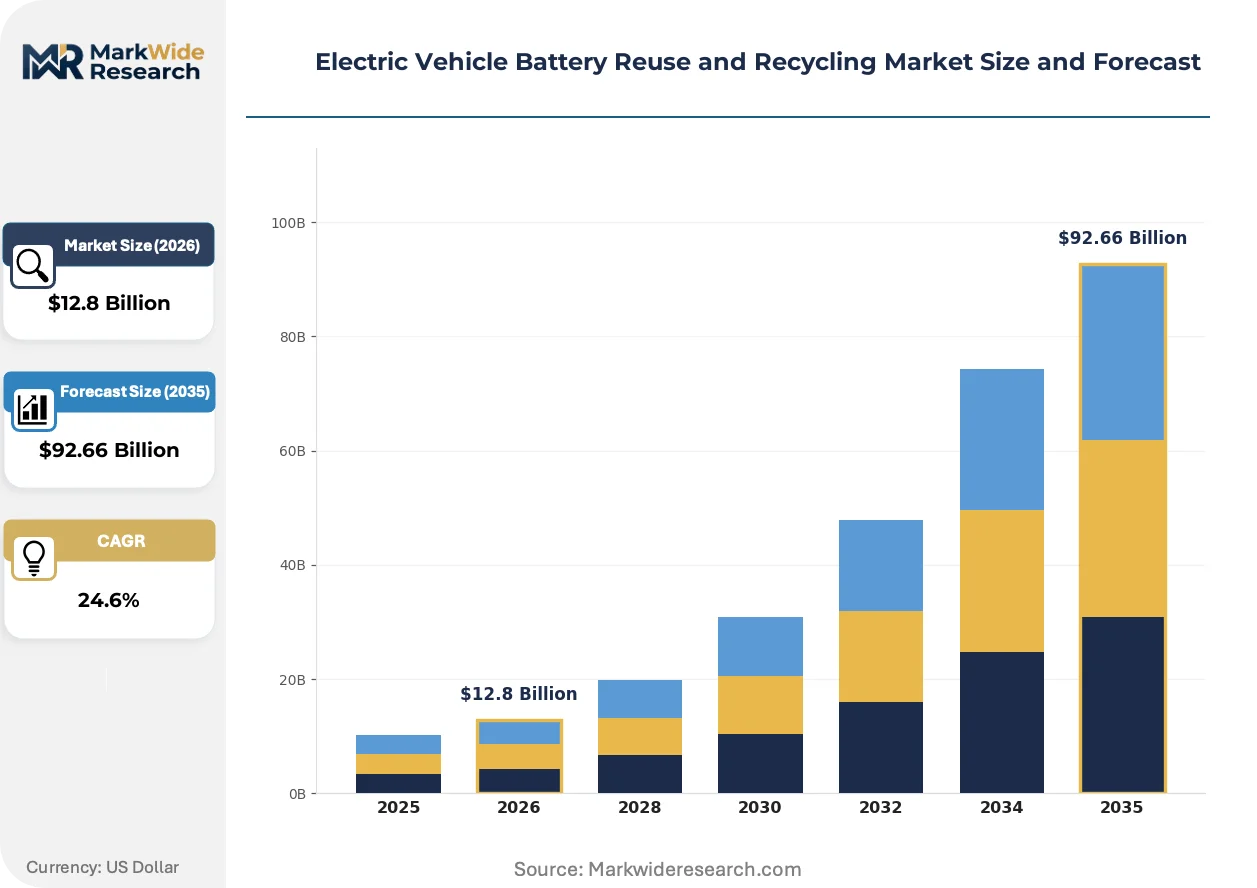
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $92.66 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Recycling Method: Pyrometallurgical, Hydrometallurgical, Direct Recycling, Biological End User: Automakers, Battery Manufacturers, Recycling Facilities, Renewable Energy Systems Distribution Channel: Direct Sales, Online Sales, Third-Party Distributors, Partnerships |
| Companies Covered | Li-Cycle Corp., Umicore, Redwood Materials, Ascend Elements, Guangdong Brunp Recycling Technology Co. Ltd., Nissan Motor/4R Energy, Renault Group, Connected Energy, RePurpose Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Reuse and Recycling Market Trends and Innovations
Processing technology, regulatory architecture, and procurement logic are simultaneously restructuring how value flows through post-automotive battery channels.
Direct recycling approaches are collapsing the energy and reagent intensity of cathode material recovery by preserving original crystal structures rather than dissolving and reprecipitating active materials. Battery manufacturers seeking certified recycled feedstock are piloting these methods at commercial scale. The structural consequence is a compression of unit processing costs that threatens to undercut conventional hydrometallurgical operators within this decade.
China's MIIT and SAMR dual carbon goals enforce producer responsibility for new energy vehicle batteries through GB standards that tie recycling permits to manufacturing licenses. Domestic automakers must demonstrate closed-loop material recovery or face production caps. This regulatory architecture is most acutely affecting cathode producers, who are integrating backward into preprocessing to secure compliant feedstock.
Long-term offtake agreements with embedded feedstock guarantees are displacing spot-market purchasing among stationary energy storage developers. These buyers require decade-long supply certainty for grid-scale deployments, favoring recyclers with proven collection networks and refining capacity. Germany's industrial clustering around Hamburg and Stuttgart exhibits this pattern most visibly, with utilities signing multi-year contracts before facilities reach operational status.
Electric Vehicle Battery Reuse and Recycling Market Segmentation
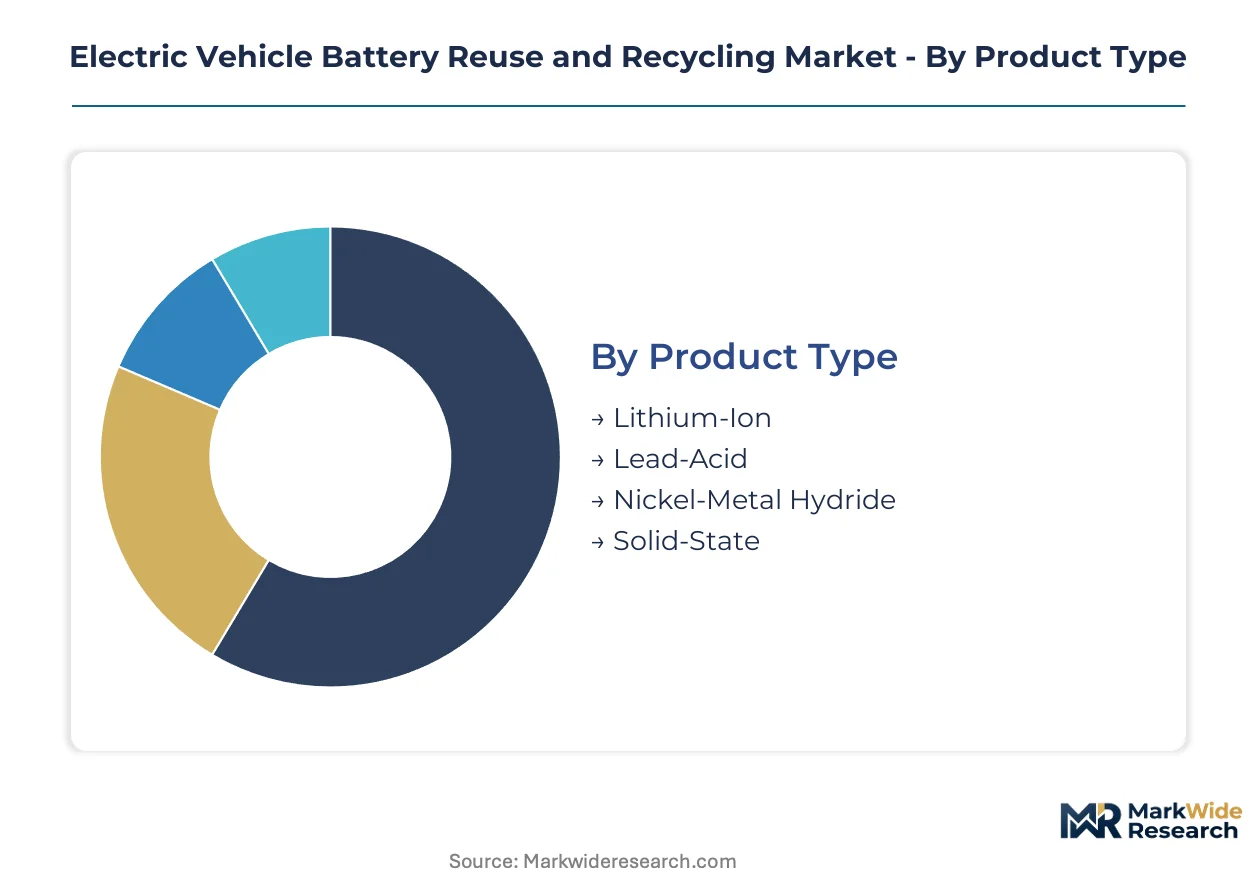
Segmentation in the Electric Vehicle Battery Reuse and Recycling Market reveals how distinct chemistry types, processing technologies, and procurement channels create divergent margin profiles and capital intensity requirements. Understanding these divisions enables stakeholders to align infrastructure investments with the specific throughput and purity demands of each segment.
Product Type:
Cycle times vary dramatically across chemistries, with some battery formats reaching end-of-first-life within five years while others persist for fifteen years in secondary applications.
- Lithium-Ion:Dominant chemistry in automotive applications, these packs retain 70-80% capacity upon retirement and supply the primary feedstock stream for hydrometallurgical refiners. Demand concentrates among battery manufacturers seeking certified recycled lithium, cobalt, and nickel to meet EU Battery Regulation quotas.
- Lead-Acid:Mature recycling infrastructure already captures over 99% of these batteries through established smelter networks, though volumes are declining as automotive electrification accelerates. The segment serves industrial backup power and conventional vehicle starter applications with minimal growth trajectory.
- Nickel-Metal Hydride:Hybrid vehicle legacy chemistry requiring specialized preprocessing due to rare earth content and different thermal profiles during dismantling.
- Solid-State:Emerging chemistry with unproven end-of-life characteristics; preprocessing protocols remain under development as commercial volumes remain negligible.
Lithium-Ion anchors the volume base while Solid-State gains share at the steepest rate as next-generation manufacturing scales.
Recycling Method:
Capital deployment patterns reflect fundamental trade-offs between recovery purity, energy intensity, and feedstock flexibility across processing approaches.
- Hydrometallurgical:Wet-chemistry processes achieve superior lithium and graphite recovery rates compared with thermal alternatives, attracting the majority of new facility investment. German industrial clustering around Hamburg and Stuttgart favors this method for its lower emissions profile and compatibility with EU Green Deal compliance requirements.
- Direct Recycling:Preserves cathode crystal structures rather than dissolving and reprecipitating active materials, collapsing reprocessing energy intensity. Battery manufacturers piloting these methods at commercial scale seek the cost advantages this approach promises over conventional hydrometallurgy.
- Pyrometallurgical:High-temperature smelting infrastructure dominates existing capacity but cannot economically recover lithium, creating stranded asset risk for operators with sunk capital in this approach.
- Biological:Bioleaching approaches using microorganisms to extract metals remain at pilot scale with unproven throughput economics for commercial deployment.
Hydrometallurgical processing commands the installed base while Direct Recycling attracts the most aggressive capital allocation.
End User:
Procurement sophistication varies sharply across buyer categories, with some demanding decade-long supply certainty while others operate on spot-market flexibility.
- Automakers:Face mandatory recycled content thresholds under EU Battery Regulation and China's MIIT producer responsibility frameworks, compelling long-term offtake agreements with embedded feedstock guarantees. These buyers require mass-balance certification and digital passport traceability.
- Battery Manufacturers:Cathode producers integrate backward into preprocessing to secure compliant feedstock, particularly in China where SAMR ties recycling permits to manufacturing licenses.
- Recycling Facilities:Intermediate processors seeking standardized feedstock streams to optimize batch economics and reduce chemistry heterogeneity costs.
- Renewable Energy Systems:Stationary storage developers absorbing retired automotive cells at scale, emerging as the fastest-expanding purchaser segment for second-life battery packs.
Automakers anchor contract value while Renewable Energy Systems expand most quickly as grid-scale deployment accelerates.
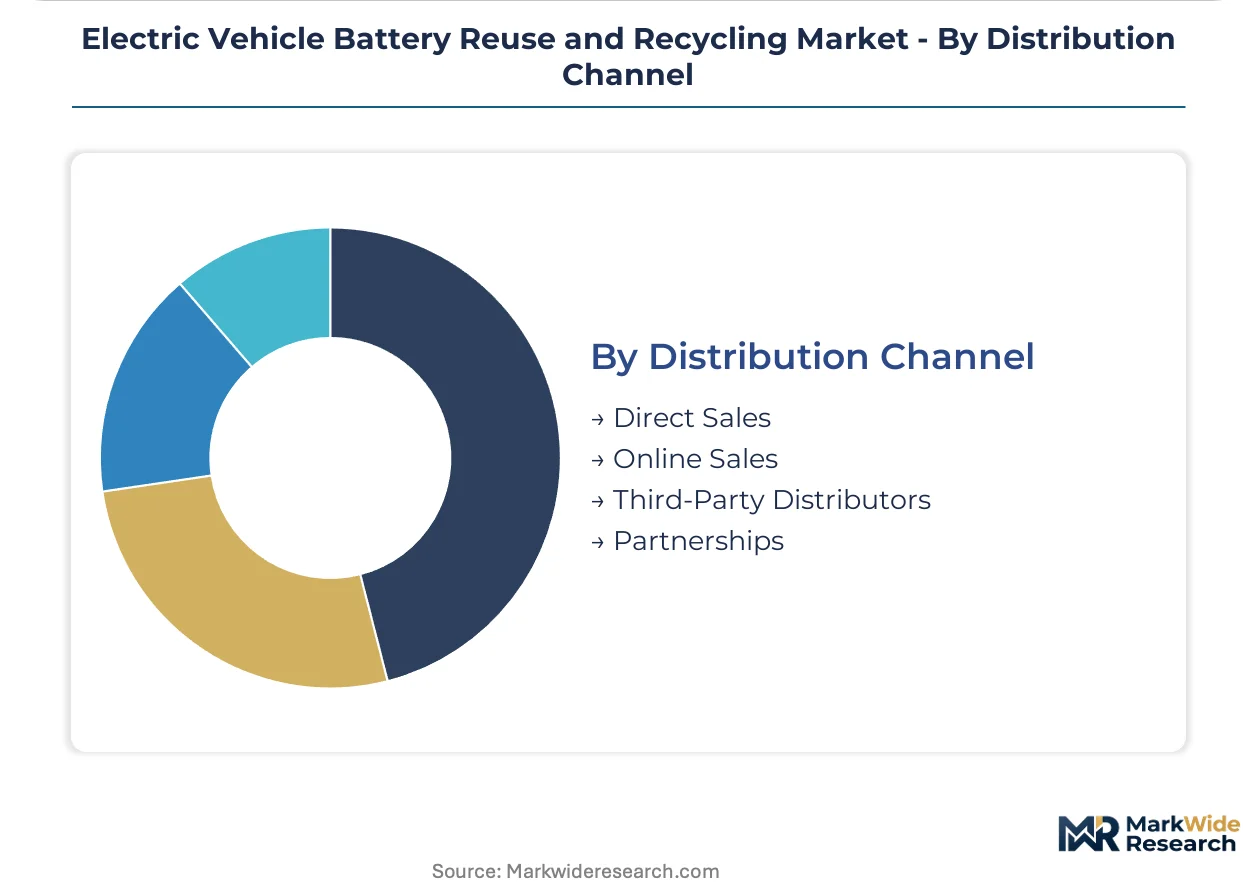
Distribution Channel:
Channel economics hinge on transport cost structures and the regulatory complexity of cross-border hazardous waste movement.
- Direct Sales:Automaker-to-recycler relationships are tilting toward long-term offtake agreements that compress decades of linear sourcing into compressed transition windows, favored by large-scale centralized processors with proven collection networks.
- Third-Party Distributors:Specialized logistics providers handle EPA hazardous waste manifest documentation requirements in the United States, enabling mid-scale processors to access feedstock without building captive transport infrastructure.
- Online Sales:Digital platforms for standardized battery testing and valuation remain nascent, constrained by the need for physical state-of-health verification before pricing.
- Partnerships:Co-located collection and processing infrastructure adjacent to major automotive manufacturing corridors reduces transport costs and feedstock uncertainty.
Direct Sales captures the premium contract tier while Third-Party Distributors enable geographic expansion for capital-constrained processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for certified recycled content under EU Battery Regulation quotas, while Chinese processors compete on volume throughput tied to MIIT producer responsibility mandates. This asymmetry shapes cross-border feedstock flows and investment allocation across preprocessing and refining infrastructure.
Germany
Automakers face binding recycled content thresholds under EU Battery Regulation deadlines, compelling long-term offtake agreements with embedded feedstock guarantees. The country's national industrial regulator enforces strict hazardous waste transport documentation that favors large-scale centralized processors. Industrial clustering around Hamburg and Stuttgart creates Europe's densest network of hydrometallurgical preprocessing and refining facilities.
China
Domestic automakers must demonstrate closed-loop material recovery or face production caps under MIIT and SAMR dual carbon goals. GB standards administered by the national market regulator tie recycling permits to new energy vehicle manufacturing licenses. Cathode producers in the Yangtze River Delta region integrate backward into preprocessing to secure compliant feedstock streams.
United States
Stationary energy storage developers absorb retired automotive cells at scale, emerging as the fastest-expanding purchaser segment for second-life battery packs. EPA hazardous waste rules classify certain end-of-life batteries as universal waste, streamlining interstate transport while imposing strict manifest documentation requirements. Co-located collection and processing infrastructure concentrates adjacent to major automotive manufacturing corridors in the Midwest and Southeast.
South Korea
Battery manufacturers seek certified recycled lithium, cobalt, and nickel to supply cathode production for export markets facing EU regulatory compliance. The national technology regulator enforces extended producer responsibility frameworks aligned with OECD guidelines. Preprocessing capacity clusters in the Seoul Capital Area and Busan-Ulsan industrial corridor to serve integrated battery-cell manufacturing ecosystems.
India
Domestic cell production incentives under the PLI scheme extension create captive recycling demand tied to manufacturing permits. The Bureau of Indian Standards and central electricity authority administer technical specifications for energy storage safety and performance. Industrial activity concentrates in Gujarat and Maharashtra, where battery assembly plants anchor emerging collection and dismantling networks.
Electric Vehicle Battery Reuse and Recycling Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, feeding refined materials into cathode production. The vendor base organizes around three strategic archetypes: spoke-and-hub network operators securing geographically distributed feedstock access, integrated refiners recovering high-purity transition metals, and co-located processors building collection infrastructure adjacent to automotive corridors. Dominant competitive moves include long-term offtake agreements with embedded feedstock guarantees and backward integration into preprocessing to secure compliant material streams.
Within the integrated refiner tier, Umicore anchors European capacity for high-purity cobalt, nickel, and lithium recovery. Li-Cycle Corp. and Redwood Materials exemplify North American platform strategies, with the former leveraging distributed spoke-and-hub designs and the latter concentrating co-located infrastructure near manufacturing corridors. These three occupy positions that straddle the boundary between pure-play recycling and integrated battery materials supply.
| Leading Market Players |
|---|
| Li-Cycle Corp. |
| Umicore |
| Redwood Materials |
| Ascend Elements |
| Guangdong Brunp Recycling Technology Co. Ltd. |
| Nissan Motor/4R Energy |
| Renault Group |
| Connected Energy |
| RePurpose Energy |
| Others |
Pricing and Supply Chain Analysis
Hamburg's hydrometallurgical preprocessing cluster commands pricing leverage over European cathode producers scrambling to meet EU Battery Regulation recycled content quotas. Capacity concentration in this northern German port city compresses feedstock competition and elevates contract premiums for certified mass-balance material.
Pricing Analysis
Configured-to-order pricing for battery passport-compliant material commands spreads of 15-25% above standard hydrometallurgical output. Contract-based long-term offtake agreements dominate procurement, with price differentiation resting on certification tier and volume scale. Cost compression in standard-grade output is intensifying because pyrometallurgical incumbents cannot recover lithium and must discount to maintain offtake. Stationary energy storage developers exhibit highest price sensitivity due to decade-long deployment economics, while automakers under regulatory mandate show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from German automakers now stretch to 90-120 days, forcing recyclers to seek supply-chain finance facilities from institutional lenders. Feedstock draws from Germany, China, and the United States, with raw material dependencies centering on lithium carbonate, cobalt hydroxide, and high-purity nickel sulfate. Single-source vulnerability concentrates in Chinese cathode precursor output subject to MIIT export licensing. Distribution runs through co-located collection hubs adjacent to Stuttgart and Wolfsburg manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital passport verification services and mass-balance certification subscriptions are expanding faster than physical preprocessing hardware, transforming battery recycling into a service-attach business model.
For Market Incumbents: Entrench through backward integration into dismantling robotics and exclusive collection partnerships with Renault Group and Nissan Motor/4R Energy. Hydrometallurgical operators face stranded asset risk from direct recycling technology convergence; defend by piloting cathode structure preservation methods in Hamburg and Stuttgart facilities. For New Entrants and Emerging Players: India's Gujarat and Maharashtra battery assembly corridors represent the most penetrable entry point, with PLI scheme manufacturing permits creating captive recycling demand. Second-life stationary storage in Southeast Asian grid-scale deployments offers secondary white-space. Go-to-market through third-party logistics partnerships bypassing EPA manifest infrastructure costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated refiners with proven hydrometallurgical lithium recovery and digital passport platform deployment. Five-to-ten year viability hinges on EU Battery Regulation quota enforcement trajectory and China's MIIT dual carbon goal implementation pace. Watch for inflection in direct recycling commercial scale announcements from cathode producers.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Passport Platform Deployment | Mass-balance certification enables premium pricing under EU Battery Regulation traceability mandates. |
| Backward Integration into Dismantling | Pack-to-cell robotics reduces chemistry heterogeneity costs and improves batch economics. |
| Long-term Offtake Agreement Expansion | Embedded feedstock guarantees secure decade-long supply certainty for stationary storage developers. |
| Direct Recycling Technology Piloting | Cathode crystal structure preservation collapses reprocessing energy intensity versus hydrometallurgy. |
| Co-located Collection Infrastructure | Adjacent positioning to Stuttgart and Wolfsburg corridors minimizes transport cost and feedstock uncertainty. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with stationary energy storage procurement directors, hydrometallurgical plant managers, automaker sustainability officers, and cathode producer feedstock strategists. Secondary validation drew from EU Battery Regulation implementation guidance, EPA hazardous waste manifest databases, MIIT producer responsibility filings, and customs trade data on lithium carbonate and cobalt hydroxide flows. Bottom-up facility capacity modeling and top-down regulatory quota analysis were triangulated to calibrate market sizing.
Calibration across the analysis window employed segment-level growth rate derivation from chemistry-type retirement curves and processing technology deployment schedules. Modeled dimensions span battery chemistry, recycling method, end-user category, and distribution channel, with regional regulatory cluster as an additional overlay. CAGRs were computed from installed base projections and capacity utilization assumptions. Forecast inputs incorporated EU recycled content threshold phase-in schedules and China's dual carbon goal enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in lithium and cobalt spot price volatility, battery electric vehicle adoption curves, or regulatory quota enforcement timing would shift the trajectory. Forecasts reflect documented assumptions on technology substitution rates and feedstock availability clustering. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market