
 Lithium Battery Recycling Market | 2026-2036
Lithium Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Recycling Market Insights
Project finance tied to offtake agreements is reshaping competitive entry in lithium battery recycling, lowering capital barriers for mid-scale operators. Umicore leverages its integrated refining complex in Belgium to recover cobalt and nickel with closed-loop chemistry. Glencore anchors its position through backward integration into mining assets that feed smelter feedstock blending. Redwood Materials specializes in hydrometallurgical purification at gigafactory-adjacent hubs, cutting logistics costs for cell manufacturers.
Lithium battery recycling encompasses the collection, dismantling, and chemical recovery of spent lithium-ion cells to extract cobalt, lithium, nickel, and manganese at purity grades exceeding 99.5% for re-entry into cathode production. The process targets reduction of virgin mining dependence while meeting battery-grade material specifications enforced by automotive OEMs. Hydrometallurgical routes now dominate new capacity builds due to lower energy intensity and higher lithium recovery rates compared with pyrometallurgical alternatives. Direct recycling approaches are attracting pilot-scale investment as the fastest-growing process category, preserving cathode crystal structures and bypassing full elemental decomposition. Electric vehicle applications command the deepest margin pools among end-use segments, driven by volume concentration and long-term offtake contracts with cell producers.
The EPA governs hazardous waste classification for spent batteries under RCRA, while the EU Battery Regulation enforces recycled content minimums and carbon footprint disclosure across the European value chain. China's MIIT and SAMR coordinate national recycling quotas and blacklist enforcement for licensed dismantlers, tightening market access for informal operators. Stakeholders must monitor how divergent Extended Producer Responsibility schemes across jurisdictions alter collection network economics and compliance cost allocation.
Market Dynamics
EU Battery Regulation mandates are forcing producers to reconfigure supply chains around recycled content thresholds, while electric vehicle OEMs lock in long-term offtake agreements that reshape capital access for recyclers.
Growth Catalysts
- EU recycled content mandates:The EU Battery Regulation enforces minimum recycled lithium, cobalt, and nickel thresholds in new batteries, compelling manufacturers to secure certified secondary material streams and validate supply chain provenance.
- Electric vehicle OEM offtake contracts:Cell producers and automotive manufacturers are signing decade-long supply agreements with recyclers, de-risking project finance and accelerating capacity buildouts adjacent to gigafactory clusters.
- Hydrometallurgical process maturation:Advances in solvent extraction and electrowinning now recover lithium at battery-grade purity exceeding 99.5%, displacing energy-intensive pyrometallurgical routes in new facility designs.
Market Restraints
- Feedstock collection fragmentation:Spent batteries remain dispersed across informal collection networks in India, Nigeria, and Southeast Asia, limiting traceability and concentrating viable feedstock supply among licensed dismantlers in China and the EU.
- Lithium price volatility:Spot market fluctuations for battery-grade lithium carbonate compress recycler margins when virgin material undercuts recovered product pricing during oversupply periods.
- Technical limitation in direct recycling:Preservation of cathode crystal structures requires precise state-of-health diagnostics that remain uneconomical at commercial scale, constraining deployment beyond pilot facilities.
Strategic Opportunities
- North American capacity gap:The United States currently hosts limited operational hydrometallurgical capacity relative to projected EV retirement volumes, creating first-mover advantages for domestic hub development near Detroit and Nevada manufacturing corridors.
- Grid storage second-life applications:Stationary energy storage operators are establishing certification pathways for retired EV batteries, extending value extraction before chemical recycling and creating dual-revenue collection partnerships.
- Carbon border adjustment alignment:The EU Carbon Border Adjustment Mechanism rewards low-carbon recycled content, positioning battery recyclers to capture premium pricing against virgin mining imports from carbon-intensive jurisdictions.
Industry Challenges
- Electrochemical engineer scarcity:Specialized expertise in battery chemistry, separation science, and process safety remains concentrated among a limited pool of professionals trained at German, Belgian, and Chinese technical institutes.
- RCRA hazardous waste permitting:US facilities face multi-year EPA approval timelines for handling spent lithium-ion cells under RCRA subtitle C, delaying revenue generation and inflating pre-operational carrying costs.
- Black mass trading opacity:Intermediate products from mechanical shredding lack standardized assays and pricing benchmarks, complicating offtake negotiations and working capital management for independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Recycling Market |
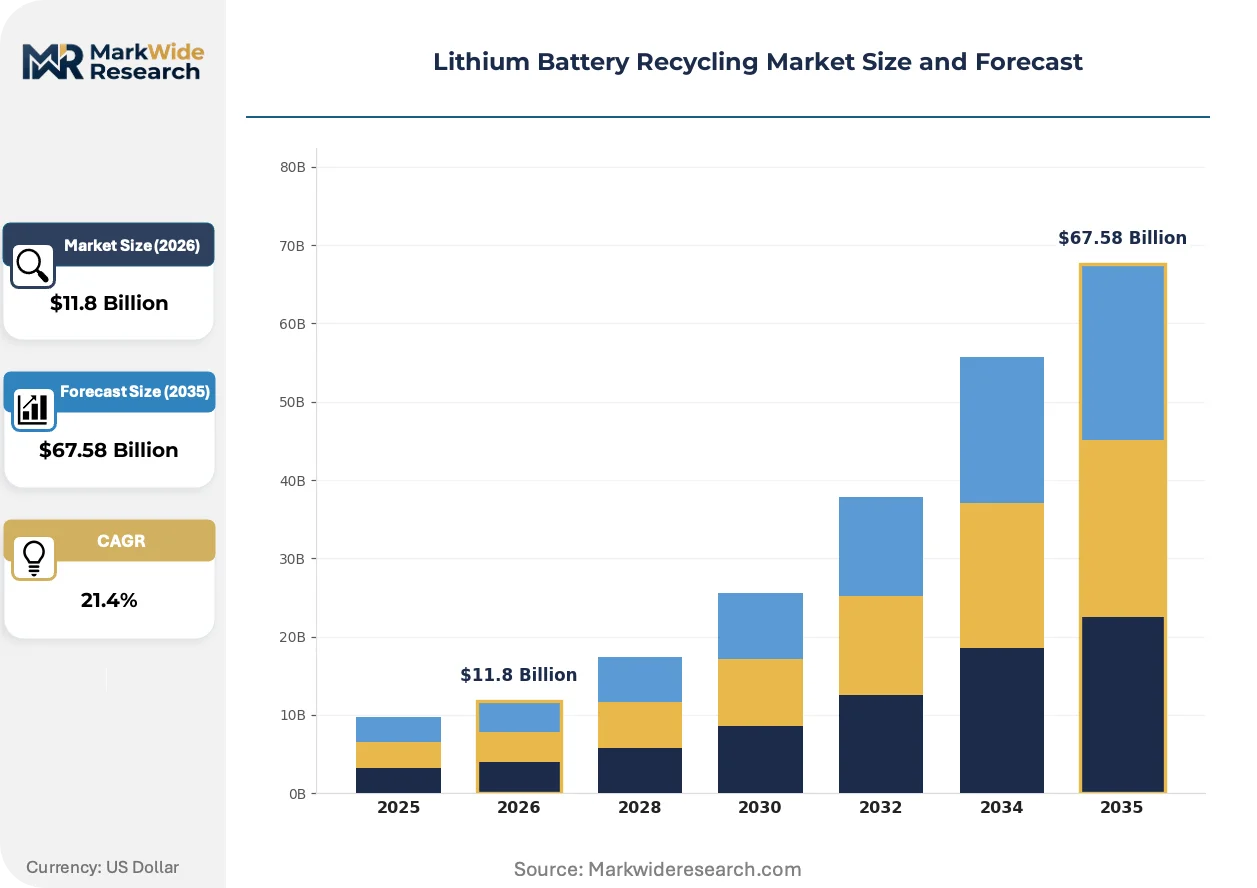
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $67.58 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Pyrometallurgical, Hydrometallurgical, Biotechnological, Direct Recycling Application: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Equipment Material Type: Lithium Cobalt Oxide, Lithium Iron Phosphate, Lithium Nickel Manganese Cobalt, Others End User: Aerospace, Automotive, Renewable Energy, Electronics Manufacturing |
| Companies Covered | Umicore, Glencore, GEM Co., Ltd., Li-Cycle Holdings Corp., Redwood Materials, Brunp Recycling, Cirba Solutions, Contemporary Amperex Technology Co., Limited, Fortum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Recycling Market Trends and Innovations
Process convergence and regulatory precision are redefining competitive advantage in lithium battery recycling, with technology choices increasingly locked in by policy architecture rather than pure economics.
Direct cathode regeneration is hybridizing hydrometallurgical and solid-state processing approaches to preserve active material structures. Automotive OEMs are piloting this route for nickel-manganese-cobalt chemistries to reduce re-manufacturing energy intensity by half. The technology is compressing the traditional value chain by eliminating intermediate refining steps and enabling closed-loop return to cell production.
REACH substance restrictions are tightening purity requirements for recovered cobalt and nickel entering EU battery supply chains. The regulation forces recyclers to implement additional purification stages and third-party certification, raising operational complexity. Hydrometallurgical operators in Belgium and Germany are responding by integrating in-house analytical laboratories to demonstrate compliance batch-by-batch.
Long-term tolling arrangements are displacing spot market transactions as the dominant procurement model for black mass and recovered salts. Cell manufacturers in South Korea and Japan are locking in fixed-volume, fixed-price contracts spanning five to seven years to hedge against feedstock scarcity. This shift is most visible in supply agreements between European refiners and Asian cathode producers, where price volatility protection now outweighs short-term cost optimization.
Lithium Battery Recycling Market Segmentation
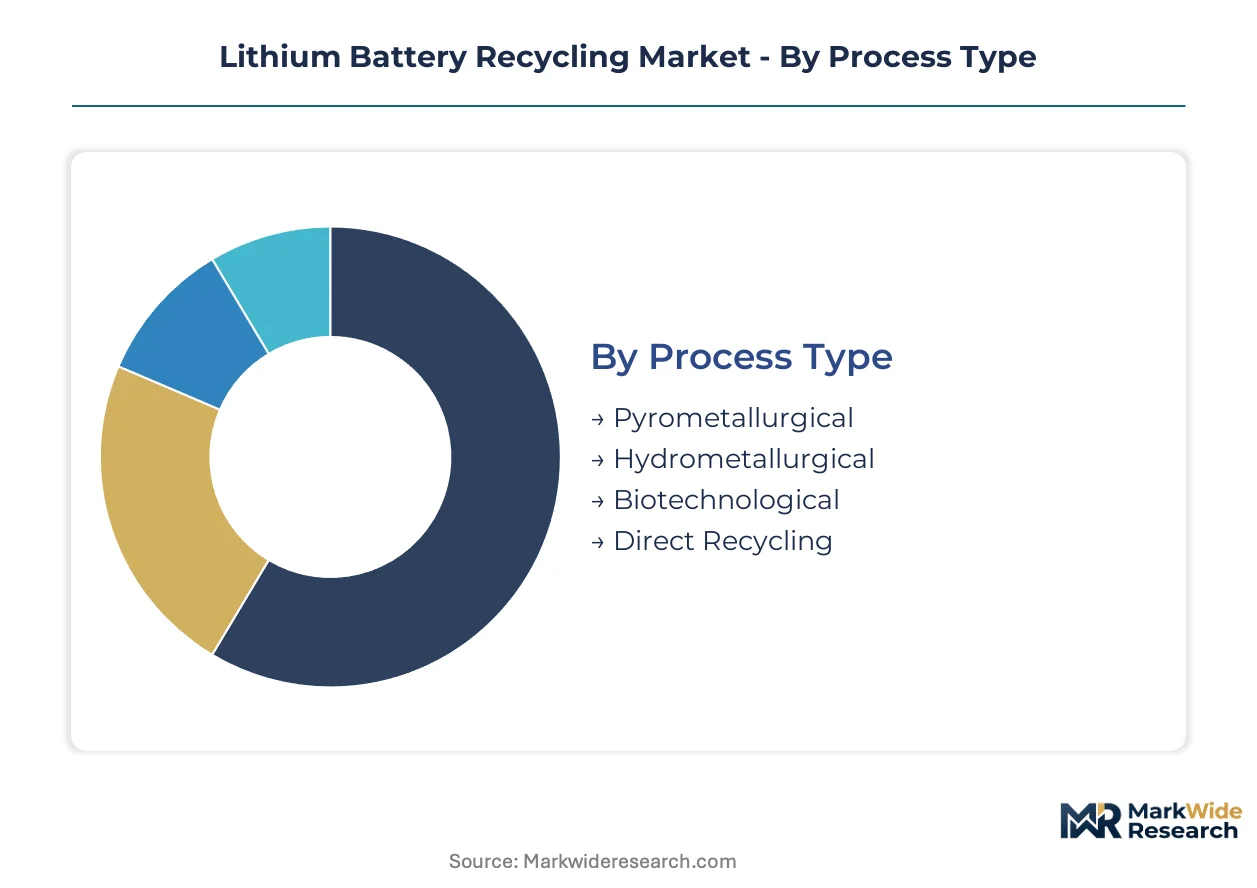
Segmentation in lithium battery recycling determines capital allocation, technology selection, and offtake strategy. Cycle times vary dramatically across process types and applications, dictating which segments attract project finance versus pilot investment.
Process Type:
Hydrometallurgical routes achieve commercial scale fastest, while direct recycling remains trapped in extended validation cycles.
- Pyrometallurgical:High-temperature smelting recovers cobalt and nickel through alloy formation, sacrificing lithium to slag. Glencore's integrated smelters in Belgium and Canada rely on this route for mining feedstock blending, though energy costs now disadvantage new builds against hydrometallurgical alternatives.
- Hydrometallurgical:Solvent extraction and electrowinning achieve battery-grade lithium recovery exceeding 99.5% purity. Umicore's Belgian complex and Redwood Materials' Nevada hubs deploy this chemistry adjacent to gigafactory corridors, cutting logistics costs and securing decade-long automotive offtake contracts.
- Biotechnological:Bioleaching using acidophilic bacteria offers selective metal recovery at ambient temperatures. Pilot facilities in Germany and Finland test scalability constraints against conventional chemistry.
- Direct Recycling:Cathode crystal structure preservation bypasses full elemental decomposition. Pilot investments from South Korean cell manufacturers target 50% energy reduction, though state-of-health diagnostics remain uneconomical at commercial throughput.
Hydrometallurgical processing anchors the volume base while direct recycling gains share at the steepest rate.
Application:
Volume concentration and margin depth diverge sharply across end-use segments, with automotive contracts commanding premium pricing against fragmented consumer streams.
- Consumer Electronics:Smartphones and laptops generate dispersed, low-volume feedstock with mixed cathode chemistries. Collection networks in India and Southeast Asia remain informal, limiting traceability for EU Battery Regulation compliance and compressing recycler margins.
- Electric Vehicles:Retired EV packs deliver concentrated, homogeneous feedstock with predictable cobalt-nickel-manganese ratios. Long-term offtake agreements between cell producers and recyclers de-risk project finance, with OEMs in Germany, the United States, and South Korea locking in dedicated supply.
- Energy Storage Systems:Grid-scale batteries extend value through second-life certification before chemical recycling. Stationary operators in California and Texas establish dual-revenue partnerships, delaying material return to processors by 5-7 years.
- Industrial Equipment:Forklifts, mining vehicles, and medical devices contribute specialized form factors requiring manual dismantling. Lower volumes restrict dedicated facility investment, routing feedstock through generalist processors in China.
Electric vehicle applications concentrate revenue while energy storage systems expand most quickly through second-life pathway development.
Material Type:
Cathode chemistry determines recovery economics, with high-cobalt formulations commanding premium processing margins against iron-phosphate alternatives.
- Lithium Cobalt Oxide:High cobalt content in consumer electronics batteries enables profitable recovery even at smaller scale. Processing concentrates in China and Belgium where cobalt refining infrastructure exists.
- Lithium Iron Phosphate:Absence of cobalt and nickel compresses recovery value, requiring volume scale for unit economics. Chinese recyclers dominate this segment through integrated collection networks serving domestic EV manufacturers.
- Lithium Nickel Manganese Cobalt:Balanced metal content supports diversified revenue streams from nickel, cobalt, and manganese. Automotive OEMs in Germany and South Korea prioritize this chemistry for closed-loop return to cell production.
- Others:Lithium manganese oxide and emerging silicon-anode formulations represent niche volumes requiring specialized separation chemistry.
Lithium nickel manganese cobalt dominates revenue contribution while lithium iron phosphate climbs fastest on EV adoption in China.
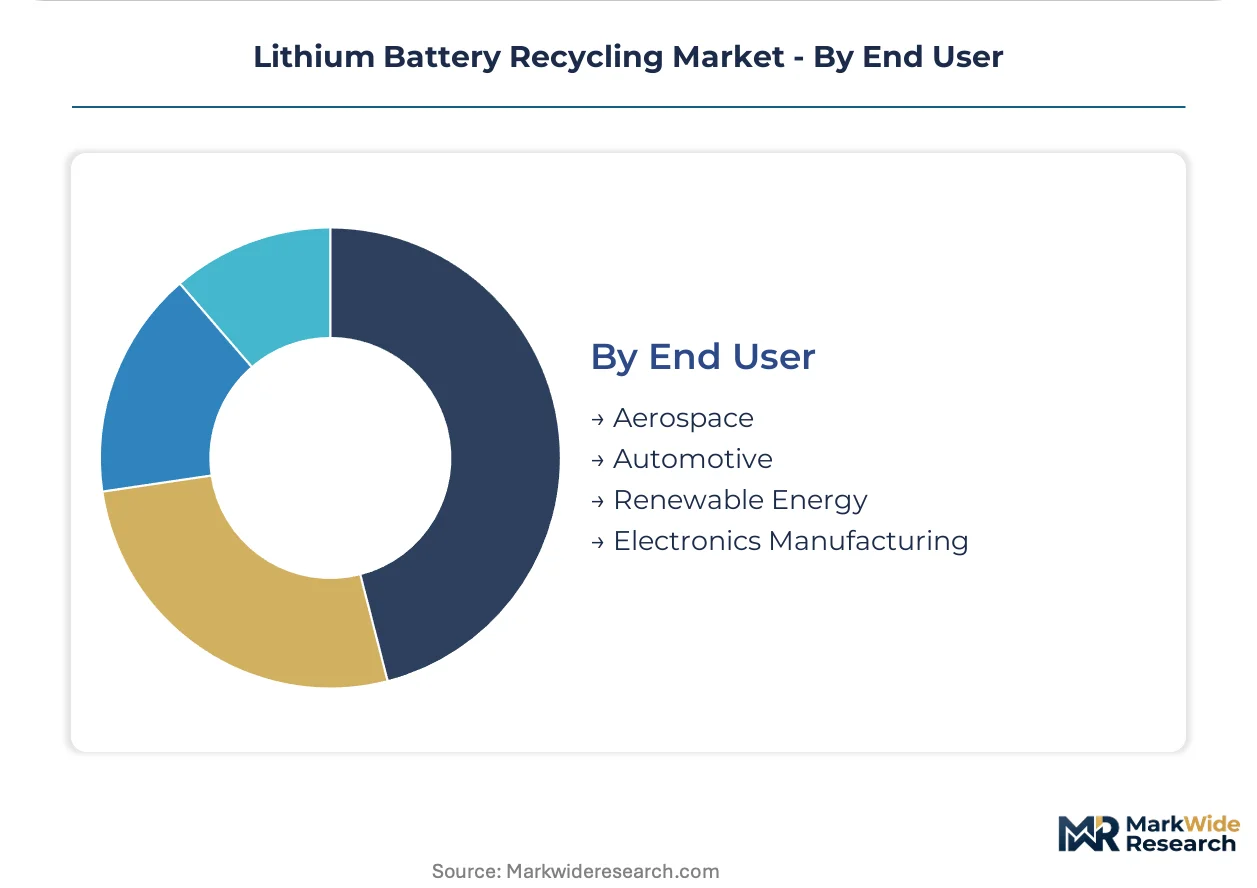
End User:
Customer sophistication and contract structure vary dramatically, with aerospace and automotive demanding certified provenance against electronics manufacturing's price sensitivity.
- Aerospace:Strict material traceability requirements and low volumes limit dedicated recycling infrastructure. Battery waste routes through specialized hazardous waste handlers in France and the United States.
- Automotive:Cell manufacturers and OEMs enforce battery-grade specifications and carbon footprint disclosure. EU Battery Regulation mandates drive direct investment in hydrometallurgical capacity across Germany, Poland, and Hungary.
- Renewable Energy:Wind and solar developers generate intermittent battery waste from backup systems. Project finance structures lag EV-linked recycling, though California and Texas grid operators pilot collection partnerships.
- Electronics Manufacturing:Contract manufacturers in Vietnam and Mexico generate predictable scrap streams from cell production defects. Toll processing arrangements dominate, with fixed-price contracts displacing spot market transactions.
Automotive end users anchor contract value while renewable energy builds share fastest through grid storage retirement waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Regulation mandates are accelerating capacity deployment across multiple jurisdictions, while IRA tax credits in the United States reshape capital allocation for gigafactory-adjacent recycling hubs.
United States
Retired EV battery volumes from Tesla, Ford, and GM are concentrating feedstock supply in the Midwest and Nevada manufacturing corridors. EPA RCRA subtitle C permitting timelines extend 18-36 months, delaying facility commissioning. Detroit and Reno host the densest clusters of hydrometallurgical projects under construction, with Redwood Materials anchoring the Nevada hub.
China
Domestic EV retirement waves from BYD and CATL generate homogeneous NMC and LFP feedstock at scale. MIIT and SAMR coordinate national recycling quotas and blacklist enforcement, squeezing informal dismantlers from licensed supply chains. Jiangsu and Guangdong provinces concentrate operational capacity, with Brunp Recycling and GEM Co., Ltd. integrated across collection-to-refining value chains.
Germany
Automotive OEMs including Volkswagen and BMW enforce battery-grade material specifications and carbon footprint disclosure for closed-loop return. The EU Battery Regulation's recycled content thresholds drive direct investment in hydrometallurgical capacity across North Rhine-Westphalia and Saxony. Umicore's Belgian complex supplies German cathode producers through tolling arrangements.
South Korea
Cell manufacturers LG Energy Solution and Samsung SDI lock in decade-long offtake agreements with European and North American recyclers to hedge feedstock scarcity. MFDS coordinates hazardous waste handling standards for spent battery imports. The Gyeonggi-do cluster around Seoul hosts pilot direct recycling facilities targeting 50% energy reduction in cathode regeneration.
Belgium
Integrated refining infrastructure and port access position the country as Europe's primary cobalt and nickel recovery hub. REACH substance restrictions tighten purity requirements for recovered materials entering EU battery supply chains. The Antwerp industrial zone concentrates closed-loop chemistry operations serving German and French automotive OEMs.
Lithium Battery Recycling Market Competitive Landscape
On the supply side, the industry is consolidating around integrated refiners with captive feedstock access and project-financed mid-scale operators with secured offtake agreements. Three archetypes dominate: mining-backed smelter operators blending primary and secondary feedstock; hydrometallurgical specialists co-located with gigafactory clusters; and state-linked Chinese dismantlers controlling domestic collection networks. Competitive moves center on backward integration into mining assets and long-term tolling arrangements displacing spot market transactions.
Among Belgian and German integrated refiners, Umicore occupies a position exemplifying closed-loop chemistry at scale, while Glencore represents the mining-backed archetype through smelter feedstock blending. Redwood Materials anchors the North American hydrometuregical specialist tier. Chinese state-linked operators including GEM Co., Ltd. and Brunp Recycling exemplify vertically integrated collection-to-refining models serving domestic EV manufacturers.
| Leading Market Players |
|---|
| Umicore |
| Glencore |
| GEM Co., Ltd. |
| Li-Cycle Holdings Corp. |
| Redwood Materials |
| Brunp Recycling |
| Cirba Solutions |
| Contemporary Amperex Technology Co., Limited |
| Fortum |
| Others |
Pricing and Supply Chain Analysis
Chinese black mass concentration in Jiangsu and Guangdong provinces feeds margin capture downstream at Belgian hydrometallurgical refiners and Nevada gigafactory-adjacent hubs. Pricing power clusters where certified battery-grade output commands automotive offtake premiums against fragmented informal collection networks.
Pricing Analysis
Certification level (EU Battery Regulation compliance, REACH substance restrictions, RCRA subtitle C permitting) creates the primary spread between battery-grade recovered materials and industrial-grade alternatives. Long-term tolling arrangements with fixed-volume, fixed-price structures dominate procurement between Asian cell manufacturers and European refiners, displacing spot market transactions. Cost compression in black mass intermediates is intensifying because standardized assays remain absent, forcing independent operators to absorb working capital uncertainty. Electronics manufacturing contract recyclers in Vietnam and Mexico exhibit the highest price sensitivity, while German and South Korean automotive OEMs prioritize provenance validation over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from South Korean cell manufacturers now anchor working capital structures for European hydrometallurgical operators. Feedstock concentration in China, Belgium, and the United States determines operational viability, with licensed dismantlers in Jiangsu province controlling upstream collection density. The supply chain draws from cobalt mining assets in the DRC, lithium brine operations in Chile, and nickel laterite deposits in Indonesia, creating multi-jurisdictional commodity exposure. Single-source vulnerability concentrates in Chinese state-linked recyclers with integrated collection-to-refining control. Distribution runs through tolling arrangements linking Belgian refiners to German cathode producers and Nevada hubs to Detroit manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Battery Regulation mandates fragment competitive space by forcing supply chain reconfiguration around recycled content thresholds, creating specialist niches for certified operators and geographic arbitrageurs.
For Market Incumbents: Pre-empt feedstock scarcity by locking decade-long offtake agreements with retiring EV fleet operators before second-life certification pathways extend value extraction timelines. Backward integration into mining assets anchors smelter feedstock blending against hydrometallurgical competitors, while in-house analytical laboratories demonstrate REACH compliance batch-by-batch against tightening purity requirements. For New Entrants and Emerging Players: Pursue the North American hydrometallurgical capacity gap near Detroit and Nevada manufacturing corridors where EPA permitting delays have constrained incumbent expansion. Grid storage second-life partnerships in California and Texas offer the most penetrable entry vector, with toll processing arrangements for retired EV batteries providing revenue before chemical recycling scale. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale hydrometallurgical operators holding secured automotive offtake but facing feedstock collection fragmentation. The five-to-ten year viability window favors targets with RCRA subtitle C permits already in hand and co-location contracts with gigafactory clusters. Watch lithium price volatility direction as the inflection indicator for recycler margin compression versus expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | LG Energy Solution's decade-long offtake contracts de-risk project finance for Nevada hydrometallurgical hubs. |
| Backward Integration | Glencore's mining asset control secures smelter feedstock blending against lithium price volatility cycles. |
| Capacity Expansion | Redwood Materials' gigafactory-adjacent hub buildout cuts logistics costs for Tesla and Panasonic cell production. |
| Green Certification Program | EU Carbon Border Adjustment Mechanism rewards low-carbon recycled content against virgin mining imports. |
| Joint Venture | Brunp Recycling's OEM partnerships integrate collection networks serving BYD domestic EV retirement waves. |
Research Methodology
A spread of perspectives from hydrometallurgical plant managers, automotive OEM procurement leads, EPA regulatory affairs specialists, and black mass trading intermediaries converged on the working assumptions. Primary interviews combined with secondary validation from EPA RCRA filings, EU Battery Regulation implementation guidance, MIIT recycling quota disclosures, and SEC 10-K supply chain disclosures. Bottom-up feedstock volume estimates and top-down cathode material demand projections were triangulated to anchor market sizing.
Demand-supply balance modeling across the analysis window segmented by process type, cathode chemistry, and end-use application to isolate margin pool concentration. CAGRs derived from installed EV fleet retirement curves, second-life pathway adoption rates, and hydrometallurgical capacity buildout timelines. Forecast inputs incorporated EU Battery Regulation recycled content threshold phase-ins and IRA tax credit eligibility for domestic content.
Sensitivities concentrate around lithium carbonate spot price volatility, EPA permitting timeline extensions, and direct recycling technology maturation beyond pilot scale. Forecasts reflect assumptions on feedstock collection network formalization rates and automotive OEM vertical integration intentions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
Automotive Oil Recycling Market