
 Prepaid Battery Recycling Market | 2026-2036
Prepaid Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Prepaid Battery Recycling Market Analytics
North American hydrometallurgical capacity is expanding as processors retrofit facilities for lithium-ion chemistries. Umicore leverages its integrated refining complex in Belgium to sustain cathode precursor output from recycled feedstock. Veolia dominates French collection infrastructure through municipal partnerships and reverse logistics contracts. Gravita India anchors South Asian lead-acid recovery with furnace technology adapted to informal sector feedstock streams.
Prepaid battery recycling denotes a service model where collection, transport, and material recovery costs are paid upfront by producers or consumers rather than settled at end-of-life, typically involving hydrometallurgical or pyrometallurgical processing to recover cobalt, lithium, and nickel at purity grades exceeding 99.5% for battery-grade reuse. The model insulates OEMs from volatile spot prices for virgin materials while ensuring compliant disposal pathways. Processing services for lithium-ion batteries command premium margins due to complex disassembly and thermal treatment requirements, while lead-acid recycling remains mature with thinner margin pools concentrated in smelter throughput efficiency. Collection services are scaling fastest among service types as retailers and automotive dealerships become mandated handoff points under producer responsibility frameworks.
The EU Battery Regulation and REACH compliance standards are tightening recovery rate thresholds and restricting hazardous substance leakage, forcing recyclers to certify mass balance documentation for each chemistry stream. EPA hazardous waste rules under RCRA govern US interstate transport and storage limits for end-of-life batteries, while India's BIS standards and PLI scheme incentives are accelerating formal sector capacity buildout. Stakeholders must monitor how carbon border adjustments and recycled content mandates reshape sourcing economics between virgin mining and closed-loop recovery pathways.
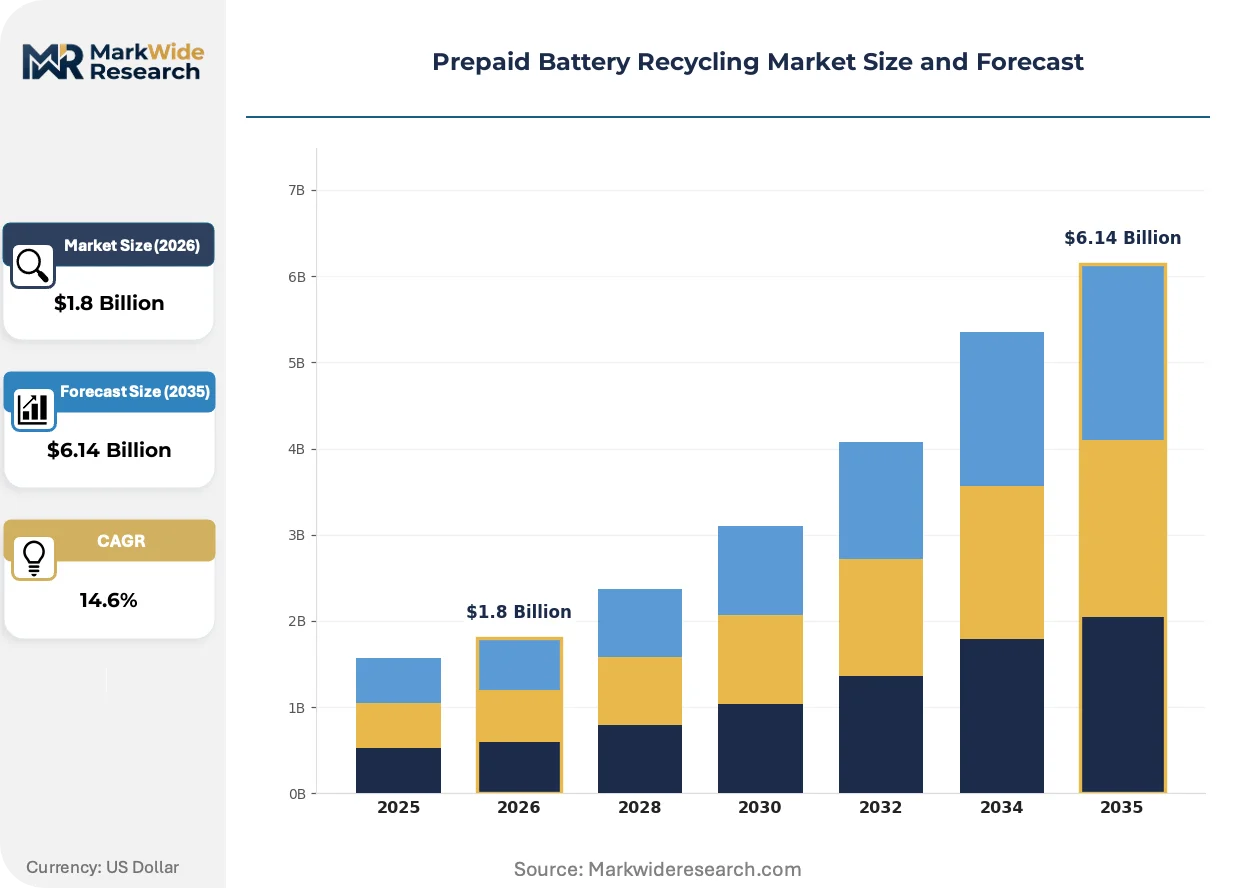
Market Dynamics
Extended producer responsibility mandates are forcing automotive OEMs to internalize end-of-life costs, converting battery recycling from a peripheral compliance cost into a core supply chain function with direct margin impact.
Growth Catalysts
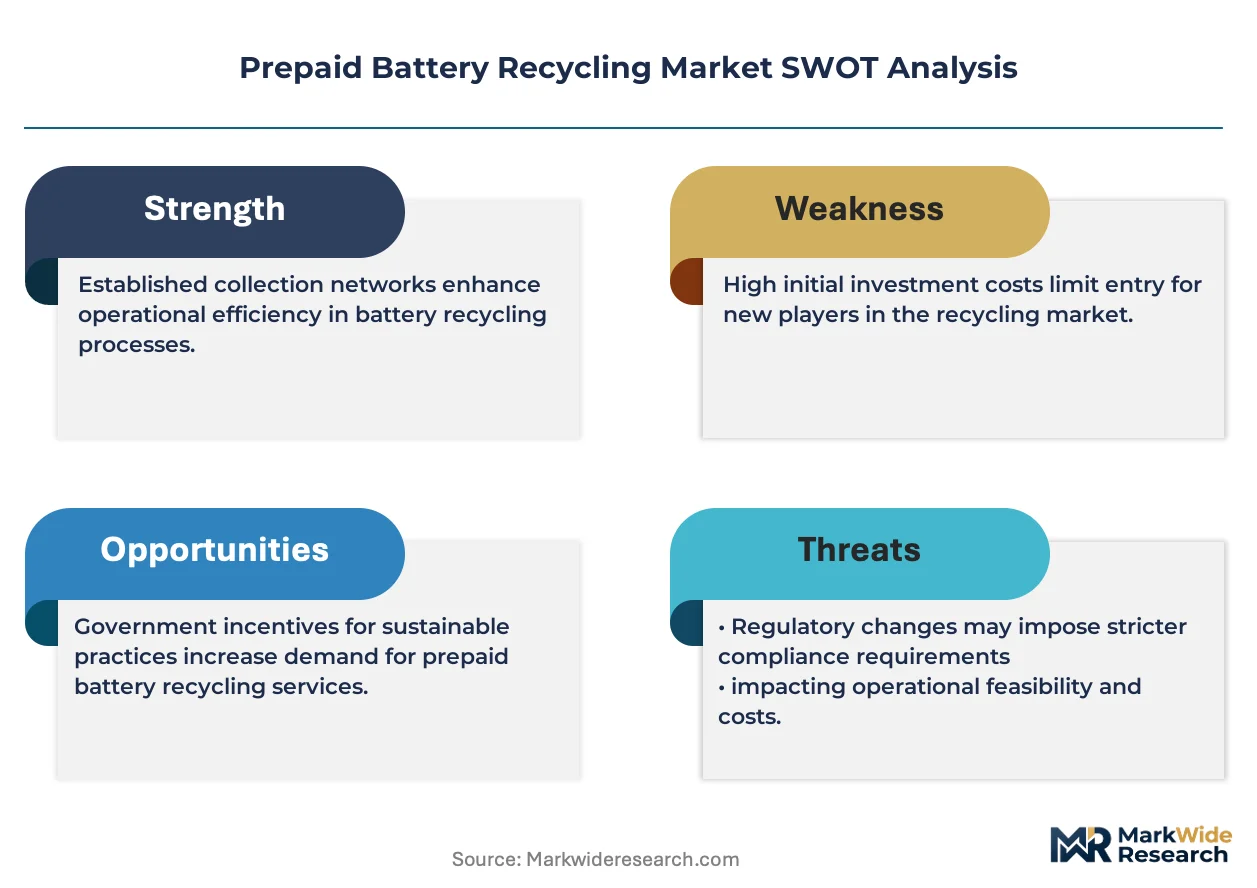
- EU Battery Regulation recovery thresholds:Binding material recovery rates for lithium, cobalt, and nickel are compelling manufacturers to secure prepaid recycling contracts before 2030 deadlines.
- Automotive electrification:Massive battery pack volumes from retiring EV fleets are creating predictable feedstock streams that justify dedicated processing infrastructure investments.
- Hydrometallurgical purification:Advanced solvent extraction methods now yield battery-grade metals exceeding 99.5% purity, closing the quality gap with virgin mined materials.
Market Restraints
- Cobalt price volatility:Democratic Republic of Congo supply concentration exposes recyclers to input cost swings that compress margins on fixed-price prepaid contracts.
- Collection infrastructure gaps:Sparse reverse logistics networks in Eastern European markets inflate transport costs and limit feedstock access for new entrants.
- Pyrometallurgical energy intensity:High-temperature smelting processes face escalating carbon costs under EU emissions trading schemes, disadvantaging legacy furnace operators.
Strategic Opportunities
- India formalization:BIS standards and PLI scheme incentives are consolidating informal lead-acid collectors into licensed channels ripe for prepaid model adoption.
- Second-life battery arbitrage:Stationary energy storage applications are creating intermediate value capture before final recycling, extending producer responsibility windows.
- Retailer collection mandates:Electronics retailers are becoming mandated handoff points under French and German producer responsibility frameworks, opening new channel partnerships.
Industry Challenges
- Battery passport traceability:EU mass balance documentation requirements demand expensive IT system overhauls for recyclers handling mixed chemistry streams.
- Skilled technician scarcity:Safe disassembly of high-voltage lithium-ion packs requires certified electricians that outpace vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepaid Battery Recycling Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection Service, Processing Service, Logistics Service, Consulting Service Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Alkaline End User: Consumer Electronics, Automotive Manufacturers, Industrial Companies, Renewable Energy Providers Distribution Channel: Direct Sales, Online Platforms, Retail Outlets, Partnerships |
| Companies Covered | Veolia, Umicore, Call2Recycle, Retriev Technologies, Gravita India, Exide Technologies, East Penn Manufacturing, EnerSys, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepaid Battery Recycling Market Evolving Landscape
Prepaid battery recycling is transitioning from commodity recovery toward integrated circular supply chain services, with technology and policy converging to standardize material provenance and quality assurance.
Direct recycling via cathode rejuvenation is modularizing processing architectures, allowing smaller facilities to bypass intermediate refining stages. Tier 2 automotive suppliers are piloting containerized units co-located with manufacturing plants. This distributed model is compressing transport costs and enabling just-in-time recycled material feedstock for cathode production.
REACH substance restrictions and EU Battery Regulation carbon footprint declarations are forcing recyclers to document energy sources and process emissions. Industrial consequence includes mandatory third-party audit chains for every kilogram of recovered material. German processors are responding fastest, integrating renewable power purchase agreements to secure competitive positioning under forthcoming carbon border adjustments.
Automotive OEMs are unbundling recycling service procurement from battery purchase agreements, creating standalone contract vehicles with specialized recyclers. Tier 1 suppliers and captive finance arms are displacing integrated OEM recycling departments as primary contract holders. This shift is most visible in Germany and France, where producer responsibility transfer mechanisms are formalizing earlier than in Southern European markets.
Prepaid Battery Recycling Market Segmentation
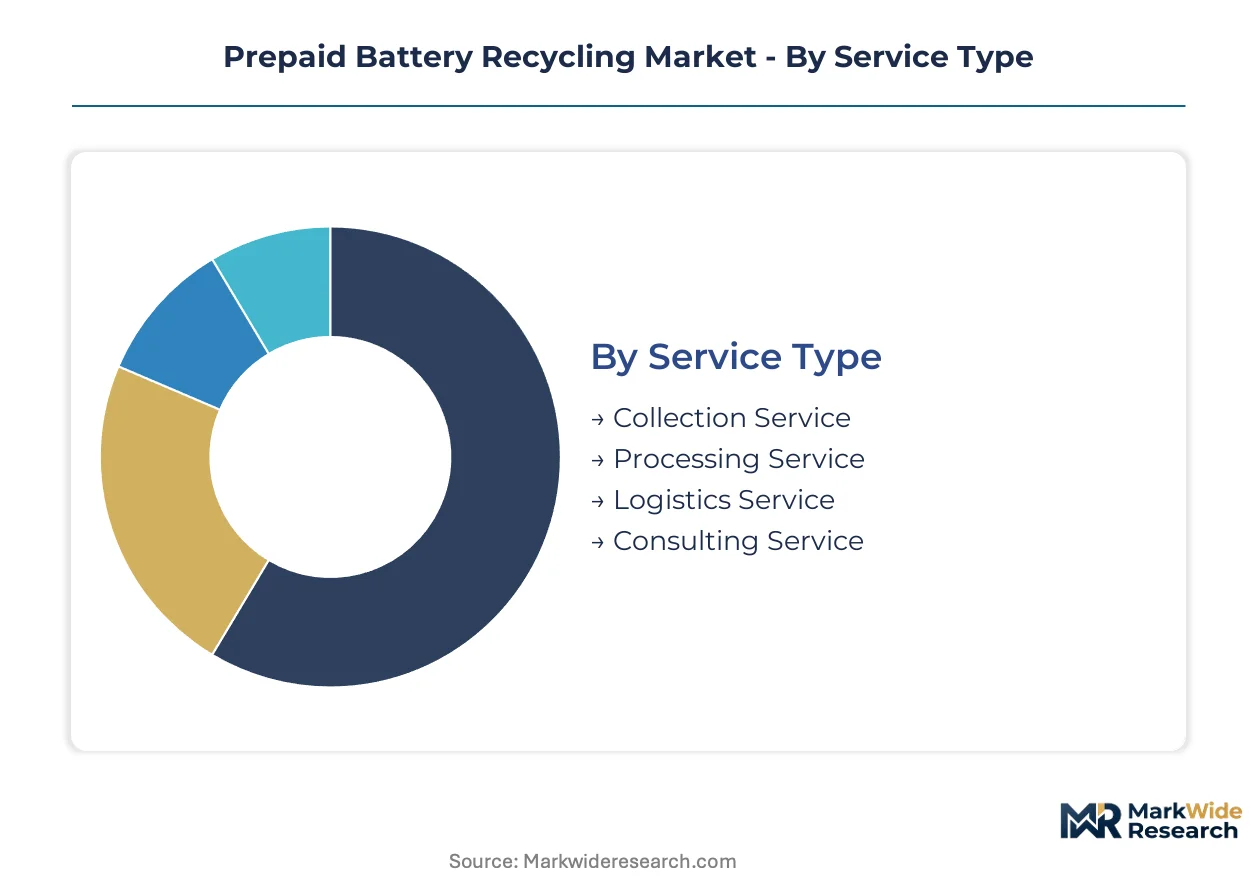
Prepaid battery recycling service providers configure their offerings around distinct operational layers, from front-end collection networks to back-end metallurgical processing. Segment boundaries determine contract structures, margin profiles, and capital intensity requirements for market participants.
Service Type:
Standalone collection and logistics services operate independently of processing infrastructure, while integrated processing services embed capital-heavy metallurgical operations.
- Collection Service:Reverse logistics networks capture end-of-life batteries from retailers, dealerships, and municipal drop-off points. German automotive OEMs are mandating retailer handoff partnerships under extended producer responsibility frameworks, compressing collection windows and demanding real-time tracking systems.
- Processing Service:Hydrometallurgical and pyrometallurgical facilities recover cobalt, lithium, and nickel at battery-grade purity thresholds. EU Battery Regulation recovery mandates are forcing processors to certify mass balance documentation for each chemistry stream, elevating compliance costs for mixed-feedstock operators.
- Logistics Service:Specialized hazmat transport and temporary storage solutions bridge collection nodes with processing facilities. EPA RCRA interstate transport rules in the US govern lithium-ion battery movement, requiring licensed carriers and manifest documentation.
- Consulting Service:Compliance advisory and circular supply chain design support producer responsibility implementation. REACH substance restriction guidance and carbon footprint declaration protocols dominate service demand in European markets.
Collection Service leads volumes today; Consulting Service is gaining share fastest.
Battery Type:
Chemistry-specific processing requirements create divergent margin structures, with lithium-ion commanding premium recovery economics against mature lead-acid operations.
- Lithium-ion:Complex disassembly and thermal treatment recover cobalt, lithium, nickel, and graphite for cathode precursor reuse. Automotive electrification in Germany and France is generating predictable EV pack feedstock streams that justify dedicated hydrometallurgical investments.
- Lead-acid:Mature smelter infrastructure achieves near-total lead recovery through furnace-based processing. India's BIS standards and PLI scheme incentives are consolidating informal collectors into licensed channels, formalizing previously fragmented supply.
- Nickel-metal Hydride:Hybrid vehicle battery recovery extracts rare earth elements and nickel alloys for steel alloying applications. Toyota and Honda legacy hybrid fleets in Japan and North America anchor residual demand.
- Alkaline:Consumer battery recycling recovers zinc and manganese dioxide at thinner margin pools. Retailer collection mandates in France are expanding feedstock access for specialized processors.
Lead-acid dominates tonnage throughput; lithium-ion shows steepest expansion trajectory.
End User:
Customer segments differentiate by volume predictability, contract duration, and technical specification requirements for recovered material output.
- Consumer Electronics:Smartphone and laptop OEMs require certified destruction of proprietary battery designs with data security protocols. Apple's prepaid recycling commitments and Samsung's Galaxy Upcycling programs establish reference contract structures.
- Automotive Manufacturers:Binding extended producer responsibility mandates in the EU are converting recycling from peripheral compliance cost to core supply chain function. Volkswagen, BMW, and Renault are unbundling recycling procurement from battery purchase agreements.
- Industrial Companies:Forklift, backup power, and motive power battery fleets generate bulk lead-acid and lithium-ion streams with predictable replacement cycles. Warehouse automation in Germany's logistics corridors concentrates demand.
- Renewable Energy Providers:Utility-scale battery storage installations create deferred recycling liabilities with 10-15 year operational lifespans. Stationary storage projects in California and Texas are designing second-life arbitrage into asset planning.
Automotive Manufacturers anchor contract value; Renewable Energy Providers are expanding most quickly.
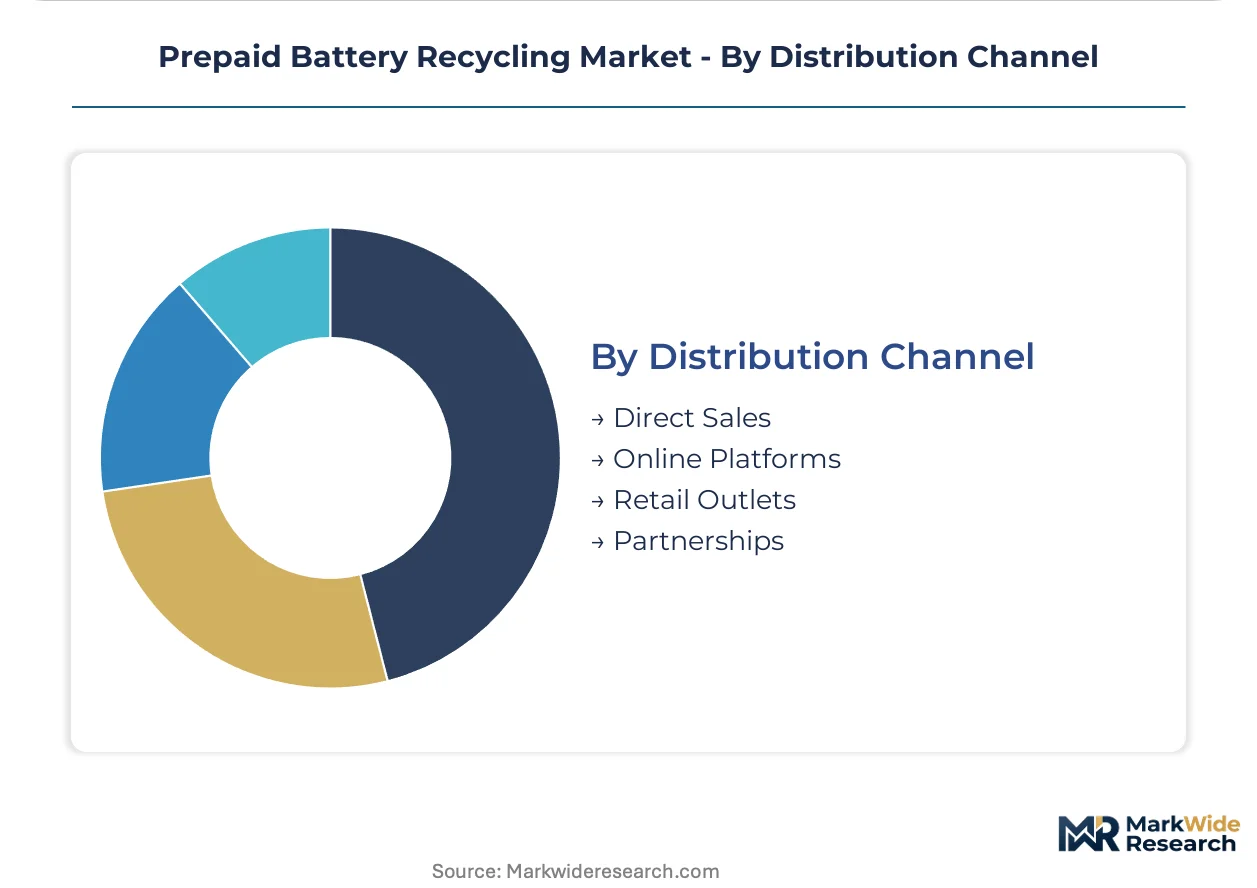
Distribution Channel:
Channel selection determines customer acquisition costs, contract customization depth, and geographic reach constraints for service providers.
- Direct Sales:Enterprise account teams negotiate multi-year prepaid contracts with automotive OEMs and industrial fleet operators. Umicore and Veolia deploy dedicated sales infrastructure for cathode precursor and municipal partnership deals.
- Online Platforms:Digital marketplaces match small-scale generators with certified recyclers for quote aggregation and logistics scheduling. French and German producer responsibility frameworks are mandating platform integration for compliance documentation.
- Retail Outlets:Electronics retailers and automotive dealerships serve as mandated collection handoff points. Best Buy in the US and Fnac in France have integrated prepaid recycling into point-of-sale transactions.
- Partnerships:Strategic alliances with battery manufacturers, logistics providers, and waste management firms extend service coverage without captive infrastructure. Gravita India's lead-acid smelter network leverages informal sector partnerships for feedstock security.
Direct Sales commands premium pricing; Online Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's prepaid battery recycling infrastructure outpaces France in processing capacity density, while India's informal sector formalization accelerates faster than China's regulatory consolidation efforts.
Germany
Automotive OEMs under extended producer responsibility mandates drive contract volumes for lithium-ion recovery. The EU Battery Regulation enforces binding material recovery thresholds and carbon footprint declarations. Industrial clusters around Hamburg and Düsseldorf anchor hydrometallurgical processing capacity and reverse logistics networks.
United States
Retiring EV fleets from California and Texas create predictable feedstock streams for dedicated processors. EPA RCRA hazardous waste rules govern interstate transport and storage limits for end-of-life batteries. The Pacific Northwest and Southeast automotive corridors concentrate collection infrastructure near manufacturing plants.
India
Lead-acid battery replacement cycles in logistics and telecom sectors generate bulk feedstock for formal sector consolidation. BIS standards and PLI scheme incentives accelerate licensed channel development and smelter capacity buildout. Gujarat and Maharashtra industrial zones host furnace operators adapting technology to informal sector feedstock streams.
France
Retailer collection mandates transform electronics retailers and automotive dealerships into mandated handoff points under producer responsibility frameworks. REACH substance restrictions and mass balance documentation requirements elevate compliance costs. Municipal partnerships with Veolia anchor collection infrastructure in Paris and Lyon metropolitan areas.
Belgium
Cathode precursor demand from European battery manufacturers sustains integrated refining complex operations. EU Battery Regulation traceability requirements enforce mass balance documentation for each chemistry stream. The Antwerp port region facilitates feedstock import logistics and material export to cathode production facilities.
Prepaid Battery Recycling Market Competitive Landscape
European producers anchor the integrated processing tier; North American specialists hold collection and logistics capabilities. The market structures around three tiers: capital-heavy metallurgical operators, reverse logistics specialists, and compliance advisory firms. Strategic archetypes include integrated refiners with cathode precursor output, collection network operators with municipal partnerships, and technology licensors with modular processing units. Competitive moves concentrate on capacity expansion for hydrometallurgical purification and strategic partnerships with automotive OEMs for prepaid contract security.
Among European integrated operators, Umicore and Veolia exemplify distinct positioning archetypes. Umicore occupies the metallurgical integration position with Belgian refining complex operations. Veolia represents the municipal partnership model with French collection infrastructure dominance. Gravita India anchors South Asian lead-acid recovery, demonstrating formal sector consolidation strategies for informal feedstock streams.
| Leading Market Players |
|---|
| Veolia |
| Umicore |
| Call2Recycle |
| Retriev Technologies |
| Gravita India |
| Exide Technologies |
| East Penn Manufacturing |
| EnerSys |
| Johnson Controls |
| Others |
Value Network & Pricing Analysis
Hydrometallurgical purification scale-up in Germany and Belgium is compressing unit recovery costs while concentrating processing capacity in Western European industrial clusters, simultaneously reshaping contract pricing power and feedstock sourcing economics for prepaid recycling operators.
Pricing Analysis
Capacity additions in Germany and Belgium are reshaping price floors for battery-grade cobalt and nickel recovery. Three-tier pricing structure across premium, standard, and economy levels segments contracts by purity certification and carbon footprint documentation, with automotive OEMs least price-sensitive due to regulatory compliance imperatives while small electronics retailers face acute cost compression. Price differentiation hinges on EU Battery Regulation mass balance certification and renewable energy sourcing verification. Pricing pressure stems from cobalt spot volatility in the Democratic Republic of Congo, forcing fixed-price prepaid contract renegotiations.
Supply Chain Analysis
EU Battery Regulation domestic-content mandates are reshaping sourcing toward European-sourced black mass and pre-processed feedstock. Supply concentrates in Germany, Belgium, and France for hydrometallurgical refining, with raw material dependencies on imported lithium concentrates from Australia and Chile, cobalt hydroxide from the Democratic Republic of Congo, and nickel matte from Indonesia. Single-source vulnerability in cobalt supply chains exposes processors to geopolitical disruption. Distribution runs through Antwerp port logistics and dedicated hazmat rail corridors to Düsseldorf and Hamburg industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prepaid battery recycling operates as a geographic-arbitrage play between EU regulatory premium pricing and India's formalizing low-cost lead-acid recovery, with the cost differential widening as EU carbon border adjustments phase in.
For Market Incumbents: Cement hydrometallurgical capacity leadership through backward integration into black mass preprocessing in Hamburg and Antwerp port zones. Lock in decade-long prepaid contracts with Volkswagen, BMW, and Renault before 2030 EU recovery mandates harden. Defend against modular direct-recycling technology disruptors by certifying closed-loop cathode precursor output under REACH carbon footprint protocols. For New Entrants and Emerging Players: Capture India's formalizing lead-acid collection corridors under BIS standards and PLI scheme incentives, where licensed channel consolidation lags processing capacity buildout. Target second-life battery arbitrage services for California and Texas utility-scale storage operators seeking deferred recycling liabilities. Lead with digital platform integration for French and German retailer compliance documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among South Asian lead-acid smelters with informal sector feedstock capture capabilities and pending licensed-channel conversion. Long-term viability centers on cathode precursor integration with European battery manufacturing. Watch EU Battery Regulation delegated act implementation on recycled content mandates as the inflection signal for contract repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Capacity Expansion | Belgian and German processors secure battery-grade purity thresholds exceeding 99.5% for cathode reuse. |
| Black Mass Preprocessing Integration | Antwerp port facilities reduce feedstock transport costs and customs exposure for EU-bound material. |
| Retailer Collection Mandate Partnerships | French and German electronics retailers become locked-in handoff nodes under producer responsibility frameworks. |
| Second-Life Battery Arbitrage Services | California and Texas utility storage operators extend asset lifecycles before final recycling obligations trigger. |
| Renewable Power Purchase Agreements | German processors secure competitive positioning under forthcoming EU carbon border adjustment mechanisms. |
Research Methodology
Direct dialogue with recycling plant operations managers, OEM sustainability procurement leads, EU regulatory affairs specialists, and municipal waste partnership coordinators grounded qualitative insights. Secondary validation drew from EPA RCRA hazardous waste filings, EU Battery Regulation delegated act documentation, Indian BIS standards publications, and customs trade data on black mass and precursor material flows. Bottom-up capacity modeling and top-down demand triangulation from automotive electrification forecasts anchored volume estimates.
Bottom-up segment analysis modeled service type, battery chemistry, end-user category, and distribution channel dynamics across the projection horizon. Hydrometallurgical yield assumptions, EU recovery threshold compliance costs, and cobalt-lithium-nickel price correlation matrices informed value projections. CAGRs derived from segment-level growth rate blending and cross-validation against installed EV fleet retirement curves.
EU Battery Regulation implementation delays, cobalt supply disruptions in the Democratic Republic of Congo, and India's informal sector formalization pace are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market