
 Marine Lithium-Ion Battery Market | 2026-2036
Marine Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Lithium-Ion Battery Market Insights
Buyer concentration among commercial ferry operators is rebalancing toward fragmented regional transit authorities and private offshore vessel contractors. Corvus Energy dominates Nordic electrification projects through its Oslo engineering hub and captive supply of liquid-cooled modular systems. Spear Power Systems specializes in defense-grade battery architectures for submarine propulsion, leveraging its Kansas-based manufacturing for MIL-STD compliance. EST-Floattech anchors European inland waterway retrofits with Dutch-designed containerized battery rooms that simplify classification society approvals.
Marine lithium-ion batteries are rechargeable electrochemical storage systems engineered with IP67 or higher ingress protection, active thermal management, and cobalt-reduced cathode formulations to survive salt spray, vibration, and partial-state-of-charge cycling inherent to vessel duty profiles. Prismatic cells lead commercial shipping installations where space-optimized pack architectures maximize kilowatt-hour density below deck, while polymer formats gain share in recreational boating where conformal wrapping suits compact hull geometries. Electric boats represent the fastest-growing application segment as harbor cities restrict diesel entry, though hybrid vessels retain the largest installed base and associated service revenue pools.
DNV classification rules, the EU Green Deal's FuelEU Maritime initiative, and EPA Clean Air Act vessel standards collectively mandate emissions reductions that force propulsion electrification and validate battery system certification costs. IMO's revised strategy for net-zero greenhouse gas emissions by mid-century accelerates retrofit timelines for existing fleets, directly expanding addressable demand for dockside installation services. Stakeholders must monitor cell supply agreements and shore charging infrastructure buildouts as the binding constraint on fleet conversion velocity.
Market Dynamics
IMO's revised net-zero strategy for 2050 is compressing fleet conversion timelines, forcing dockside electrification infrastructure buildouts and validating battery system certification costs across commercial shipping corridors.
Growth Catalysts
- FuelEU Maritime initiative:The EU's binding well-to-wake emissions framework mandates renewable energy adoption for vessels calling at European ports, accelerating retrofit demand for existing diesel fleets.
- Nickel-manganese-cobalt chemistry advances:Cell innovations extending cycle life in saltwater environments are reducing total cost of ownership for ferry operators in Norway's fjord transit networks.
- Harbor city diesel restrictions:Municipal entry bans on combustion engines in Copenhagen, Amsterdam, and Vancouver are pulling electric boat demand from public transit authorities.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings constrain pack pricing predictability for vessel integrators negotiating multi-year supply contracts.
- East Asian cell concentration:Cathode and separator production clusters in China and South Korea create single-source dependency risks for European system assemblers.
- Thermal runaway containment:Current fire suppression standards impose weight penalties that erode cargo capacity on weight-sensitive fast ferries.
Strategic Opportunities
- US inland waterway retrofits:The EPA Clean Air Act vessel standards create compliance-driven demand for hybrid-electric towboats on the Mississippi River system.
- Autonomous vessel convergence:Battery-electric propulsion architectures are converging with unmanned surface vehicle navigation systems to enable reduced-crew offshore operations.
- Shore charging infrastructure:Port authority electrification programs in Rotterdam and Singapore open recurring service revenue streams for system integrators.
Industry Challenges
- Marine electrical engineering talent scarcity:Shortages of certified technicians familiar with DNV classification rules delay commissioning schedules for retrofitted vessels.
- Classification society approval timelines:Case-by-case battery room certification processes stretch 12-18 months, mismatching fleet operator procurement cycles.
- Legacy propulsion integration:Hybrid system architecture complexity rises when mating electric drives with existing gearbox and shafting configurations on converted hulls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Lithium-Ion Battery Market |
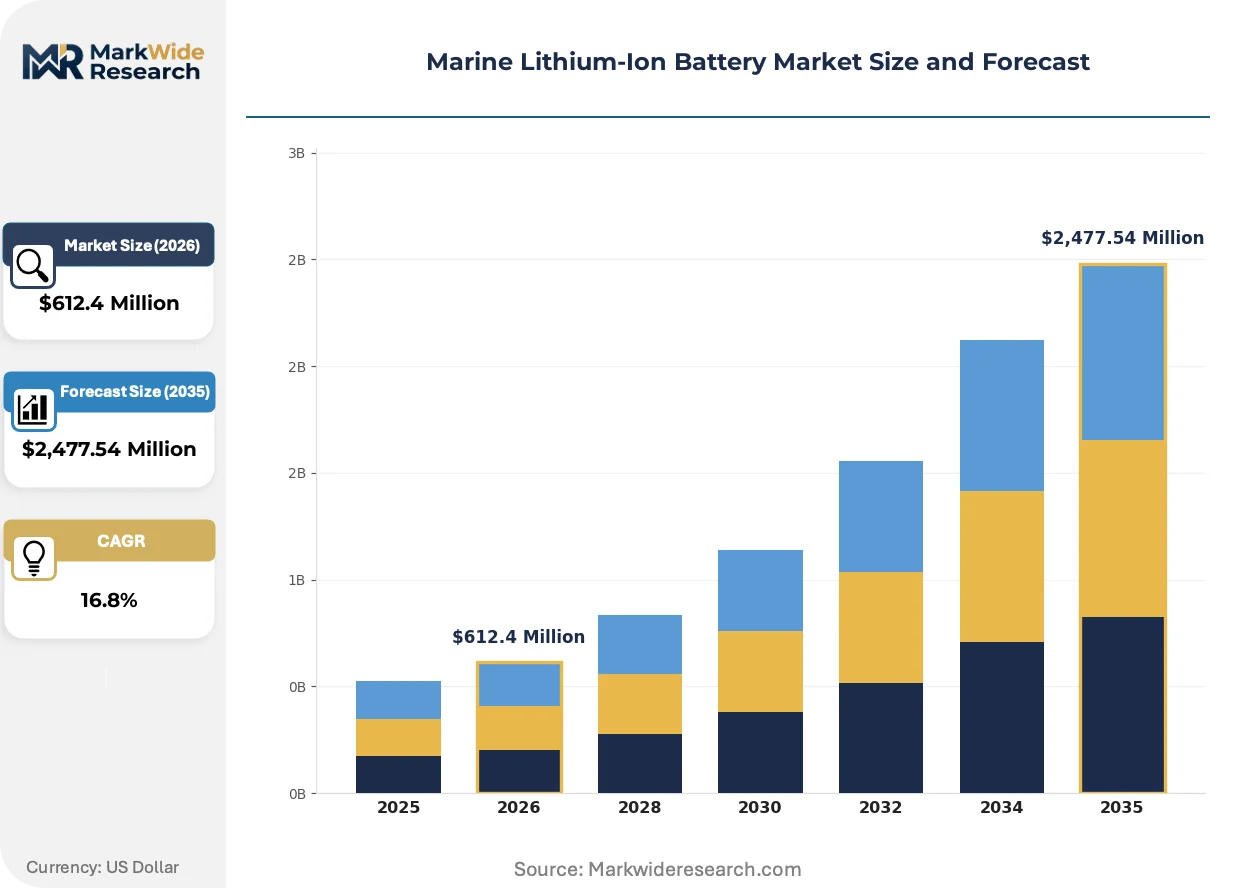
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,477.54 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Polymer, Depressed Application: Electric Boats, Hybrid Vessels, Submarines, Offshore Platforms End User: Commercial Shipping, Recreational Boating, Military, Research Institutes Installation: Retrofit, OEM Integration, Dockside, Offshore |
| Companies Covered | Corvus Energy, Spear Power Systems, EST-Floattech, Forsee Power, Akasol, XALT Energy, Saft, Leclanché SA, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Lithium-Ion Battery Market Trends and Innovations
Solid-state cell architectures and modular pack designs are reshaping how marine integrators approach vessel electrification, compressing development cycles while expanding addressable hull sizes.
Lithium-metal anode technology is converging with ceramic electrolyte formulations to enable energy densities exceeding 400 Wh/kg. Norwegian ferry operators are piloting these cells in Arctic route applications where low-temperature performance degradation plagues conventional graphite anodes. The structural consequence is converging with lighter hull designs that sacrifice less cargo volume to battery mass.
The EU Green Deal's CSRD disclosure requirements are mandating Scope 3 emissions reporting for maritime logistics chains. Shipowners must now document upstream energy sources, pushing battery-electric vessels into charter preference for corporate sustainability compliance. Baltic Sea container feeders are responding fastest, with operators restructuring fleet procurement around verified renewable shore power contracts.
Leasing models for battery packs are displacing outright capital purchases among regional ferry authorities. Dutch and German transit operators now contract for energy-as-a-service, transferring cell degradation risk to system suppliers. This shift concentrates most visibly in the Wadden Sea island routes, where public procurement rules favor operational expenditure structures over infrastructure balance-sheet expansion.
Marine Lithium-Ion Battery Market Segmentation
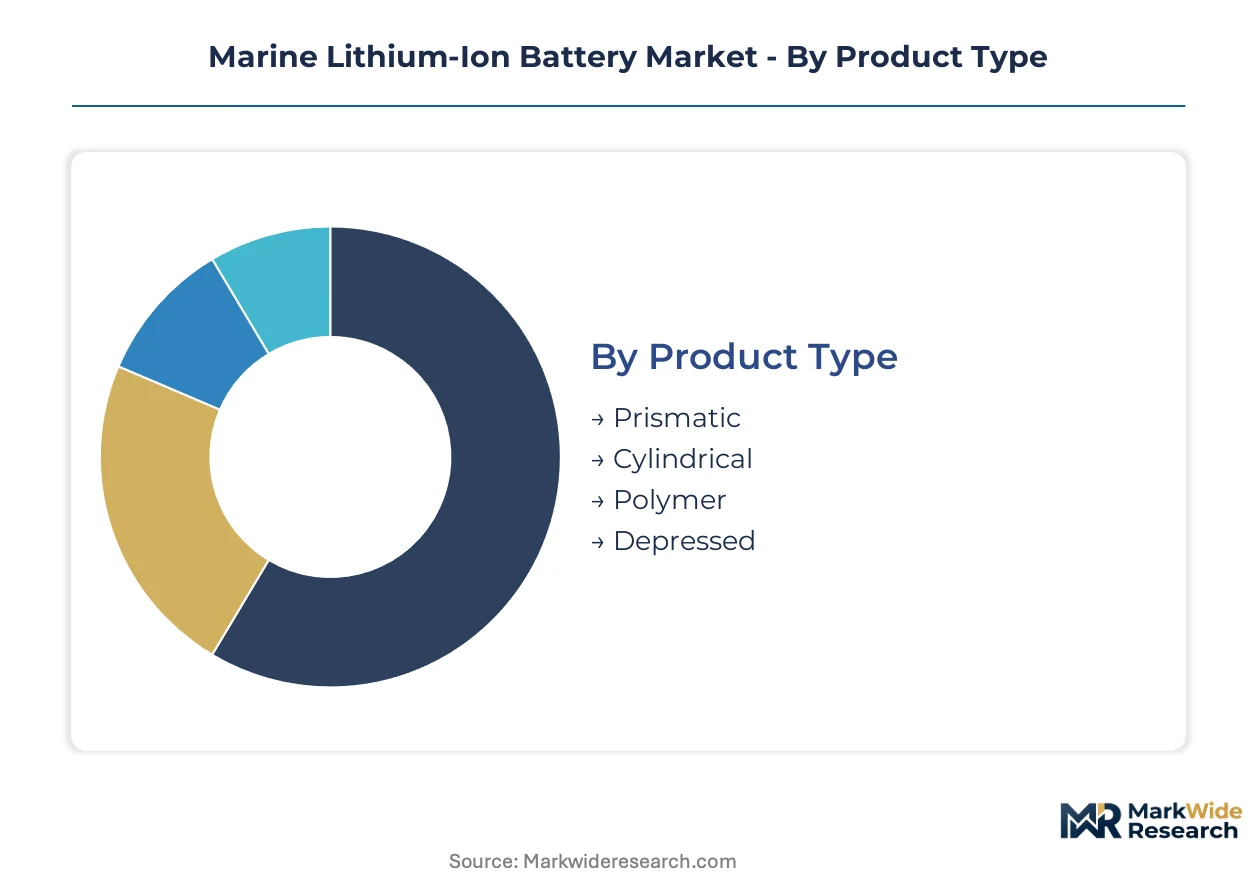
Segmentation in marine lithium-ion batteries reveals how certification burdens, thermal management requirements, and vessel duty cycles reshape procurement priorities across cell formats and installation modes. Each dimension carries distinct approval pathways through DNV, Lloyd's Register, and classification societies that govern fleet conversion economics.
Product Type:
DNV classification rules impose differentiated fire suppression and thermal runaway containment standards across cell geometries, with prismatic formats facing the most stringent compartmentalization mandates for commercial shipping certification.
- Prismatic:Rigid aluminum-cased cells with layered electrode stacks deliver space-optimized pack architectures maximizing kilowatt-hour density below deck. Demand concentrates in Norway's fjord transit networks where ferry operators prioritize volumetric efficiency for high-frequency route electrification under FuelEU Maritime compliance deadlines.
- Polymer:Flexible pouch configurations with laminated foil enclosures enable conformal wrapping that suits compact hull geometries in recreational boating. Baltic Sea yacht manufacturers specify these formats for premium electric day-cruisers where hull curvature limits rigid pack placement.
- Cylindrical:Steel-cased 18650 and 21700 formats leverage automotive scale economies for cost-sensitive inland waterway retrofits.
- Depressed:Low-profile cell architectures engineered for submarine battery rooms with severe height restrictions.
Volume sits with prismatic formats in commercial installations; growth tilts toward polymer configurations as recreational electrification accelerates.
Application:
Harbor city diesel restrictions are rebalancing application mix toward electric boats, while hybrid vessels retain the largest installed base and associated service revenue pools from ongoing fleet retrofits.
- Electric Boats:Pure battery-electric propulsion systems with no onboard combustion capability serve municipal transit authorities in Copenhagen, Amsterdam, and Vancouver where entry bans on diesel engines pull demand from public ferry operators. Copenhagen's harbor bus network exemplifies this shift, with battery swaps replacing conventional bunkering infrastructure.
- Hybrid Vessels:Combined diesel-electric architectures with clutchable gensets dominate existing fleet conversions where range anxiety and charging infrastructure gaps persist. Mississippi River towboat operators deploy these systems to satisfy EPA Clean Air Act vessel standards without sacrificing operational flexibility for long-haul cargo movements.
- Submarines:Pressure-resistant battery rooms with MIL-STD compliance requirements for defense-grade propulsion.
- Offshore Platforms:Station-keeping power systems for drilling rigs and floating production units.
Hybrid vessels anchor current revenue; electric boats are gaining share fastest in newbuild procurement.
End User:
Procurement authority fragmentation is dispersing across regional transit authorities and private contractors, diluting the buyer concentration once held by national ferry operators.
- Commercial Shipping:Container feeders, bulk carriers, and tanker fleets with IMO-mandated decarbonization timelines. Baltic Sea operators restructure procurement around verified renewable shore power contracts to satisfy EU Green Deal CSRD disclosure requirements.
- Military:Naval procurement with MIL-STD-810 and MIL-STD-461 electromagnetic compatibility mandates.
- Recreational Boating:Yacht builders and marina operators serving high-net-worth individual owners.
- Research Institutes:Arctic and oceanographic survey vessels with specialized low-temperature performance requirements.
Commercial shipping commands procurement volume; military specifications drive margin premiums.
Installation:
Dockside infrastructure buildouts are compressing retrofit timelines, though OEM integration remains the preferred pathway for hull designs optimized around battery mass distribution from inception.
- Retrofit:Conversion of existing diesel vessels through hull cutting, structural reinforcement, and battery room insertion. Dutch-designed containerized battery rooms simplify classification society approvals for EST-Floattech deployments across European inland waterways.
- OEM Integration:Original equipment manufacturer incorporation of battery systems during newbuild construction. Norwegian shipyards specify liquid-cooled modular systems from captive engineering hubs to minimize commissioning delays.
- Dockside:Shore-based charging infrastructure and battery swap stations.
- Offshore:Remote installation and maintenance protocols for platforms beyond conventional port access.
Retrofit installations dominate addressable fleet size; OEM integration captures the steepest expansion trajectory in newbuild orderbooks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean lithium brine deposits anchor cathode supply chains for marine cell manufacturers. Norwegian fjord transit networks and Baltic Sea shipping corridors concentrate demand as FuelEU Maritime deadlines tighten. Cell production clusters in China and South Korea feed system integrators across three continents.
Norway
Fjord ferry electrification drives procurement volumes as municipal operators replace diesel fleets. The Norwegian Maritime Authority enforces strict battery room safety standards under DNV classification rules. Oslo engineering hubs host liquid-cooled modular system development for high-frequency route applications.
Germany
Defense-grade submarine propulsion contracts sustain premium-tier demand from naval procurement agencies. The EU Green Deal's FuelEU Maritime initiative mandates renewable energy adoption for vessels calling at Hamburg and Bremerhaven. Baltic Sea container feeders restructure procurement around verified renewable shore power contracts.
Netherlands
European inland waterway retrofits accelerate as EST-Floattech deploys containerized battery rooms. The EU CSRD disclosure requirements push corporate charterers toward battery-electric vessels for Scope 3 compliance. Wadden Sea island routes pioneer energy-as-a-service leasing models for regional transit authorities.
United States
Mississippi River towboat operators deploy hybrid-electric systems to satisfy EPA Clean Air Act vessel standards. The Inflation Reduction Act's clean energy provisions support dockside charging infrastructure buildouts. Kansas-based manufacturing anchors defense-grade battery architecture production for MIL-STD compliance.
China
Cathode and separator production clusters supply global system assemblers despite single-source dependency risks. The Ministry of Ecology and Environment's dual carbon goals accelerate domestic vessel electrification programs. Yangtze River Delta shipyards integrate battery systems during newbuild construction for coastal feeder routes.
Marine Lithium-Ion Battery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in autonomous vessel convergence and shore charging infrastructure. The vendor base stratifies across liquid-cooled modular specialists, defense-grade architects, and containerized retrofit designers. Three archetypes dominate: Nordic electrification leaders, MIL-STD compliance specialists, and inland waterway retrofit innovators. Competitive moves concentrate on strategic partnerships with port authorities and technology licensing for thermal management systems.
Within the Nordic electrification tier, Corvus Energy and EST-Floattech exemplify divergent geographic anchoring strategies. Corvus Energy represents the Oslo-based engineering hub model with captive supply relationships, while EST-Floattech occupies the Dutch-designed containerized system niche for simplified classification approvals. Spear Power Systems anchors the defense-grade specialist archetype from its Kansas manufacturing base, illustrating how MIL-STD compliance requirements create geographic concentration in secure supply chains.
| Leading Market Players |
|---|
| Corvus Energy |
| Spear Power Systems |
| EST-Floattech |
| Forsee Power |
| Akasol |
| XALT Energy |
| Saft |
| Leclanché SA |
| Siemens Energy |
| Others |
Pricing and Supply Chain Analysis
Captive cathode supply relationships in Norwegian engineering hubs anchor both procurement security and pricing power for liquid-cooled modular system suppliers serving fjord ferry operators under tightening FuelEU Maritime deadlines. This integration choice insulates pack assemblers from lithium carbonate volatility while compressing total cost of ownership for high-frequency route electrification.
Pricing Analysis
Warranty bundling with thermal management system maintenance separates premium-tier suppliers from unbundled competitors in commercial shipping procurement. Three-tier pricing structure across DNV-certified, Lloyd's Register-approved, and uncertified economy levels reflects fire suppression testing investment and classification society approval timelines. Cost compression in the economy tier intensifies as automotive-scale cylindrical cell imports erode margins for inland waterway retrofits. Regional transit authorities exhibit the highest price sensitivity, while defense procurement agencies absorb premium pricing for MIL-STD compliance.
Supply Chain Analysis
Certified marine electrical engineering talent scarcity in Norway, Germany, and the Netherlands constrains system integration capacity and extends commissioning lead times for dockside retrofits. Cathode active material production draws from Chilean lithium brine deposits and Chinese precursor refining clusters, creating single-source vulnerability risks for European pack assemblers. Tariff exposure on separator imports from South Korean manufacturers threatens margin stability for Kansas-based defense-grade producers. Distribution runs through captive engineering hubs serving Nordic electrification projects and containerized battery room specialists for inland waterway networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is compressing margins across the value chain as system integrators pursue backward control over cell supply agreements to secure volume under IMO net-zero mandates.
For Market Incumbents: Lock in long-term cathode supply contracts with Chilean and Australian mining operators before FuelEU Maritime compliance deadlines tighten procurement competition. Expand Oslo engineering hub capacity to reduce commissioning delays that plague competitors facing DNV certification backlogs. Priority defensive moves center on thermal management IP licensing and shore charging infrastructure partnerships that create switching costs for ferry operators. For New Entrants and Emerging Players: Launch via energy-as-a-service leasing models targeting Wadden Sea island routes and other regional transit authorities constrained by public procurement rules favoring operational expenditure structures. White-space concentration sits in autonomous vessel convergence applications where battery-electric architectures intersect with unmanned surface vehicle navigation systems. Target Mississippi River towboat hybrid retrofits as the most penetrable segment given EPA Clean Air Act enforcement gaps and limited incumbent presence. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automotive battery producers seeking marine certification capabilities and shore charging infrastructure specialists. Long-term viability favors vertically integrated system assemblers with captive cathode relationships and DNV-approved fire suppression architectures. The inflection signal to watch is port authority electrification program acceleration in Rotterdam and Singapore as binding constraints on fleet conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Supply | Secures lithium carbonate access for Norwegian pack assemblers facing FuelEU Maritime demand surges. |
| DNV Certification Fast-Track Investment | Compresses 12-18 month battery room approval timelines to match ferry operator procurement cycles. |
| Shore Charging Infrastructure Partnership | Opens recurring service revenue streams with Rotterdam and Singapore port authorities. |
| Energy-as-a-Service Leasing Launch | Transfers cell degradation risk to suppliers for Dutch and German transit operators. |
| Thermal Management IP Licensing | Monetizes liquid-cooled modular system expertise across Nordic electrification projects. |
Research Methodology
Multi-period observation of ferry electrification order flows, cathode supply contract structures, and classification society approval timelines anchored the trend analysis, supplemented by interviews with shipyard procurement directors, DNV certification engineers, port authority electrification officers, and marine electrical systems integrators. Secondary validation drew from IMO greenhouse gas strategy documents, EU Green Deal regulatory filings, EPA Clean Air Act vessel standard enforcement data, and customs records of lithium carbonate trade flows. Bottom-up vessel fleet conversion modeling triangulated against top-down addressable market sizing across the analysis window.
Segment-weighting approaches applied differential growth assumptions to prismatic versus polymer cell formats, electric boat versus hybrid vessel applications, and retrofit versus OEM integration pathways. The analytical framework incorporated vessel duty cycle intensity, harbor city diesel restriction enforcement patterns, and shore charging infrastructure deployment rates throughout the forecast period. CAGRs were derived from fleet replacement timelines under IMO net-zero mandates and cell chemistry innovation adoption curves for nickel-manganese-cobalt formulations.
The model assumes a particular technology adoption path; alternative pathways for solid-state lithium-metal architectures would alter the outlook for energy density and low-temperature performance assumptions. Forecasts reflect documented assumptions regarding FuelEU Maritime enforcement stringency and lithium carbonate price stabilization. Material deviation in DNV classification rule amendments or Chilean lithium export policy shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market