
 Asia-Pacific Battery Recycling Market | 2026-2036
Asia-Pacific Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Battery Recycling Market Outlook
Electric vehicle OEMs are redrawing procurement priorities across the Asia-Pacific battery recycling landscape. GEM Co., Ltd. leverages its integrated cathode precursor capacity to dominate hydrometallurgical recovery flows in China. SK TES anchors South Korean operations through partnerships with domestic cell manufacturers, while Attero Recycling sustains collection density across India's fragmented automotive aftermarket.
Asia-Pacific battery recycling encompasses the disassembly, sorting, and chemical recovery of spent electrochemical cells to reclaim lithium, cobalt, nickel, and manganese compounds for re-entry into cathode manufacturing. Hydrometallurgical routes achieve higher purity recovery rates for lithium-ion chemistries compared with pyrometallurgical alternatives, though energy intensity varies by feedstock grade. Lithium-ion recycling commands the fastest expansion trajectory as EV penetration deepens across the region's major automotive markets. Lead-acid processing retains volume dominance through India's vast two-wheeler and uninterruptible power supply base, where collection networks remain mature and margin pools thin.
China's MEE enforces discharge standards for recycling effluents while SAMR oversees national standard GB/T specifications for recovered material quality. India's BIS and CPCB frameworks are tightening extended producer responsibility mandates for battery importers and assemblers. Stakeholders must monitor regulatory divergence between national recovery rate targets and actual enforcement capacity as feedstock competition intensifies.
Market Dynamics
Feedstock competition between cathode material refiners and hydrometallurgical recyclers is compressing margin pools across China's Jiangsu and Guangdong provinces, where collection infrastructure clusters near precursor manufacturing hubs.
Growth Catalysts
- Extended Producer Responsibility Mandates:India's BIS and CPCB frameworks are tightening compliance thresholds for battery importers, forcing formal channel development and collection density improvements across the fragmented automotive aftermarket.
- Dual Carbon Policy Enforcement:China's MEE discharge standards and SAMR quality specifications are accelerating feedstock diversion from informal collectors toward licensed hydrometallurgical operators with effluent treatment capabilities.
- Lithium-Ion Chemistry Proliferation:Electric vehicle OEM procurement of recycled cathode precursors is displacing primary mining contracts as cell manufacturers seek supply security for nickel and cobalt compounds.
Market Restraints
- Feedstock Concentration Risk:China's Jiangsu and Guangdong provinces control disproportionate shares of accessible spent battery flows, creating geographic supply vulnerability for operators without coastal logistics networks.
- Collection Infrastructure Gaps:India's vast two-wheeler and UPS lead-acid base relies on informal aggregator networks with poor traceability, limiting feedstock quality predictability for formal recyclers.
- Pyrometallurgical Energy Intensity:High-temperature recovery routes face escalating electricity cost volatility and carbon accounting exposure under China's dual carbon tracking systems.
Strategic Opportunities
- Southeast Asia Feedstock Development:Thailand and Indonesia's emerging EV assembly bases lack mature collection infrastructure, creating first-mover positioning for integrated recycler-refiner partnerships with domestic cell manufacturers.
- Direct Recycling Technology Convergence:Cathode regeneration processes that bypass full elemental dissolution are attracting pilot investment from South Korean cell producers seeking lower-emission material loops.
- Urban Mining Channel Innovation:Digital freight platforms connecting dismantlers with hydrometallurgical facilities are compressing logistics costs and improving lot traceability across China's industrial clusters.
Industry Challenges
- Skilled Technician Scarcity:Battery disassembly and diagnostic expertise remains concentrated among legacy lead-acid operators, creating workforce bottlenecks for lithium-ion processing scale-up.
- Capex Intensity for Effluent Systems:China's MEE standards require substantial investment in wastewater treatment and zero-liquid-discharge infrastructure, disadvantaging smaller operators against integrated chemical conglomerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Battery Recycling Market |
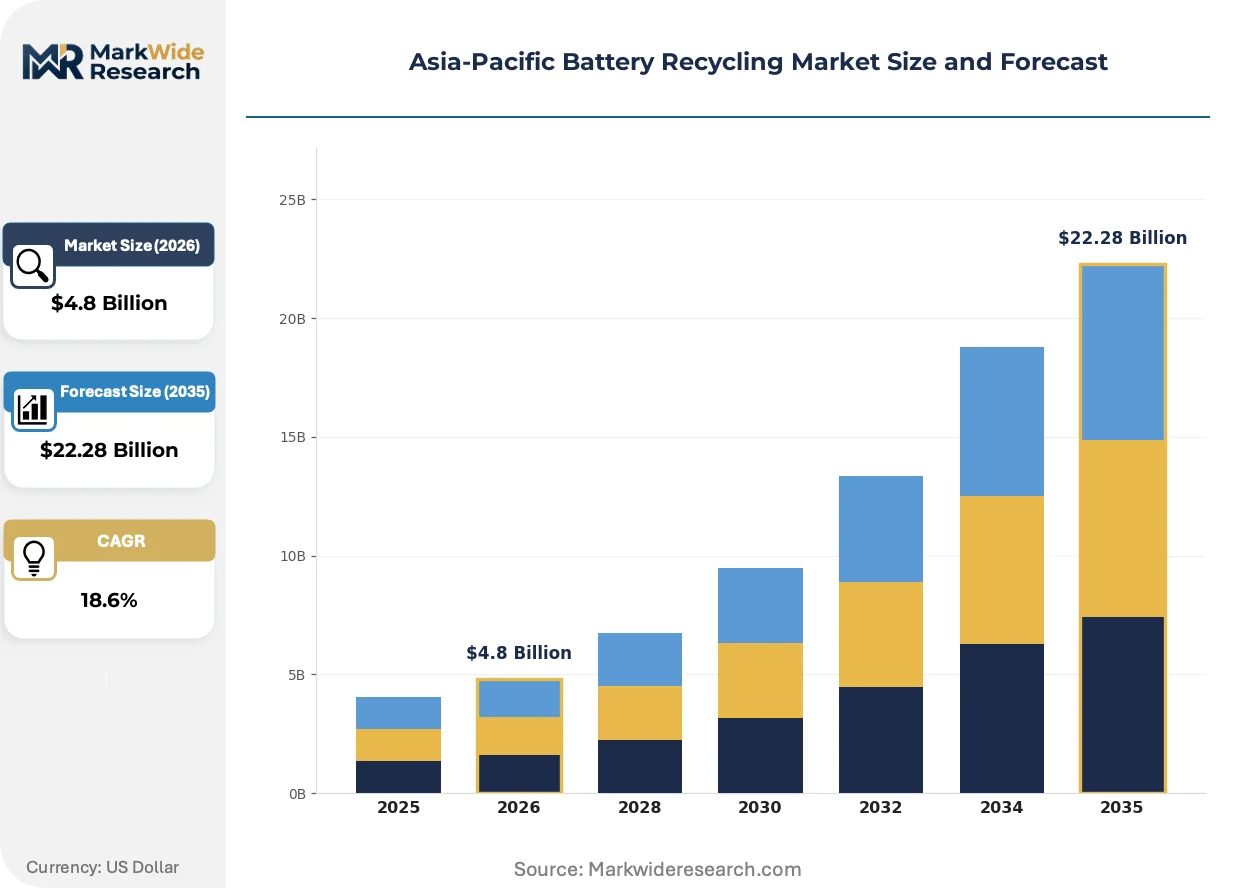
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Others End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Technology: Hydrometallurgical, Pyrometallurgical, Biotechnological, Mechanical Service Type: Collection, Processing, Treatment, Consulting |
| Companies Covered | GS Yuasa International Ltd, Attero Recycling, GEM Co., Ltd., Lohum Cleantech, ACE Green Recycling, Exide Industries Limited, Neometals Ltd, SK TES, Contemporary Amperex Technology Co., Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Battery Recycling Market Strategic Shifts
Direct cathode regeneration and closed-loop precursor manufacturing are compressing traditional hydrometallurgical processing steps, while regulatory carbon accounting forces transparency across material provenance chains.
Direct recycling technology is decomposing the conventional black-mass intermediary stage by preserving cathode crystal structures through selective relithiation rather than full elemental dissolution. South Korean cell manufacturers are piloting these routes for NCM chemistries at moderate scale. The technology is decomposing incumbent hydrometallurgical margin structures by reducing reagent consumption and energy intensity.
China's MEE effluent discharge standards and SAMR material quality specifications are forcing recycler consolidation toward integrated chemical parks with shared wastewater infrastructure. Operators without captive precursor offtake agreements face exclusion from formal feedstock allocation systems. Jiangsu province's industrial clusters are responding fastest through state-backed recycling park development.
Automotive OEMs are consolidating supplier lists toward recyclers with verified carbon intensity data and cathode precursor co-location capabilities. Long-term offtake contracts with fixed-volume escalation clauses are displacing spot market transactions for battery-grade nickel and cobalt compounds. This concentration is most visible in China's Guangdong province, where EV manufacturers have established direct recycling partnerships with integrated refiner-recyclers.
Asia-Pacific Battery Recycling Market Segmentation
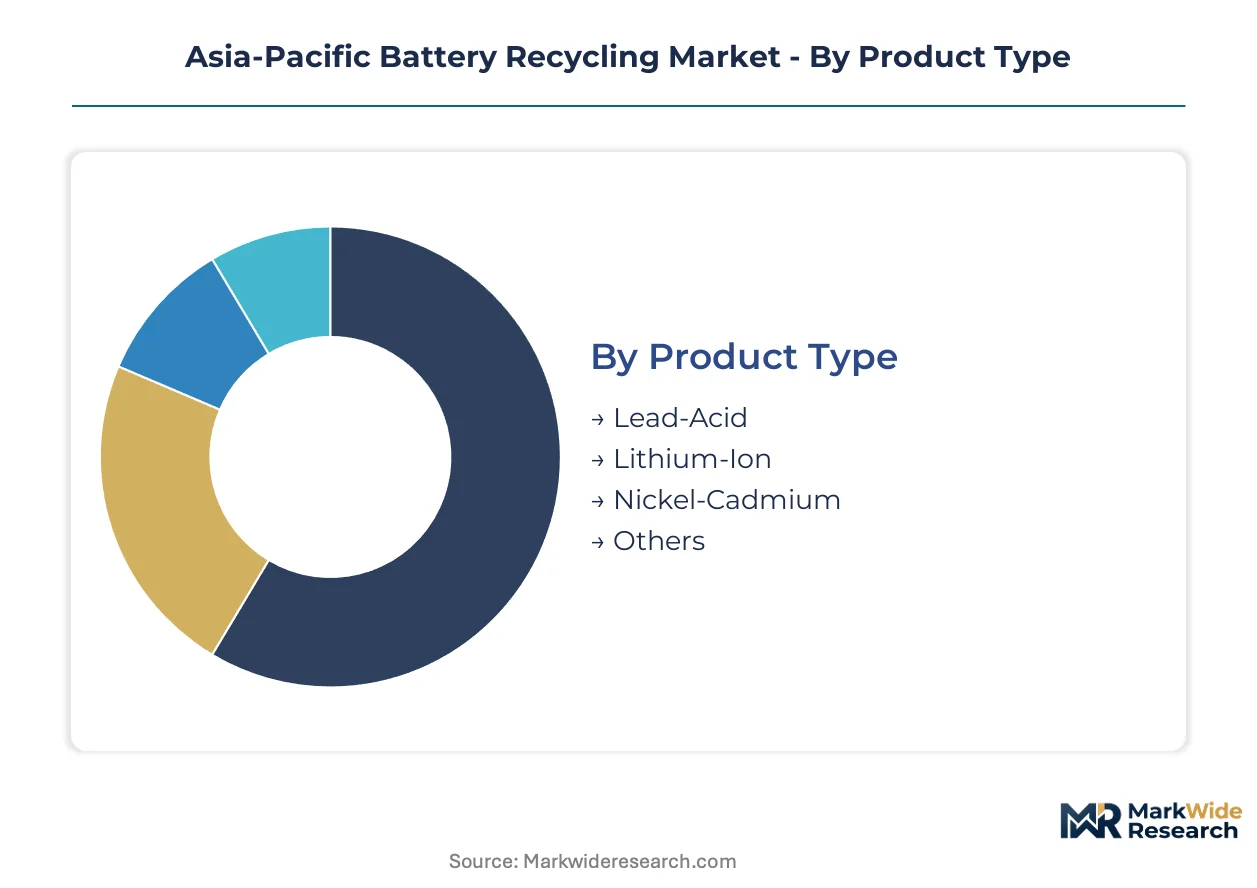
Segmentation in Asia-Pacific battery recycling reveals how chemistry-specific recovery economics and regulatory pressure reshape competitive positioning across distinct feedstock streams. Understanding these divisions exposes where margin compression concentrates and where technology substitution threatens incumbent operators.
Product Type:
Substitution pressure intensifies against nickel-cadmium and legacy chemistries as lithium-ion cost curves flatten and environmental liability frameworks tighten across China and India.
- Lead-Acid:Mature sulfuric acid-electrode systems dominate India's two-wheeler and uninterruptible power supply aftermarket. Demand concentrates in Maharashtra and Tamil Nadu industrial corridors where informal collection networks feed formal smelters facing BIS compliance deadlines.
- Lithium-Ion:NCM and LFP cathode chemistries require hydrometallurgical separation of lithium, cobalt, nickel, and manganese compounds. China's Jiangsu province clusters the highest processing density as electric vehicle OEM procurement shifts toward verified carbon-intensity supply chains.
- Nickel-Cadmium:Aviation and railway backup applications sustain limited recovery volumes. India's CPCB extended producer responsibility mandates are accelerating phase-out timelines for industrial Ni-Cd installations.
- Others:Sodium-sulfur and flow battery chemistries occupy niche grid-storage roles. Japan's METI recycling guidelines for stationary energy storage systems remain under development.
Lead-acid retains volume leadership across India's fragmented automotive aftermarket; lithium-ion holds the steepest expansion curve as electric vehicle penetration deepens in China and South Korea.
End User:
Cost tier stratification separates high-volume automotive contracts from margin-dilute industrial processing, with renewable energy storage emerging as the premium pricing segment.
- Automotive:Passenger electric vehicle OEMs in China and South Korea dominate cathode precursor offtake negotiations. Guangdong province's integrated recycler-refiner partnerships command premium pricing through verified carbon accounting.
- Consumer Electronics:Smartphone and laptop battery streams deliver lower metal concentrations per unit. Collection density challenges persist across Southeast Asia's dispersed urban populations.
- Industrial:Forklift and material handling equipment generate predictable lead-acid feedstock volumes. India's manufacturing hubs near Pune and Chennai sustain formal channel development.
- Renewable Energy:Grid-scale battery installations in China and Australia create emerging demand for direct cathode regeneration services. Project developers seek closed-loop material agreements to satisfy green financing criteria.
Automotive commands the dominant revenue share; renewable energy storage is gaining share fastest as utility-scale deployment accelerates across Australia and China.
Technology:
Application-specific recovery requirements favor hydrometallurgical purity for lithium-ion while pyrometallurgical routes defend cost positions in lead-acid processing.
- Hydrometallurgical:Acid leaching and solvent extraction achieve battery-grade metal recovery rates for lithium-ion cathode materials. China's MEE effluent discharge standards are consolidating licensed capacity toward integrated chemical parks with shared wastewater infrastructure.
- Pyrometallurgical:High-temperature smelting remains economically viable for lead-acid and nickel-containing feedstocks. Electricity cost volatility under China's dual carbon tracking systems is compressing margins for standalone operators.
- Biotechnological:Bioleaching using acidophilic bacteria offers reduced reagent consumption for low-grade ores and black mass. South Korean pilot programs are testing fungal-based lithium recovery at moderate scale.
- Mechanical:Physical disassembly and sorting precede chemical treatment stages. Automated dismantling lines face skilled technician scarcity across China's lithium-ion processing expansion.
Pyrometallurgical retains cost leadership in lead-acid; hydrometallurgical is expanding most quickly as lithium-ion feedstock quality requirements tighten.
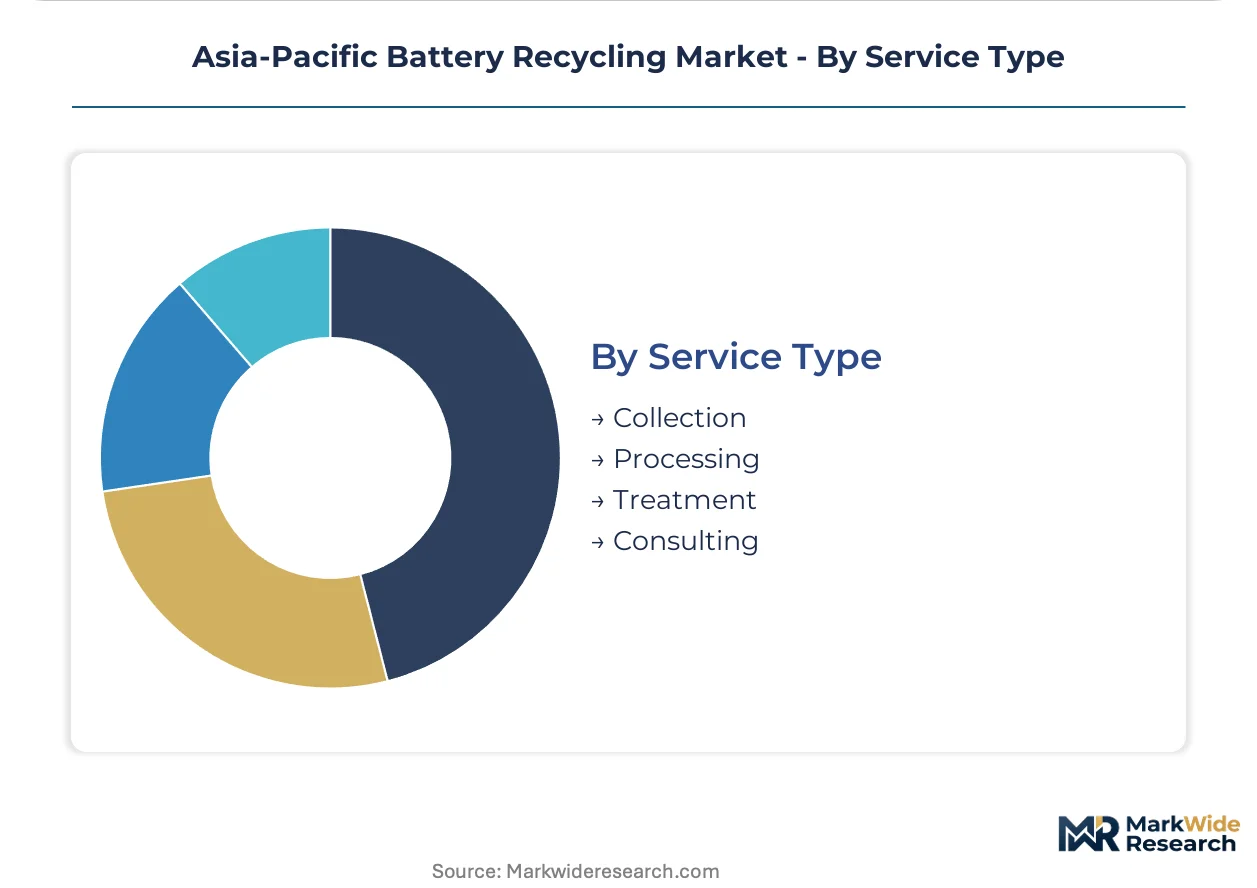
Service Type:
Customer type divergence separates asset-light collection logistics from capital-intensive processing infrastructure, with treatment services capturing the steepest margin expansion.
- Collection:Reverse logistics networks aggregate spent batteries from dispersed end-users. India's informal aggregator dominance creates traceability gaps that formal channel investments must close under BIS mandates.
- Processing:Black mass production and elemental separation constitute the value-intensive core. China's Jiangsu province licensing requirements favor operators with captive precursor offtake agreements.
- Treatment:Effluent management and hazardous waste disposal face tightening MEE standards. Zero-liquid-discharge infrastructure investment disadvantages smaller operators against chemical conglomerates.
- Consulting:Regulatory compliance advisory and carbon accounting verification support OEM procurement teams. South Korean cell manufacturers seek material provenance documentation for EU-bound exports.
Processing captures the dominant value pool; treatment services are climbing the fastest as discharge standard enforcement intensifies across China's coastal provinces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle OEM procurement teams dominate buyer concentration across the region, with cathode precursor offtake negotiations increasingly favoring integrated refiner-recyclers with verified carbon accounting capabilities.
China
Jiangsu and Guangdong provinces anchor spent battery collection density, feeding hydrometallurgical clusters near precursor manufacturing hubs. SAMR's GB/T quality specifications and MEE discharge standards are accelerating feedstock diversion from informal collectors toward licensed operators with zero-liquid-discharge infrastructure. GEM Co., Ltd. leverages integrated cathode precursor capacity to dominate recovery flows in Jiangsu's industrial parks.
India
Maharashtra and Tamil Nadu industrial corridors sustain lead-acid processing dominance through two-wheeler and UPS aftermarket density. BIS compliance deadlines and CPCB extended producer responsibility mandates are forcing formal channel development across fragmented automotive aftermarkets. Attero Recycling sustains collection density through partnerships with informal aggregator networks transitioning toward traceable logistics.
South Korea
Domestic cell manufacturers anchor cathode precursor demand, with SK TES partnering across the battery value chain for feedstock security. The country's national environmental regulator enforces recycling quotas that align with EU-bound export documentation requirements. Pilot direct recycling programs for NCM chemistries are attracting investment from cell producers seeking lower-emission material loops.
Japan
METI recycling guidelines for stationary energy storage systems are under development as grid-scale battery deployment accelerates. Aviation and railway backup applications sustain limited nickel-cadmium recovery volumes. Sodium-sulfur and flow battery chemistries occupy niche grid-storage roles with emerging end-of-life protocols.
Australia
Grid-scale battery installations are creating emerging demand for direct cathode regeneration services as utility-scale deployment accelerates. Project developers seek closed-loop material agreements to satisfy green financing criteria. The country's national environmental regulator is developing frameworks for utility-scale battery end-of-life management.
Asia-Pacific Battery Recycling Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive precursor offtake agreements, compressing standalone recycler margins. Tiered competitive structure separates asset-heavy hydrometallurgical operators from logistics-focused collection specialists. Dominant archetypes include integrated refiner-recyclers, regional collection network operators, and cathode material manufacturers with backward integration into recovery. Competitive moves concentrate on strategic partnerships with cell manufacturers and capacity expansion within licensed chemical parks.
Among Asia-Pacific-based operators, GEM Co., Ltd. and SK TES occupy positions representing integrated and partnership-driven archetypes respectively, while Attero Recycling exemplifies collection-density-focused positioning within India's fragmented aftermarket. These three anchors illustrate how geographic feedstock concentration and regulatory compliance capacity are separating scalable operators from marginal players.
| Leading Market Players |
|---|
| GS Yuasa International Ltd |
| Attero Recycling |
| GEM Co., Ltd. |
| Lohum Cleantech |
| ACE Green Recycling |
| Exide Industries Limited |
| Neometals Ltd |
| SK TES |
| Contemporary Amperex Technology Co., Limited |
| Others |
Value Chain & Pricing Dynamics
China's SAMR GB/T quality specifications gate both feedstock qualification and price premiums for recovered cathode materials, compressing margin pools for operators lacking integrated precursor capacity while rewarding verified carbon-intensity documentation. Electric vehicle OEM procurement teams exploit this bifurcation to extract supply security commitments through long-term offtake structures.
Pricing Analysis
Prior-generation pyrometallurgical routes command economy-tier pricing for lead-acid recovery, while current-generation hydrometallurgical lithium-ion processing captures standard-tier margins, and emerging direct cathode regeneration technologies secure premium positioning through reduced reagent intensity. Contract-based long-term offtake agreements dominate cathode precursor transactions, with price differentiation driven by carbon accounting verification and captive refiner co-location. Cost compression in standard-tier hydrometallurgical services is intensifying because MEE effluent compliance investments concentrate capacity among integrated chemical parks. Automotive OEMs demonstrate lowest price sensitivity, prioritizing supply security and verified provenance over unit economics.
Supply Chain Analysis
Port congestion across the Shanghai-Ningbo corridor elevates inbound logistics costs for black mass feedstock arriving from Southeast Asian collection networks, compressing margins for Jiangsu province operators without coastal warehouse positioning. Supply concentrates in China, South Korea, and Japan for lithium-ion cell manufacturing, with raw material dependencies spanning Australian spodumene, Indonesian nickel laterite, and DRC cobalt hydroxide. Single-source vulnerability in China's Jiangsu and Guangdong province clusters creates geographic concentration risk for formal feedstock allocation. Distribution runs through licensed chemical parks with shared wastewater infrastructure, excluding standalone operators from OEM procurement lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle OEM procurement consolidation is redistributing bargaining power toward buyers with volume commitment scale, fragmenting competitive positioning among recyclers competing for limited qualified supplier slots.
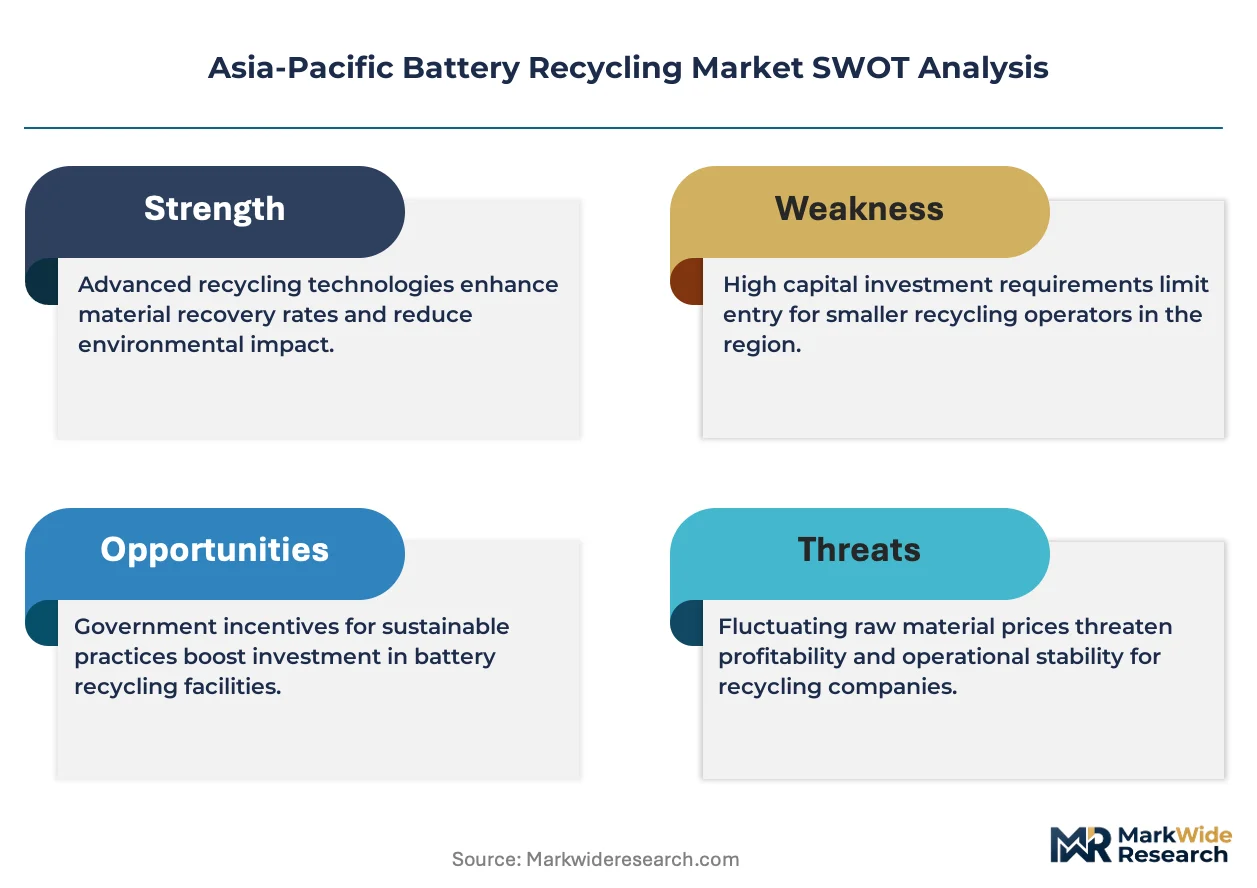
For Market Incumbents: Shield margin structures by deepening captive precursor offtake agreements with Jiangsu province chemical parks, while accelerating zero-liquid-discharge certification to preempt MEE enforcement escalation that threatens unlicensed capacity. Direct cathode regeneration pilots from South Korean cell manufacturers pose substitution risk to conventional hydrometallurgical flows. For New Entrants and Emerging Players: BIS certification fast-tracks for India's Maharashtra and Tamil Nadu industrial corridors unlock formal channel participation as CPCB extended producer responsibility mandates displace informal aggregator networks. Target Southeast Asia's Thailand and Indonesia EV assembly bases where collection infrastructure gaps create first-mover positioning for integrated recycler-refiner partnerships with domestic cell manufacturers. For Investors and Strategic Acquirers: China's dual carbon tracking system enforcement reshapes the acquisition landscape toward operators with verified carbon intensity data and coastal logistics networks. Five-to-ten year viability favors integrated refiner-recyclers with SAMR GB/T compliance and captive precursor capacity. Watch for feedstock diversion acceleration from informal collectors as MEE discharge standard enforcement intensifies across Guangdong province.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Cathode Regeneration Pilot Investment | South Korean cell manufacturers test lower-emission NCM recovery routes bypassing full elemental dissolution. |
| Zero-Liquid-Discharge Infrastructure Deployment | Jiangsu province chemical parks consolidate licensed capacity under MEE effluent discharge standards. |
| Urban Mining Digital Platform Development | Freight platforms connecting dismantlers with hydrometallurgical facilities compress logistics costs across China's industrial clusters. |
| Extended Producer Responsibility Compliance Investment | India's BIS and CPCB frameworks force formal channel development across fragmented automotive aftermarkets. |
| Integrated Recycler-Refiner Partnership Formation | Thailand and Indonesia EV assembly bases lack mature collection infrastructure, creating partnership opportunities with domestic cell manufacturers. |
Study Parameters
Operator-level perspectives from recycling plant managers, cathode precursor procurement leads at cell manufacturers, MEE compliance officers, and informal aggregator network coordinators anchored the qualitative base. Primary interview insights combined with secondary validation from SAMR GB/T standard filings, MEE discharge compliance databases, BIS certification registries, and customs trade data for black mass and recovered compounds. Bottom-up capacity modeling and top-down OEM procurement survey triangulation ensured segmentation consistency across chemistry types and service categories.
Sensitivity analysis tested feedstock availability scenarios, regulatory enforcement intensity variations, and technology substitution timelines across the projection horizon. Segmentation dimensions modeled include battery chemistry, recovery technology route, service type, end-use application, and provincial regulatory cluster. CAGRs derived from installed base retirement curves, EV penetration assumptions, and collection infrastructure development trajectories. Industry-specific forecast inputs span China's dual carbon policy implementation pace and India's extended producer responsibility compliance deadlines.
Underlying assumptions cover MEE enforcement consistency, SAMR quality specification adherence, and feedstock competition dynamics between refiners and recyclers, with deviation risk concentrated in informal collector diversion rates and direct recycling technology scale-up velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Power Battery Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market