
 EV Battery Reuse Market | 2026-2036
EV Battery Reuse Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Reuse Market Analysis
EU Battery Directive is decoupling compliance costs from virgin material dependence, raising the economic threshold for market entry. Tesla leverages its closed-loop collection infrastructure to dominate North American feedstock flows. Renault Group anchors European second-life capacity through vertically integrated remanufacturing partnerships. 4R Energy Corporation specializes in Nissan Leaf pack diagnostics, occupying a defensible niche in lithium-iron-phosphate refurbishment.
EV battery reuse recovers electrochemical cells from retired automotive traction packs, typically retaining 70-80% of original capacity, for redeployment in stationary storage or lower-power mobility. These systems extend useful service life by 5-15 years while avoiding raw material extraction. Energy Storage Systems leads application demand as utilities seek cost-competitive alternatives to new lithium-ion installations. Grid Stabilization represents the fastest-expanding segment, driven by frequency regulation contracts and renewable intermittency management. Lithium-ion technology dominates reuse volumes due to pack standardization and established state-of-health diagnostics, though Nickel-Metal Hydride retains niche relevance in hybrid vehicle circularity programs.
REACH mandates in Europe govern hazardous substance thresholds in repurposed cells, while the EU Battery Directive establishes recycled content quotas that reshape OEM procurement obligations. EPA hazardous waste classifications in the United States determine interstate transport permissions for end-of-life packs, directly affecting collection network economics. China's GB standards and dual carbon goals enforce traceability requirements that filter into export markets. Stakeholders must monitor how evolving extended producer responsibility frameworks alter liability allocation between automotive manufacturers and reuse service providers.
Market Dynamics
Binding storage procurement targets under Germany's national climate framework are forcing grid operators to absorb retired automotive packs faster than diagnostic capacity can scale, creating a structural bottleneck in feedstock qualification.
Growth Catalysts
- EU Battery Directive recycled content quotas:Mandatory thresholds for certified second-life feedstock are compelling OEMs to establish captive collection networks rather than rely on spot markets.
- Utility-scale frequency regulation contracts:Grid operators in markets with high renewable penetration are signing long-term offtake agreements for repurposed lithium-ion installations.
- State-of-health diagnostics automation:Machine-learning classification of cell degradation curves is collapsing pack grading costs from weeks to hours.
Market Restraints
- Cobalt and lithium price volatility:Input cost swings for cathode materials are eroding the cost advantage of second-life systems against new production during commodity spikes.
- China's GB standards traceability requirements:Export-market filtration through Chinese dual carbon enforcement is concentrating certified feedstock access within domestic remanufacturing chains.
- Cell-to-pack thermal runaway propagation:Uncontrolled failure cascades in densely packed second-life configurations are limiting energy density in stationary redeployment.
Strategic Opportunities
- India's CEA storage mandates:State-level renewable purchase obligations are opening procurement channels for cost-sensitive distribution companies without domestic cell manufacturing.
- Marine vessel electrification:Harbor craft and short-sea shipping operators are specifying repurposed automotive packs for propulsion systems with lower duty cycles.
- Blockchain-enabled provenance tracking:Immutable chain-of-custody records are satisfying EU Battery Directive compliance verification while reducing audit overhead.
Industry Challenges
- Battery management system firmware interoperability:Proprietary communication protocols from disparate OEMs are forcing costly controller replacement during pack reconfiguration.
- UL 1973 certification timelines:Third-party safety validation for stationary reuse applications is extending project delivery schedules by 8-14 months.
- Electrochemical technician scarcity:Specialized skills in cell-level diagnostics and thermal management design are concentrated among a limited pool of remanufacturing engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Reuse Market |
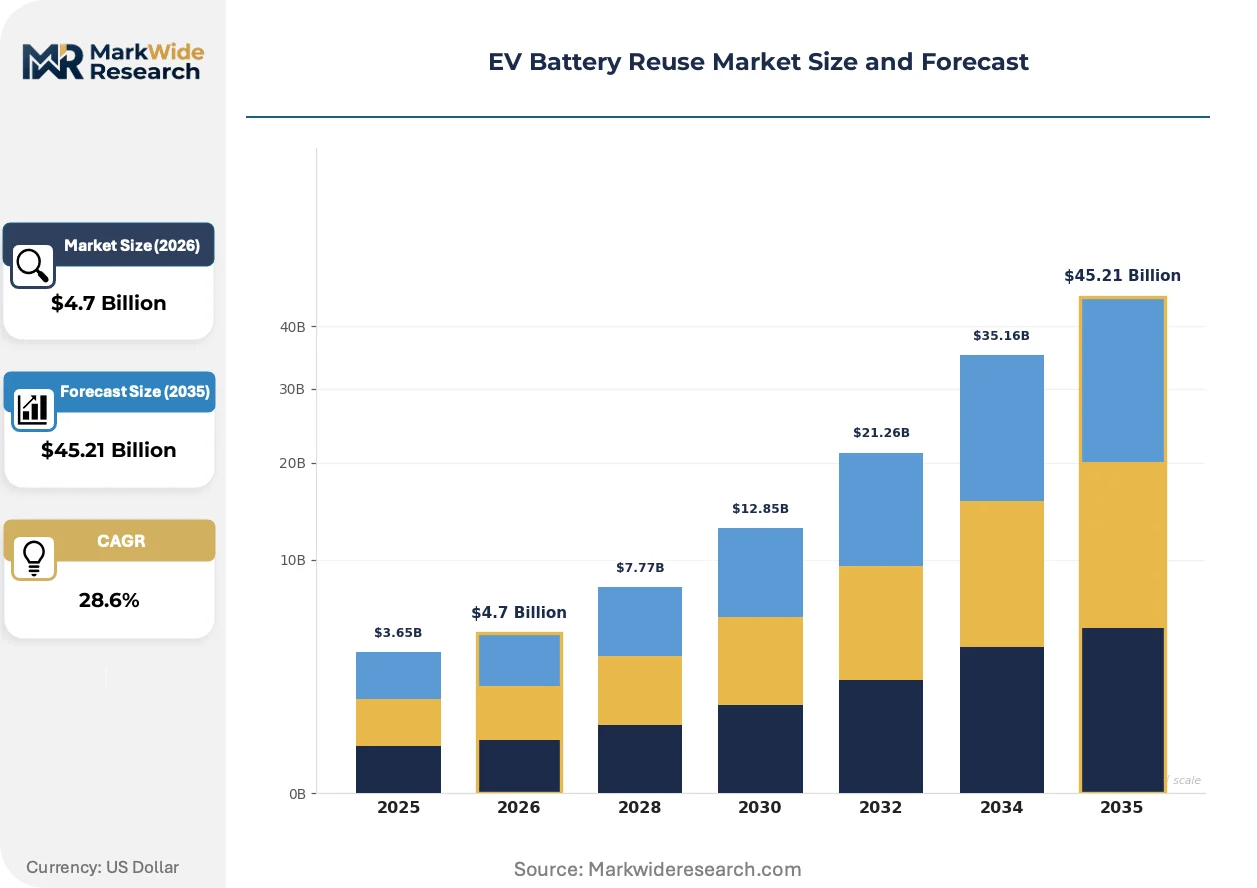
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Energy Storage Systems, Renewable Energy Integration, Second-Life Applications, Grid Stabilization Technology: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Flow Batteries End User: Utilities, Commercial Users, Residential Users, Automotive OEMs Distribution Channel: Direct Sales, Online Retail, Wholesalers, Partnerships |
| Companies Covered | 4R Energy Corporation, Connected Energy, RePurpose Energy, Renault Group, Tesla, Nissan Motor, Element Energy, Spiers New Technologies, Nuvation Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Reuse Market Emerging Trajectories
Diagnostic automation and modular system architecture are compressing the economics of pack redeployment while regulatory traceability requirements are reshaping competitive moats around data infrastructure rather than physical assets.
AI-driven electrochemical impedance spectroscopy is decentralizing cell grading from centralized laboratory facilities to containerized field units. Utilities with dispersed renewable generation portfolios are deploying these systems at collection hubs to accelerate feedstock velocity. The technology is decentralizing quality assurance costs across distributed networks rather than concentrating them in specialized remanufacturing centers.
REACH hazardous substance thresholds are tightening permissible heavy metal content in repurposed cells destined for European stationary installations. The regulation is forcing Asian pack processors to retrofit separation and purification lines to maintain market access. Grid-scale storage developers in Germany and the Netherlands are now specifying REACH-compliant feedstock certification as a contract precondition.
Long-term service agreements are displacing upfront equipment sales as the dominant commercial model for second-life storage deployments. Independent power producers are signing 10-15 year performance contracts that transfer operational risk to reuse service providers. This shift is most pronounced in California and Texas, where merchant storage operators prioritize balance-sheet treatment over capital ownership.
EV Battery Reuse Market Segmentation
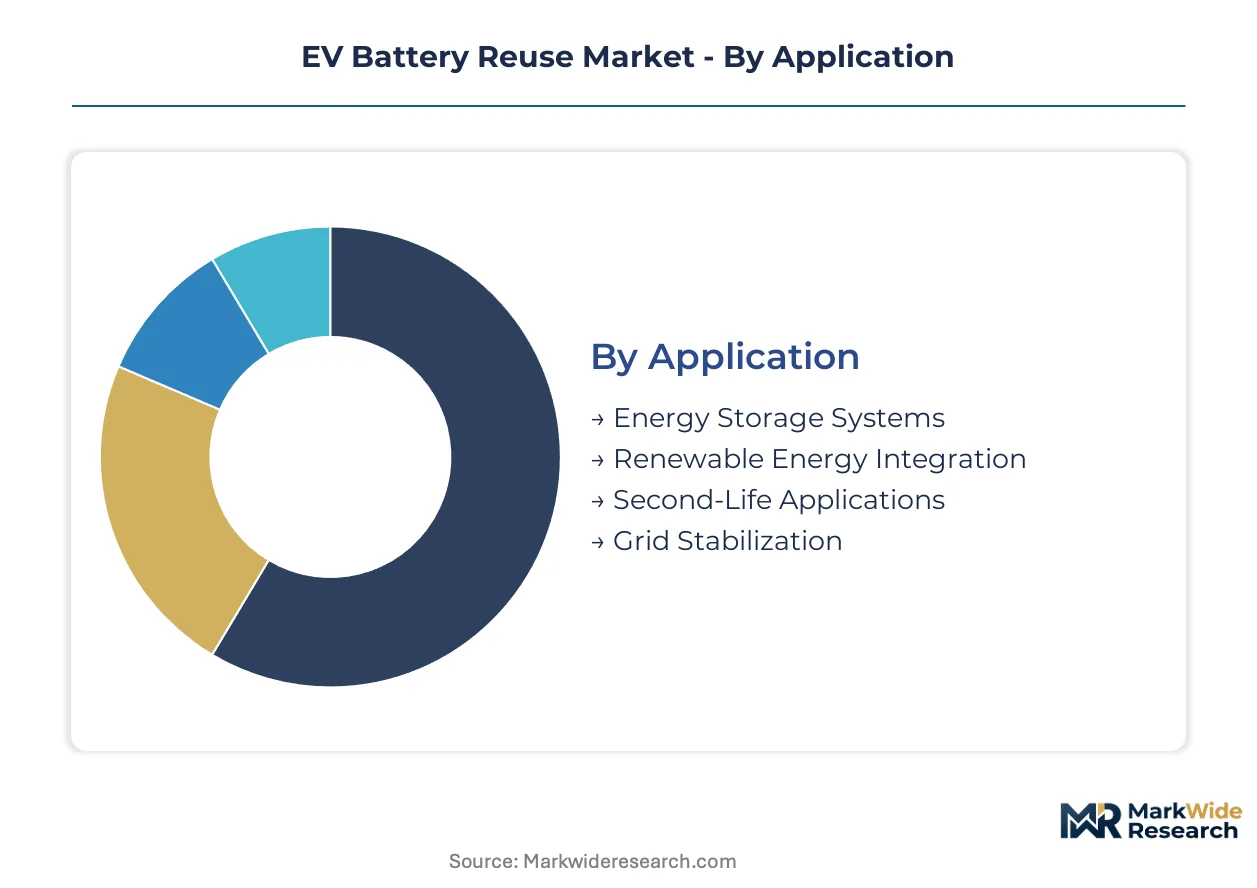
Segmentation in EV battery reuse reveals how value migrates from automotive retirement to stationary redeployment. Each category exposes different cost structures, certification requirements, and customer procurement behaviors that reshape competitive positioning across the value chain.
Application:
Standardization dominates utility-scale deployments while customization proliferates in niche industrial integrations.
- Energy Storage Systems:Grid-scale installations absorb the largest volume of qualified second-life packs. German utilities under binding climate procurement targets are signing long-term offtake agreements for repurposed lithium-ion arrays.
- Grid Stabilization:Frequency regulation contracts and renewable intermittency management drive demand for rapid-response battery assets. Texas and California merchant storage operators prioritize this segment for ancillary services revenue streams.
- Renewable Energy Integration:Solar and wind developers pair retired automotive cells with generation assets to smooth output curves.
- Second-Life Applications:Lower-power mobility and off-grid installations extend service life for packs below utility-grade standards.
Leading the category by volume: Energy Storage Systems. Expanding most quickly: Grid Stabilization.
Technology:
Pack standardization and diagnostic maturity separate high-volume reuse candidates from specialty chemistries.
- Lithium-ion:Standardized form factors and established state-of-health diagnostics enable automated grading at scale. Automotive OEMs concentrate feedstock collection around nickel-manganese-cobalt and lithium-iron-phosphate variants.
- Nickel-Metal Hydride:Hybrid vehicle circularity programs sustain niche refurbishment volumes. Toyota and Honda legacy fleet retirements supply dedicated remanufacturing lines in Japan and North America.
- Lead-Acid:Minimal overlap with automotive traction packs limits relevance in second-life value chains.
- Flow Batteries:Vanadium and zinc-bromide systems compete for long-duration storage applications outside automotive reuse streams.
Technology concentration: Lithium-ion commands feedstock flows. Steepest expansion trajectory: Flow Batteries in long-duration storage.
End User:
Procurement sophistication and contract duration separate institutional buyers from fragmented residential demand.
- Utilities:Centralized procurement teams negotiate multi-year performance contracts with certified reuse providers. German transmission system operators specify REACH-compliant feedstock under national storage mandates.
- Commercial Users:Industrial facilities and data centers seek behind-the-meter installations for peak shaving and backup power.
- Automotive OEMs:Captive collection networks supply vertically integrated remanufacturing operations to meet EU Battery Directive recycled content quotas.
- Residential Users:Distributed solar adopters drive small-scale demand through installer channels with limited standardization.
Customer hierarchy: Utilities anchor contract values. Gaining share fastest: Commercial Users seeking energy cost hedging.
Distribution Channel:
Channel selection reflects asset traceability requirements and project financing structures.
- Direct Sales:Large-scale utility and OEM procurement bypass intermediaries for chain-of-custody documentation. Blockchain-enabled provenance tracking satisfies EU Battery Directive compliance verification through this channel.
- Partnerships:Strategic alliances between automotive manufacturers and energy developers secure dedicated feedstock pipelines.
- Wholesalers:Regional distributors aggregate smaller commercial and residential demand with limited certification services.
- Online Retail:E-commerce platforms serve hobbyist and off-grid segments with minimal warranty coverage.
Channel dominance: Direct Sales captures institutional volumes. Climbing the fastest: Partnerships with long-term service agreement structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs the largest share of qualified second-life feedstock as grid operators race to meet binding storage procurement targets under the national climate framework.
Germany
Transmission system operators source repurposed automotive packs for frequency regulation and renewable intermittency management. The EU Battery Directive mandates recycled content thresholds that reshape OEM procurement obligations. Industrial clusters in North Rhine-Westphalia and Bavaria host diagnostic facilities that grade retired cells for utility-scale redeployment.
United States
Merchant storage operators in California and Texas sign long-term offtake agreements for second-life lithium-ion arrays. EPA hazardous waste classifications determine interstate transport permissions for end-of-life packs. The Pacific Northwest concentrates remanufacturing capacity where hydropower-rich grids seek cost-competitive storage alternatives.
China
Domestic remanufacturing chains capture certified feedstock under GB standards traceability requirements that filter into export markets. Dual carbon goals enforce documentation protocols across the value chain. The Yangtze River Delta anchors cell grading infrastructure that serves both domestic utilities and international battery service providers.
India
State-level renewable purchase obligations open procurement channels for cost-sensitive distribution companies without domestic cell manufacturing. Central Electricity Authority storage mandates accelerate demand for repurposed automotive packs. Gujarat and Karnataka concentrate project development activity where solar developers pair retired cells with generation assets.
Japan
Hybrid vehicle circularity programs sustain niche refurbishment volumes for nickel-metal hydride systems from legacy fleet retirements. METI guidelines shape extended producer responsibility frameworks that allocate liability between automotive manufacturers and reuse service providers. The Kansai region hosts specialized remanufacturing lines that process Toyota and Honda battery returns.
EV Battery Reuse Market Vendor Landscape
German producers anchor one tier of the competitive structure; Japanese specialists hold established positions in hybrid battery circularity. The market exhibits tiered concentration where automotive OEMs operate captive collection networks alongside independent remanufacturing service providers. Three archetypes dominate: vertically integrated automakers, dedicated battery diagnostics firms, and utility-facing energy storage developers. Strategic partnerships and long-term service agreements represent the dominant competitive moves as participants seek to lock in feedstock pipelines and offtake certainty.
Within the automotive OEM tier, Renault Group exemplifies European vertical integration through remanufacturing partnerships that secure EU Battery Directive compliance. Tesla anchors North American feedstock flows through closed-loop collection infrastructure. 4R Energy Corporation occupies a defensible specialist position in lithium-iron-phosphate refurbishment, representing the dedicated diagnostics archetype that serves specific battery chemistry segments.
| Leading Market Players |
|---|
| 4R Energy Corporation |
| Connected Energy |
| RePurpose Energy |
| Renault Group |
| Tesla |
| Nissan Motor |
| Element Energy |
| Spiers New Technologies |
| Nuvation Energy |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between UL 1973-validated utility arrays and uncertified commercial installations splits both pricing power and supply chain configuration across the EV battery reuse value chain. German grid operators pay premiums for REACH-compliant feedstock with full chain-of-custody documentation while Indian distribution companies absorb lower-grade packs without thermal propagation testing, compressing margins at the diagnostic tier.
Pricing Analysis
Volume throughput at the commodity tier runs against margin capture at the certified tier. Three-tier pricing structure across premium, standard, and economy levels reflects the gap between utility-scale offtake agreements with 10-15 year performance guarantees and spot-market transactions for ungraded cells. Pricing pressure stems from cobalt and lithium price volatility eroding second-life cost advantages against new production during commodity spikes. Commercial users in behind-the-meter applications exhibit highest price sensitivity while German transmission system operators prioritize certification compliance over unit economics.
Supply Chain Analysis
Electrochemical technician scarcity in Germany, China, and the United States constrains diagnostic capacity expansion faster than retired automotive pack flows accumulate. Feedstock draws from nickel-manganese-cobalt and lithium-iron-phosphate automotive retirements, with cell grading equipment and thermal management components as critical inputs. Single-source vulnerability concentrates in Chinese GB standards-certified processing lines that filter into export markets. Distribution runs through direct sales channels for institutional procurement and strategic partnerships for captive OEM feedstock pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into collection infrastructure and downstream energy storage development defines competitive positioning as players race to secure qualified feedstock and long-term offtake certainty.
For Market Incumbents: Hedge against feedstock competition from automotive OEM captive networks by locking exclusive collection agreements with fleet operators before regulatory thresholds tighten. Invest in automated state-of-health diagnostics to collapse grading costs and defend margin position against emerging AI-native entrants. Prioritize UL 1973 pre-certification of pack configurations to compress project delivery timelines that currently extend 8-14 months. For New Entrants and Emerging Players: EU Battery Directive recycled content quotas in Germany open a window for certified second-life feedstock aggregation services that incumbent automakers cannot scale internally. Target India's CEA storage mandates where state-level renewable purchase obligations create procurement channels for cost-sensitive distribution companies without domestic cell manufacturing. Pursue marine vessel electrification specifications as a go-to-market angle with lower duty cycle requirements and less stringent certification barriers than utility-scale deployments. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated battery diagnostics firms given automation catalysts collapsing pack grading costs from weeks to hours. Long-term viability favors specialists with proprietary electrochemical impedance spectroscopy capabilities and established OEM partnerships across the analysis window. Monitor machine-learning classification accuracy rates as the inflection indicator for which diagnostic platforms achieve scalable feedstock velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Diagnostic Scale-Up | Machine-learning cell grading collapses qualification timelines from weeks to hours for utilities. |
| Captive Collection Network Buildout | OEM-controlled feedstock pipelines satisfy EU Battery Directive recycled content mandates. |
| Long-Term Service Agreement Pivot | 10-15 year performance contracts transfer operational risk to reuse service providers. |
| Blockchain Provenance Integration | Immutable chain-of-custody records reduce EU Battery Directive compliance audit overhead. |
| Marine Electrification Partnership | Harbor craft operators specify repurposed automotive packs for lower-duty propulsion systems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with utility planning officers, remanufacturing engineers, automotive OEM sustainability leads, and grid operators provided qualitative calibration. EIA storage deployment databases, EU Battery Directive implementation reports, EPA hazardous waste classification records, and Chinese GB standards documentation supplied quantitative foundations. Bottom-up feedstock flow modeling triangulated against top-down market sizing across the projection horizon.
Data-stream reconciliation between automotive retirement forecasts and stationary storage demand projections shaped the analytical framework. Segmentation dimensions span application type, battery chemistry, end-user procurement sophistication, and distribution channel structure. CAGRs were derived from fitted growth curves against historical deployment trajectories. State-of-health diagnostic automation rates and EU recycled content threshold enforcement timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook by accelerating automotive pack retirement profiles. Forecasts reflect assumptions regarding regulatory enforcement consistency and commodity price stabilization. Material deviation in cobalt-lithium price spreads or EU Battery Directive penalty structures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Battery Scrap Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Prepaid Battery Recycling Market