
 Battery Recycling Process Quality and Purity Test Instruments Market | 2026-2036
Battery Recycling Process Quality and Purity Test Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Recycling Process Quality and Purity Test Instruments Market Insights
ISO 17025 laboratory accreditation is redrawing competitive boundaries for instrument suppliers serving battery recyclers. Bruker leverages its mass spectrometry heritage to anchor positions in European black mass analysis labs. Thermo Fisher Scientific dominates the North American recycling plant channel through its ICP-OES and XRF portfolio breadth.
Battery recycling process quality and purity test instruments encompass analytical systems measuring elemental composition, moisture, particle morphology, and electrochemical properties of recovered active materials at ppm-level detection thresholds; these instruments verify that recycled lithium, cobalt, and nickel meet re-manufacturing specifications for new cell production. Spectrometers command the largest installed base among instrument types due to their indispensability in elemental quantification of black mass and precursor salts. Chromatographs are gaining traction fastest in moisture and organic contaminant detection as dry-room standards tighten for cathode powder reuse.
The EU Battery Regulation and China's GB/T standards for recycled battery materials are mandating traceable purity documentation, forcing recyclers to upgrade from spot-check sampling to inline or near-line analytical loops. The US EPA and state-level hazardous waste rules add compliance layers for facilities handling electrolyte-contaminated feedstocks. Stakeholders must weigh capital deployment between multi-technique platforms and dedicated single-parameter analyzers as regional certification requirements diverge.
Market Dynamics
The EU Battery Regulation's recycled content mandates are compressing analytical verification timelines from weeks to hours, forcing recyclers to trade batch-based lab testing for inline spectrometry loops that operate at production-line speeds.
Growth Catalysts
- Black Mass Standardization:China's GB/T standards for recovered cathode materials are mandating ppm-level impurity documentation, compelling recyclers to deploy ICP-OES and XRF systems for every production batch.
- Cell-to-Cell Infrastructure Expansion:South Korea's battery OEMs are building captive recycling capacity, creating dedicated demand channels for multi-technique analytical platforms that verify nickel-cobalt-manganese ratios.
- Dry-Room Compliance Tightening:Moisture thresholds for reused cathode powders now require Karl Fischer titration and gas chromatography verification, accelerating chromatograph adoption in powder processing facilities.
Market Restraints
- Helium Supply Concentration:ICP-MS and certain GC-MS systems depend on helium carrier gas, with Qatar and the US controlling over 80 percent of global liquefaction capacity, exposing recyclers to price volatility and allocation risk.
- Reference Material Scarcity:Certified reference materials for black mass and precursor salt matrices remain limited to NIST and BAM inventories, creating calibration bottlenecks for new market entrants.
- Capital Intensity of Multi-Technique Platforms:Integrated XRF-ICP-MS systems require seven-figure capital deployment, excluding smaller recyclers from highest-precision certification tiers.
Strategic Opportunities
- Secondary Cities in China:Recycling capacity is dispersing from Shenzhen and Changzhou to interior provinces like Hunan and Jiangxi, creating greenfield instrument demand outside established analytical service clusters.
- Near-Line Automation:Robotic sample handling coupled with laser-induced breakdown spectroscopy enables real-time black mass sorting, compressing analytical turnaround from hours to minutes.
- US Inflation Reduction Act:Domestic content bonuses for battery materials are incentivizing North American recyclers to invest in ISO 17025-accredited labs to qualify for tax credits.
Industry Challenges
- Metallurgical Chemist Shortage:Operation of ICP-OES and XRF systems requires specialized training in matrix interference correction, with European technical universities producing fewer than 200 qualified graduates annually.
- Legacy LIMS Integration:Many recycling plants operate 15-year-old laboratory information management systems that lack API connectivity to modern spectrometer data streams, forcing expensive middleware development.
- Cross-Border Calibration Traceability:Recyclers serving multiple jurisdictions must maintain parallel calibration chains for EU Notified Bodies, China's CNAS, and US NVLAP, tripling quality system overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Recycling Process Quality and Purity Test Instruments Market |
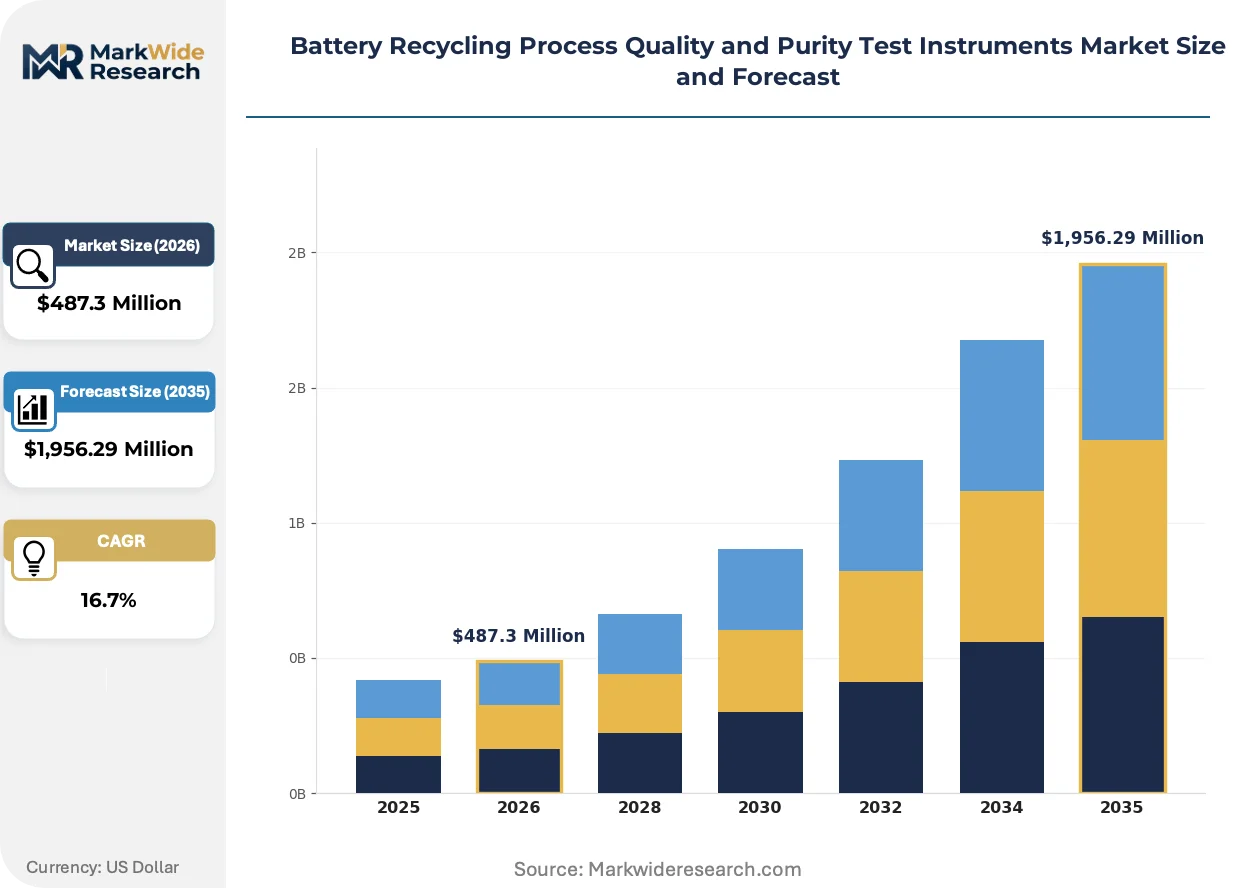
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,956.29 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Instrument Type: Spectrometers, Chromatographs, Microscopes, Conductivity Meters, Calorimeters Testing Parameter: Purity Level, Chemical Composition, Moisture Content, Particle Size, Conductivity Measurement Application: Material Sorting, Contamination Detection, Quality Assurance, Process Optimization, Safety Compliance End User: Recycling Plants, Material Recovery Facilities, Waste Management Companies, Research Laboratories, Quality Control Departments |
| Companies Covered | Thermo Fisher Scientific, Bruker, Hitachi High-Tech, Agilent Technologies, AMETEK SPECTRO, Malvern Panalytical, Metrohm, Shimadzu, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Recycling Process Quality and Purity Test Instruments Market Trends and Innovations
Portable and handheld analytical devices are penetrating battery recycling facilities, shifting quality verification from centralized labs to production-floor decision points. This spatial redistribution of analytical capability is compressing feedback loops and redefining supplier relationships.
Laser-induced breakdown spectroscopy (LIBS) is fragmenting the elemental analysis landscape for black mass characterization. Secondary recyclers in Germany and South Korea are adopting handheld LIBS units for rapid lithium and cobalt screening at receiving docks. The technology is fragmenting market share previously captured by benchtop XRF, particularly for mixed-chemistry feedstocks where speed outweighs precision.
REACH Annex XVII restrictions on nickel compounds are tightening occupational exposure limits in European recycling facilities. The regulation is mandating continuous air monitoring alongside material purity verification, driving demand for combined elemental and particulate analysis systems. German recyclers are responding by integrating ICP-MS with automated air sampling modules to satisfy dual compliance obligations.
Service contracting is displacing capital purchase for mid-scale recyclers facing utilization uncertainty. Analytical instrument vendors in North America are unbundling hardware ownership from operation, offering per-sample pricing with guaranteed uptime. This model is penetrating most rapidly among recyclers processing variable feedstock volumes from consumer electronics, where throughput fluctuates seasonally.
Battery Recycling Process Quality and Purity Test Instruments Market Segmentation
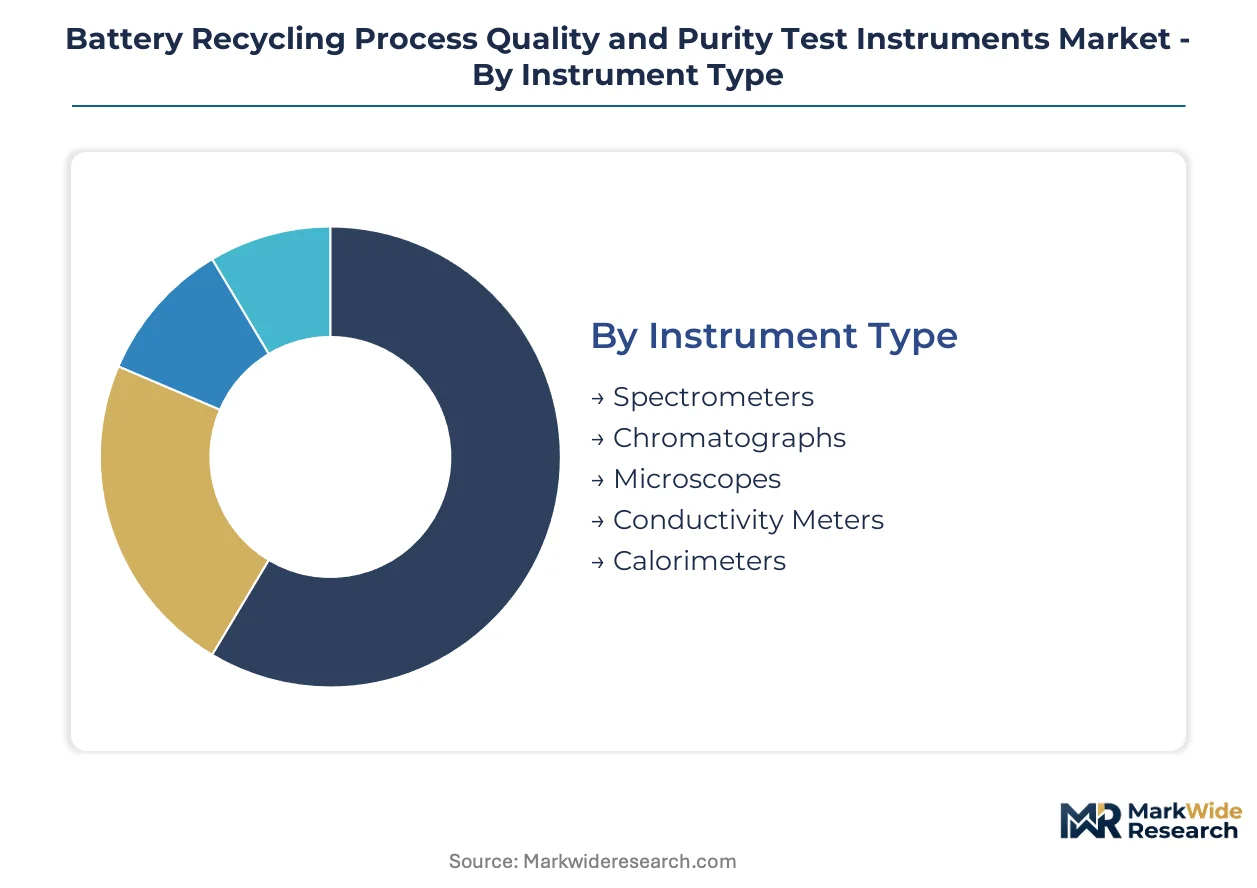
Segmentation reveals where instrument substitution pressures concentrate. Spectrometers face erosion from handheld LIBS units. Chromatographs compete against simpler Karl Fischer titration for moisture verification. Understanding these pressure gradients guides capital allocation and supplier positioning.
Instrument Type:
Substitution threats fragment most acutely here, with portable technologies displacing benchtop systems in black mass screening applications.
- Spectrometers:ICP-OES and XRF systems dominate elemental quantification of recovered lithium, cobalt, and nickel at ppm detection thresholds. Demand concentrates in German and Chinese black mass analysis labs where GB/T and REACH compliance mandates batch documentation. Bruker and Thermo Fisher anchor positions through ISO 17025-accredited service networks.
- Chromatographs:Gas and liquid chromatography systems detect organic contaminants and moisture in cathode precursor salts. South Korean cell-to-cell recycling facilities deploy these most intensively as dry-room standards tighten for NCM powder reuse.
- Microscopes:Scanning electron microscopy verifies particle morphology and coating integrity of recovered active materials.
- Conductivity Meters:Electrochemical impedance spectroscopy units measure ionic conductivity of recycled electrolyte fractions.
- Calorimeters:Differential scanning calorimetry assesses thermal stability of reprocessed cathode materials.
Spectrometers anchor the volume base while chromatographs gain share at the steepest rate.
Testing Parameter:
Cost tier differentiation separates premium multi-parameter platforms from dedicated single-analyte systems.
- Purity Level:ppm-level impurity verification for lithium, cobalt, and nickel requires ICP-MS or XRF systems with certified reference materials. Chinese recyclers in Hunan and Jiangxi provinces invest most aggressively here to meet GB/T documentation requirements.
- Chemical Composition:Nickel-cobalt-manganese ratio verification uses ICP-OES for precursor salt qualification.
- Moisture Content:Karl Fischer titration and gas chromatography quantify water content in hygroscopic cathode powders.
- Particle Size:Laser diffraction and dynamic light scattering characterize powder morphology for cell manufacturing compatibility.
- Conductivity Measurement:Electrochemical methods validate ionic transport properties of recycled electrolyte components.
Purity level testing commands the highest capital allocation while moisture content verification expands most quickly.
Application:
Application maturity varies sharply, with material sorting representing established demand and process optimization emerging as a greenfield segment.
- Material Sorting:LIBS and XRF systems classify mixed-chemistry feedstocks at receiving docks. German secondary recyclers deploy handheld units for rapid lithium and cobalt screening, compressing analytical turnaround from hours to minutes.
- Contamination Detection:ICP-MS identifies trace heavy metals and electrolyte residues in black mass streams.
- Quality Assurance:Batch release testing verifies compliance with OEM specifications for remanufacturing.
- Process Optimization:Inline spectrometry loops enable real-time hydrometallurgical adjustment, a capability South Korean captive recycling facilities pioneer.
- Safety Compliance:Continuous air monitoring for nickel particulates integrates with REACH Annex XVII occupational exposure limits.
Material sorting anchors installed capacity while process optimization climbs the fastest.
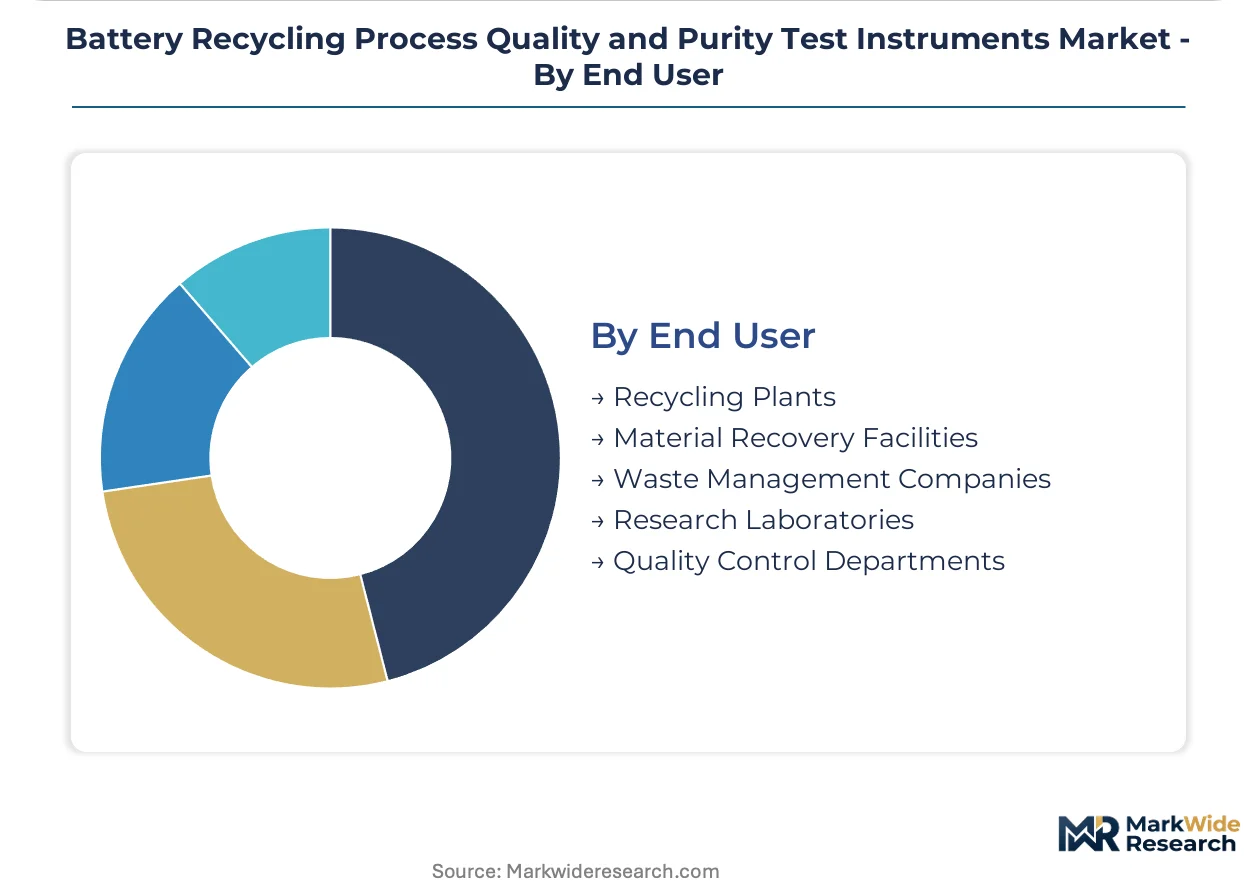
End User:
Customer type determines procurement modality, with large recycling plants favoring capital purchase and mid-scale facilities adopting service contracts.
- Recycling Plants:Integrated hydrometallurgical facilities in China and South Korea deploy multi-technique platforms for captive black mass processing. These operators require seven-figure capital deployment for XRF-ICP-MS systems.
- Material Recovery Facilities:Dedicated sorting operations concentrate feedstock supply for downstream refiners.
- Waste Management Companies:Diversified environmental service providers add battery streams to existing hazardous waste infrastructure.
- Research Laboratories:Universities and national institutes develop novel characterization methods for emerging battery chemistries.
- Quality Control Departments:OEM inbound inspection labs verify recycled content claims for regulatory compliance.
Recycling plants represent the dominant revenue channel while quality control departments emerge as the most rapidly expanding customer type.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Battery Regulation's recycled content mandates and China's GB/T standards for recovered cathode materials are redirecting capital toward analytical instrument fleets in battery recycling clusters across Germany, China, South Korea, Japan, and the United States.
China
GB/T documentation requirements for ppm-level impurity verification in black mass are compelling recyclers in Hunan and Jiangxi provinces to deploy ICP-OES and XRF systems at every production stage. SAMR enforcement of traceable purity documentation is compressing analytical timelines from batch testing to near-line loops. Changzhou and Shenzhen remain analytical service hubs, though capacity disperses to interior provinces.
Germany
REACH Annex XVII occupational exposure limits for nickel compounds mandate continuous air monitoring alongside material purity verification in recycling facilities. ECHA enforcement is driving integration of ICP-MS with automated air sampling modules. The Rhine-Ruhr industrial corridor hosts the densest concentration of black mass analysis labs serving European cathode material recovery.
South Korea
Cell-to-cell recycling infrastructure expansion by domestic battery OEMs creates captive demand for multi-technique analytical platforms verifying nickel-cobalt-manganese ratios. METI-aligned industrial policy supports ISO 17025 laboratory accreditation for material recovery facilities. The Busan-Ulsan coastal belt concentrates new hydrometallurgical recycling capacity with dedicated analytical instrument deployment.
Japan
JIS standards for recycled battery materials and METI circular economy targets are upgrading analytical verification protocols at legacy recycling facilities. Domestic battery manufacturers require ppm-level impurity documentation for remanufacturing acceptance. The Kansai region around Osaka maintains established analytical service networks serving precursor salt refiners.
United States
EPA hazardous waste rules for electrolyte-contaminated feedstocks layer compliance requirements atop state-level regulations in battery recycling facilities. The Inflation Reduction Act's domestic content bonuses incentivize ISO 17025-accredited lab investment to qualify for tax credits. Michigan and Ohio industrial corridors concentrate emerging recycling capacity with analytical instrument procurement.
Battery Recycling Process Quality and Purity Test Instruments Market Competitive Landscape
Listed analytical instrument leaders compete with private specialists across certification-tier positioning and service contracting modalities. The market structure consolidates around multi-technique platform providers while fragmenting into handheld and portable device specialists. Three archetypes dominate: diversified life science conglomerates with spectrometry heritage, dedicated materials characterization firms, and emerging portable technology developers. Competitive moves concentrate on service contracting unbundling and ISO 17025-accredited service network expansion.
Among diversified analytical platform providers, Thermo Fisher Scientific and Bruker exemplify contrasting geographic anchoring strategies. Thermo Fisher represents North American channel dominance through recycling plant direct relationships. Bruker occupies a position in European black mass analysis labs leveraging mass spectrometry heritage. PerkinElmer sits within the mid-tier service contracting tier where utilization-based pricing models penetrate most rapidly among variable-throughput recyclers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bruker |
| Hitachi High-Tech |
| Agilent Technologies |
| AMETEK SPECTRO |
| Malvern Panalytical |
| Metrohm |
| Shimadzu |
| PerkinElmer |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for helium carrier gas deliveries from Qatar and the US are compressing inventory buffers for ICP-MS operators while amplifying pricing power among suppliers with secured allocation contracts. This supply-chain tightness feeds directly into instrument pricing tiers, with multi-technique platforms commanding premium placement against single-parameter alternatives.
Pricing Analysis
Certification level (ISO 17025/GB/T-grade) creates the primary spread between analytical instrument tiers, with accredited systems commanding 40-60% premiums over non-certified equivalents. Three-tier pricing structure across premium, standard, and economy levels segments by detection threshold capability and service bundling intensity. Cost compression in the economy tier is intensifying because Chinese interior provinces are deploying stripped-down XRF units for basic black mass screening. Small-scale recyclers in variable-throughput segments exhibit highest price sensitivity, while South Korean captive facilities demonstrate lowest sensitivity due to OEM-backed capital deployment.
Supply Chain Analysis
Germany and the US anchor precision spectrometer manufacturing, while China dominates component fabrication and final assembly for mid-tier systems. Critical dependencies include germanium detectors for XRF systems, neodymium magnets for mass spectrometer ion optics, and helium liquefaction capacity concentrated in Qatar and the US. Single-source vulnerability in certified reference materials from NIST and BAM creates calibration bottlenecks that propagate through downstream pricing. Distribution runs through direct sales channels for large recycling plants and analytical service networks for mid-scale facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from handheld LIBS units fragmenting the black mass screening segment, requiring defensive repositioning around precision-tier certification and service contracting modalities.
For Market Incumbents: Compound ISO 17025-accredited service network density in China's Hunan and Jiangxi provinces to defend against portable LIBS erosion in basic screening applications. Deepen backward integration into certified reference material production to escape NIST/BAM supply constraints. Prioritize per-sample pricing contracts for mid-scale recyclers facing utilization uncertainty. For New Entrants and Emerging Players: Lead with robotic sample handling modules for near-line automation in German and South Korean black mass processing facilities, where analytical turnaround compression commands premium positioning. Target secondary Chinese cities dispersing from Changzhou and Shenzhen clusters. Pursue service-contract-only market penetration to bypass capital-intensity barriers for smaller recyclers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core materials characterization divisions amid portfolio rationalization. Five-to-ten-year viability hinges on regulatory enforcement continuity for ppm-level documentation mandates. Watch for SAMR acceleration of GB/T compliance timelines as the inflection signal for Chinese demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Accreditation | Positions suppliers for EU Battery Regulation and China's SAMR enforcement of traceable purity documentation. |
| Helium Supply Security Partnerships | Mitigates allocation risk for ICP-MS operators dependent on Qatar and US liquefaction capacity. |
| Near-Line Automation Deployment | Compresses analytical turnaround from hours to minutes in South Korean cell-to-cell recycling facilities. |
| Certified Reference Material Production | Resolves NIST/BAM inventory bottlenecks constraining new entrant calibration capabilities. |
| Per-Sample Service Contracting | Captures mid-scale recycler demand facing seasonal throughput fluctuation from consumer electronics feedstocks. |
Research Methodology
The analysis maps spectrometer, chromatograph, microscope, and portable device sub-sectors, each validated through plant managers at hydrometallurgical facilities, procurement leads at battery OEMs, and aftermarket service heads. Primary interviews with recycling plant engineers, laboratory accreditation auditors, and channel distribution partners combined with secondary validation against SAMR enforcement bulletins, ECHA REACH guidance documents, EPA hazardous waste rulings, and SEC filings from listed instrument manufacturers. Bottom-up instrument deployment counts triangulated against top-down market sizing from regional recycling capacity expansion.
Consistency checks validated volume and value outputs against external benchmarks including regional recycling plant commissioning announcements, laboratory accreditation registry growth, and helium consumption patterns from liquefaction export data. The analytical framework modeled instrument type, testing parameter, application maturity, and end-user procurement modality across the projection horizon. CAGRs derived from segment-specific adoption curves weighted by regulatory enforcement timelines and capital expenditure cycles in battery recycling infrastructure.
Forecasts assume regulatory continuity in EU Battery Regulation implementation, China's GB/T standard enforcement, and US IRA domestic content provisions; material policy shifts would require re-modeling. Specific risks include helium supply disruption, metallurgical chemist training pipeline constraints, and legacy LIMS integration failures. Recalibration cycles align with material shifts in SAMR enforcement intensity and EU delegated act publication timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Second-Life EV Battery Market
Battery Recycling
Battery Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Battery Scrap Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market