
 Lithium-Ion Battery Recycling Process Market | 2026-2036
Lithium-Ion Battery Recycling Process Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Recycling Process Market Insights
Battery-grade material purity specifications are rotating toward cathode-active-material-ready outputs rather than intermediate mixed salts. Umicore leverages its integrated refining and cathode precursor capacity to capture margin downstream of basic recovery. Redwood Materials anchors North American operations with closed-loop partnerships across major automakers. Li-Cycle Holdings Corp. differentiates through hub-and-spoke logistics that minimize transportation costs for spent batteries.
Lithium-ion battery recycling process encompasses mechanical shredding, thermal treatment, hydrometallurgical leaching, and electrochemical refining to recover cobalt, lithium, nickel, and manganese at purities exceeding battery manufacturing thresholds. The primary purpose is to reintroduce recovered materials into cathode production, reducing virgin mining dependence and associated supply chain risks. Hydrometallurgy leads process type adoption due to lower energy intensity and higher selectivity for lithium recovery compared to pyrometallurgical alternatives. Material recovery focused on cobalt and nickel commands premium margins, though lithium recovery is gaining structural importance as carbonate and hydroxide prices drive economics. End user demand from automotive OEMs outpaces other segments, driven by producer responsibility mandates and vertical integration into battery supply chains.
The EU Battery Regulation and ECHA REACH frameworks establish mandatory recycled content quotas and chemical safety standards that reshape process design and capital allocation across European recycling investments. EPA hazardous waste rules in the United States classify spent batteries under universal waste provisions, streamlining interstate collection while imposing strict emissions controls on smelting operations. China's MIIT and SAMR administer dual carbon goals and national standards that mandate traceability in recycled material flows. Stakeholders must monitor evolving cathode chemistry shifts, particularly sodium-ion and lithium-iron-phosphate growth, which alter recovery value pools and process technology requirements.
Market Dynamics
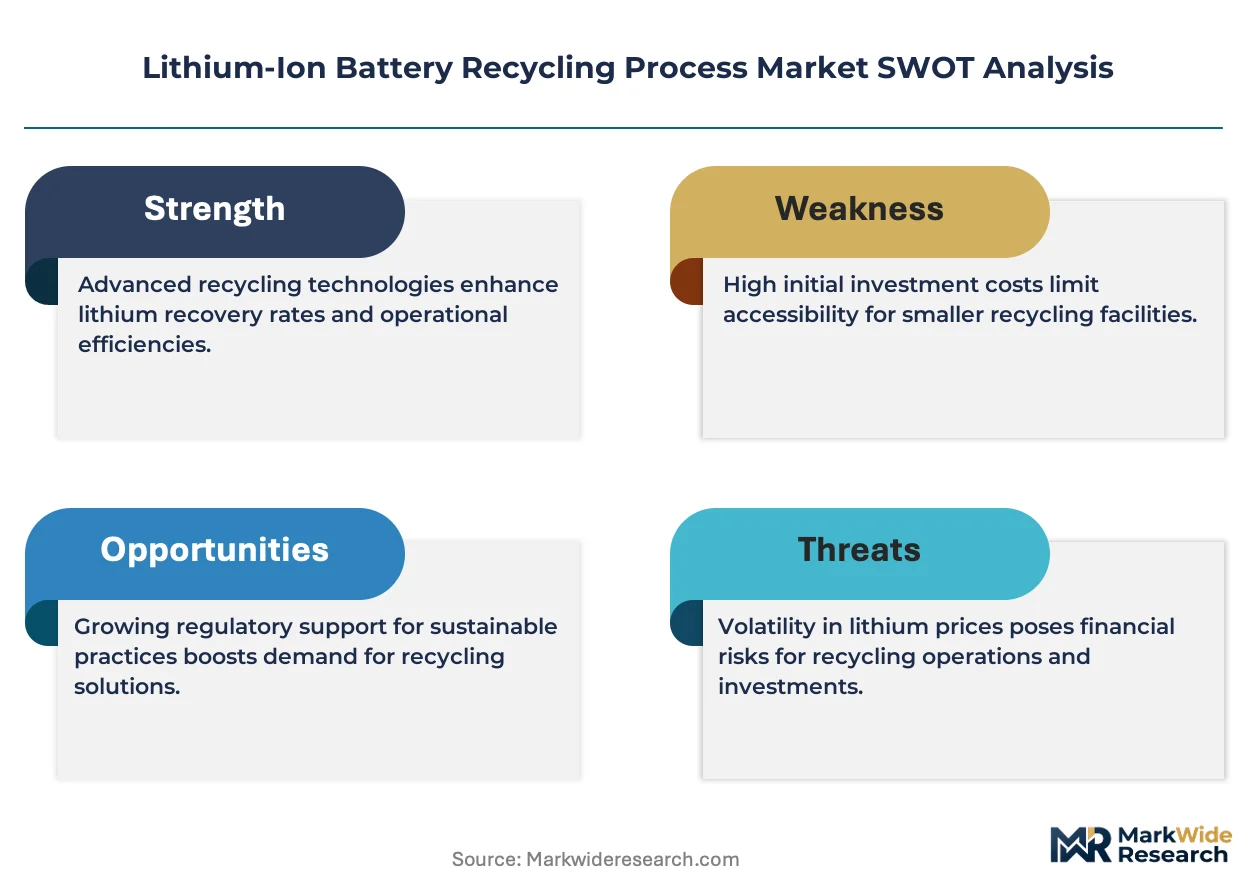
The EU Battery Regulation's recycled content mandates are forcing capital reallocation toward integrated hydrometallurgical capacity, compressing timelines for standalone mechanical preprocessing investments.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled content thresholds for lithium, cobalt, and nickel in new batteries drive capacity commitments across Germany, Poland, and France.
- Automotive OEM producer responsibility:Extended producer responsibility frameworks in California and New York require manufacturers to finance end-of-life collection and processing infrastructure.
- Direct recycling methods:Cathode regeneration technologies that preserve crystal structure reduce reprocessing energy by half compared to conventional hydrometallurgical routes.
Market Restraints
- Spent battery supply concentration:Collection networks cluster in China, creating feedstock access bottlenecks for European and North American processors.
- Lithium price volatility:Carbonate and hydroxide price swings below $15,000 per metric ton erode project economics for standalone lithium recovery lines.
- Sodium-ion substitution:CATL and BYD commercialization of sodium-ion cells for stationary storage removes cobalt and nickel from future feedstock pools.
Strategic Opportunities
- India's battery waste rules:The 2022 Battery Waste Management Rules mandate phased collection targets, creating first-mover advantages for hydrometallurgical investments near Chennai and Pune.
- Black mass tolling networks:Regional preprocessing hubs that mechanically shred batteries and produce standardized black mass output reduce transport costs for downstream refiners.
- IRA domestic content credits:Section 45X manufacturing credits apply to recycled critical minerals, improving project returns for US-based cathode precursor production.
Industry Challenges
- Electrochemical engineer scarcity:Specialized expertise in lithium-selective extraction and solvent extraction circuit design commands premium compensation, constraining expansion timelines.
- UN 38.3 certification complexity:Transport classification testing for damaged or defective batteries adds weeks to collection-to-processing logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Recycling Process Market |
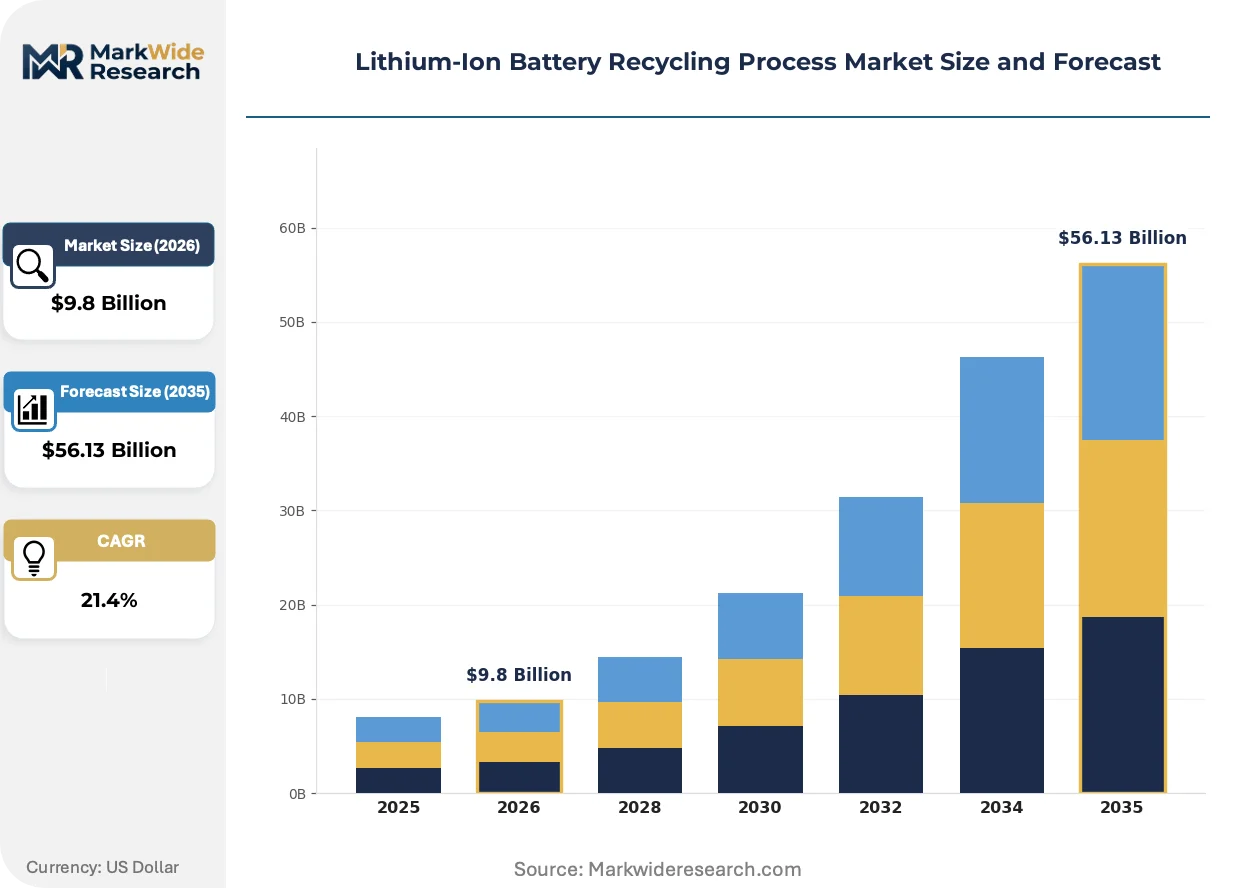
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $56.13 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Pyrometallurgy, Hydrometallurgy, Biochemical, Direct Recycling End User: Automotive OEMs, Consumer Electronics, Industrial Manufacturers, Energy Storage Providers Material Recovery: Cobalt, Lithium, Nickel, Manganese Service Type: Collection, Transportation, Processing, Refurbishment |
| Companies Covered | Umicore, Glencore, Li-Cycle Holdings Corp., GEM Co., Ltd., Redwood Materials, Cirba Solutions, American Battery Technology Company, Fortum, Retriev Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Recycling Process Market Trends and Innovations
Process intensification and digital traceability systems are compressing recovery yields while expanding the addressable feedstock pool beyond cylindrical cells to pouch and prismatic formats.
Direct cathode regeneration is miniaturizing the traditional recovery value chain by bypassing intermediate metal salt production. BMW and Volkswagen pilot programs in Germany are validating regenerated NMC811 cathode performance at pilot scale. This technology is compressing the margin capture structure, threatening standalone hydrometallurgical refiners that lack downstream cathode precursor integration.
REACH Article 33 disclosure requirements for recycled content origin are forcing batch-level traceability system investments across European processors. The ECHA SCIP database mandates component-level tracking for batteries placed on the EU market. Automotive OEMs are responding by requiring processor integration with their supply chain visibility platforms, favoring larger operators with IT infrastructure capacity.
Long-term offtake contracting is displacing spot market sales as the dominant procurement model for recovered materials. Battery cell manufacturers in South Korea and Japan are securing five- to ten-year supply agreements with European recyclers to meet Scope 3 emissions targets. This shift is most visible in Germany, where Umicore and BASF have structured contracts linking recovery volumes to specific OEM cathode precursor demand.
Lithium-Ion Battery Recycling Process Market Segmentation
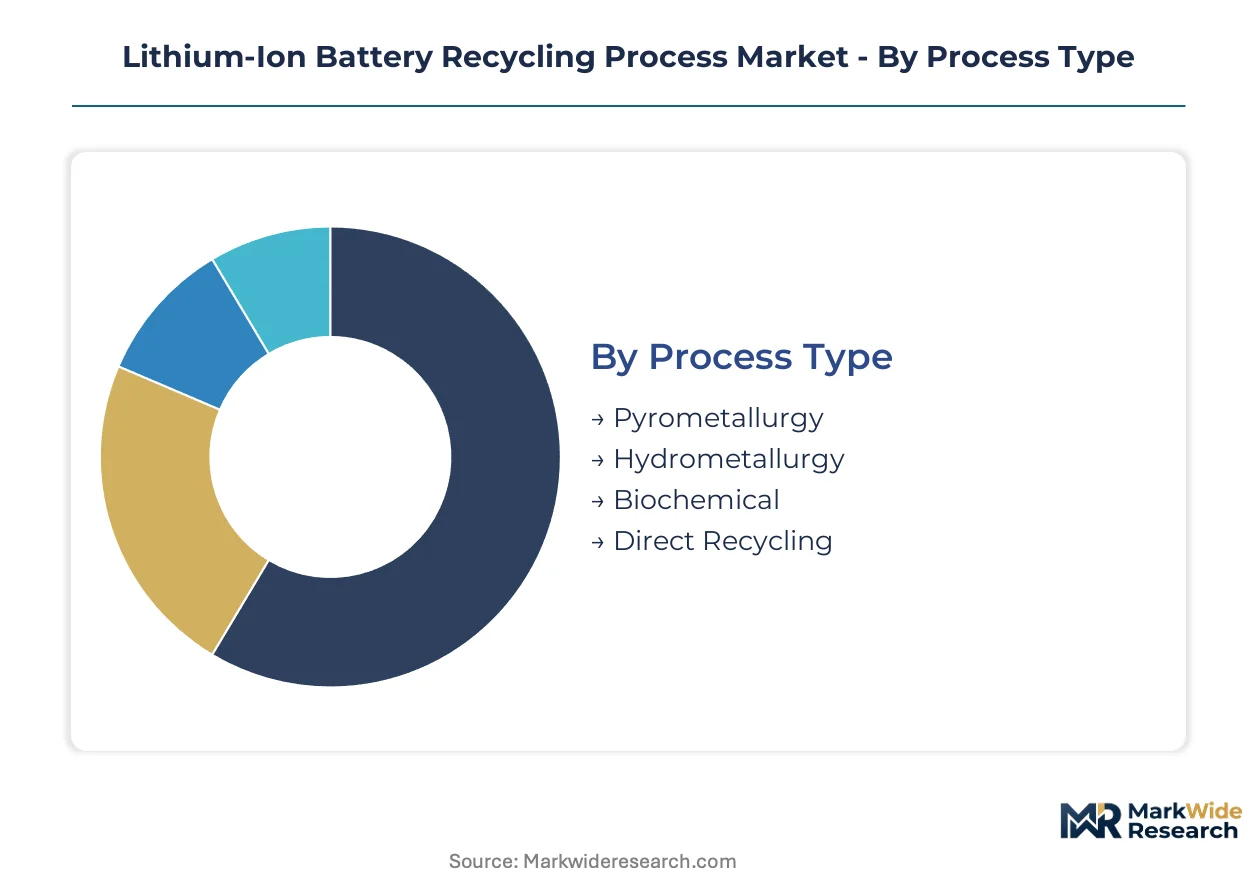
Process technology selection determines capital intensity and recovery yields across recycling operations. End-user concentration shapes service bundling requirements and contract structures. Material recovery priorities shift with cathode chemistry evolution and commodity price cycles.
Process Type:
Hydrometallurgy commands the widest margin pools due to lower energy intensity and superior lithium selectivity, though direct recycling threatens to compress downstream value capture.
- Hydrometallurgy:Acid leaching and solvent extraction circuits recover cobalt, lithium, nickel, and manganese at battery-grade purity. German industrial clusters around Dresden anchor capacity investments driven by EU Battery Regulation recycled content mandates. The technology's modular design allows staged capacity expansion.
- Direct Recycling:Cathode regeneration preserves crystal structure through relithiation, cutting reprocessing energy by half versus conventional routes. BMW and Volkswagen pilot programs in Germany validate regenerated NMC811 performance. This method threatens standalone refiners lacking precursor integration.
- Pyrometallurgy:High-temperature smelting recovers cobalt and nickel alloys but loses lithium to slag; EPA emissions controls constrain US deployment.
- Biochemical:Microbial leaching using acidophilic bacteria operates at ambient temperature and pressure; still pre-commercial at scale.
The dominant share belongs to Hydrometallurgy, while Direct Recycling is closing the gap fastest.
End User:
Automotive OEMs concentrate procurement volumes and drive vertical integration into recycling assets through producer responsibility mandates.
- Automotive OEMs:Extended producer responsibility frameworks in California and New York require manufacturers to finance collection infrastructure. Cell manufacturers in South Korea and Japan secure five- to ten-year offtake agreements with European recyclers to meet Scope 3 targets. Contract structures link recovery volumes to cathode precursor demand.
- Energy Storage Providers:Stationary battery deployments generate predictable end-of-life volumes with standardized cell formats. Sodium-ion substitution for grid storage applications removes cobalt and nickel from future feedstock pools, altering recovery economics.
- Consumer Electronics:Fragmented device ownership complicates collection; black mass tolling networks aggregate feedstock for downstream refiners.
- Industrial Manufacturers:Forklift and material handling equipment batteries offer concentrated, high-cobalt feedstock with established reverse logistics.
Automotive OEMs capture the largest contract value, though Energy Storage Providers are expanding most quickly as grid-scale deployments mature.
Material Recovery:
Cobalt and nickel recovery historically generated premium margins, but lithium extraction is gaining structural importance as carbonate and hydroxide price volatility reshapes project economics.
- Cobalt:Sulfate and metal forms command highest unit values; Democratic Republic of Congo supply concentration drives ethical sourcing premiums for recycled material.
- Lithium:Carbonate and hydroxide recovery from spent electrolyte and cathode active material requires selective precipitation or electrochemical separation. Price swings below $15,000 per metric ton erode standalone recovery line economics.
- Nickel:Sulfate for NMC cathodes recovered through solvent extraction; stainless steel contamination from cell casings complicates purification.
- Manganese:Lower-value recovery typically blended into steel production rather than battery-grade outputs.
Cobalt retains the highest margin per kilogram recovered, while Lithium is climbing the fastest as cathode chemistries shift toward higher nickel and lithium ratios.
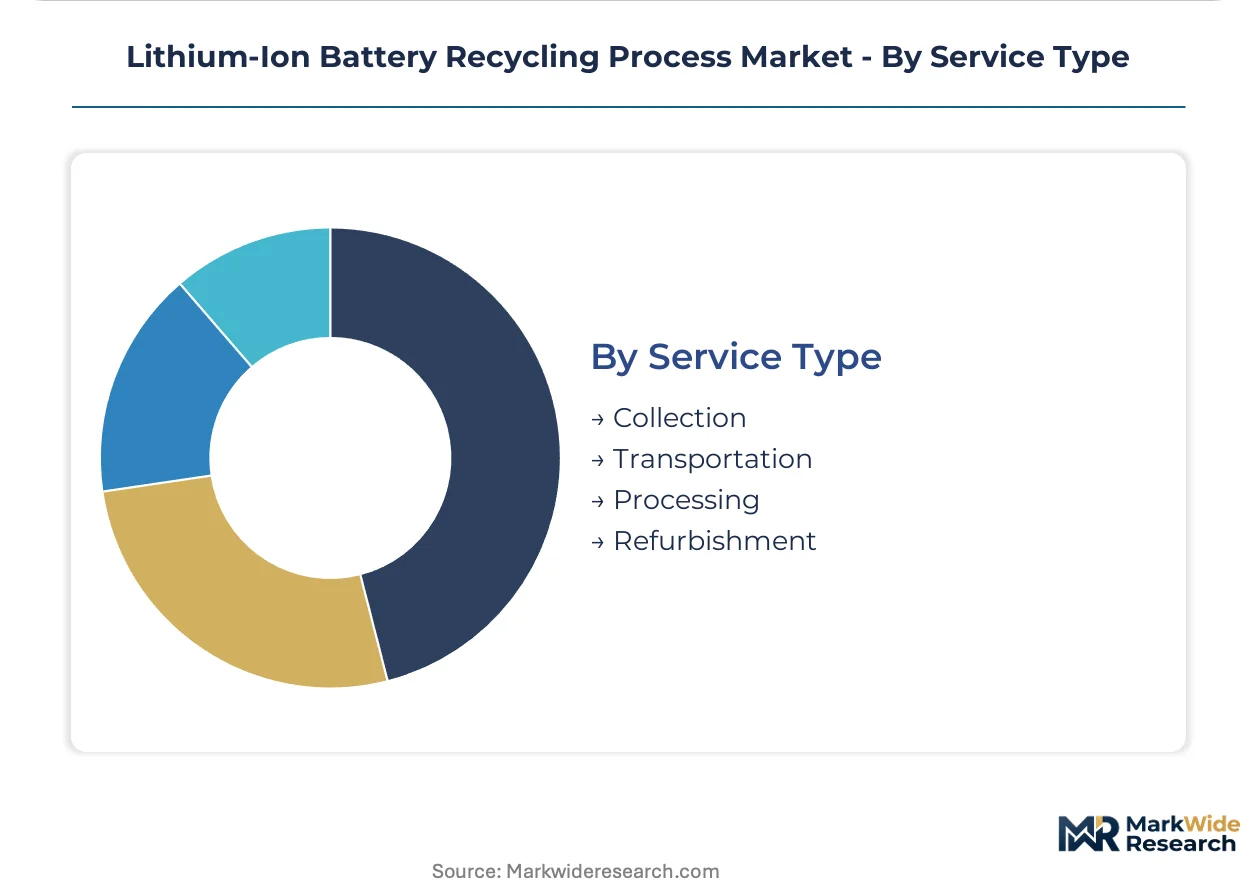
Service Type:
Transportation and processing capture the greatest value add, while collection margins compress under competitive pressure for feedstock access.
- Processing:Mechanical shredding, thermal treatment, hydrometallurgical leaching, and electrochemical refining constitute the core value creation stage. Hub-and-spoke logistics minimize transportation costs by preprocessing batteries into standardized black mass near collection points.
- Transportation:UN 38.3 certification complexity for damaged batteries extends collection-to-processing timelines. Interstate movement of spent batteries falls under EPA universal waste provisions in the United States, streamlining regulatory burden.
- Collection:Networks cluster in China, creating feedstock access bottlenecks for European and North American processors.
- Refurbishment:Second-life applications for electric vehicle batteries in stationary storage extend useful life before material recovery.
Processing commands the dominant revenue share, while Transportation is gaining share fastest as logistics optimization becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Germany absorb capacity at scale regardless of lithium price swings, while North American processors pause expansion when carbonate falls below $15,000 per metric ton. This elasticity gap is widening as IRA credits decouple US project economics from spot markets.
Germany
Automotive OEM procurement volumes concentrate around Dresden and Hamburg industrial clusters, where Umicore and BASF operate integrated cathode precursor facilities. The EU Battery Regulation mandates minimum recycled content thresholds for lithium, cobalt, and nickel, forcing capital commitments ahead of feedstock availability. Industrial parks near Hamburg host co-located shredding, hydrometallurgical refining, and precursor synthesis operations.
United States
IRA Section 45X manufacturing credits apply to recycled critical minerals, improving project returns for domestic cathode precursor production. EPA hazardous waste rules classify spent batteries under universal waste provisions, streamlining interstate collection while imposing strict emissions controls on smelting. Redwood Materials anchors Nevada operations with closed-loop partnerships across major automakers.
China
Collection networks cluster in Guangdong and Jiangsu provinces, creating feedstock access bottlenecks for European and North American processors. MIIT and SAMR administer dual carbon goals and national standards mandating traceability in recycled material flows. GEM Co., Ltd. and other domestic processors control black mass supply chains through vertical integration into battery manufacturing.
South Korea
Cell manufacturers secure five- to ten-year offtake agreements with European recyclers to meet Scope 3 emissions targets. The country's national industrial regulator enforces extended producer responsibility frameworks that finance collection infrastructure. Industrial complexes near Ulsan host cathode material plants sourcing recovered nickel and cobalt from overseas processors.
India
The 2022 Battery Waste Management Rules mandate phased collection targets, creating first-mover advantages for hydrometallurgical investments near Chennai and Pune. State-level industrial development corporations offer land and power subsidies for recycling parks in Tamil Nadu and Maharashtra. Feedstock access remains constrained by informal collection networks concentrated in Delhi and Mumbai.
Lithium-Ion Battery Recycling Process Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated refiners commanding margin downstream while logistics specialists minimize unit economics through hub-and-spoke networks. The market structures around three tiers: multinational materials conglomerates with cathode precursor capacity, pure-play recyclers scaling hydrometallurgical capacity, and regional preprocessing operators aggregating black mass. Strategic moves concentrate on backward integration into battery collection networks and forward integration into cathode active material production.
Among integrated materials specialists, Umicore and Glencore occupy positions spanning refining through precursor synthesis. Li-Cycle Holdings Corp. exemplifies the logistics-optimized archetype with hub-and-spoke infrastructure minimizing transportation costs. Redwood Materials represents the closed-loop partnership model anchoring regional supply security for automotive OEMs.
| Leading Market Players |
|---|
| Umicore |
| Glencore |
| Li-Cycle Holdings Corp. |
| GEM Co., Ltd. |
| Redwood Materials |
| Cirba Solutions |
| American Battery Technology Company |
| Fortum |
| Retriev Technologies |
| Others |
Pricing and Supply Chain Analysis
Sodium-ion chemistry substitution for grid storage applications simultaneously redraws feedstock geography toward China-centric collection networks and compresses recovery premiums for cobalt and nickel. This chemistry shift forces processors to reprice lithium extraction as the sole high-margin recovery stream while relocating supply chain investments toward lithium-dominant hydrometallurgical capacity.
Pricing Analysis
Long-term offtake contracting drives lifetime value more than spot sales, with five- to ten-year agreements linking recovery volumes to cathode precursor demand from South Korean and Japanese cell manufacturers. Price differentiation rests on battery-grade purity certification and geographic proximity to automotive OEM clusters, with German industrial parks commanding premiums over standalone refiners. Cost compression in standalone mechanical preprocessing is intensifying because EU Battery Regulation mandates compress timelines for basic shredding investments. Energy storage providers exhibit highest price sensitivity due to sodium-ion substitution removing cobalt and nickel from future feedstock pools, while automotive OEMs absorb premiums for Scope 3 compliance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European processors dependent on Chinese black mass imports. Supply concentrates in China, Germany, and South Korea, with collection networks clustering in Guangdong and Jiangsu provinces creating feedstock access bottlenecks for Western operators. Raw material dependencies center on spent NMC and LFP batteries, sulfuric acid for leaching circuits, and organic solvents for extraction. Single-source vulnerability runs through Chinese black mass supply chains controlled by vertically integrated domestic processors. Distribution runs through hub-and-spoke networks preprocessing batteries into standardized black mass near collection points before refining.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Black mass tolling services represent the fastest-expanding recurring-revenue layer, outpacing hardware margins as regional preprocessing hubs aggregate fragmented feedstock for downstream refiners. This service-attach model decouples processor economics from commodity price swings through fixed-fee tolling structures.
For Market Incumbents: Shield margin pools by deepening cathode precursor integration ahead of direct recycling technology maturation, which threatens standalone hydrometallurgical refiners lacking downstream synthesis capacity. Secure collection network control through backward integration into battery logistics, as feedstock access bottlenecks in China constrain European and North American expansion timelines. For New Entrants and Emerging Players: Second-life refurbishment services for electric vehicle batteries represent the most penetrable white-space target, with stationary storage applications extending useful life before material recovery. India's 2022 Battery Waste Management Rules create first-mover positioning near Chennai and Pune, where state-level subsidies support recycling park development. Pursue equipment-leasing partnerships with informal collection networks in Delhi and Mumbai to secure feedstock access without capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Capital is best deployed toward logistics-optimized pure-play recyclers with hub-and-spoke infrastructure and established automotive OEM partnerships, as these assets command premium valuations in consolidation scenarios. Long-term viability favors operators with demonstrated lithium-selective extraction expertise and solvent extraction circuit design capabilities. Watch sodium-ion commercialization rates by CATL and BYD as the critical inflection indicator for cobalt and nickel recovery value pool erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Integration | Captures margin downstream of basic recovery through in-house NMC and LFP synthesis capacity. |
| Hub-and-Spoke Network Expansion | Reduces transportation costs by preprocessing batteries into standardized black mass near collection points. |
| Direct Recycling Pilot Scale-Up | BMW and Volkswagen validation programs in Germany test regenerated NMC811 performance against virgin material. |
| Long-Term Offtake Contracting | Links recovery volumes to specific OEM cathode precursor demand across five- to ten-year agreements. |
| IRA Section 45X Credit Capture | Improves project returns for US-based recycled critical minerals and domestic precursor production. |
Research Methodology
Initial hypotheses were tested against primary input from hydrometallurgical plant managers, automotive OEM procurement leads, battery collection network operators, and cathode material R&D directors, then refined through secondary validation. Bottom-up and top-down triangulation combined regulatory filing analysis from EPA, ECHA, and MIIT with trade data on black mass flows, SEC disclosures from listed recyclers, and EU Battery Regulation implementation trackers. Field intelligence on process technology economics and offtake contract structures was cross-referenced against capacity announcement databases and industrial park development records.
Variance decomposition across the projection horizon isolates volume drivers from price assumptions, with segmentation modeled by process technology, end-user vertical, and material recovery priority. CAGRs were derived from installed capacity buildout trajectories, feedstock availability curves, and regulatory mandate implementation schedules. Industry-specific forecast inputs include cathode chemistry evolution toward higher nickel and lithium ratios, sodium-ion substitution rates for stationary storage, and IRA credit eligibility thresholds for domestic content.
Forecasts assume regulatory continuity in EU Battery Regulation recycled content mandates, EPA universal waste provisions, and China's dual carbon goals; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Global Lead-Acid Battery Scrap Market
Battery Recycling
Lithium Ion Battery Recovery Market
Battery Recycling
Lithium Ion Battery Recycling Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market