
 Lithium Ion Battery Recycling Market | 2026-2036
Lithium Ion Battery Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Ion Battery Recycling Market Intelligence
China's rapid build-out of domestic battery recycling capacity is reshaping the global flow of spent lithium-ion cells. This strategic move pressures operators in other regions to scale quickly. Redwood Materials specializes in recovering high-purity metals for direct reintegration into battery manufacturing. Li-Cycle competes using a novel hydrometallurgical spoke-and-hub model, while European leader Umicore leverages extensive metallurgical expertise across its operations.
Lithium-ion battery recycling encompasses processes to recover valuable materials from end-of-life batteries. These methods target critical metals like cobalt, nickel, lithium, and manganese, preventing them from entering landfills. The primary commercial purpose is to establish a secure, secondary supply chain for battery manufacturing. Hydrometallurgical technologies are gaining favor over pyrometallurgical methods for their higher efficiency, while the electric vehicles segment now generates the largest and fastest-growing stream of feedstock.
Regulatory frameworks create the foundational demand for recycled content and responsible disposal. The EU Green Deal, through its Battery Regulation, imposes strict collection and recovery targets. In parallel, China's MIIT enforces extended producer responsibility, holding manufacturers accountable for battery end-of-life. The ability to navigate these varied regional compliance schemes is now a core competency for all market participants.
Market Dynamics
The central dynamic is the collision between exponential feedstock growth from the electric vehicle sector and the urgent need for a circular economy, codified by regulations like the EU's Battery Regulation. This pressure compels the rapid industrialization of recycling technologies to create a secondary supply of critical battery metals.
Growth Catalysts
- Regulatory Mandates:Policies such as the EU Battery Regulation and China's extended producer responsibility schemes create non-negotiable demand for recycling by setting mandatory collection targets and minimum levels of recycled content in new batteries.
- Electric Vehicle Expansion:The automotive industry's shift to electrification generates a large, predictable, and growing stream of end-of-life batteries, providing the essential feedstock required to operate recycling facilities at an industrial scale.
- Hydrometallurgical Advances:Continuous improvements in hydrometallurgical processes are enabling higher recovery rates for valuable materials like cobalt, nickel, and lithium, improving the economic viability of recycling operations compared to pyrometallurgy.
Market Restraints
- High Capital Intensity:The construction of safe, environmentally compliant, and large-scale recycling facilities, whether using pyrometallurgical or hydrometallurgical methods, requires substantial upfront capital investment, creating a high barrier to entry.
- Logistical Complexity:Collecting, safely transporting, and storing large volumes of hazardous, end-of-life lithium-ion batteries is logistically complex and expensive, adding significant operational costs that can impact profitability.
- Feedstock Inconsistency:The wide diversity of battery chemistries (e.g., NMC, LFP, NCA) and formats from different manufacturers complicates the standardization of recycling processes, requiring flexible or dedicated lines that reduce operational efficiency.
Strategic Opportunities
- Geographic Expansion:Establishing recycling infrastructure in nascent electric vehicle markets, particularly in India and Southeast Asia, presents a significant first-mover advantage before local collection and processing networks mature.
- Stationary Storage Recycling:Developing specialized recycling channels for large-format batteries from grid-scale energy storage systems (ESS) opens a new, high-volume feedstock stream as early installations begin to reach their end of life.
- Battery Passport Integration:The development of digital battery passports, as mandated by the EU, creates an opportunity to provide data-driven recycling services, using battery-specific information to optimize sorting and material recovery processes.
Industry Challenges
- Safety and Compliance:Managing the inherent fire and chemical hazards of lithium-ion batteries requires rigorous safety protocols and specialized workforce training to comply with environmental and occupational health regulations from bodies like the EPA.
- Feedstock Flow Volatility:Recyclers face challenges in securing a consistent and predictable volume of spent batteries, as collection rates and the timing of vehicle scrappage can fluctuate, impacting plant utilization and production planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Ion Battery Recycling Market |
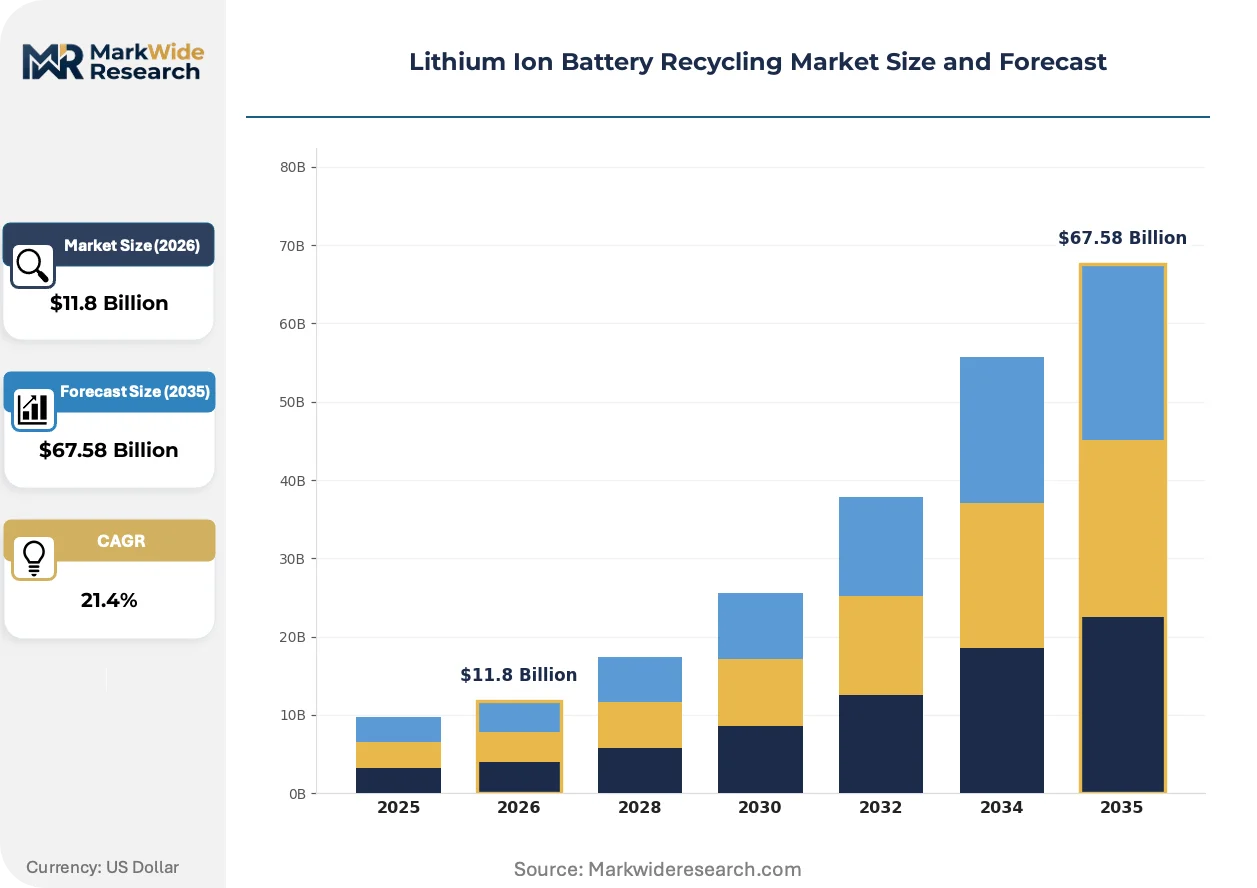
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $67.58 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Nickel Cobalt Aluminum, Lithium Manganese Oxide, Lithium Iron Phosphate, Nickel Manganese Cobalt, Lithium Titanate Technology: Pyrometallurgical, Hydrometallurgical, Direct Recycling, Mechanical, Biological End User Industry: Consumer Electronics, Electric Vehicles, Aerospace, Renewable Energy Storage, Defense Process Stage: Collection, Dismantling, Material Recovery, Refining, Waste Treatment |
| Companies Covered | Umicore, Glencore, Cirba Solutions, RecycLiCo Battery Materials, Contemporary Amperex Technology, GEM, Li-Cycle Holdings, Redwood Materials, Brunp Recycling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Ion Battery Recycling Market Strategic Shifts & Innovations
The industry's operational focus is shifting from basic material recovery to the creation of a truly circular supply chain. This evolution is defined by innovations that enable the direct re-introduction of recycled materials into high-value battery components, minimizing process steps and resource consumption.
Direct recycling represents a significant technological evolution, aiming to recover and rejuvenate cathode materials without breaking them down into their constituent elemental metals. Battery manufacturers are actively piloting these methods in partnership with recyclers to lower the carbon footprint and cost of cathode production. The industry's technological trajectory is migrating from recovering simple metallic salts to regenerating complex, specification-grade cathode active materials for direct reuse in new cells.
Regulatory frameworks are directly incentivizing regionalized supply chains. The US Inflation Reduction Act (IRA), for example, provides significant consumer tax credits for electric vehicles whose batteries contain a minimum percentage of critical minerals sourced from recycling facilities in North America. This policy is forcing automakers to secure domestic recycling capacity to ensure their vehicles qualify. The passenger EV segment is most affected, with manufacturers now establishing long-term offtake agreements with North American recyclers.
Automakers are fundamentally altering their procurement of recycling services by moving from transactional, end-of-life disposal contracts to strategic, long-term partnerships. This model often involves joint ventures or dedicated offtake agreements that guarantee the automaker a closed-loop supply of critical materials like cobalt and nickel recovered from their own manufacturing scrap and end-of-life batteries. This collaborative approach is most visible in Europe and North America, where EV manufacturing is scaling most rapidly.
Lithium Ion Battery Recycling Market Segmentation
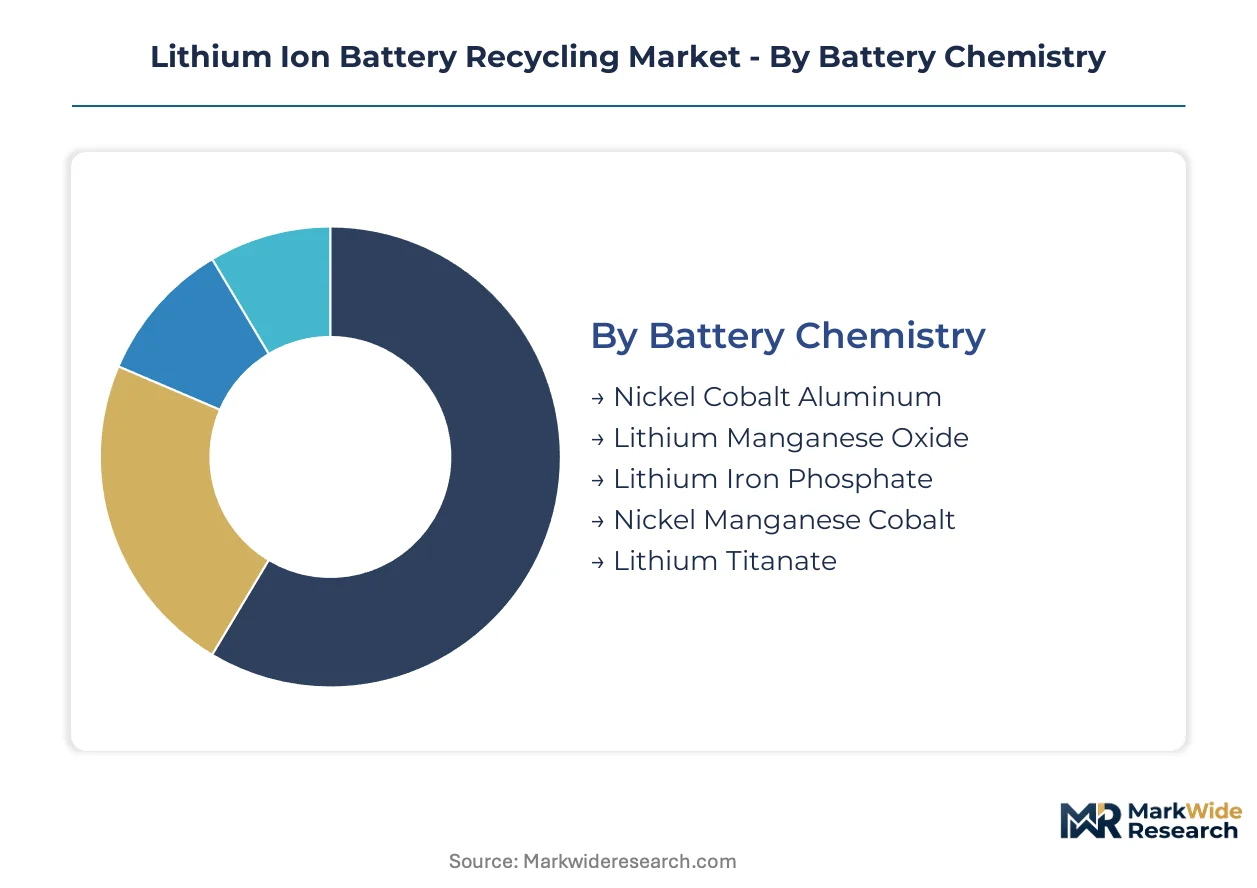
Market segmentation provides a structured view of the lithium-ion battery recycling ecosystem, highlighting critical variations in material composition, processing methodologies, and end-use applications. Understanding these distinctions is essential for strategic investment and for developing targeted recycling solutions across the value chain.
Battery Chemistry:
The use-case spectrum for lithium-ion batteries directly influences the chemical compositions requiring specialized recycling approaches.
- Nickel Manganese Cobalt:These chemistries offer high energy density, making them prevalent in electric vehicle applications. Recovery processes prioritize nickel, cobalt, and lithium, which represent significant economic value for reintegration into new battery production.
- Lithium Iron Phosphate:Characterized by thermal stability and a longer cycle life, LFP batteries are increasingly used in stationary energy storage systems and some electric vehicle models. Recycling focuses on recovering lithium and iron, often requiring different processing parameters due to the absence of cobalt and nickel.
- Nickel Cobalt Aluminum:This chemistry provides high power and energy density, commonly found in high-performance electric vehicles and power tools. Recycling efforts concentrate on efficiently extracting nickel, cobalt, and aluminum.
- Lithium Manganese Oxide:LMO batteries offer good power capability and safety, often used in medical devices and some electric bikes. Material recovery targets lithium and manganese.
- Lithium Titanate:Known for its rapid charging capabilities and long cycle life, LTO is found in specialized applications like electric buses and industrial equipment. Recycling processes extract lithium and titanium compounds.
Established volume favors Nickel Manganese Cobalt; emerging adoption favors Lithium Iron Phosphate.
Technology:
Technological maturity dictates processing efficiency and material purity, shaping investment decisions across the recycling value chain.
- Hydrometallurgical:This method uses aqueous solutions to selectively leach and separate valuable metals from shredded battery materials. Hydrometallurgy offers higher recovery rates and purer end-products, making it economically attractive for producing battery-grade precursors.
- Direct Recycling:An innovative approach that aims to restore cathode materials to their original state without completely breaking down their chemical structure. Direct recycling minimizes energy consumption and maintains the complex crystalline structure of cathode materials, enabling their direct reuse in new batteries.
- Pyrometallurgical:This high-temperature process melts batteries to recover metals, typically producing metal alloys. Pyrometallurgy is energy-intensive and often results in lower recovery rates for lithium and other volatile elements.
- Mechanical:Involves physical processes like shredding, crushing, and sieving to separate different components of the battery. Mechanical pre-treatment reduces battery volume and prepares materials for subsequent chemical processing.
- Biological:Utilizes microorganisms or their byproducts to extract metals from battery waste. Biological methods are still largely in the research and development phase, offering a potentially environmentally friendly alternative.
Efficiency gains drive investment in Hydrometallurgical processes, while sustainability goals propel Direct Recycling methods.
End User Industry:
The varied applications of lithium-ion batteries create distinct feedstock streams with unique volume and handling requirements.
- Electric Vehicles:This segment generates the largest and fastest-growing stream of end-of-life batteries, driven by global electrification mandates. Recycling focuses on high-value materials like nickel, cobalt, and lithium.
- Renewable Energy Storage:Grid-scale battery storage systems contribute large-format batteries with varying chemistries as early installations reach end-of-life. These systems present opportunities for large-volume material recovery.
- Consumer Electronics:Small-format batteries from devices like smartphones, laptops, and power tools represent a diverse but fragmented feedstock. Collection and sorting present logistical challenges for this segment.
- Aerospace:Specialized, high-performance batteries from aircraft and drones require rigorous safety protocols during handling and recycling. Material recovery focuses on critical metals for high-reliability applications.
- Defense:Military applications utilize robust and often custom-designed lithium-ion batteries. Recycling processes must adhere to strict security and material traceability requirements.
High-volume applications define current market demand; specialized sectors offer niche opportunities.
Process Stage:
Value addition occurs across multiple stages, from initial battery handling to the final purification of critical materials.
- Material Recovery:This stage involves the chemical or physical extraction of valuable metals from processed battery waste. Material recovery is central to creating a secondary supply chain for battery manufacturing.
- Refining:Purifies the extracted metals to battery-grade specifications, making them suitable for direct reintegration into new battery components. Refining ensures the quality and performance of recycled materials.
- Collection:Involves gathering end-of-life batteries from various sources, including consumers, automotive service centers, and industrial facilities. Effective collection networks are crucial for securing consistent feedstock.
- Dismantling:Manually or semi-automatically disassembling battery packs into modules and individual cells. Dismantling is critical for safety and to separate components for efficient processing.
- Waste Treatment:Manages the non-recoverable byproducts and hazardous waste generated during the recycling process. Responsible waste treatment ensures environmental compliance and minimizes ecological impact.
Upstream processes ensure feedstock availability; downstream stages dictate material quality and market value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive global shipping lanes underpin the movement of both spent lithium-ion batteries and recovered materials across continents. These established trade routes enable the concentration of processing capacity while supporting the distribution of recycled metals. Regional disparities in regulatory frameworks and feedstock availability shape the development of localized recycling ecosystems.
China
China's robust domestic battery manufacturing infrastructure drives significant demand for recycled materials. The Ministry of Industry and Information Technology (MIIT) enforces extended producer responsibility schemes, mandating manufacturers to manage end-of-life batteries. Industrial clusters in the Yangtze River Delta and Shenzhen are actively expanding recycling facilities to meet this internal demand.
United States
The expanding electric vehicle market in the United States generates a substantial feedstock stream for battery recycling. The Inflation Reduction Act (IRA) provides significant incentives for domestic processing and critical mineral recovery. Nevada, home to Redwood Materials, is emerging as a key hub for large-scale battery recycling and material re-manufacturing.
Germany
Germany's prominent automotive industry and commitment to the EU Green Deal fuel demand for circular battery materials. The EU Battery Regulation sets ambitious collection and recovery targets for all battery types. Baden-Württemberg and Saxony host significant automotive R&D and manufacturing, fostering localized recycling initiatives.
South Korea
South Korea's advanced battery manufacturing sector creates a continuous need for high-purity recycled metals. The Ministry of Environment actively promotes battery recycling and resource circulation policies. Major industrial zones like Ulsan and Gyeonggi Province are developing specialized facilities for processing battery production scrap and end-of-life cells.
Lithium Ion Battery Recycling Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the lithium-ion battery recycling value chain. The market features a tiered structure, with large-scale processors alongside niche technology providers. Strategic archetypes include integrated recyclers focused on closed-loop solutions, technology licensors advancing specific recovery methods, and specialized material refiners. Capacity expansion and strategic partnerships are dominant competitive moves, driven by the need to secure feedstock and meet regulatory demands.
Specialists in advanced material recovery, such as Umicore, exemplify established metallurgical expertise across diverse battery chemistries, providing high-purity materials. Li-Cycle Holdings represents a novel hydrometallurgical approach, leveraging its spoke-and-hub model to process black mass efficiently across multiple North American and European locations. Meanwhile, Redwood Materials anchors a vertically integrated recycling and material re-manufacturing strategy, particularly focusing on the North American electric vehicle ecosystem. These companies are actively shaping the industry's technological and operational benchmarks through their distinct business models and regional expansion efforts.
| Leading Market Players |
|---|
| Umicore |
| Glencore |
| Cirba Solutions |
| RecycLiCo Battery Materials |
| Contemporary Amperex Technology |
| GEM |
| Li-Cycle Holdings |
| Redwood Materials |
| Brunp Recycling |
| Others |
Cost & Logistics Intelligence
Trans-continental shipping lanes, essential for moving spent batteries and recovered materials, introduce significant cost dynamics influencing supply concentration and downstream price differentiation. This market's supply chain is evolving rapidly, driven by both technological advancements and stringent regulatory pressures.
Pricing Analysis
Volume-discount tiering structures characterize pricing for recycled battery materials, reflecting processing scale and purity levels. Price differentiation stems from the quality grade of recovered materials, ensuring suitability for battery-grade precursors, and the volume scale of feedstock provided by suppliers. Pricing softness reflects volatility in virgin metal prices, creating pressure on recyclers' margins. Automakers, driven by mandated recycled content targets, exhibit the least price sensitivity, prioritizing secure supply chains over marginal cost savings.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming more common, supporting the high capital intensity of recycling operations. Geographic supply concentrates in China, which processes a large volume of spent cells, while North America and Europe rapidly build out new facilities. The supply chain relies on spent lithium-ion batteries as its primary raw material, with critical metals like cobalt and nickel as key outputs. Feedstock inconsistency, due to diverse battery chemistries, represents a structural risk. Distribution runs through direct sales to battery manufacturers, often via long-term offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium-ion battery recycling market presents a fragmentation opportunity, as the accelerating shift to electric vehicles creates diverse feedstock streams demanding specialized recycling solutions.
For Market Incumbents: Harden core hydrometallurgical processing capabilities to achieve higher recovery rates for critical metals. Secure long-term feedstock agreements with major automotive OEMs and stationary storage providers to mitigate feedstock flow volatility. Invest in capacity addition in North America and Europe, aligning with regional regulatory incentives. This strategy counters the threat posed by emerging direct recycling technologies and ensures compliance with evolving environmental standards.
For New Entrants and Emerging Players: Pursue specialized recycling channels for lithium iron phosphate (LFP) batteries, which represent a rapidly expanding segment in stationary storage and certain EV models. Target nascent EV markets in India and Southeast Asia, establishing early collection and processing networks before established players dominate. A data-driven recycling service, leveraging digital battery passports for optimized sorting, offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Specialized hydrometallurgical processors with proven high-purity recovery capabilities offer long-term viability within the critical metals supply chain over the next decade. These firms contribute to a circular economy for battery manufacturing. Acquire technology licensors advancing direct recycling methods that reduce energy consumption and preserve cathode structures. Successful commercialization of direct recycling at scale represents a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Long-Term Offtake Agreements | Guarantees consistent feedstock volume for recyclers and stable material supply for battery manufacturers. |
| Invest in Hydrometallurgical R&D | Improves recovery efficiency and purity of battery-grade metals like lithium and nickel. |
| Expand Processing Capacity in North America | Leverages the US Inflation Reduction Act incentives and addresses regional EV market growth. |
| Develop LFP-Specific Recycling Lines | Captures value from the growing segment of lithium iron phosphate batteries in storage applications. |
| Integrate Battery Passport Data | Optimizes sorting and material recovery processes, enhancing overall operational efficiency for recyclers. |
Research Approach
Desk research of industry association reports, government environmental agency publications, and academic journals preceded structured interviews with battery manufacturers, recycling plant operators, automotive OEMs, and regulatory officials. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation methods were applied to reconcile disparate data points.
The forecast framework held regulatory mandates and technological trajectories fixed while varying adoption rates for electric vehicles and energy storage systems across the analysis window. Segmentation dimensions modeled included battery chemistry, processing technology, end-user industry, process stage, and regional market. Compound annual growth rates were derived from historical growth patterns and projected market expansion, incorporating industry-specific forecast inputs like EV adoption rates and battery material prices.
Sensitivities concentrate around geopolitical shifts impacting raw material access and unexpected technological breakthroughs in battery chemistry. Forecasts reflect assumptions documented through extensive research and expert consultation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
EV Battery Reuse Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market