
 China Oil and Gas Downstream Market | 2026-2036
China Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
China Oil and Gas Downstream Market Outlook
Project finance tied to green bond issuance is rewriting competitive entry barriers for independent refiners. China Petroleum & Chemical Corporation leverages its integrated refining-petrochemical footprint to sustain margin capture across the value chain. PetroChina Company Limited anchors its position through pipeline and storage infrastructure control in northern China. Shell Energy (China) Limited competes via differentiated natural gas trading and LNG terminal access.
China oil and gas downstream operations transform crude oil and natural gas feedstocks into refined fuels, petrochemical intermediates, and specialty products through catalytic cracking, hydrocracking, and steam reforming processes at temperatures exceeding 500°C, serving as the critical link between upstream extraction and end-use consumption. Refined fuels dominate volume throughput but face structural margin compression from electric vehicle penetration in the transportation end user segment. Petrochemicals represent the fastest-expanding product type as polyethylene and polypropylene demand from packaging and automotive applications outpaces fuel growth. Direct sales channels to industrial buyers concentrate value capture away from fragmented retail outlet networks.
SAMR enforces national GB standards on fuel quality and product labeling that determine market access for domestic and imported refined products. MEE implements dual carbon goals through emissions intensity benchmarks that force refinery upgrades or capacity retirements. NMPA oversees chemical registration requirements that shape petrochemical product portfolios and import substitution strategies. Stakeholders must monitor how carbon border adjustment mechanisms and provincial emissions trading schemes reshape cost structures for export-oriented petrochemical derivatives.
Market Dynamics
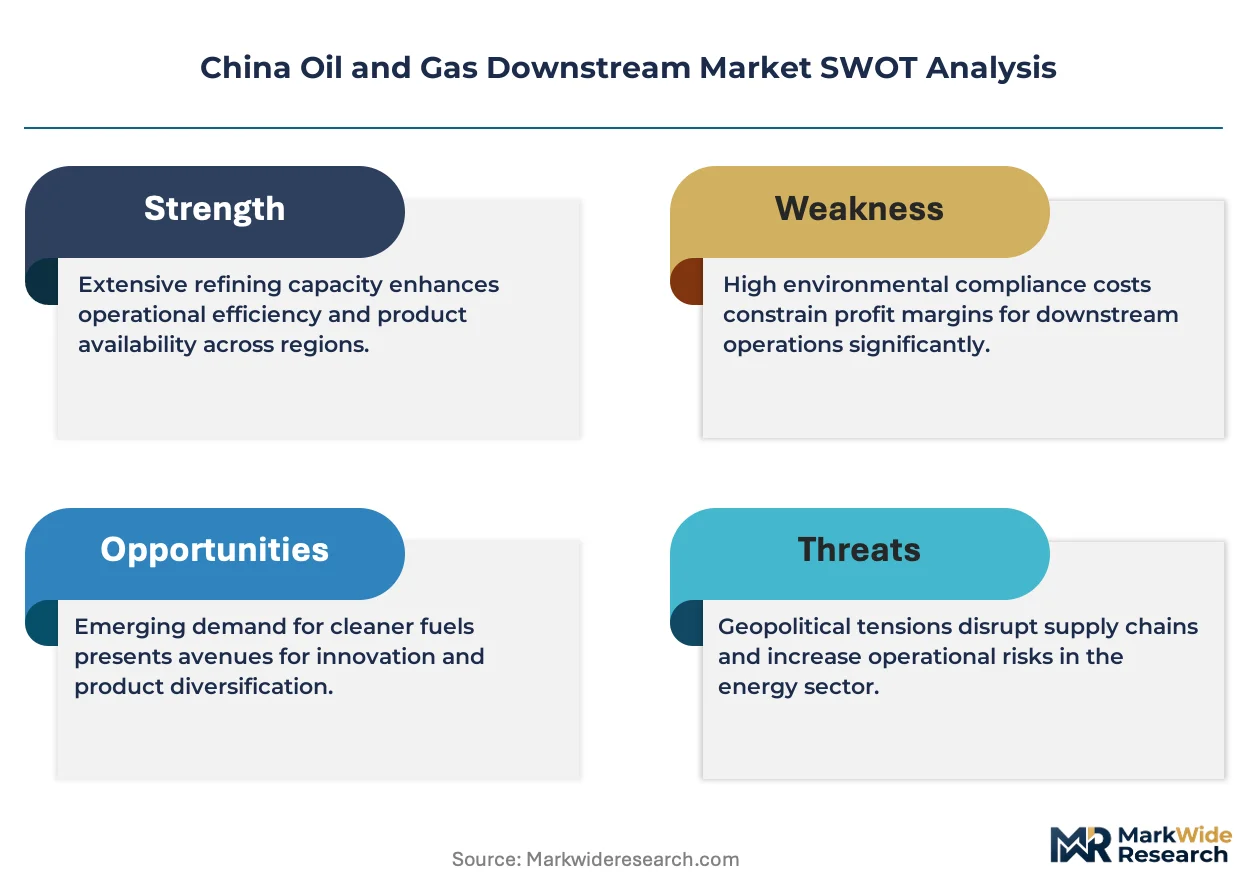
The MEE dual carbon goals are forcing refinery operators to retire marginal capacity or deploy carbon capture retrofits, compressing margins across Shandong's independent refining cluster while advantaging integrated state-owned operators with capital access.
Growth Catalysts
- Automotive lightweighting:Polypropylene and engineering polymer demand from electric vehicle battery housings and structural components is accelerating throughput at Yangtze River Delta petrochemical complexes.
- SAMR fuel quality standards:GB VI-B gasoline and diesel specifications are mandating hydrocracker and alkylation unit investments that upgrade product slate toward higher-margin petrochemical feedstocks.
- NMPA chemical registration:New substance notification requirements for imported specialty chemicals are creating import substitution opportunities for domestic polyethylene glycol and solvent producers.
Market Restraints
- Crude import quota volatility:Ministry of Commerce allocation uncertainty for independent refiners disrupts feedstock planning and working capital cycles.
- MEE emissions intensity benchmarks:Refineries exceeding carbon intensity thresholds face production curtailments during peak air quality enforcement periods.
- Electric vehicle penetration:Battery electric and plug-in hybrid vehicle sales are structurally compressing gasoline demand growth in coastal provinces.
Strategic Opportunities
- Hainan free trade port:Duty-free status for imported crude and export-oriented petrochemical derivatives enables tariff arbitrage for integrated refining-petrochemical investments.
- Green bond project finance:Carbon reduction-linked financing instruments are lowering cost of capital for hydrogen production and carbon capture unit deployment.
- Digital twin technology:Process simulation and predictive maintenance convergence is enabling remote operations centers to optimize yield across multiple refinery sites.
Industry Challenges
- Process control engineering scarcity:Distributed control system integration and advanced process control talent shortages delay digital transformation timelines.
- Legacy hydrotreater retrofit complexity:Integrating new catalyst formulations and reactor internals with existing pressure vessel specifications extends turnaround durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Oil and Gas Downstream Market |
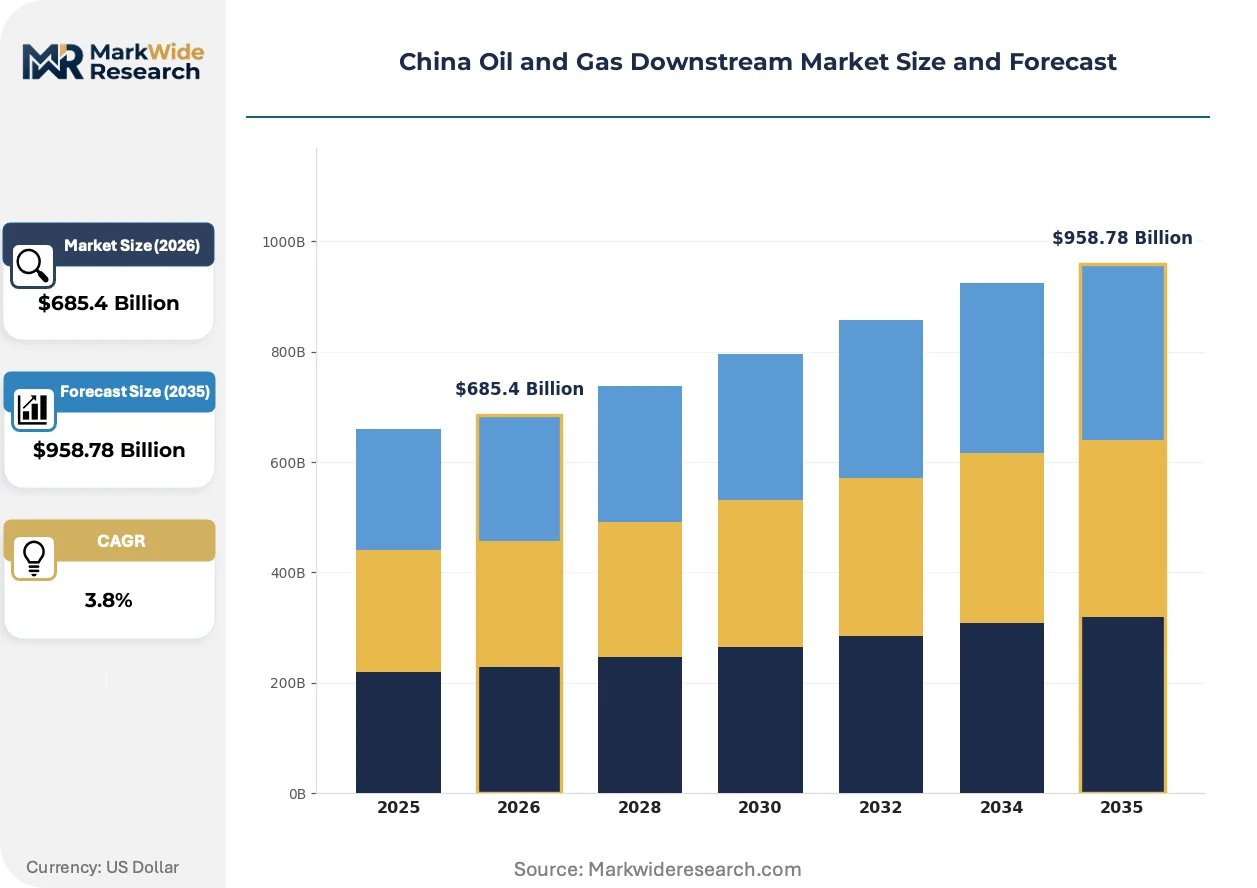
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $958.78 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Natural Gas Liquids End User: Transportation, Industrial, Residential, Commercial Distribution Channel: Retail Outlets, Wholesalers, Direct Sales, E-commerce Service Type: Logistics, Storage, Refining, Maintenance |
| Companies Covered | China Petroleum & Chemical Corporation, China National Petroleum Corporation, Sinopec Shanghai Petrochemical, PetroChina Company Limited, China National Offshore Oil Corporation, Shell Energy (China) Limited, Chevron Corporation, TotalEnergies, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Oil and Gas Downstream Market Strategic Shifts
Digital infrastructure deployment and regulatory carbon accounting are converging to transform how refinery operators optimize yield, manage emissions, and interface with industrial buyers.
Artificial intelligence-driven predictive maintenance is digitizing reliability engineering across catalytic cracking and hydrocracking units. Sinopec and PetroChina affiliates are deploying machine learning models to forecast coke deposition and catalyst deactivation. This capability is digitizing maintenance scheduling, compressing unplanned outage frequency and extending catalyst cycle lengths.
MEE emissions trading scheme expansion is tightening monitoring, reporting, and verification requirements for refinery carbon dioxide and methane releases. Operators must install continuous emissions monitoring systems and submit third-party verified inventories. Shandong Province independent refiners face the steepest compliance cost escalation as they lack integrated carbon capture infrastructure.
Direct sales contracting to industrial polyethylene and polypropylene buyers is displacing traditional distributor-mediated procurement in coastal manufacturing belts. Large automotive and packaging converters are negotiating multi-year offtake agreements with refinery-petrochemical complexes. This pattern concentrates procurement leverage in the Yangtze River Delta and Pearl River Delta manufacturing corridors.
China Oil and Gas Downstream Market Segmentation
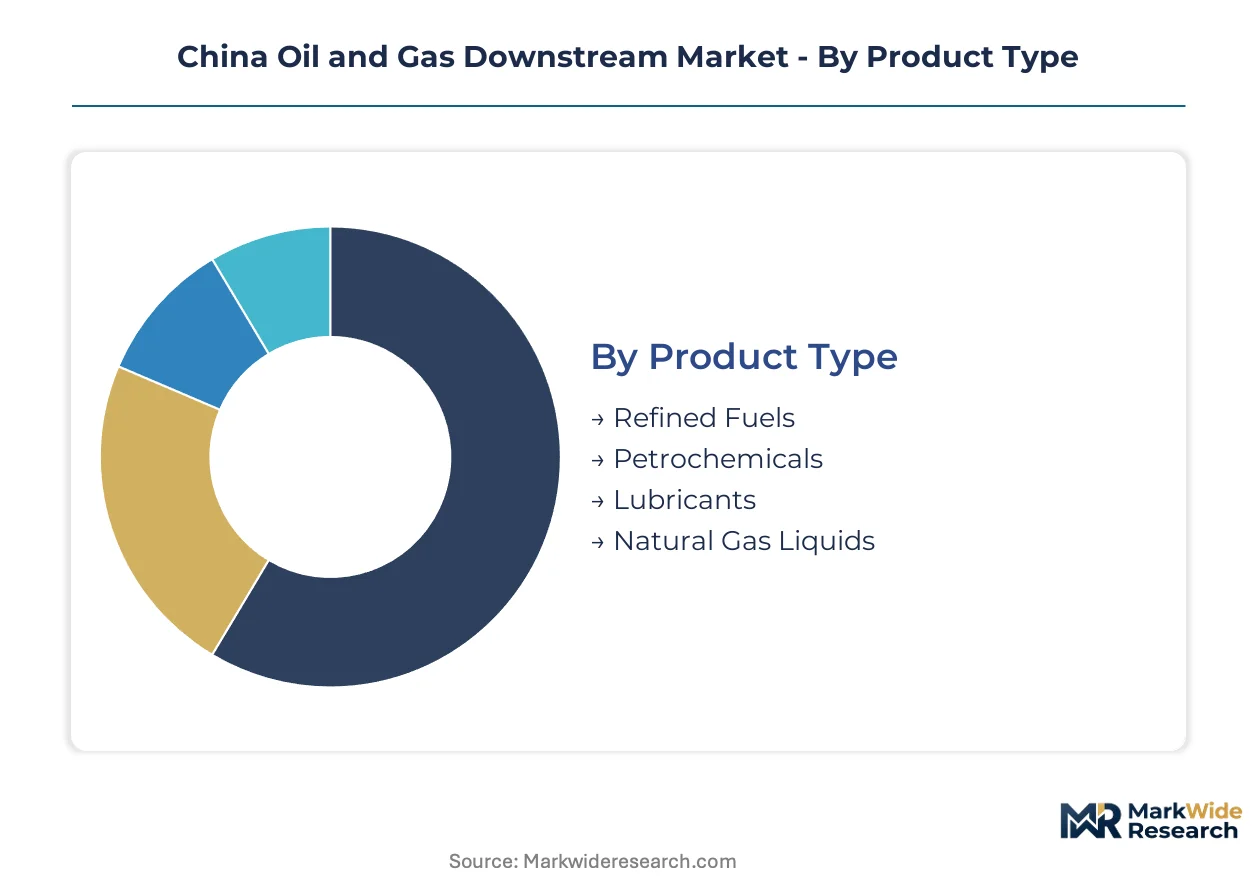
China's downstream oil and gas market segments along product chemistry, end-use application, and channel structure. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Cost tier differentiation separates commodity fuels from specialty chemicals with divergent capital intensity and pricing power.
- Refined Fuels:Gasoline, diesel, and jet kerosene produced through fluid catalytic cracking and hydrocracking at temperatures exceeding 500°C. Demand concentrates in coastal provinces where electric vehicle penetration is compressing gasoline volume growth most severely.
- Petrochemicals:Polyethylene, polypropylene, and aromatics derived from naphtha steam cracking and catalytic reforming. Yangtze River Delta automotive lightweighting applications are driving fastest capacity absorption for engineering polymers and battery housing materials.
- Lubricants:Base oils and formulated lubricants meeting GB 11121 and GB 11122 specifications for automotive and industrial applications.
- Natural Gas Liquids:Ethane, propane, and butane fractions separated from natural gas processing for petrochemical feedstock or residential heating use.
Refined fuels hold installed capacity. Petrochemicals is rotating up the share rankings.
End User:
Application concentration determines product mix optimization and margin capture potential across the value chain.
- Transportation:Fuel demand from road, rail, aviation, and marine fleets consuming gasoline, diesel, and marine gasoil. Shandong Province independent refiners face structural compression as battery electric vehicle sales erode gasoline offtake in coastal megacities.
- Industrial:Process heat, feedstock, and power generation across steel, cement, and chemical manufacturing. Pearl River Delta packaging converters are negotiating multi-year polypropylene offtake agreements directly with integrated refinery-petrochemical complexes.
- Residential:LPG for cooking and piped natural gas for heating in urban and peri-urban households.
- Commercial:Diesel backup power, HVAC fuel oil, and specialty solvents for service sector operations.
Industrial end users command procurement leverage. Transportation is ceding volume share fastest.
Distribution Channel:
Channel selection shapes working capital requirements and customer relationship depth in a market transitioning from retail fragmentation toward direct contracting.
- Retail Outlets:Branded and independent fuel stations dispensing gasoline and diesel to consumer and fleet vehicles. Sinopec and PetroChina affiliate networks dominate throughput in northern China pipeline corridors.
- Direct Sales:Long-term contracts between refiners and industrial polyethylene, polypropylene, and solvent buyers. Yangtze River Delta manufacturing belts are seeing fastest displacement of distributor-mediated procurement by direct refinery relationships.
- Wholesalers:Regional distributors aggregating smaller industrial and commercial accounts below direct sales minimums.
- E-commerce:Digital platforms for lubricants, specialty chemicals, and small-volume industrial solvent orders.
Direct sales channels concentrate value capture. E-commerce is climbing the fastest among channel expansions.
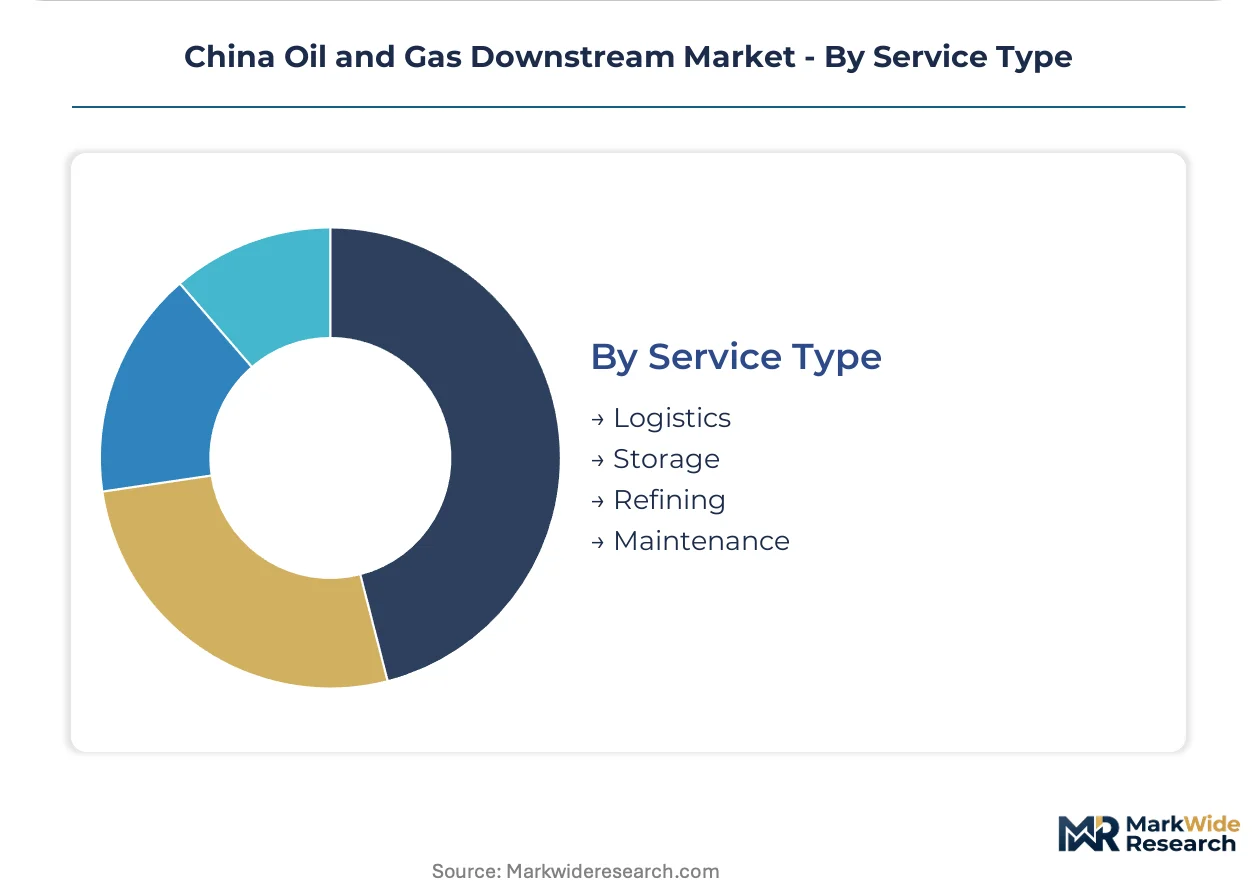
Service Type:
Service maturity separates asset-heavy infrastructure control from operational support functions with variable margin profiles.
- Refining:Crude distillation, conversion, and upgrading operations at integrated and independent facilities. Shandong Province's independent cluster faces MEE emissions intensity benchmarks forcing carbon capture retrofits or marginal capacity retirements.
- Storage:Crude and product tankage, underground caverns, and strategic petroleum reserve capacity. PetroChina's northern China pipeline and terminal infrastructure anchors domestic distribution control.
- Logistics:Pipeline transport, rail tank car, and coastal tanker movements connecting production to demand centers.
- Maintenance:Turnaround services, catalyst replacement, and reliability engineering for process units.
Refining commands capital deployment. Storage is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's downstream oil and gas market exhibits pronounced regional asymmetry between import-dependent coastal refining clusters and inland consumption centers. Trade flows concentrate through designated port zones where crude import quotas determine operational viability for independent processors.
Shandong Province
Independent refiners in Shandong's Dongying and Qingdao clusters process imported medium-sour crudes under Ministry of Commerce quota allocations. MEE emissions intensity benchmarks are forcing carbon capture retrofits or marginal capacity retirements among smaller operators lacking integrated petrochemical downstream. The province's refining capacity exceeds domestic product offtake, creating surplus gasoline and diesel movements to northern China via rail and pipeline.
Yangtze River Delta
Petrochemical demand from automotive lightweighting applications is accelerating throughput at Ningbo and Shanghai integrated complexes. SAMR-enforced GB VI-B fuel specifications mandate hydrocracker investments that upgrade product slates toward higher-margin polyethylene and polypropylene feedstocks. Jiangsu and Zhejiang manufacturing belts are seeing fastest displacement of distributor-mediated procurement by direct refinery relationships with packaging converters.
Pearl River Delta
Guangdong's refining-petrochemical complexes serve export-oriented manufacturing demand for specialty solvents and engineering polymers. NMPA chemical registration requirements for imported specialty chemicals are creating import substitution opportunities for domestic polyethylene glycol producers. Shenzhen and Dongguan automotive suppliers are negotiating multi-year polypropylene offtake agreements directly with integrated complexes.
Beijing-Tianjin-Hebei
PetroChina's pipeline and storage infrastructure anchors domestic distribution control across northern China corridors. MEE dual carbon goals enforce production curtailments during peak air quality enforcement periods, compressing margins for refineries exceeding carbon intensity thresholds. Tianjin's LNG terminal capacity supports natural gas liquid fractionation for regional petrochemical feedstock supply.
Hainan Free Trade Port
Duty-free status for imported crude and export-oriented petrochemical derivatives enables tariff arbitrage for integrated refining-petrochemical investments. Yangpu Economic Development Zone is attracting green bond project finance for hydrogen production and carbon capture unit deployment. The island's location supports Southeast Asian export markets for refined products and specialty chemicals.
China Oil and Gas Downstream Market Competitive Environment
On the supply side, the industry is bifurcated between capital-intensive state-owned integrated operators and margin-pressed independent refiners concentrated in coastal provinces. Sinopec and PetroChina affiliates control pipeline infrastructure and strategic storage capacity, creating structural barriers for non-integrated entrants. Three archetypes dominate: national champions with full value chain integration, regional independents dependent on import quotas, and international traders leveraging LNG terminal access. Competitive dynamics center on carbon capture retrofit financing and direct sales contracting to industrial polyethylene buyers.
Among state-owned integrated operators, China Petroleum & Chemical Corporation and PetroChina Company Limited occupy positions defined by pipeline corridor control and petrochemical complex scale. Shell Energy (China) Limited represents the international trading archetype, differentiated by LNG terminal access and natural gas portfolio management. These three entities exemplify how infrastructure ownership, import quota access, and clean fuel transition capital determine competitive positioning under tightening MEE emissions benchmarks.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| China National Petroleum Corporation |
| Sinopec Shanghai Petrochemical |
| PetroChina Company Limited |
| China National Offshore Oil Corporation |
| Shell Energy (China) Limited |
| Chevron Corporation |
| TotalEnergies |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Shandong Province's independent refining cluster anchors China's downstream pricing dynamics, where surplus gasoline and diesel production capacity exceeding regional offtake forces price competition into northern China pipeline corridors. MEE emissions intensity benchmarks compress margins for carbon-intensive operators while advantaging integrated state-owned complexes with carbon capture capital access.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across polyethylene and polypropylene feedstocks. Price differentiation separates GB VI-B certified fuels from standard grades while volume scale and direct sales relationships concentrate procurement leverage in Yangtze River Delta manufacturing belts. Cost compression in refined fuels intensifies as battery electric vehicle penetration erodes gasoline demand growth in coastal provinces. Fleet operators and independent fuel distributors exhibit highest price sensitivity, whereas integrated petrochemical converters with multi-year supply agreements demonstrate lowest.
Supply Chain Analysis
Tariff exposure between Middle East crude suppliers and Shandong independent refiners dominates supply chain risk calculus under Ministry of Commerce quota volatility. Geographic supply concentration draws from Saudi Arabia, Russia, and Iraq for medium-sour crude feedstocks while specialty catalysts and advanced process control systems rest on German and Japanese manufacturing. Single-source vulnerability concentrates in hydrocracking catalyst formulations where proprietary reactor internals create extended turnaround dependencies. Distribution runs through PetroChina's northern pipeline network, coastal tanker movements, and rail tank car corridors connecting Dongying and Qingdao clusters to inland demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's downstream oil and gas sector faces high-growth disruption from MEE dual carbon enforcement, where emissions trading scheme expansion and carbon capture retrofit mandates are rewriting competitive economics for independent refiners.
For Market Incumbents: Insulate margin position through backward integration into hydrogen production and carbon capture infrastructure at Yangtze River Delta complexes. Accelerate direct sales contracting with automotive OEMs for battery housing polypropylene to lock in offtake before import substitution alternatives mature. Prioritize green bond project finance access to lower capital costs for emissions compliance investments.
For New Entrants and Emerging Players: Pursue Hainan Free Trade Port duty-free crude import status to establish tariff-advantaged refining-petrochemical capacity serving Southeast Asian export markets. Target specialty solvent production for NMPA chemical registration substitution opportunities where domestic polyethylene glycol producers face limited competition. Deploy digital twin technology as differentiation wedge for remote operations center contracts with Shandong independent refiners lacking process control engineering talent.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned enterprise non-core asset divestitures, particularly stranded refining capacity in Beijing-Tianjin-Hebei corridors facing production curtailment risk. Long-term viability hinges on carbon capture retrofit completion and petrochemical downstream integration depth. Monitor MEE emissions trading scheme price discovery as inflection signal for independent refiner distress acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | MEE emissions intensity benchmarks force capacity retention at Shandong independent refiners. |
| Green Bond Project Finance | Dual carbon-linked instruments lower capital costs for hydrogen production investments. |
| Direct Sales Contracting | Multi-year polypropylene offtake agreements with Yangtze River Delta automotive suppliers concentrate value capture. |
| Digital Twin Technology Integration | Predictive maintenance convergence enables remote operations center yield optimization. |
| Hainan Free Trade Port Investment | Duty-free crude status enables tariff arbitrage for Southeast Asian export-oriented derivatives. |
Study Parameters
Operator-level perspectives from refinery operations directors, petrochemical procurement leads at automotive OEMs, MEE regional enforcement officers, and green bond structuring specialists anchored the qualitative base. Secondary validation drew from SAMR GB standards filings, MEE emissions trading scheme disclosure registries, Ministry of Commerce crude import quota allocations, and Sinopec SEC 20-F submissions. Bottom-up capacity modeling and top-down demand projection triangulation established volume and value estimates.
Scenario-bracketing framed analytical approaches across the projection horizon, with CAGRs derived from segmented capacity absorption rates and end-use demand elasticity modeling. Segmentation dimensions included product chemistry tier, end-use application concentration, distribution channel structure, and service type maturity. Industry-specific forecast inputs incorporated MEE dual carbon policy implementation pacing and electric vehicle penetration curves in coastal provinces.
Sensitivities concentrate around MEE emissions trading scheme price volatility, Ministry of Commerce crude quota allocation shifts, and carbon border adjustment mechanism implementation timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market