
 Modified Sine Wave Home Inverters Market | 2026-2036
Modified Sine Wave Home Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Sine Wave Home Inverters Market Analytics
Modular inverter kits with detachable battery compartments is decoupling hardware from storage decisions for cost-sensitive buyers. AIMS Power leverages vertical integration to control component sourcing across its product lines. Giandel anchors its position through specialization in high-wattage recreational vehicle configurations. Renogy differentiates via channel control, dominating direct-to-consumer renewable energy platforms.
Modified sine wave home inverters produce a stepped approximation of alternating current through pulse-width modulation at switching frequencies typically between 50 and 60 hertz, serving as affordable power conversion for basic appliances where waveform fidelity remains secondary to cost efficiency. Transformerless topologies now lead the technology segment due to lighter weight and higher efficiency ratings, while the 3000W product type captures the fastest growth as it matches typical residential solar array outputs. The residential application segment holds the deepest margin pools, though recreational vehicles command premium pricing for vibration-hardened designs.
The US Department of Energy enforces minimum efficiency standards that disqualify legacy transformer-based units from federal incentive programs, while the EU F-Gas Regulation restricts refrigerant-dependent cooling loads that modified sine wave units commonly power. India's Bureau of Energy Efficiency mandates star-labeling for power conversion equipment, compressing margins for uncertified imports. Stakeholders must monitor whether evolving harmonic distortion limits in emerging economies will force design migrations toward pure sine wave architectures.
Market Dynamics
Transformerless topology adoption is compressing manufacturing costs while US Department of Energy efficiency standards disqualify legacy transformer-based designs from federal incentive eligibility, forcing a hardware transition across residential and recreational vehicle segments.
Growth Catalysts
- Rural electrification frameworks:Off-grid residential programs in sub-Saharan Africa are expanding addressable demand for cost-sensitive power conversion equipment among households without grid access.
- Distributed solar-home-system mandates:India's Bureau of Energy Efficiency star-labeling requirements are accelerating certified product adoption through quality-linked procurement incentives.
- Recreational vehicle power requirements:Vibration-hardened inverter specifications for mobile applications are creating premium product tiers with sustained margin pools.
Market Restraints
- Harmonic distortion technical ceilings:Modified sine wave output limitations restrict compatibility with sensitive electronics and motor-driven appliances, capping addressable load categories.
- Copper and magnetic core input volatility:Transformer-based legacy inventory carries material cost exposure that compresses margins when commodity prices spike.
- Pure sine wave substitution pressure:Falling costs of advanced pulse-width modulation controllers are narrowing the price gap between modified and pure sine wave alternatives.
Strategic Opportunities
- Modular battery decoupling:Detachable storage compartments allow manufacturers to separate inverter hardware from lithium-ion procurement decisions, reducing upfront buyer commitment.
- EU F-Gas Regulation alignment:Refrigerant-dependent cooling load restrictions create specification windows for modified sine wave units powering compliant appliance categories.
- Direct-to-consumer channel expansion:Renewable energy platform dominance enables bypass of traditional electrical distributor markups for residential solar kit bundling.
Industry Challenges
- Multi-jurisdiction certification timelines:Concurrent UL, CE, and BIS testing requirements extend product launch cycles and strain engineering bandwidth.
- Legacy appliance compatibility verification:Pre-2010 motor loads and medical equipment create unpredictable failure modes that elevate warranty claim exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Sine Wave Home Inverters Market |
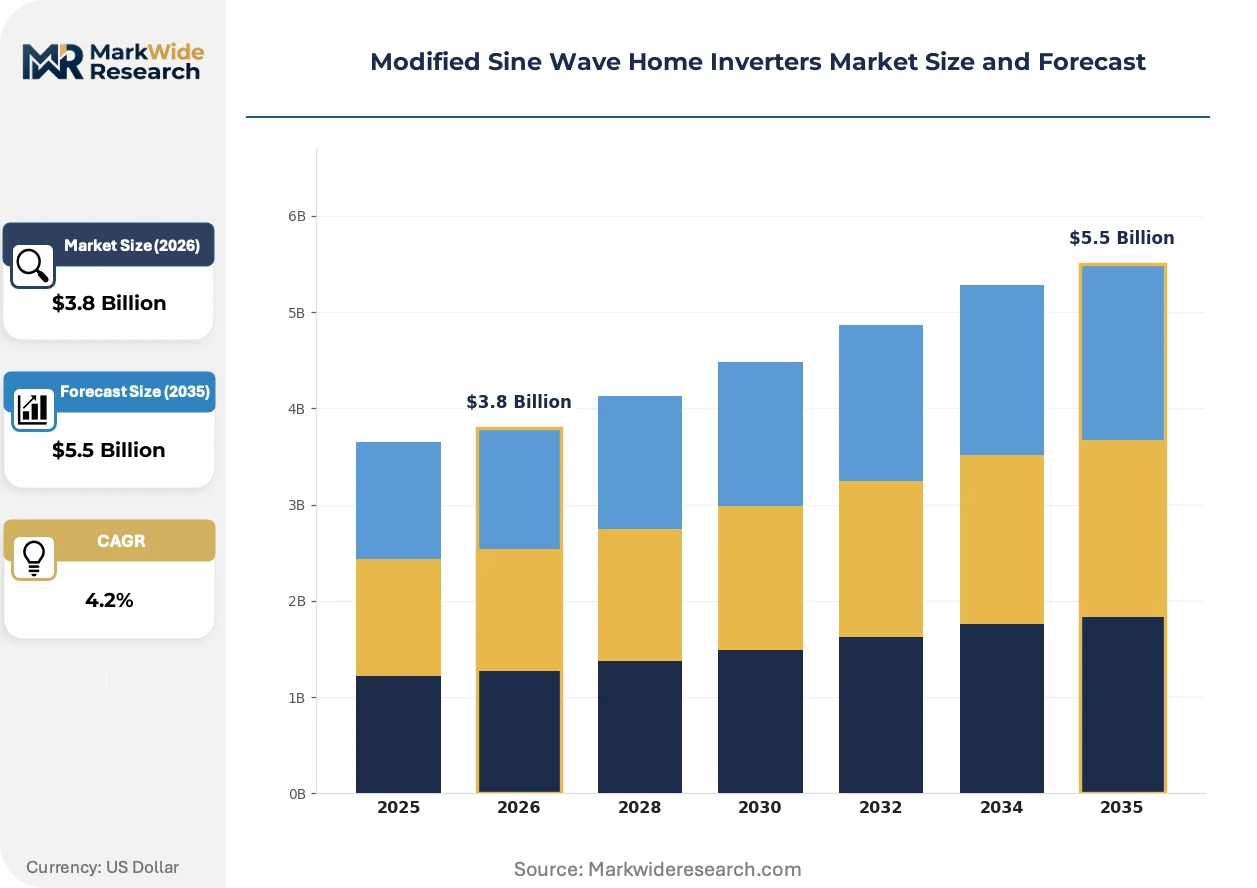
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1500W, 3000W, 5000W, 10000W Application: Residential, Recreational Vehicles, Off-Grid, Backup Power Technology: Transformer-Based, Transformerless, Hybrid, Digital Control End User: Homeowners, Contractors, DIY Enthusiasts, Renewable Energy Installers |
| Companies Covered | AIMS Power, Giandel, Samlex America, Renogy, JOEYOUNG, Genius Power, SUNRUNE, GuangZhou HanFong New Energy Technology Co., Ltd., Kingson Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Sine Wave Home Inverters Market Evolving Landscape
Pulse-width modulation switching at 50-60 hertz is yielding to higher-frequency silicon carbide implementations, while procurement patterns fragment across direct-to-consumer platforms and traditional electrical distribution.
Transformerless inverter architectures eliminate magnetic core weight and copper winding costs while delivering efficiency ratings above 95 percent. Recreational vehicle manufacturers are specifying these designs for payload-sensitive installations. Silicon carbide switching is overtaking insulated-gate bipolar transistor configurations in mid-wattage residential segments.
The EU F-Gas Regulation restricts refrigerant-dependent cooling loads that modified sine wave units commonly power, compressing addressable appliance categories in European markets. Manufacturers are responding with load-specific compatibility labeling and targeted marketing toward resistive heating and lighting applications. India's Bureau of Energy Efficiency mandates are accelerating certified product turnover in the fastest-expanding geography.
Direct-to-consumer renewable energy platforms are disintermediating traditional electrical distributors for residential solar kit procurement. Buyers now configure inverter-battery combinations through online interfaces rather than contractor-mediated specifications. This channel shift concentrates in India and North American off-grid residential segments where installation labor availability varies regionally.
Modified Sine Wave Home Inverters Market Segmentation
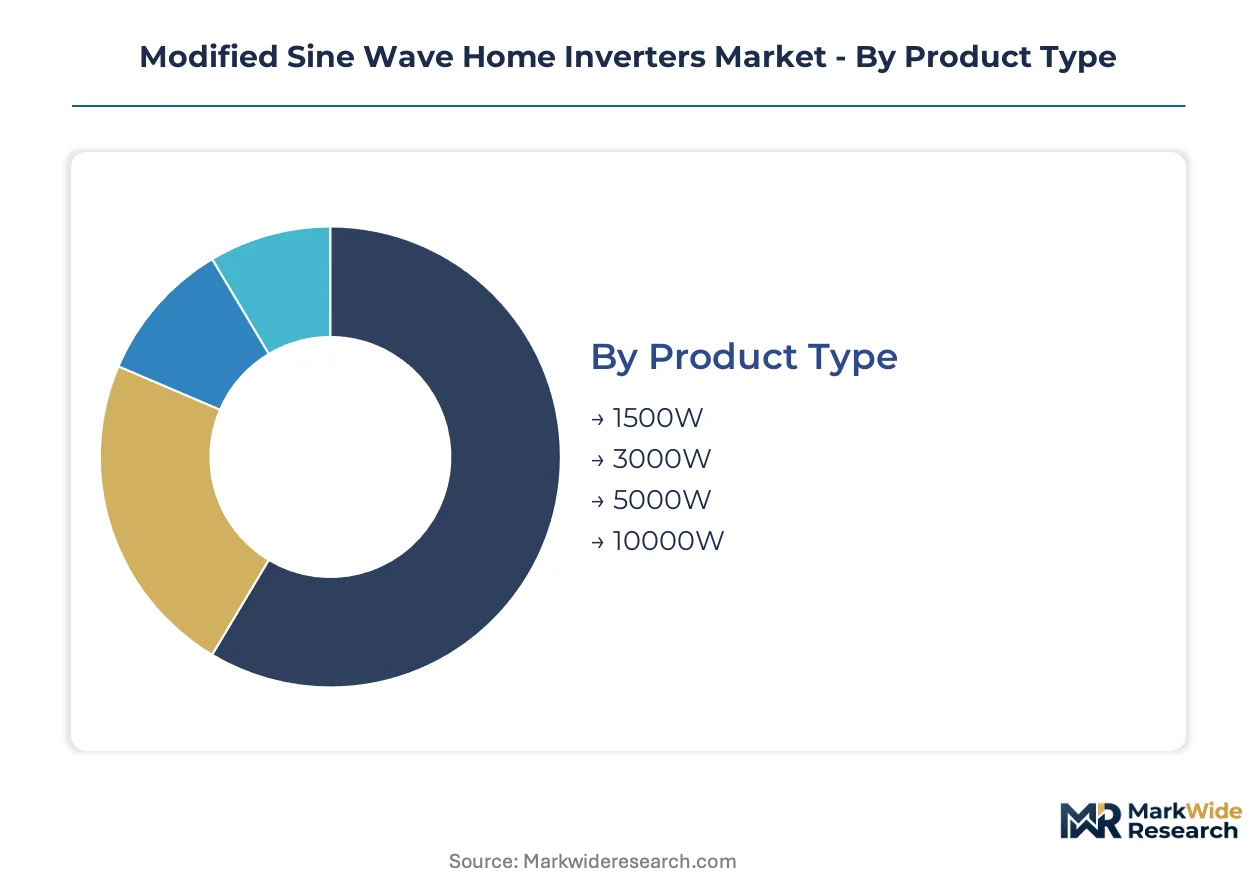
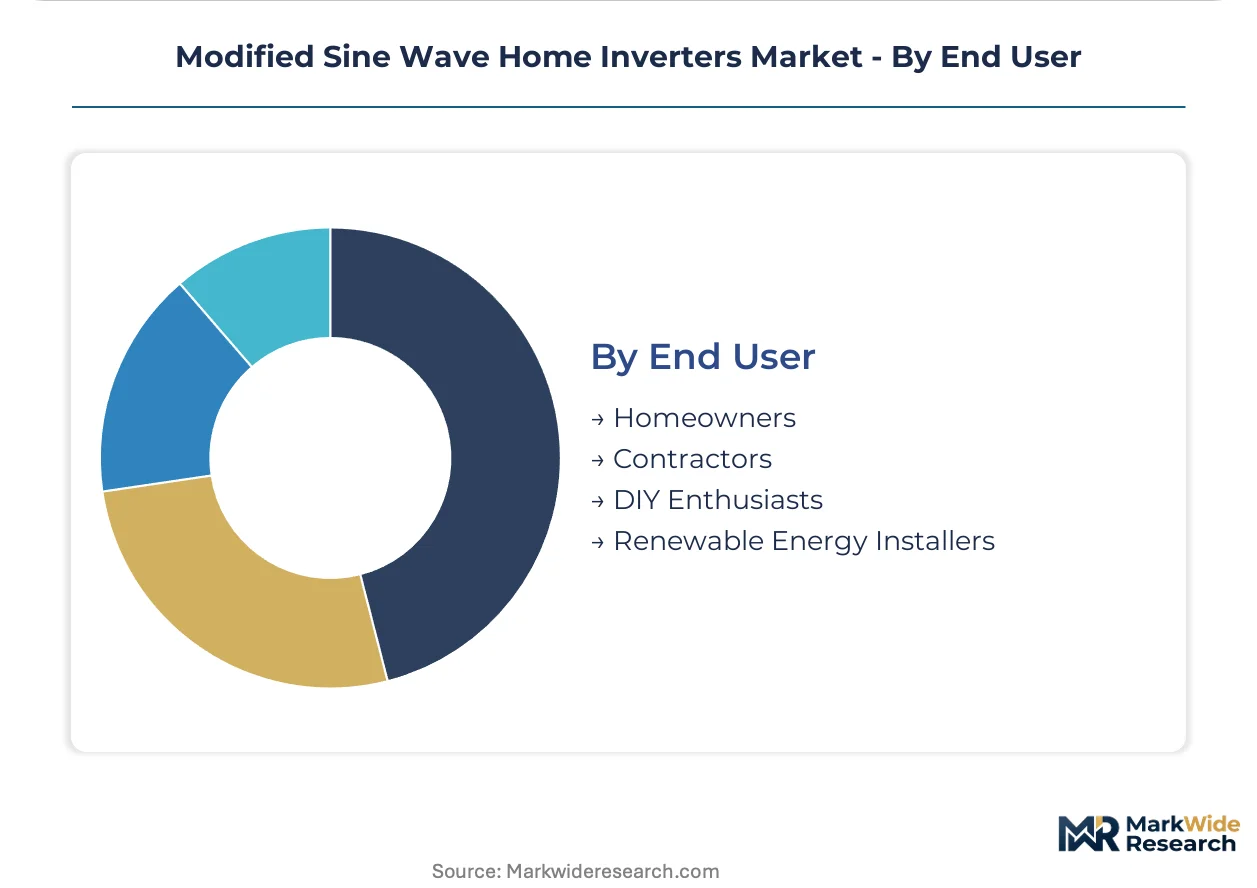
Segmentation in modified sine wave home inverters reveals how procurement patterns fragment across power ratings, installation contexts, and buyer technical sophistication. Manufacturers configure product lines to match distinct margin profiles and certification requirements across these divides.
Product Type:
Supply concentration clusters around mid-wattage platforms where component standardization meets residential solar array matching.
- 1500W:Entry-level units serve basic lighting and small appliance loads through compact transformer-based designs. Demand concentrates among off-grid cabins and emergency backup installations in rural India where capital constraints dominate purchase decisions.
- 3000W:Dominant residential specification aligns with typical rooftop solar outputs through transformerless architectures. India's distributed solar-home-system deployments are accelerating adoption among certified product procurement channels.
- 5000W:Higher-capacity platforms target multi-appliance households with sustained load requirements.
- 10000W:Commercial-residential crossover units support small business backup and large property installations.
3000W absorbs the bulk of installed capacity; 3000W is expanding most quickly.
Application:
Cost tier differentiation separates premium vibration-hardened designs from standard residential units.
- Residential:Grid-tied and off-grid home installations constitute the volume base through standardized efficiency ratings. US Department of Energy standards are disqualifying legacy transformer-based units from federal incentive eligibility.
- Recreational Vehicles:Mobile specifications command sustained margin premiums through payload-optimized transformerless designs. North American RV manufacturers are specifying these for vibration-hardened installations.
- Off-Grid:Remote property and rural electrification programs in sub-Saharan Africa are expanding cost-sensitive demand.
- Backup Power:Grid-failure contingency systems prioritize rapid switching and surge tolerance.
Residential captures deepest volume pools; Recreational Vehicles maintains premium pricing power.
Technology:
Volume migration toward transformerless platforms is displacing legacy magnetic core architectures.
- Transformer-Based:Legacy copper-wound designs persist in price-sensitive segments despite weight and efficiency penalties. Copper price volatility compresses margins for manufacturers holding legacy inventory.
- Transformerless:Silicon carbide switching enables ratings above 95 percent efficiency through eliminated magnetic cores. India's Bureau of Energy Efficiency star-labeling mandates are accelerating certified product turnover.
- Hybrid:Dual-mode units bridge grid-tied and off-grid functionality.
- Digital Control:Microprocessor-managed power conditioning enables precise waveform shaping.
Transformerless dominates new installations; Transformerless is gaining share fastest.
End User:
Customer type determines channel configuration and support intensity requirements.
- Homeowners:Direct-to-consumer renewable energy platforms enable self-directed procurement of bundled solar-inverter kits. Online configuration tools are displacing contractor-mediated specifications in India and North America.
- Contractors:Professional installation networks demand bulk pricing and warranty backing for multi-unit projects.
- DIY Enthusiasts:Technical hobbyists drive modular battery decoupling preferences.
- Renewable Energy Installers:Certified technicians require star-label compliance and documentation packages.
Homeowners represent the broadest addressable base; Renewable Energy Installers concentrate certified product flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India, China's coastal manufacturing belts, and US federal incentive corridors are concentrating inverter production and procurement decisions across three continents.
United States
Off-grid residential installations in the Mountain West and Pacific Northwest are absorbing transformerless 3000W units. The US Department of Energy enforces efficiency standards that disqualify legacy transformer-based designs from federal tax credit eligibility. Texas and Arizona clusters host distribution centers serving DIY solar kit assemblers.
India
Distributed solar-home-system deployments in Gujarat and Maharashtra are accelerating certified product turnover. The Bureau of Energy Efficiency mandates star-labeling for power conversion equipment, compressing margins for uncertified imports. Tamil Nadu manufacturing zones produce transformerless architectures for domestic and export markets.
Germany
Recreational vehicle manufacturers in Bavaria and Baden-Württemberg specify vibration-hardened transformerless designs for payload-sensitive installations. The EU F-Gas Regulation restricts refrigerant-dependent cooling loads that modified sine wave units commonly power. Stuttgart industrial corridors host testing facilities for CE compliance verification.
China
Guangdong and Zhejiang provinces dominate component fabrication for pulse-width modulation controllers and silicon carbide switching modules. The country's dual carbon goals accelerate efficiency-rated product adoption through procurement guidelines. Shenzhen electronics clusters supply transformerless topology subassemblies to global inverter assemblers.
Brazil
Rural electrification programs in Minas Gerais and Bahia expand cost-sensitive demand for 1500W entry-level units. ANVISA registration requirements for medical equipment compatibility create specification barriers for modified sine wave imports. São Paulo distribution hubs consolidate regional logistics for South American markets.
Modified Sine Wave Home Inverters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across transformerless topology segments. The vendor base separates into three tiers: vertically integrated component manufacturers, channel-dominant renewable energy platforms, and regional fabricators serving price-sensitive procurement. Strategic moves concentrate on backward integration into silicon carbide switching supply and direct-to-consumer platform expansion.
Among North American specialists, AIMS Power and Giandel occupy distinct positioning vectors within recreational vehicle and residential backup segments. Renogy anchors the direct-to-consumer channel tier through renewable energy platform dominance. These three exemplify how geographic specialization and channel control separate competitors in a market where component standardization erodes product-level differentiation.
| Leading Market Players |
|---|
| AIMS Power |
| Giandel |
| Samlex America |
| Renogy |
| JOEYOUNG |
| Genius Power |
| SUNRUNE |
| GuangZhou HanFong New Energy Technology Co., Ltd. |
| Kingson Electronics Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Off-grid residential procurement programs in sub-Saharan Africa and India's Bureau of Energy Efficiency star-labeling mandates concentrate buyer power among certified product channels, anchoring a three-tier pricing structure across premium transformerless, standard certified, and economy uncertified tiers.
Pricing Analysis
Short lead-time premiums for transformerless 3000W units run 15-25 percent above contract pricing, while spot inventory of legacy transformer-based designs trades at clearance discounts. Price differentiation rests on BIS certification tier and silicon carbide switching content. Cost compression in the 1500W entry segment intensifies as Chinese module imports expand. DIY enthusiasts in North America show highest price sensitivity; recreational vehicle OEMs show lowest.
Supply Chain Analysis
Regional distribution centers in Texas, São Paulo, and Johannesburg consolidate hub-and-spoke patterns for final-mile delivery to solar kit assemblers. Manufacturing concentrates in China, India, and Vietnam for pulse-width modulation controllers and magnetic components. Raw material draws from copper winding suppliers, silicon carbide substrate fabricators, and aluminum heat sink extruders. Single-source vulnerability in silicon carbide switching modules elevates risk exposure. Distribution runs through direct-to-consumer renewable energy platforms and traditional electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modified sine wave home inverters market reads as a cost-of-compliance story where India's Bureau of Energy Efficiency star-labeling and US Department of Energy efficiency standards erect certification barriers that favor incumbent players with testing infrastructure.
For Market Incumbents: Hedge against pure sine wave substitution by accelerating silicon carbide switching R&D and securing captive supply of high-frequency PWM controllers. Backward integration into transformerless topology subassemblies in Tamil Nadu manufacturing zones defends margin position against commodity copper volatility. For New Entrants and Emerging Players: Enter via modular battery decoupling architectures targeting DIY enthusiasts in North American off-grid residential segments. White-space concentrates in vibration-hardened recreational vehicle specifications where payload-optimized designs command sustained premiums. Go-to-market runs through direct-to-consumer renewable energy platform partnerships. For Investors and Strategic Acquirers: The window for entry favors transformerless topology specialists with BIS and UL certification pipelines already in progress. Long-term viability hinges on regulatory compliance moats widening as harmonic distortion limits tighten. Watch India's Bureau of Energy Efficiency enforcement intensity as inflection signal for certified product turnover acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Switching | Captive supply of high-frequency modules insulates margins from single-source vulnerability. |
| BIS Star-Label Certification Program | Quality-linked procurement incentives in India compress uncertified import margins. |
| Direct-to-Consumer Platform Expansion | Channel control bypasses electrical distributor markups in residential solar kit bundling. |
| Modular Battery Decoupling Architecture | Detachable storage compartments reduce upfront buyer commitment in cost-sensitive segments. |
| Vibration-Hardened RV Specification Development | Premium tier positioning captures sustained margin pools in North American mobile applications. |
Research Methodology
Trade customs records, Bureau of Energy Efficiency certification databases, and US Department of Energy efficiency standard filings formed the secondary backbone, cross-referenced against primary interviews with inverter product managers, renewable energy platform procurement leads, EPC contractors, and off-grid installation technicians. Bottom-up unit shipment estimates and top-down addressable market sizing were triangulated across transformerless and transformer-based technology segments.
Historical trendline analysis of certified product turnover rates and silicon carbide switching adoption curves informed the projection framework across power rating tiers, application contexts, and end-user archetypes. CAGRs were derived from segmented growth rate reconciliation. Key inputs included India's distributed solar-home-system deployment pipelines and US federal incentive eligibility evolution.
Revisions become necessary when copper and magnetic core commodity volatility spikes, when emerging economies tighten harmonic distortion limits, or when pure sine wave controller costs compress the technology gap. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Smart Power Market
Power
Russian Federation Power Market
Power
Europe Microturbine Market
Power
Direct Current Power System Market
Power
High Voltage DC Power System Market
Power
Malaysia Power EPC Market
Power
North America Microturbine Market
Power
Statcom Market
Power
Resonant Power Converters Market
Power
Power Purchase Agreement Market
Power
Italy Power Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Argentina Power Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
LNG Power Barge Market
Power
Power Rental Market