
 Second-Life EV Battery Market | 2026-2036
Second-Life EV Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Second-Life EV Battery Market Outlook
Aftermarket energy storage revenue is rewriting profit allocation across the automotive value chain. Redwood Materials leverages upstream control over cathode precursor production to capture margin pools that OEMs once retained. Nissan Motor Corporation anchors its position through proprietary battery health assessment protocols developed across its LEAF fleet operations. B2U Storage Solutions competes via large-scale stationary storage installations that aggregate thousands of retired EV modules.
Second-life EV batteries comprise retired automotive lithium-ion cells that retain 70-80% of original capacity after vehicle service, undergoing grading, reconfiguration, and safety recertification for stationary applications. Their primary commercial purpose is to defer recycling costs while delivering grid-scale energy storage at 30-50% lower unit economics than new batteries. Stationary storage leads product type deployment as utilities prioritize bulk capacity over cycling precision. Lithium-ion technology dominates the technology stack due to module standardization and established diagnostic protocols. Grid support applications within the application dimension concentrate margin pools where frequency regulation contracts command premium availability payments.
The EU Battery Regulation and China's MIIT circular economy standards are converging on mandatory state-of-health disclosure at battery retirement, which directly shapes product traceability requirements and cross-border trade eligibility. The EPA's evolving hazardous waste classifications in the United States further condition how retired packs move between jurisdictions and processing facilities. Stakeholders must monitor whether emerging certification regimes fragment into incompatible national standards or coalesce around IEC technical specifications that would enable liquid secondary markets.
Market Dynamics
Stationary storage economics are compressing as repurposing costs fall below new battery procurement thresholds, pulling retired automotive packs into grid-scale deployment faster than recycling infrastructure can absorb them.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled content thresholds and traceability systems create compliant offtake channels for graded second-life cells.
- Grid modernization programs:State-backed utility procurement in China concentrates demand for bulk stationary capacity.
- Lithium-ion standardization:Module diagnostic protocols reduce reconfiguration labor and accelerate safety recertification timelines.
Market Restraints
- Cathode material cost volatility:Nickel and cobalt price swings compress margin pools for refurbished pack assemblers.
- Supply concentration in China:Processing infrastructure for battery grading and cell matching clusters in Shandong and Guangdong provinces.
- State-of-health disclosure mandates:Divergent national certification regimes fragment cross-border trade eligibility.
Strategic Opportunities
- Commercial building microgrids:Behind-the-meter installations in Germany and the Netherlands absorb mid-grade retired packs.
- Frequency regulation contracts:Grid operators in Texas and California pay premium availability payments for fast-response storage.
- Digital battery passports:IEC technical specifications for standardized health data unlock liquid secondary markets.
Industry Challenges
- Diagnostic technician scarcity:Cell-level grading requires electrochemistry expertise that workforce development programs have not scaled.
- Fire safety certification timelines:UL 9540A testing for repurposed packs extends deployment schedules.
- Legacy BMS integration:Proprietary battery management firmware from OEMs complicates module aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second-Life EV Battery Market |
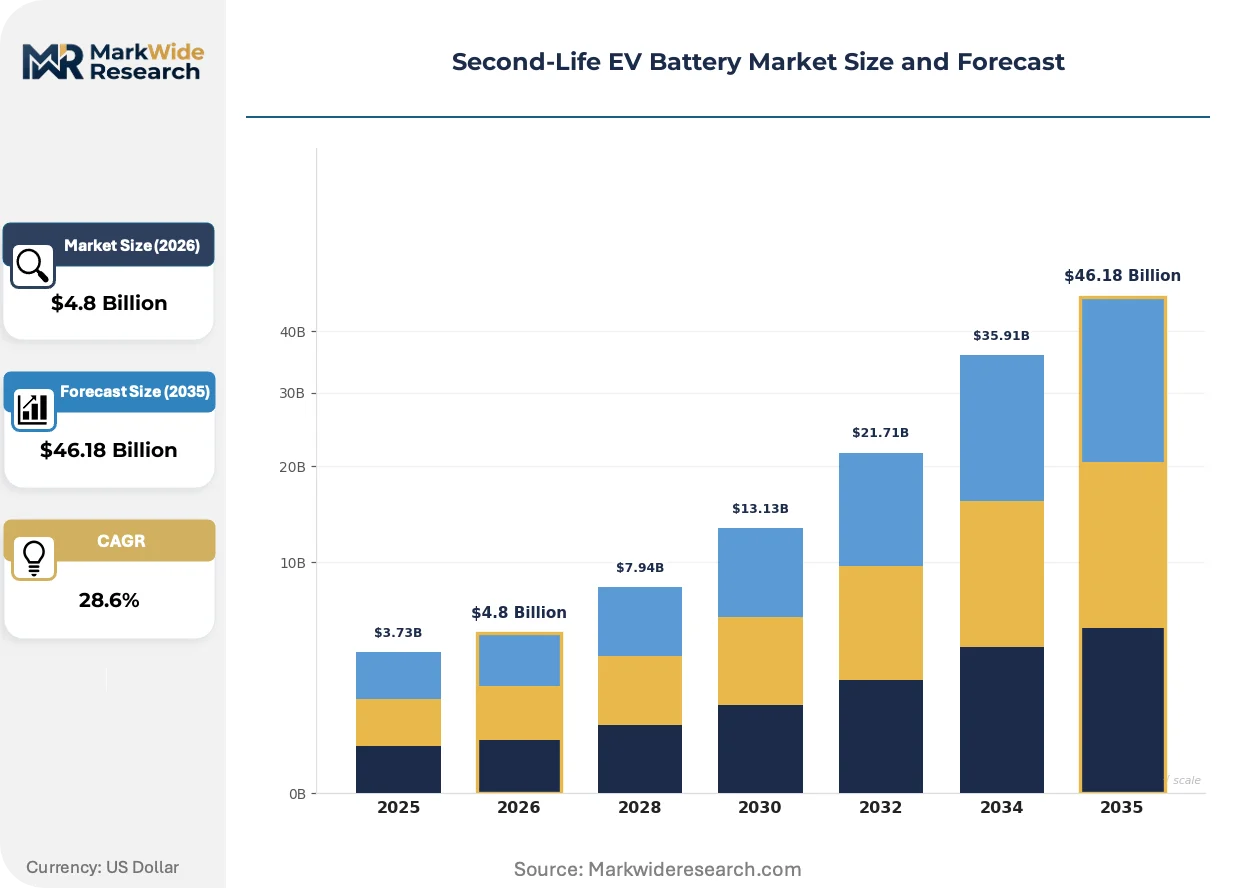
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Storage, Grid Support, Backup Power, Renewable Integration Technology: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Flow Batteries End User: Utilities, Commercial Buildings, Residential Users, Automotive Sector Application: Energy Storage Systems, Electric Grid Services, Load Shifting, Off-Grid Solutions |
| Companies Covered | Connected Energy, B2U Storage Solutions, Redwood Materials, Element Energy, Nissan Motor Corporation, Tesla, Rejoule, BeePlanet, Zenobē, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second-Life EV Battery Market Strategic Shifts
Three forces are restructuring how retired automotive cells re-enter commercial circulation: diagnostic automation, regulatory disclosure convergence, and procurement model fragmentation across buyer tiers.
Machine-learning-based state-of-health prediction is hybridizing with electrochemical impedance spectroscopy to reduce grading costs. Independent repurposers in South Korea and the Netherlands deploy these hybrid systems to assess thousands of modules daily. The technology is hybridizing what were separate technical specialties into unified assessment platforms that compress due diligence timelines.
The EU Battery Regulation and China's MIIT circular economy standards are converging on mandatory state-of-health disclosure at battery retirement. This convergence forces repurposers to maintain dual certification tracks or lobby for mutual recognition agreements. Grid-scale stationary storage projects in Europe face the tightest compliance timelines as the regulation phases in between 2027 and 2030.
Utility procurement departments are unbundling long-term service contracts from hardware supply. This unbundling shifts risk allocation toward repurposers who must guarantee performance without controlling upstream cell quality. The trend is most visible in ERCOT and CAISO territories where merchant storage developers compete on availability-based revenue streams rather than capital cost alone.
Second-Life EV Battery Market Segmentation
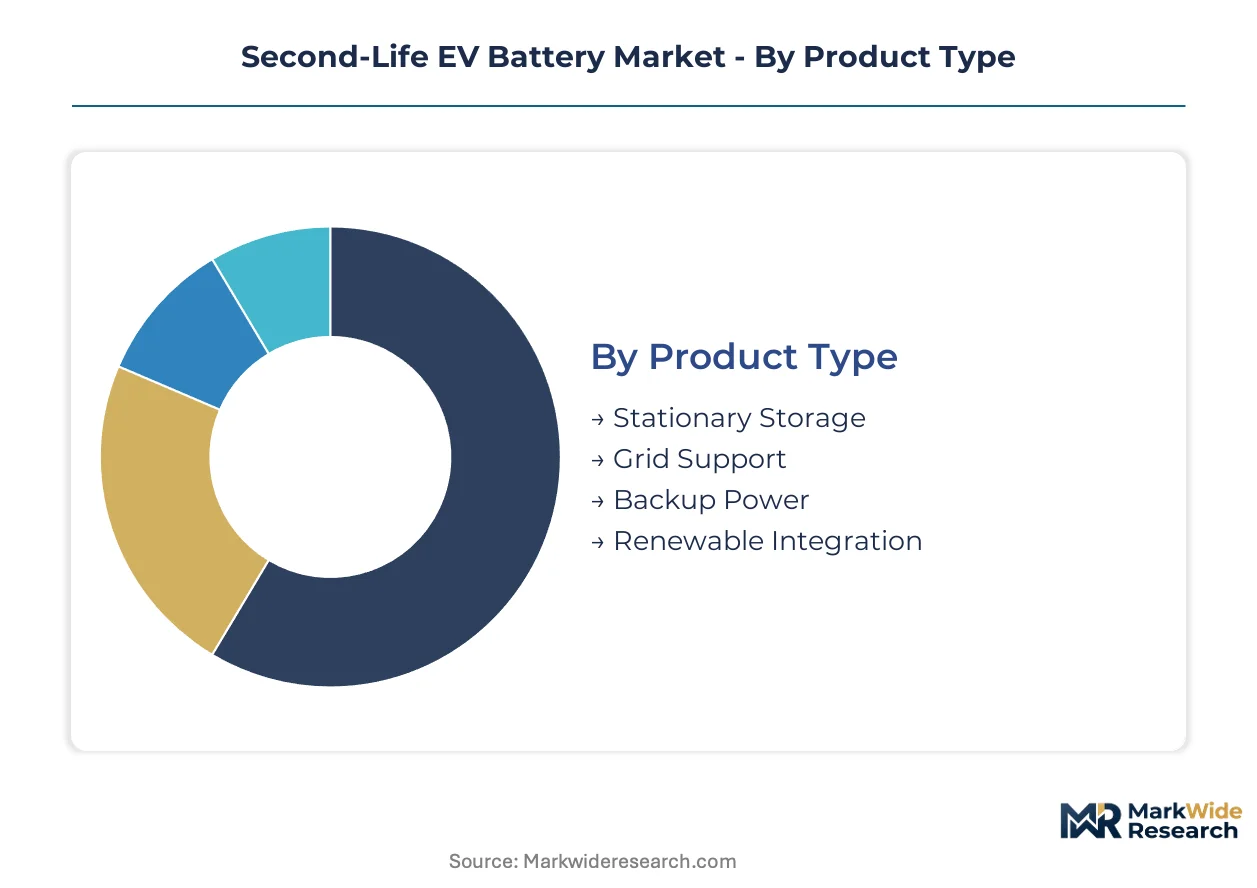
Segmentation in second-life EV batteries reveals how retired automotive cells fragment across divergent technical requirements and buyer sophistication. Each dimension carries distinct margin structures and certification burdens that reshape competitive positioning.
Product Type:
Use-case spectrum spans bulk capacity deployment to precision power quality services.
- Stationary Storage:Grid-scale installations aggregate thousands of retired modules for bulk energy arbitrage. Utilities in Texas and California concentrate procurement where availability payments reward rapid response capability.
- Grid Support:Frequency regulation and voltage stabilization services demand tighter cycling precision than bulk storage. ERCOT territory commands premium contracts for fast-ramp resources that second-life configurations increasingly satisfy.
- Backup Power:Commercial microgrids in Germany and the Netherlands absorb mid-grade retired packs for resilience against grid interruption.
- Renewable Integration:Solar and wind pairing requires storage that buffers intermittency without premium cycle life.
Established volume favors Stationary Storage; emerging adoption favors Grid Support.
Technology:
Cost tier stratification separates standardized diagnostics from bespoke electrochemical handling.
- Lithium-ion:Dominant technology stack benefiting from module standardization and established state-of-health protocols. Diagnostic automation in South Korea and the Netherlands now processes thousands of cells daily.
- Nickel-Metal Hydride:Legacy hybrid vehicle packs retain niche applications where thermal stability outweighs energy density requirements.
- Lead-Acid:Price-sensitive backup power segments in developing markets where recycling infrastructure remains immature.
- Flow Batteries:Vanadium and zinc-bromine chemistries occupy long-duration storage niches that second-life automotive cells rarely penetrate.
Lithium-ion captures installed base concentration; Flow Batteries claim steepest expansion trajectory in long-duration niches.
End User:
Customer type determines procurement sophistication and performance guarantee requirements.
- Utilities:Centralized procurement departments unbundle long-term service contracts from hardware supply, shifting performance risk toward repurposers.
- Commercial Buildings:Behind-the-meter installations in Germany absorb mid-grade retired packs for demand charge management and resilience.
- Residential Users:Home energy storage systems in California and Australia pair rooftop solar with compact second-life configurations.
- Automotive Sector:OEMs retain select retired packs for warranty replacement pools and internal testing infrastructure.
Utilities dominate contract value; Commercial Buildings are climbing the fastest in unit deployment.
Application:
Margin concentration tracks application maturity and regulatory incentive alignment.
- Energy Storage Systems:Bulk capacity deployment for wholesale market arbitrage and renewable firming.
- Electric Grid Services:Ancillary service contracts for frequency regulation command premium availability payments in deregulated markets.
- Load Shifting:Time-of-use rate optimization for commercial and industrial consumers facing volatile electricity pricing.
- Off-Grid Solutions:Remote power installations in Australia and island territories where transmission infrastructure costs prove prohibitive.
Electric Grid Services concentrate margin pools; Off-Grid Solutions are gaining share fastest in geographic pockets with infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive utilities in Texas and California absorb retired packs fastest, while European buyers facing strict EU Battery Regulation compliance timelines pay premiums for certified traceability. Chinese state-backed procurement operates with least price elasticity due to integrated grid modernization mandates.
United States
ERCOT and CAISO territories drive merchant storage deployment through availability-based revenue streams that reward rapid response capability. The EPA's evolving hazardous waste classifications condition how retired packs move between processing facilities and grid-scale installations. Austin and Houston clusters concentrate repurposing operations where diagnostic automation compresses grading timelines for utility offtake.
Germany
Behind-the-meter commercial microgrids in industrial zones absorb mid-grade retired packs for demand charge management and resilience against grid interruption. The EU Battery Regulation phases in mandatory recycled content thresholds and traceability systems between 2027 and 2030. The Ruhr Valley and Bavaria host grading facilities that maintain dual certification tracks for cross-border trade eligibility.
China
State-backed grid modernization programs concentrate demand for bulk stationary capacity with minimal price sensitivity compared to deregulated markets. MIIT circular economy standards converge with EU disclosure requirements on mandatory state-of-health documentation at battery retirement. Shandong and Guangdong provinces cluster processing infrastructure where cell matching and safety recertification operations scale to national deployment targets.
Netherlands
Commercial building installations prioritize mid-grade retired packs for resilience and time-of-use optimization in dense urban environments. REACH compliance and CE marking requirements shape how repurposed packs enter stationary storage service. The Randstad corridor hosts independent repurposers deploying machine-learning-based diagnostic platforms that assess thousands of modules daily.
South Korea
Domestic battery manufacturers extend into second-life services through captive supply relationships with utility procurement departments. MFDS alignment with IEC technical specifications enables export-oriented certification for regional secondary markets. The Seoul Capital Area concentrates diagnostic automation development where electrochemical impedance spectroscopy hybridizes with predictive analytics.
Second-Life EV Battery Market Competitive Environment
Capability concentration sits with diagnostic specialists who command grading premiums; scale advantage sits with integrated repurposers who aggregate thousands of modules for utility contracts. The market structures around three tiers: upstream material recovery operators, midstream grading and reconfiguration services, and downstream project developers who assume performance risk. Dominant competitive moves include backward integration into cathode precursor production and strategic partnerships that unbundle long-term service contracts from hardware supply.
Within the integrated repurposer tier, B2U Storage Solutions and Redwood Materials exemplify divergent paths to margin capture. Nissan Motor Corporation anchors the OEM-retained segment through proprietary battery health assessment protocols developed across fleet operations. Connected Energy occupies a position between pure-play graders and full-project developers, reflecting how European regulatory timelines favor operators with dual certification capabilities.
| Leading Market Players |
|---|
| Connected Energy |
| B2U Storage Solutions |
| Redwood Materials |
| Element Energy |
| Nissan Motor Corporation |
| Tesla |
| Rejoule |
| BeePlanet |
| Zenobē |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor compresses freight costs for retired battery pack consolidation, yet its rate volatility feeds directly into how European repurposers price certified traceability premiums against Asian competitors with integrated domestic supply chains.
Pricing Analysis
Aftermarket service revenue from extended performance guarantees now drives lifetime value capture for integrated repurposers. Project-based contracting with availability-linked payments dominates the structure, separating premium-tier certified packs from standard-grade inventory through UL 9540A fire safety completion status. Cost compression in mid-grade reconfiguration is intensifying because diagnostic automation in South Korea and the Netherlands accelerates throughput. Utilities in deregulated markets exhibit least price sensitivity due to merchant storage revenue streams, while commercial building operators in Germany absorb economy-tier pricing for behind-the-meter resilience applications.
Supply Chain Analysis
Extended payment terms from state-backed procurement programs in China anchor supplier financing structures for grading equipment vendors. Supply concentrates in China, South Korea, and the Netherlands, with cell-matching operations drawing from nickel sulfate, cobalt hydroxide, and lithium carbonate feedstocks. Single-source vulnerability in cathode precursor processing clusters threatens margin stability when commodity price swings accelerate. Distribution runs through utility procurement departments that unbundle hardware from long-term service contracts, shifting performance risk toward downstream project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Second-Life EV Battery Market tracks a cyclical recovery pattern tied to automotive fleet retirement waves, with OEM warranty expiration clusters creating predictable supply inflections.
For Market Incumbents: Build diagnostic automation moats through electrochemical impedance spectroscopy platforms that hybridize with predictive analytics. Incumbent repurposers should secure captive supply agreements with fleet operators facing EU Battery Regulation disclosure deadlines, while investing in dual-certification capabilities for cross-border trade eligibility. Threat substitution from new lithium iron phosphate production cost compression demands backward integration into cathode precursor production to defend margin pools. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point where grid infrastructure gaps create demand for off-grid resilience configurations. New entrants should target frequency regulation contract aggregation in ERCOT and CAISO territories where availability-based revenue streams reward rapid-response capability without requiring utility-scale balance sheets. A go-to-market angle through digital battery passport platforms that automate state-of-health documentation unlocks regulatory compliance premiums. For Investors and Strategic Acquirers: Independent grading specialists with IEC-aligned certification capabilities and machine-learning diagnostic platforms offer the strongest acquisition target profile for portfolio positioning across the analysis window. Long-term viability hinges on whether regulatory disclosure regimes fragment or converge, with mutual recognition agreements between EU Battery Regulation and China's MIIT standards serving as the critical inflection signal to monitor for secondary market liquidity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Production | Captures margin pools that OEMs once retained through upstream control over critical materials. |
| Digital Battery Passport Platform Development | Unlocks liquid secondary markets by automating state-of-health documentation for EU Battery Regulation compliance. |
| Dual-Certification Grading Facility Expansion | Enables cross-border trade eligibility between EU Battery Regulation and China's MIIT circular economy standards. |
| Frequency Regulation Contract Aggregation | Secures premium availability payments in ERCOT and CAISO territories where rapid-response capability commands revenue premiums. |
| Diagnostic Automation Platform Deployment | Compresses cell-level grading timelines through hybrid electrochemical impedance spectroscopy and machine-learning prediction systems. |
Study Parameters
The analysis maps stationary storage deployment, grid support services, backup power systems, and renewable integration configurations, each validated through utility procurement officers, repurposer operations directors, diagnostic platform engineers, and OEM sustainability leads. Primary interview data triangulates against secondary sources including EPA hazardous waste classification filings, EU Battery Regulation implementation guidance, MIIT circular economy standard documents, and FERC interconnection queue data. Bottom-up project pipeline aggregation and top-down automotive fleet retirement modeling cross-validate volume estimates.
Assumptions held fixed include regulatory disclosure phase-in timelines and lithium-ion module standardization trajectories, while variables span nickel-cobalt price volatility bands and utility procurement contract unbundling velocity. Segmentation dimensions modeled encompass product type, technology chemistry, end-user sophistication tier, and application maturity across the projection horizon. CAGRs derive from installed base retirement curves and repurposing cost learning rates, with grid modernization program budgets and frequency regulation market depth serving as industry-specific forecast anchors.
Practitioners should monitor regulatory mutual recognition negotiations and cathode material price volatility spikes for early signals of forecast deviation. Macroeconomic contraction in utility capital expenditure, regulatory fragmentation into incompatible national certification regimes, or breakthroughs in solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Power Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Electric Vehicle Battery Reuse and Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
India Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Process Market