
 Automotive Oil Recycling Market | 2026-2036
Automotive Oil Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Recycling Market Intelligence
Fleet operators and heavy-duty transport buyers are redrawing procurement priorities for re-refined lubricants, shifting volume away from individual vehicle owners toward centralized maintenance contracts. Safety-Kleen Systems leverages its national collection infrastructure to dominate direct-to-fleet channels. Waste Management anchors urban density markets with integrated hazardous waste logistics. Vertex Energy competes through specialized vacuum distillation capacity at its re-refinery locations.
Automotive oil recycling recovers base oils and additives from spent engine lubricants through processes such as vacuum distillation, which separates hydrocarbons at reduced atmospheric pressure to preserve thermal stability. The output yields API Group I and Group II base stocks suitable for reblending into commercial lubricants, industrial hydraulic fluids, and marine engine oils. Vacuum distillation leads recycling technology adoption due to its energy efficiency and ability to handle high volumes of contaminated feedstock, while chemical treatment segments command margin pools where additive recovery and color removal determine product grade. Filtration systems occupy a mature position serving smaller generators with lower capital requirements, though centrifugation is gaining share in regions with stricter water-content specifications.
EPA used oil management standards under 40 CFR Part 279 govern collection, storage, and transportation practices across the United States, while state-level generator responsibility laws in California and Texas impose cradle-to-grave tracking that elevates demand for authorized workshop and industrial collection point channels. OSHA workplace exposure limits and DOT hazardous materials shipping rules add compliance layers that favor vertically integrated collectors with in-house transportation certifications. Stakeholders must monitor how state-level low-carbon fuel standards and potential federal incentives for circular feedstocks reshape the economic calculus between re-refining for lubricant reuse and alternative fuel conversion pathways.
Market Dynamics
Used oil generator responsibility laws are concentrating collection volume through authorized networks, compressing informal channels and rewarding operators with cradle-to-grave tracking capabilities. Fleet maintenance centralization is accelerating feedstock aggregation at commercial scale.
Growth Catalysts
- 40 CFR Part 279 standards:EPA used oil management rules tighten storage and transportation practices, elevating demand for certified collection infrastructure across workshop and industrial channels.
- Re-refined lubricant quality parity:API Group II base stock yields from vacuum distillation now match virgin oil performance specifications, enabling direct substitution in heavy-duty engine applications.
- California generator responsibility mandates:State-level cradle-to-grave tracking requirements create structural volume pull through authorized collection points serving fleet operators.
Market Restraints
- Crude oil price volatility:Virgin base oil cost swings compress re-refining margins when benchmark crude drops below re-refinery breakeven thresholds.
- Contaminated feedstock variability:Inconsistent water, fuel, and solids content in collected used oil degrades vacuum distillation throughput and yields.
- Alternative fuel conversion competition:Re-refiners face displacement risk from used oil burners and cement kiln fuel markets offering simpler offtake terms.
Strategic Opportunities
- Texas industrial corridor expansion:Petrochemical cluster proximity offers re-refiners access to blending infrastructure and marine lubricant offtake contracts.
- Circular feedstock incentives:Potential federal tax credits for recycled content lubricants would improve re-refining economics versus fuel conversion pathways.
- Additive recovery technology:Advanced chemical treatment systems that extract and reconstitute antioxidant and detergent packages open premium product tiers.
Industry Challenges
- Vacuum distillation technician shortage:Specialized process engineering expertise for high-temperature hydrocarbon separation remains scarce in secondary materials sectors.
- Re-refinery certification timelines:API and SAE product qualification cycles extend 18-24 months, delaying commercialization of upgraded base stock grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Recycling Market |
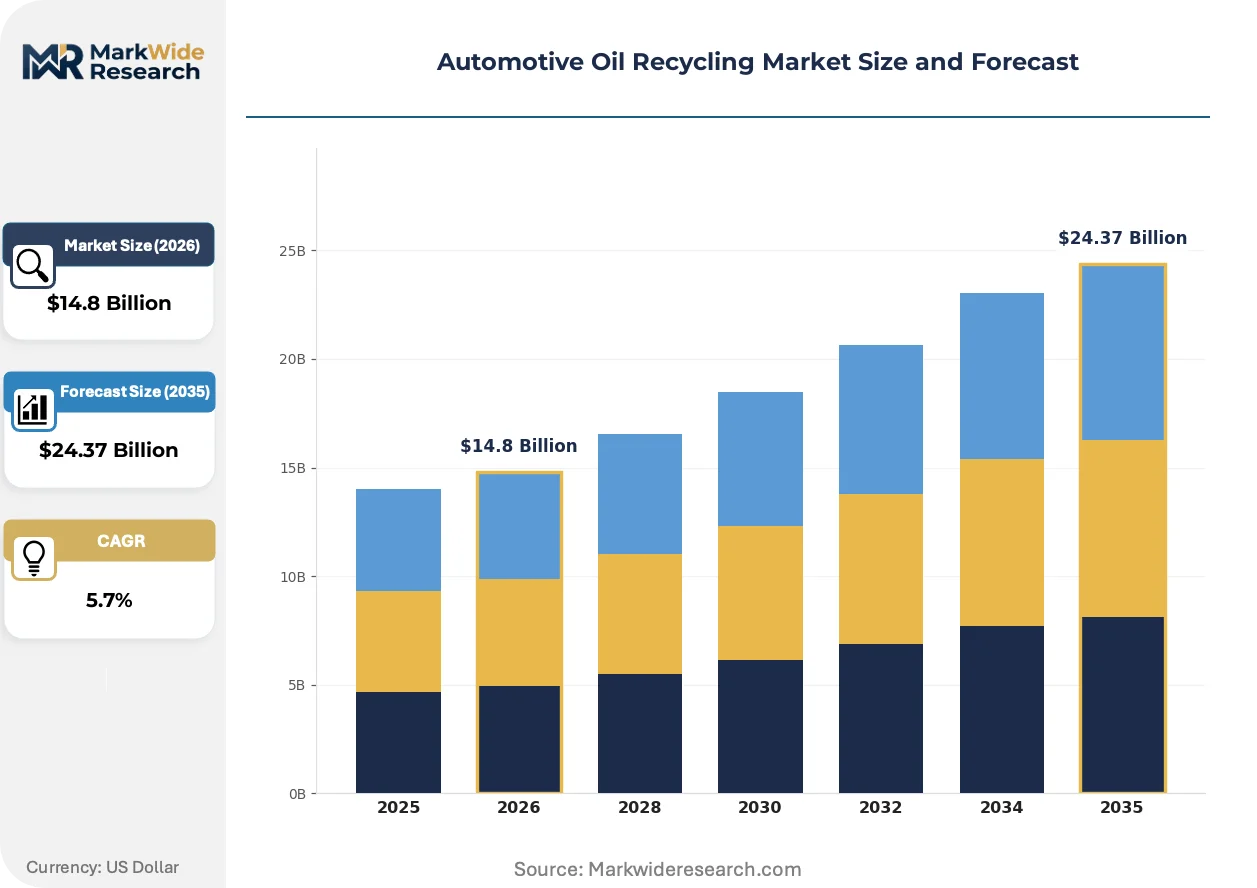
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Drop-off Centers, Mobile Collection Units, Authorized Workshops, Industrial Collection Points Recycling Technology: Vacuum Distillation, Centrifugation, Chemical Treatment, Filtration Systems End Use Industry: Manufacturing Plants, Power Generation Plants, Construction Sector, Agricultural Equipment Suppliers Distribution Channel: Direct Sales, Online Platforms, Third-Party Distributors, Retail Outlets |
| Companies Covered | Safety-Kleen Systems, Inc., Waste Management, Vertex Energy, Inc., Heritage-Crystal Clean, LLC, Veolia Environnement, Clean Harbors, NexLube, World Oil Corp, GFL Environmental Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Recycling Market Strategic Shifts & Innovations
Automotive oil recycling is transitioning from waste management to circular manufacturing, with technology and policy convergence redefining asset valuation across the value chain.
Hydrofinishing technology is displacing acid-clay treatment as the dominant re-refining pathway for color removal and sulfur reduction. Commercial fleet operators and marine lubricant blenders are adopting hydrofinished Group II base stocks for extended drain interval formulations. This shift is compressing capital deployment timelines for legacy acid-clay facilities while rewarding operators with hydrogen supply integration.
EPA is reviewing state-level low-carbon fuel standard petitions that would credit re-refined lubricants as circular feedstocks. The regulatory reconsideration creates compliance pathway uncertainty for re-refiners currently optimizing for lubricant reuse versus fuel conversion. California and Oregon program expansions would most directly affect base oil pricing in western US markets.
Fleet maintenance contracts are consolidating lubricant procurement under national service agreements with embedded used oil collection terms. Independent quick-lube operators and smaller automotive repair chains are losing direct supplier relationships as volume aggregates at centralized fleet management platforms. This concentration is most visible in Class 8 trucking and municipal bus fleets across the southeastern United States.
Automotive Oil Recycling Market Segmentation
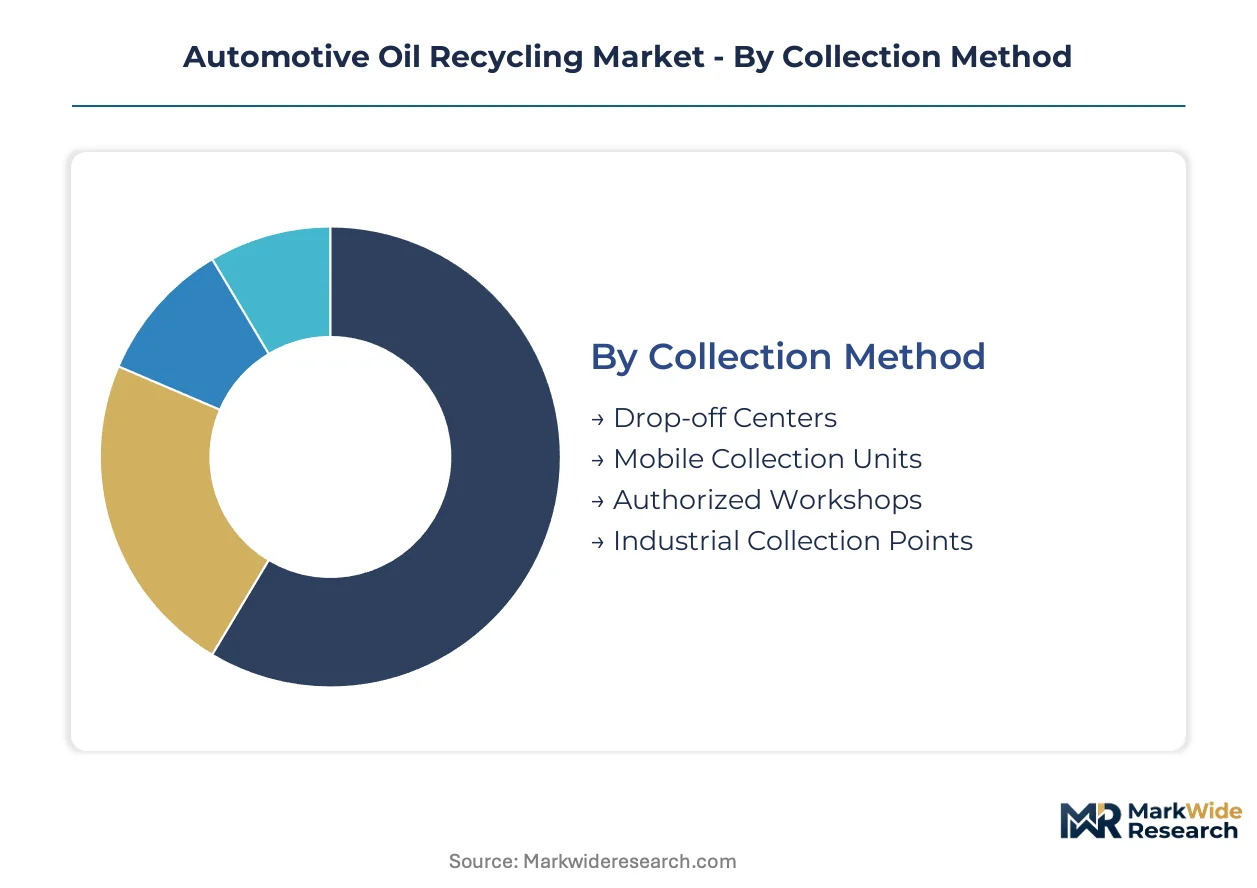
Segmentation in automotive oil recycling reveals how collection logistics, processing technology, and end-use specifications create distinct competitive arenas. Each dimension carries different capital intensity requirements and regulatory exposure, shaping where new entrants can build viable positions.
Collection Method:
Substitute pressure runs highest where informal channels compete with authorized networks on convenience and cost.
- Drop-off Centers:Fixed-location facilities serving individual vehicle owners and small repair shops with minimal infrastructure investment. Demand concentrates in California and Texas where generator responsibility laws mandate documented chain-of-custody; EPA 40 CFR Part 279 storage standards elevate compliance costs for unauthorized competitors.
- Mobile Collection Units:Fleet-based services deploying vacuum trucks to industrial generators and commercial maintenance yards. Volume aggregates at Class 8 trucking terminals across the southeastern United States as national fleet management platforms consolidate lubricant procurement contracts.
- Authorized Workshops:Certified automotive service centers with cradle-to-grave tracking capabilities integrated into repair management systems. OSHA workplace exposure limits and DOT hazardous materials certifications filter out smaller independent operators.
- Industrial Collection Points:Large-scale aggregation hubs serving manufacturing plants and power generation facilities with bulk tankage and real-time inventory monitoring. Proximity to petrochemical clusters in Texas and Louisiana determines throughput economics.
Drop-off Centers retain volume leadership; Mobile Collection Units hold the steepest expansion curve.
Recycling Technology:
Cost tier stratification separates capital-intensive re-refiners from lower-barrier filtration operators.
- Vacuum Distillation:Reduced-atmosphere hydrocarbon separation yielding API Group I and Group II base stocks with preserved thermal stability. Demand concentrates in heavy-duty engine applications where quality parity with virgin lubricants enables direct substitution; hydrogen supply integration determines margin capture for hydrofinishing upgrades.
- Chemical Treatment:Additive recovery and color removal systems commanding premium pricing where antioxidant and detergent package reconstitution opens differentiated product tiers. Feedstock variability in water and solids content constrains throughput consistency.
- Filtration Systems:Mature mechanical separation technology serving smaller generators with lower capital requirements and minimal regulatory exposure. Regional markets with less stringent water-content specifications sustain equipment deployment.
- Centrifugation:High-speed density separation gaining adoption where moisture reduction specifications tighten for marine lubricant and industrial hydraulic fluid reblending. European ECHA chemical safety standards and emerging state-level low-carbon fuel programs shape technology selection.
Vacuum Distillation retains volume leadership; Chemical Treatment holds the steepest expansion curve.
End Use Industry:
Application requirements dictate base stock grade specifications and additive package complexity.
- Manufacturing Plants:Industrial hydraulic fluid and metalworking lubricant demand from machinery maintenance operations. Volume aggregates at automotive and aerospace production facilities in Michigan and Ohio.
- Power Generation Plants:Turbine oil and transformer fluid replacement cycles creating predictable feedstock supply and offtake demand. Combined-cycle natural gas facilities in Texas and Pennsylvania anchor procurement.
- Construction Sector:Mobile equipment fleets with severe-service lubricant requirements and decentralized maintenance patterns. Highway and infrastructure project concentration in Florida and California determines regional collection density.
- Agricultural Equipment Suppliers:Seasonal demand spikes from planting and harvest cycles with dispersed rural generator locations. Dealer network consolidation in Iowa and Illinois compresses informal collection channels.
Manufacturing Plants retain volume leadership; Power Generation Plants holds the steepest expansion curve.
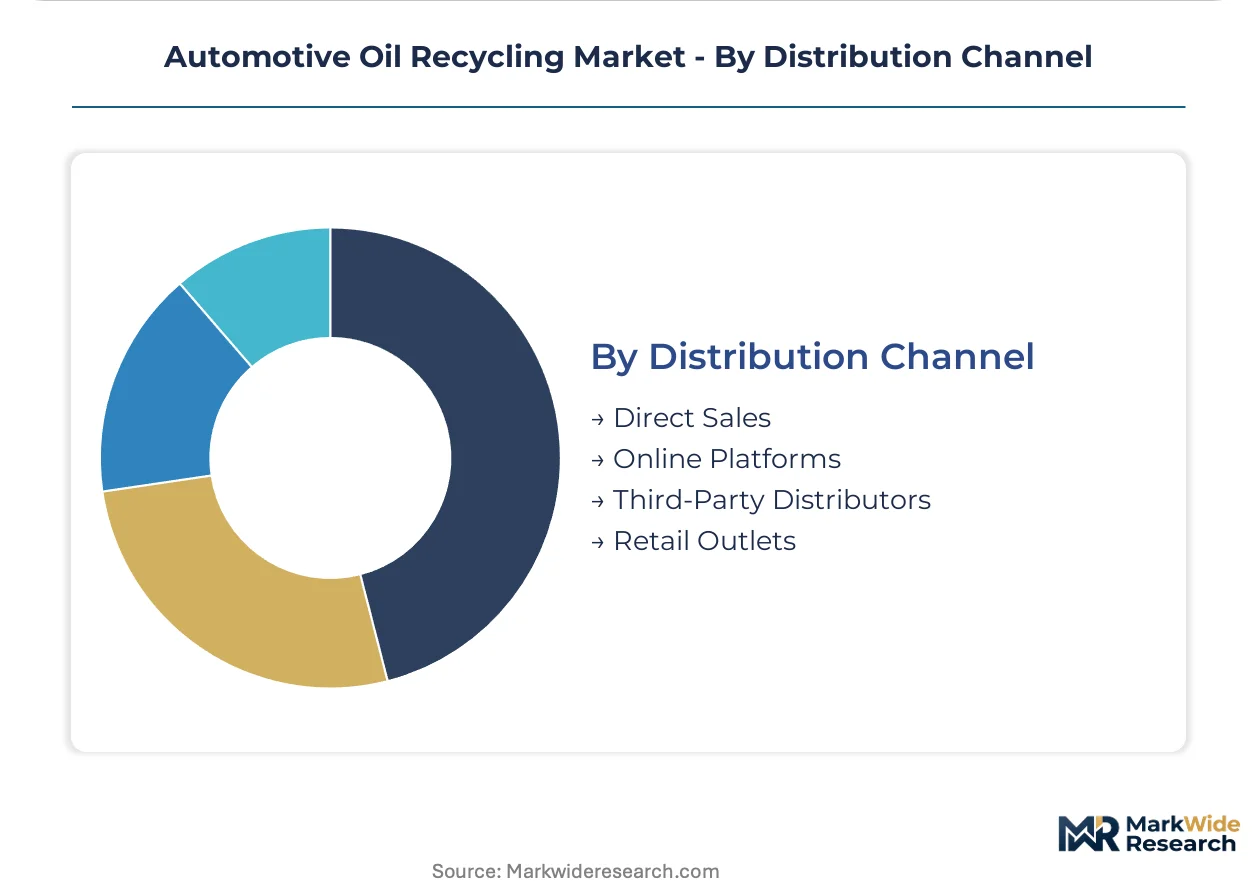
Distribution Channel:
Customer type concentration shapes channel economics and relationship requirements.
- Direct Sales:Long-term supply agreements with fleet operators and industrial blenders embedding used oil collection terms. National service contract consolidation in Class 8 trucking elevates scale requirements.
- Third-Party Distributors:Regional logistics providers bridging re-refiners and smaller commercial accounts with inventory management services. Network density in urban corridors determines competitive position.
- Online Platforms:Digital procurement interfaces for standardized product grades with transparent pricing and documented sustainability credentials. California and Oregon low-carbon fuel program participation drives platform adoption.
- Retail Outlets:Consumer-facing channels for DIY vehicle owners with minimal volume per transaction. Auto parts chain consolidation compresses independent quick-lube direct supplier relationships.
Direct Sales retains volume leadership; Online Platforms holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and heavy-duty transport buyers concentrate procurement decisions in markets with stringent generator responsibility frameworks. Re-refined lubricant demand clusters where cradle-to-grave tracking laws compress informal collection channels and reward authorized network density.
United States
Class 8 trucking terminals and municipal bus fleets drive volume aggregation through national maintenance contracts. EPA 40 CFR Part 279 standards govern storage and transportation practices, elevating compliance costs for unauthorized collectors. The Texas-Louisiana petrochemical corridor anchors re-refining capacity, with marine lubricant blenders sourcing hydrofinished Group II base stocks from regional facilities.
Germany
Automotive OEMs and industrial machinery manufacturers specify re-refined content in sustainability procurement mandates. ECHA REACH regulations govern chemical safety in additive recovery processes, shaping technology selection for color removal systems. The Rhine-Ruhr industrial cluster concentrates vacuum distillation capacity serving hydraulic fluid demand from machinery maintenance operations.
China
State-owned fleet operators and construction equipment lessors expand re-refined lubricant procurement under circular economy targets. MEE environmental compliance inspections tighten used oil collection documentation requirements. The Yangtze River Delta manufacturing belt generates feedstock from automotive and aerospace production facilities in Jiangsu and Zhejiang provinces.
Japan
Precision manufacturing plants and power generation utilities specify extended-drain interval formulations with re-refined base stocks. METI circular economy roadmaps incentivize lubricant reuse over fuel conversion pathways. The Chubu region around Nagoya concentrates metalworking lubricant demand from automotive component suppliers.
India
Commercial vehicle fleet operators and agricultural equipment dealers expand authorized collection network participation. CPCB hazardous waste management rules impose cradle-to-grave tracking on used oil generators above threshold volumes. The Delhi-Mumbai Industrial Corridor anchors industrial collection point infrastructure for manufacturing plant feedstock aggregation.
Automotive Oil Recycling Market Key Industry Players
Player mix skews toward vertically integrated waste management conglomerates with hazardous transportation certifications. Three to five national operators control authorized collection network density, while regional specialists compete on vacuum distillation technology differentiation. Strategic moves center on fleet maintenance contract consolidation and hydrogen supply integration for hydrofinishing upgrades.
Among North American integrated collectors, Safety-Kleen Systems, Inc. and Waste Management exemplify the scale-driven archetype with national logistics infrastructure. Vertex Energy, Inc. occupies a specialist position in vacuum distillation capacity deployment. These three companies represent the competitive spectrum from collection network dominance to re-refining technology focus.
| Leading Market Players |
|---|
| Safety-Kleen Systems, Inc. |
| Waste Management |
| Vertex Energy, Inc. |
| Heritage-Crystal Clean, LLC |
| Veolia Environnement |
| Clean Harbors |
| NexLube |
| World Oil Corp |
| GFL Environmental Inc. |
| Others |
Cost & Logistics Intelligence
API Group I and Group II certification tiers gate both supply qualification and price differentiation simultaneously, as blenders demand documented base stock grades for heavy-duty engine formulations while re-refiners command premiums for hydrofinished outputs meeting virgin oil parity specifications.
Pricing Analysis
Cost-plus contracts with Group II base oil indexation dominate long-term offtake agreements between re-refiners and marine lubricant blenders. Price differentiation hinges on hydrofinishing certification grade and volume scale commitments, with fleet operators securing favorable terms through embedded collection-service bundling. Pricing pressure intensifies in standard-grade segments as acid-clay legacy capacity competes for feedstock against fuel conversion pathways. Independent quick-lube operators exhibit highest price sensitivity, while national fleet management platforms prioritize supply security over unit cost.
Supply Chain Analysis
Inventory cycles for vacuum distillation feedstock stretch 45-60 days as seasonal construction activity and harvest patterns create collection surges. Supply concentrates in the United States, Germany, and China, where generator responsibility laws compress informal channels. The chain draws from spent automotive lubricants, industrial hydraulic fluids, and marine engine oils as primary inputs. Single-source vulnerability looms where regional vacuum truck fleets serve exclusive territories. Distribution runs through direct sales agreements with fleet operators and industrial blenders, bypassing fragmented third-party distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive oil recycling functions as a service-attach opportunity where cradle-to-grave collection contracts expand faster than standalone re-refining capacity, as fleet operators demand integrated maintenance logistics over commodity base oil procurement.
For Market Incumbents: Secure hydrogen supply integration for hydrofinishing upgrades before regional petrochemical clusters exhaust spare capacity. Defend mobile collection unit density in southeastern Class 8 trucking corridors against emerging regional specialists. Vertical integration into authorized workshop certification programs creates switching costs for fleet maintenance contracts. For New Entrants and Emerging Players: Anchor in centrifugation technology serving marine lubricant blenders with tightening moisture specifications, a segment where capital requirements trail vacuum distillation by half. Target industrial collection points in the Texas-Louisiana petrochemical corridor where proximity to blending infrastructure accelerates offtake negotiations. Lead with real-time inventory monitoring platforms that differentiate against legacy paper-based tracking systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrofinishing upgrade cycles as hydrogen supply integration becomes mandatory for Group II parity. Five-to-ten year viability favors operators with captive fleet maintenance contract pipelines over pure-play re-refiners exposed to crude oil price volatility. Acquisition targets should display vacuum distillation capacity utilization above regional benchmarks. Watch for EPA low-carbon fuel standard petitions as the inflection signal reshaping economics between lubricant reuse and fuel conversion pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Supply Integration | Hydrofinishing upgrades for Group II base stock parity lock in premium pricing from marine lubricant blenders. |
| Fleet Maintenance Contract Consolidation | National service agreements embed used oil collection terms that secure predictable feedstock volumes. |
| Authorized Workshop Certification | EPA 40 CFR Part 279 compliance credentials filter out informal competitors in California and Texas markets. |
| Additive Recovery Technology Investment | Chemical treatment systems that reconstitute antioxidant packages open differentiated product tiers. |
| Petrochemical Cluster Proximity Expansion | Texas-Louisiana corridor access reduces blending logistics costs for industrial hydraulic fluid offtake. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with re-refinery operations managers, fleet procurement directors, and hazardous waste logistics coordinators, combined with secondary validation against EPA enforcement data, state environmental agency filings, and base oil pricing benchmarks. Bottom-up triangulation across collection volume estimates and top-down reconciliation with re-refining capacity utilization rates anchored value projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning recycling technology type, collection method, end-use industry vertical, and distribution channel structure. CAGRs were derived from regression analysis against crude oil price scenarios and regulatory compliance cost trajectories. Forecast inputs incorporated vacuum distillation yield rates and fleet maintenance contract renewal velocities as industry-specific demand indicators.
Material uncertainties — crude oil price volatility, EPA low-carbon fuel standard rulings, and hydrogen supply cost trajectories — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Asia-Pacific Battery Recycling Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Lithium Recycling Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Nickel-Cadmium Battery Recycling Market
Battery Recycling
Battery Recycling Process Quality and Purity Test Instruments Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Equipment Market
Battery Recycling
Prepaid Battery Recycling Market
Battery Recycling
Lead Acid Battery Recycling Market
Battery Recycling
EV Battery Reuse Market