
 Solar Backsheet Market | 2026-2036
Solar Backsheet Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Backsheet Market Analysis
Module supplier procurement is rewriting competitive access across the solar backsheet landscape. DuPont de Nemours Inc. leverages fluoropolymer chemistry leadership to sustain premium positioning in high-reliability applications. Taiflex Scientific Co. Ltd. anchors volume supply across Asia-Pacific manufacturing corridors. Isovoltaic AG differentiates through European-certified production lines serving utility-scale developers with stringent durability requirements.
A solar backsheet is the outermost protective layer laminated to the rear surface of photovoltaic modules, typically constructed as a multi-layer polymer film with thickness ranging from 250 to 350 microns and dielectric strength exceeding 15 kV to ensure electrical isolation and environmental shielding. Its primary function is to block moisture ingress, resist ultraviolet degradation, and provide mechanical support across a 25-year operational lifespan. Polyester-based constructions occupy the cost-sensitive mass market tier, while Tedlar-fluoropolymer composites command margin pools in desert and coastal installations where thermal cycling and salt corrosion accelerate material fatigue. Utility-scale Projects represent the dominant end-user channel by installed capacity, though Building-integrated Photovoltaics is gaining specification share as architectural glass-integrated designs proliferate in commercial construction.
China's NMPA-equivalent materials standards, the EU's RoHS restrictions on hazardous substances, and the IEC 61215 qualification sequence collectively dictate product certification requirements and cross-border market access for backsheet manufacturers. REACH compliance in Europe and evolving EPA toxicity evaluations in the United States are elevating testing burdens for fluorinated polymer formulations. Stakeholders must monitor regulatory divergence between jurisdictions as material substitution timelines and recycling mandates reshape supplier qualification protocols.
Market Dynamics
Fluoropolymer backsheet formulations are compressing pricing power across the mid-tier supplier base as module manufacturers consolidate procurement around certified multi-layer constructions. This chemistry migration is redrawing competitive boundaries between PET-based commodity producers and fluorinated specialty film suppliers.
Growth Catalysts
- China's dual carbon goals:National renewable energy mandates are accelerating utility-scale solar farm deployment, concentrating module production capacity in Jiangsu and Anhui provinces.
- Building-integrated photovoltaics:Architectural glass-integrated designs are expanding addressable surface area beyond traditional rooftop installations into commercial facades.
- IEC 61215 qualification sequence:Harmonized testing protocols are reducing cross-border certification friction for backsheet manufacturers seeking multi-jurisdiction market access.
Market Restraints
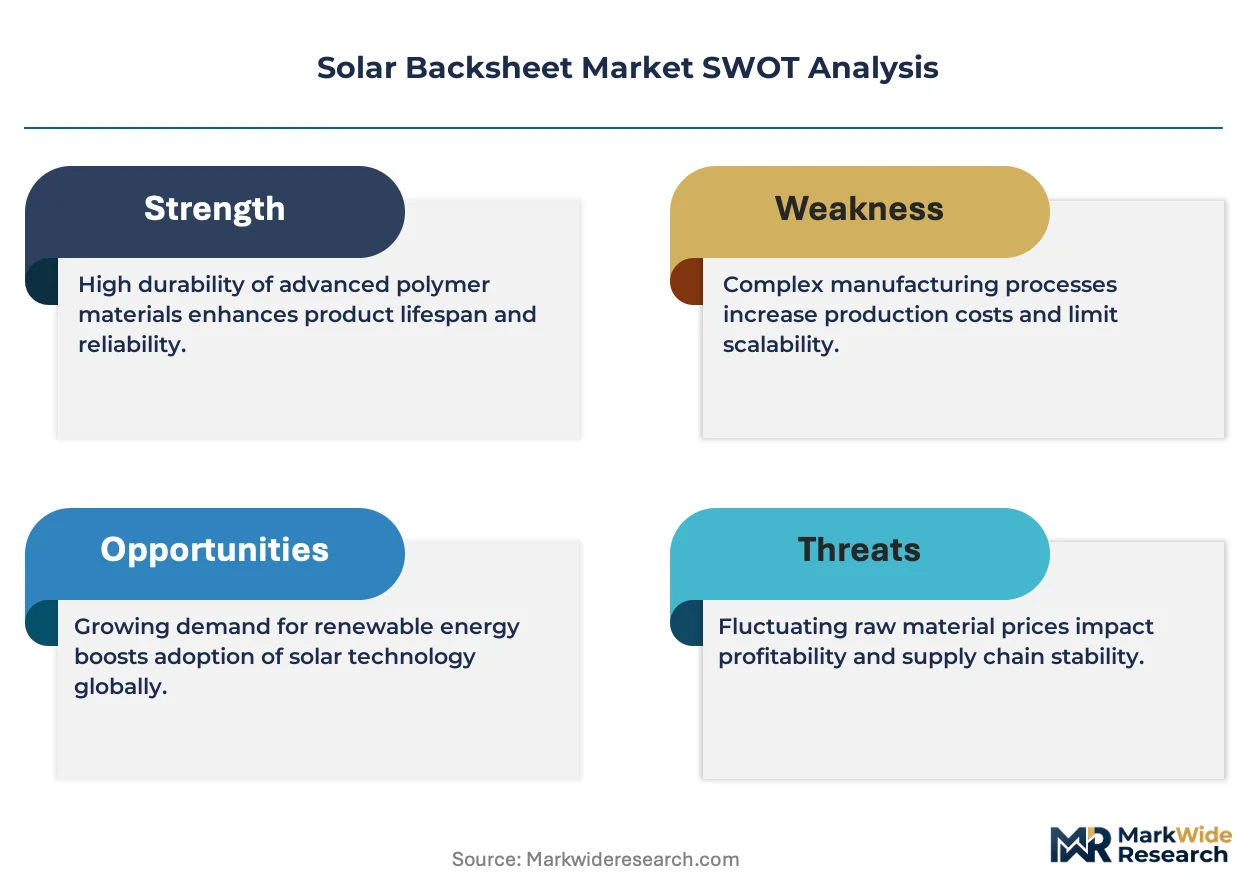
- PVDF resin supply concentration:Fluoropolymer feedstock production clusters in select chemical manufacturing corridors, exposing backsheet makers to input cost volatility and allocation constraints.
- REACH F-Gas Regulation:European restrictions on fluorinated greenhouse gases are elevating compliance burdens and extending reformulation timelines for fluoropolymer-based constructions.
- Glass-glass module substitution:Frameless bifacial designs using tempered rear glass are eliminating backsheet requirements entirely in premium utility-scale segments.
Strategic Opportunities
- India's PLI scheme:Production-linked incentive frameworks for solar module manufacturing are attracting backsheet suppliers to establish domestic lamination capacity.
- Recyclable mono-material constructions:Single-polymer backsheet designs compatible with existing PV module recycling infrastructure are opening circular economy service revenue streams.
- Desert climate specialization:Thermal cycling-resistant formulations for Middle Eastern and North African installations command durability premiums in high-irradiance environments.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise spanning fluoropolymer adhesion, UV stabilization, and dielectric engineering concentrates in aging workforce cohorts.
- 25-year warranty liability:Accelerated aging test protocols require extended validation cycles before commercial rollout, compressing product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Backsheet Market |
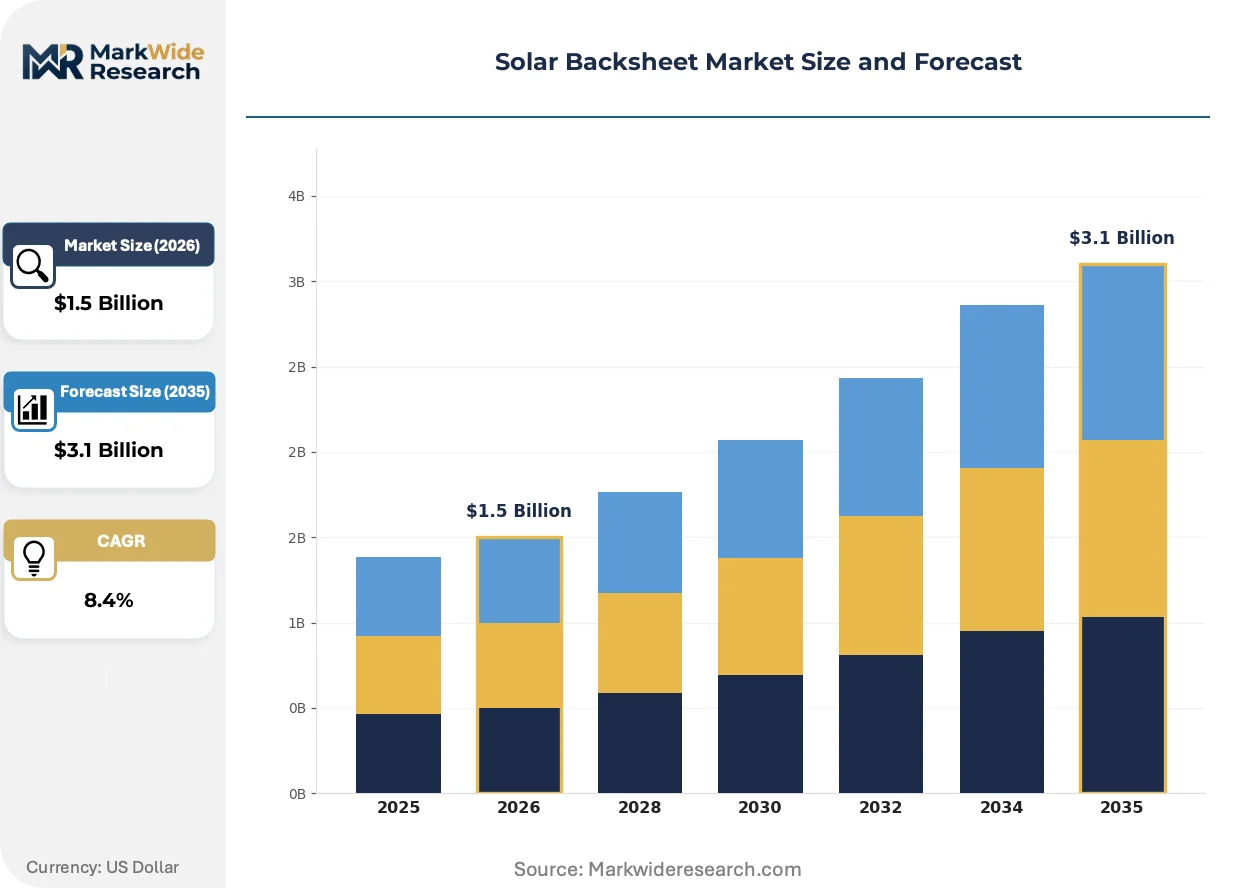
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $3.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Polyvinyl Fluoride, Polyethylene, Tedlar End User: Utility-scale Projects, Residential Installations, Commercial Installations, Off-grid Systems Application: Photovoltaic Modules, Building-integrated Photovoltaics, Concentrated Solar Power, Solar Thermal Systems Thickness: Thin Film, Flexible, Standard, High Performance |
| Companies Covered | Arkema SA, Taiflex Scientific Co. Ltd., DuPont de Nemours Inc., Madico Inc., Toyo Aluminium KK, Isovoltaic AG, 3M Co., Krempel GmbH, Coveme SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Backsheet Market Emerging Trajectories
Co-extruded multi-layer manufacturing is collapsing the cost gap between fluoropolymer and polyester constructions while preserving performance differentiation. This process innovation is enabling suppliers to reposition across pricing tiers without fundamental chemistry changes.
Coated fluoropolymer films are virtualizing traditional lamination steps by integrating adhesive and barrier functions into single-pass deposition processes. Tier-1 module suppliers in China are adopting these constructions to reduce manufacturing cycle time and capital intensity. The technology is virtualizing the historical distinction between captive in-house lamination and merchant backsheet supply.
Europe's F-Gas Regulation is forcing reformulation of PVDF-based backsheet constructions to reduce greenhouse gas emission profiles across the product lifecycle. Manufacturers serving EU utility-scale developers are accelerating pilot production of hydrofluoroolefin alternatives and non-fluorinated barrier coatings. German and Spanish project developers are now specifying low-GWP material grades in procurement tenders.
Module supplier consolidation is compressing backsheet vendor lists as procurement teams centralize qualification around dual-source strategies with stringent bankability requirements. Long-term supply agreements with volume commitments are displacing spot market transactions. This concentration is most visible in China, where the top five module producers now control the majority of global backsheet specification authority.
Solar Backsheet Market Segmentation
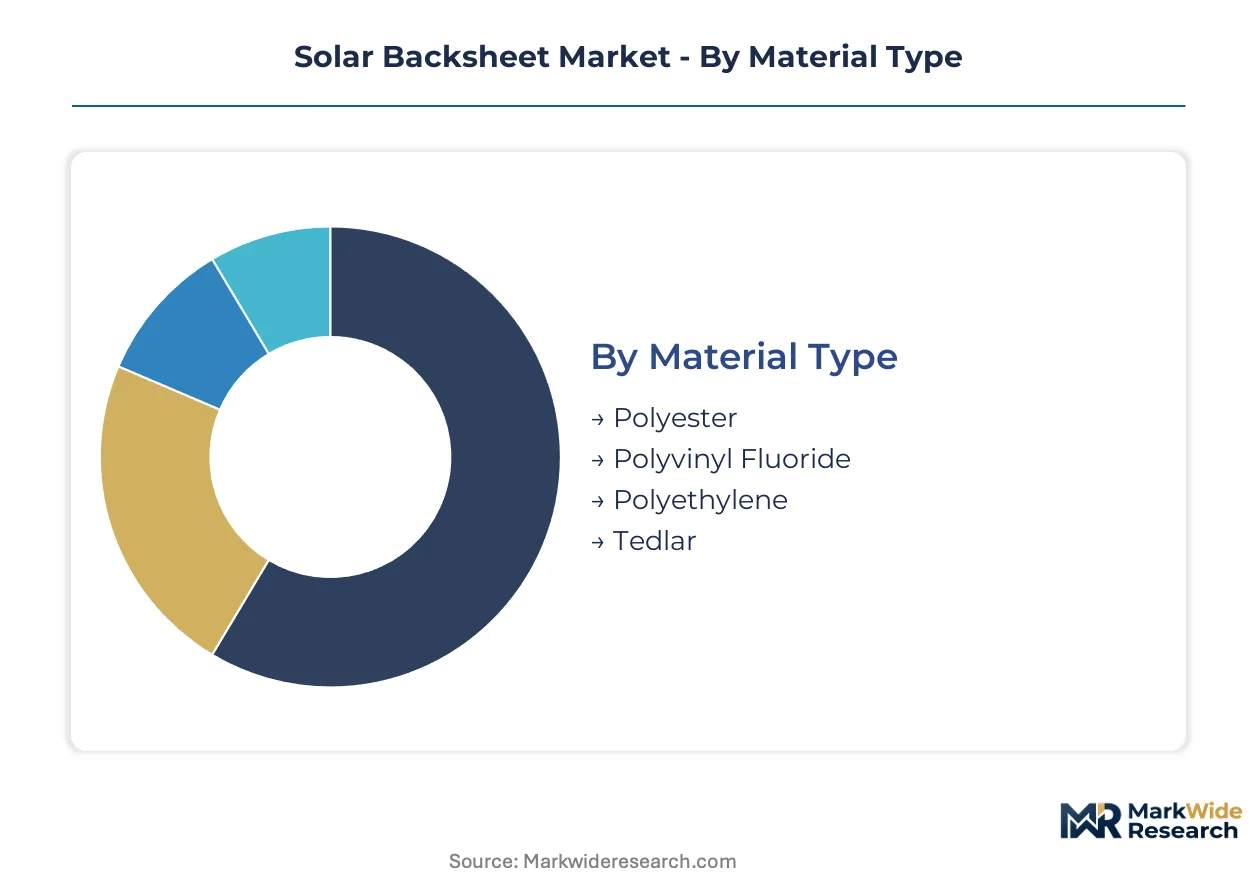
Backsheet specification diverges sharply across installation environments and module architectures. Material chemistry, thickness profiles, and end-use durability requirements create distinct procurement channels that suppliers must navigate simultaneously.
Material Type:
Cost tier and performance durability split procurement decisions across the four primary chemistries.
- Polyester:Multi-layer polyethylene terephthalate constructions dominate mass-market module production with dielectric ratings above 15 kV. Chinese module manufacturers in Jiangsu province consume the majority of global PET backsheet volume for domestic utility-scale deployment.
- Polyvinyl Fluoride:PVDF-based fluoropolymer films deliver superior UV resistance and thermal cycling performance for desert and coastal installations. REACH F-Gas Regulation compliance costs are accelerating reformulation timelines for European-bound supply.
- Polyethylene:Co-extruded polyethylene barriers serve cost-optimized distributed generation segments with simplified lamination requirements.
- Tedlar:DuPont's polyvinyl fluoride chemistry anchors premium reliability tiers with proven 25-year field performance in extreme climates.
Polyester commands the established base. The steepest expansion runs through Polyvinyl Fluoride as durability specifications tighten.
End User:
Customer type determines volume scale, certification burden, and contract structure.
- Utility-scale Projects:Centralized solar farms above 50 MW capacity specify bankable backsheet constructions with IEC 61215 qualification and extended warranty coverage. Procurement teams at Chinese developers in Anhui province centralize multi-gigawatt supply agreements around dual-source qualification.
- Residential Installations:Distributed rooftop systems prioritize cost efficiency and rapid installation compatibility. European residential installers favor lightweight constructions compatible with existing mounting hardware.
- Commercial Installations:Building-integrated and rooftop commercial projects balance aesthetic requirements with fire safety certifications.
- Off-grid Systems:Remote and rural electrification applications emphasize mechanical robustness and simplified logistics over standardized certification.
Utility-scale Projects anchor volume concentration. The fastest growth trajectory cuts through Residential Installations as distributed generation policy support expands.
Application:
Module architecture dictates barrier requirements, thermal management, and integration complexity.
- Photovoltaic Modules:Conventional crystalline silicon panels represent the core addressable market with standardized 250-350 micron backsheet specifications. Jiangsu-based module production lines consume the majority of merchant supply.
- Building-integrated Photovoltaics:Architectural glass-integrated designs require specialized aesthetic finishes and enhanced fire ratings for commercial facade deployment.
- Concentrated Solar Power:High-temperature mirror and receiver systems demand thermal stability beyond standard photovoltaic operating ranges.
- Solar Thermal Systems:Collector applications utilize modified barrier constructions optimized for heat transfer fluid compatibility.
Photovoltaic Modules retain volume dominance. Building-integrated Photovoltaics is gaining specification share fastest as architectural integration proliferates.
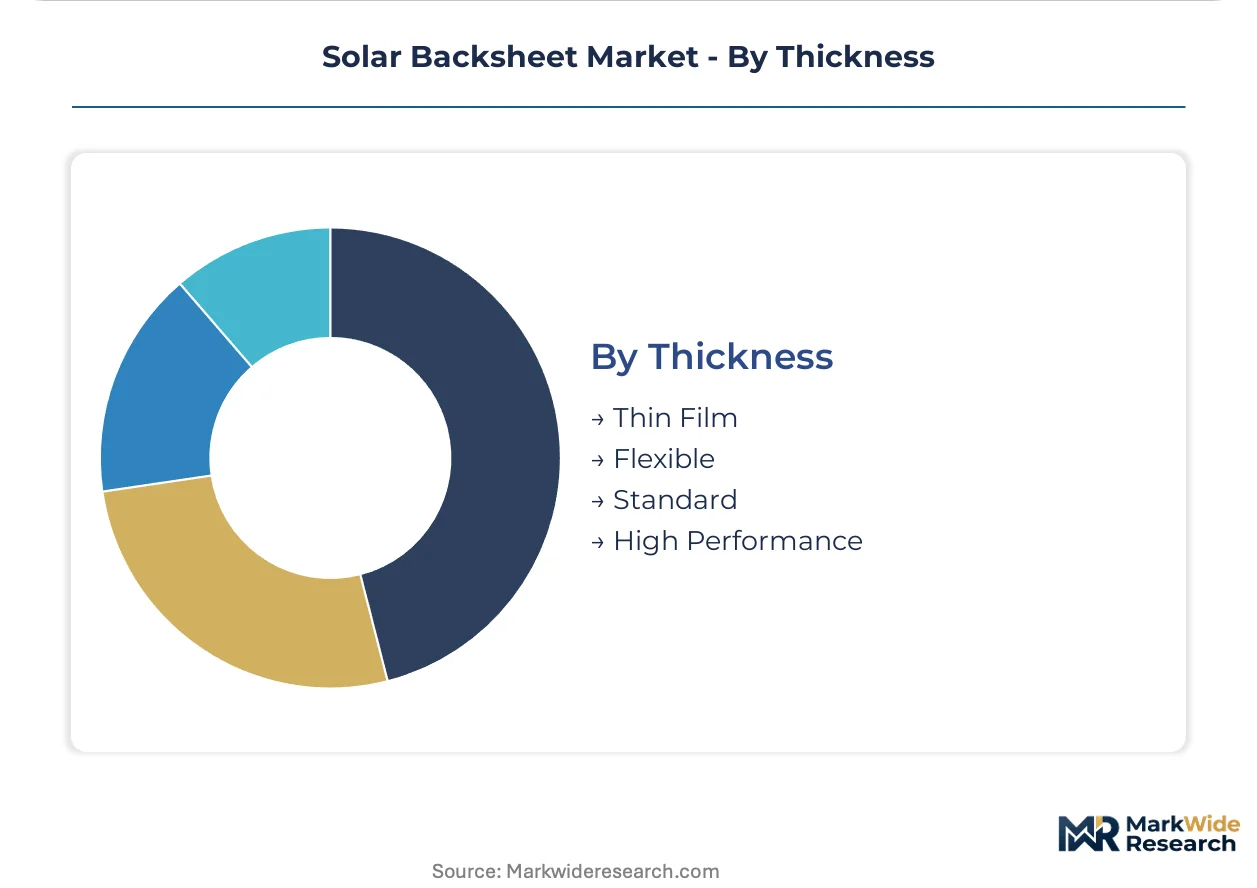
Thickness:
Mechanical performance and manufacturing flexibility segment the specification range.
- Thin Film:Sub-250 micron constructions reduce material cost and module weight for weight-constrained rooftop applications.
- Flexible:Conformable backsheet films enable curved and building-integrated installations with non-standard module geometries.
- Standard:250-350 micron multi-layer laminates balance dielectric strength, mechanical durability, and processing compatibility for conventional framed modules.
- High Performance:Enhanced thickness and barrier constructions target extreme climate installations with accelerated thermal cycling and humidity exposure.
Standard thickness retains procurement majority. High Performance specifications are climbing fastest as warranty periods extend and climate resilience requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's renewable energy corridor underwrites Europe's role as a distribution hub for fluoropolymer feedstocks serving module manufacturers. Grid interconnect capacity at Jiangsu's coastal industrial zones anchors Asia-Pacific production gravity.
China
Utility-scale solar farm deployment in Anhui province and Jiangsu manufacturing corridors drives backsheet consumption at multi-gigawatt scale. The dual carbon goals mandate issued by MEE accelerate module production capacity expansion. Suzhou-based lamination facilities consume the majority of global PET and fluoropolymer backsheet supply for domestic and export markets.
Germany
Utility-scale developers in Bavaria and North Rhine-Westphalia specify IEC 61215-qualified constructions with extended warranty coverage for bankability requirements. REACH F-Gas Regulation compliance enforced by ECHA elevates reformulation timelines for PVDF-based supply. Frankfurt-Rhine-Main logistics clusters coordinate feedstock distribution for Central European module assembly operations.
United States
Desert solar installations in Arizona and Nevada command thermal cycling-resistant formulations for extreme climate durability. EPA toxicity evaluations under TSCA influence fluorinated polymer qualification protocols for domestic supply. Texas-based module assembly corridors near Houston's petrochemical hub source barrier films for utility-scale project pipelines.
India
Production-linked incentive schemes administered by MNRE attract backsheet suppliers to establish domestic lamination capacity alongside module manufacturing. BIS certification requirements for solar components create localized qualification barriers. Gujarat's Special Economic Zone clusters host emerging backsheet conversion facilities serving western Indian solar parks.
Japan
Building-integrated photovoltaic specifications in Tokyo and Osaka metropolitan areas prioritize aesthetic finishes and fire safety certifications for commercial facade deployment. METI's renewable energy feed-in tariff frameworks sustain distributed generation installation rates. Kyushu-based module manufacturers source high-reliability constructions for coastal and island installations.
Solar Backsheet Market Vendor Landscape
On the supply side, the industry is consolidating around dual-source procurement strategies with stringent bankability requirements. Tier-1 module manufacturers centralize vendor qualification lists, compressing merchant backsheet access. Three strategic archetypes dominate: fluoropolymer chemistry specialists, volume-oriented PET converters, and integrated captive producers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure long-term supply agreements.
Among chemistry-focused specialists, DuPont de Nemours Inc. occupies a position exemplifying premium-tier fluoropolymer reliability, while Taiflex Scientific Co. Ltd. anchors volume supply across Asia-Pacific manufacturing corridors. Isovoltaic AG represents European-certified production capabilities serving utility-scale developers with stringent durability requirements.
| Leading Market Players |
|---|
| Arkema SA |
| Taiflex Scientific Co. Ltd. |
| DuPont de Nemours Inc. |
| Madico Inc. |
| Toyo Aluminium KK |
| Isovoltaic AG |
| 3M Co. |
| Krempel GmbH |
| Coveme SpA |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Jiangsu province lamination facilities is compressing utilization rates below sustainable thresholds, forcing PET-based converters to absorb margin erosion while fluoropolymer specialists maintain pricing discipline through certified supply scarcity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC 61215-qualified fluoropolymer constructions from multi-layer PET laminates and basic polyethylene barriers. Price differentiation hinges on certification grade and volume scale, with Chinese module manufacturers extracting steepest discounts through multi-gigawatt offtake commitments. Cost compression in the polyester tier is intensifying because co-extrusion process innovations are collapsing manufacturing cost differentials. Residential installers in Europe exhibit highest price sensitivity, while utility-scale developers in desert climates prioritize performance premiums over unit economics.
Supply Chain Analysis
PVDF resin feedstock production clusters in Chinese chemical manufacturing corridors, Japanese fluorochemical facilities, and select European specialty polymer plants. Backsheet manufacturing draws from fluoropolymer pellets, polyester film substrates, and adhesive coating chemicals as primary inputs. Single-source vulnerability concentrates in PVDF resin allocation, where backsheet makers face input rationing during petrochemical feedstock cracker maintenance cycles. Distribution runs through module manufacturer procurement hubs in Jiangsu and Anhui provinces, with merchant supply accessing smaller distributed generation assemblers through regional lamination subcontractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module architecture fragmentation is fragmenting procurement specifications, creating specialized niches for climate-specific formulations and recyclable mono-material constructions that bypass incumbent qualification barriers.
For Market Incumbents: Insulate premium positioning by accelerating captive fluoropolymer resin production in Zhejiang chemical parks and securing dual-source qualification status with top-five Chinese module producers before glass-glass substitution accelerates. DuPont's Tedlar chemistry leadership and Taiflex's volume scale represent defensive templates to emulate. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized manufacturing corridors by partnering with Gujarat-based module assemblers seeking localized BIS-certified supply. Recyclable mono-material PET constructions for European circular economy mandates offer the most penetrable entry vector, with technical service bundling as the preferred go-to-market mechanism. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across co-extruded multi-layer manufacturing as process virtualization reduces lamination equipment requirements. Long-term viability favors specialists with formulation chemistry depth rather than commodity converters. Acquisition targets should demonstrate IEC 61215 qualification completion and active REACH F-Gas reformulation pipelines. The signal to watch is glass-glass module share in utility-scale tenders as a demand destruction indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | PVDF feedstock control insulates margin structures against petrochemical allocation volatility. |
| Co-extrusion Process Virtualization | Single-pass deposition collapses capital intensity for tier-2 suppliers competing on cycle time. |
| REACH F-Gas Reformulation Pipeline | Low-GWP hydrofluoroolefin alternatives secure continued EU utility-scale specification access. |
| Recyclable Mono-material Certification | Single-polymer constructions align with emerging PV module recycling infrastructure requirements. |
| Desert Climate Specialization | Thermal cycling-resistant grades command durability premiums in Middle Eastern and North African installations. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with backsheet procurement directors at tier-1 module manufacturers, fluoropolymer formulation chemists, and utility-scale EPC contractors; and secondary validation through IEC certification databases, customs trade records for PET and PVDF film imports, and SEC filings of publicly traded material suppliers. Bottom-up triangulation against top-down capacity estimates anchored volume and value projections.
Forecast inputs span material chemistry migration timelines, module architecture substitution rates, and regional regulatory compliance burdens across the analysis window. Segmentation dimensions include installation environment durability requirements, module integration architecture, and procurement channel concentration. CAGRs were derived from installed capacity pipelines and backsheet intensity per watt assumptions, stress-tested against glass-glass module penetration scenarios and fluoropolymer resin supply elasticity.
Stress conditions across PVDF feedstock allocation constraints, glass-glass substitution velocity, and REACH F-Gas reformulation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding module production regionalization and certification harmonization trajectories. Cross-checking against IEA solar deployment benchmarks and BNEF module technology roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market