
 Residential Solar Panels Market | 2026-2036
Residential Solar Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Solar Panels Market Insights
Modular system bundling with battery storage and smart inverters is pivoting how residential buyers evaluate solar investments. Qcells leverages its vertically integrated cell-to-module manufacturing to control cost curves across North American installations. Canadian Solar anchors large-scale wafer capacity that feeds downstream residential module assembly. Jinko Solar competes aggressively on PERC and TOPCon cell efficiency, sustaining technology leadership in high-output rooftop formats.
Residential solar panels are photovoltaic modules engineered from silicon wafers, typically rated between 300 and 600 watts, designed to convert sunlight into direct current electricity for on-site consumption or grid export. Monocrystalline variants dominate premium rooftop installations where space constraints demand maximum wattage per square meter. Bifacial modules capture growing share among ground-mounted residential arrays where reflected light boosts yield. Rooftop installations remain the volume anchor, though off-grid configurations expand fastest in rural markets beyond utility interconnection reach.
The US Inflation Reduction Act, EU Green Deal national implementation plans, and India's PLI scheme for solar module manufacturing collectively reshape demand trajectories and local content requirements. These frameworks alter effective pricing, interconnection timelines, and supplier qualification thresholds for residential projects. Stakeholders must track evolving net metering rules and domestic manufacturing incentives to calibrate procurement geography and technology roadmaps.
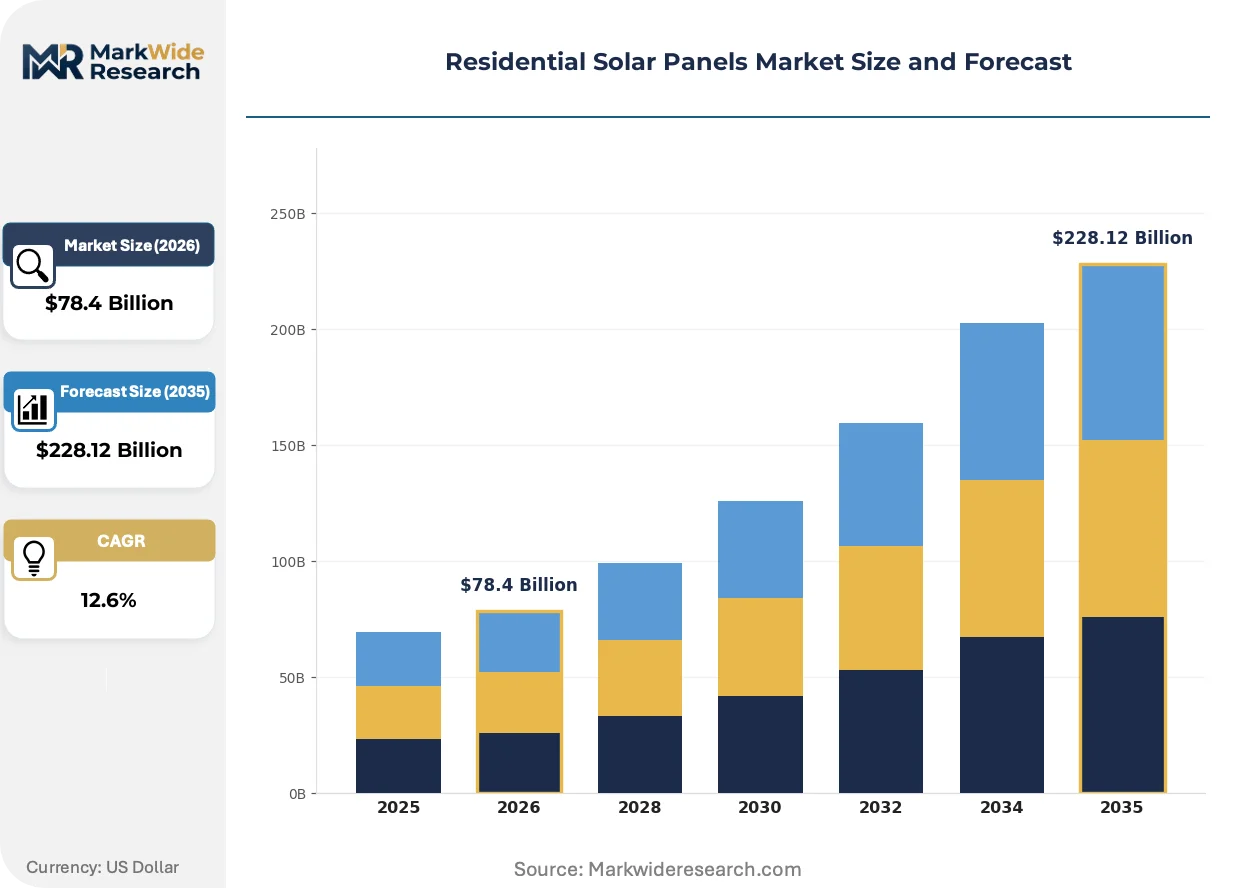
Market Dynamics
The US Inflation Reduction Act's investment tax credit extension compresses payback periods for rooftop installations, redirecting household capital toward behind-the-meter generation while reshaping installer economics across deregulated utility territories.
Growth Catalysts
- IRA Tax Credits:The US Inflation Reduction Act's 30% residential clean energy credit eliminates upfront cost barriers for middle-income households in high-rate states.
- Net Metering Evolution:California's NEM 3.0 framework, despite reducing export compensation, accelerates battery attachment rates as homeowners optimize self-consumption economics.
- TOPCon Cell Diffusion:Tunnel oxide passivated contact architecture raises module efficiency above 22%, shrinking rooftop footprint requirements for suburban installations.
Market Restraints
- Polysilicon Price Volatility:Metallurgical-grade silicon feedstock swings disrupt module pricing predictability for project financiers.
- Interconnection Queues:US regional transmission organizations impose 12-18 month study timelines, freezing project cash flows.
- Permitting Fragmentation:Municipal AHJ variations create non-standard structural engineering requirements that inflate soft costs.
Strategic Opportunities
- Texas Unpenetrated Suburbs:ERCOT's volatile wholesale pricing and minimal net metering create arbitrage opportunities for battery-optimized systems.
- Virtual Power Plant Aggregation:Utility-controlled dispatch of residential battery fleets generates recurring revenue streams beyond energy savings.
- EU Green Deal Implementation:National building renovation mandates in Germany and Italy accelerate solar-plus-storage retrofits.
Industry Challenges
- Electrical Contractor Shortage:Licensed residential electricians capable of battery integration remain scarce in fastest-growing state markets.
- Supply Chain Reconfiguration:Domestic content bonus credits force rapid supplier qualification shifts away from established Asian module sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Solar Panels Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $228.12 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-film Installation Type: Rooftop, Ground-mounted, Building Integrated, Off-grid End User: Homeowners, Property Developers, Housing Associations, Renters Financing Option: Cash Purchase, Loan, Lease, Power Purchase Agreement |
| Companies Covered | REC Group, Qcells, Hyperion Solar, Maxeon, Canadian Solar, Jinko Solar, Silfab Solar, Trina Solar, Longi Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Solar Panels Market Trends and Innovations
Rooftop solar is fragmenting into configurable subsystems where hardware, software, and financing unbundle and recombine around homeowner risk preferences and utility rate structures.
AC-coupled battery architecture is modularizing residential storage deployment, enabling retrofit attachment to existing PV arrays without DC-side reconfiguration. Third-party ownership platforms accelerate adoption among credit-constrained households. This flexibility compresses sales cycles and expands addressable market beyond new-build installations.
California's NEM 3.0 successor tariff slashes export compensation rates while extending peak pricing windows. Solar installers pivot toward storage-heavy system designs to preserve project returns. The policy shift elevates inverter-hybrid manufacturers with native battery compatibility.
Direct-to-consumer financing platforms displace traditional solar loan intermediaries, cutting customer acquisition costs by bypassing door-to-door sales channels. Online marketplace models aggregate installer bids for homeowners in competitive retail power states. Texas and Florida exhibit the fastest platform penetration where utility rate volatility heightens price transparency demand.
Residential Solar Panels Market Segmentation
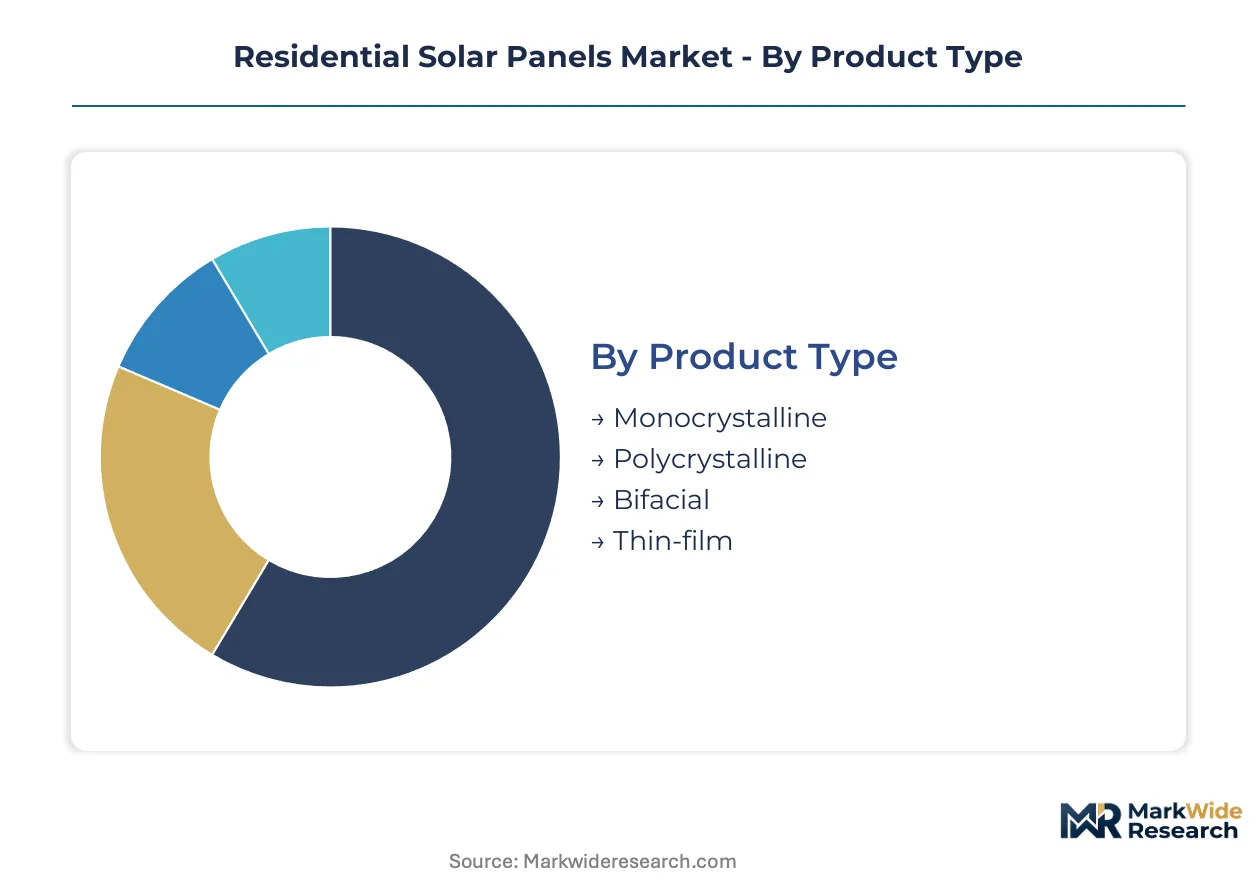
Technology and installation choices in residential solar panels directly determine system economics, interconnection complexity, and homeowner payback periods. Segmentation reveals where capital concentrates and which configurations unlock new buyer pools.
Product Type:
Monocrystalline and polycrystalline modules serve as standalone rooftop workhorses, while bifacial and thin-film technologies embed into specialized applications demanding space efficiency or architectural integration.
- Monocrystalline:Single-crystal silicon wafers deliver conversion efficiencies above 22%, commanding premium positioning in California and Florida where rooftop area constraints maximize value per square meter. High electricity rates in ERCOT territories compress payback periods for these high-output modules.
- Polycrystalline:Multi-crystal silicon construction trades peak efficiency for lower manufacturing cost, finding volume placement in Texas suburbs where expansive rooflines accommodate larger arrays and rate arbitrage drives system sizing over panel density.
- Bifacial:Dual-sided light capture boosts yield on elevated ground-mounted residential arrays with reflective surfaces beneath.
- Thin-film:Cadmium telluride and CIGS layers enable flexible form factors for building-integrated applications where rigid silicon modules fail.
Volume placements concentrate in Monocrystalline; the faster expansion belongs to Bifacial.
Installation Type:
Cost tier separation runs from standardized rooftop attachments through custom-engineered building-integrated systems to fully autonomous off-grid configurations.
- Rooftop:Rack-mounted arrays on pitched or flat residential roofs constitute the volume baseline, with attachment hardware and flashing systems standardized across IEC-certified module dimensions. California's NEM 3.0 export compensation cuts redirect installer focus toward storage-coupled rooftop designs.
- Ground-mounted:Elevated arrays on residential acreage capture bifacial gains from ground albedo, proliferating in rural Texas and Florida where lot sizes accommodate tracking or fixed-tilt structures beyond roofline constraints.
- Building Integrated:Solar tiles and facade-embedded modules replace conventional roofing materials, commanding construction-phase coordination with premium architectural specifications.
- Off-grid:Battery-coupled standalone systems serve properties beyond utility interconnection reach, climbing fastest in remote western US counties where transmission extension costs exceed solar-plus-storage capital outlay.
Ground-mounted captures the steepest expansion trajectory as rural property owners bypass interconnection queues entirely.
End User:
Customer type determines financing access, decision speed, and system permanence expectations across the ownership spectrum.
- Homeowners:Individual property owners with mortgage or title control qualify for IRA residential clean energy credits and direct loan products, driving attachment of battery storage to maximize self-consumption under evolving net metering rules.
- Property Developers:New construction multi-family and single-family builders install solar as standard amenity, capturing economies of scale in electrical rough-in and roof structural design phase.
- Housing Associations:Collective decision-making bodies navigate split incentives between common area and individual unit metering.
- Renters:Tenant households without roof rights access community solar subscriptions or landlord-facilitated green lease arrangements.
Property developers scale fastest through construction-phase integration; homeowners retain the deepest retrofit volume.
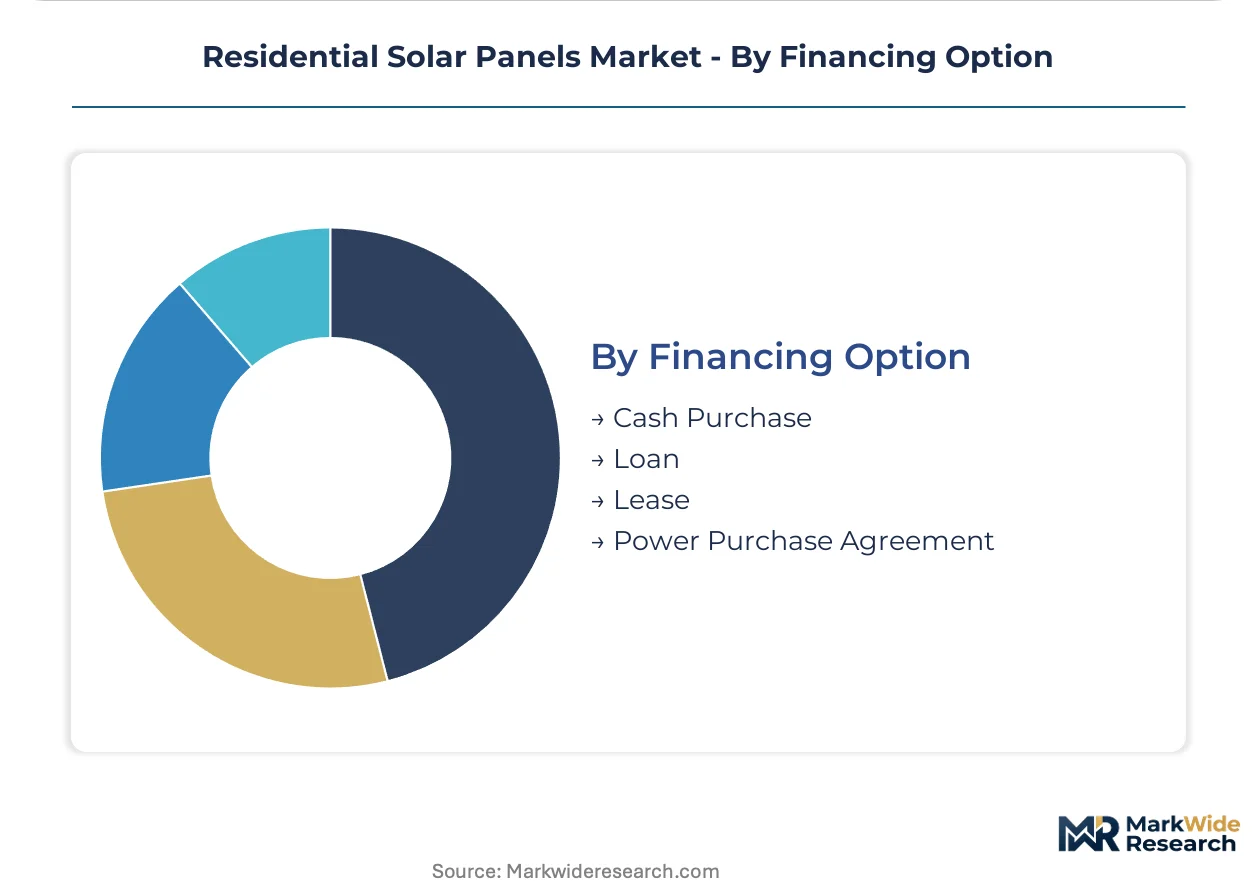
Financing Option:
Capital structure selection separates immediate ownership from third-party intermediation, reshaping customer acquisition economics and long-term asset control.
- Cash Purchase:Upfront capital deployment captures full IRA tax credit value and eliminates interest expense, concentrating among high-net-worth households in high-rate states where payback periods fall below six years.
- Loan:Secured and unsecured solar-specific lending products spread capital cost across 10-25 year terms, expanding addressable market to middle-income creditworthy buyers.
- Lease:Third-party ownership models transfer incentive capture and maintenance obligation to financiers, appealing to households with insufficient tax liability to monetize credits directly.
- Power Purchase Agreement:Per-kilowatt-hour pricing contracts lock electricity rates below utility tariffs without capital outlay, climbing fastest in deregulated retail power states with rate volatility.
Loan products capture the broadest placement volume; power purchase agreements are gaining share fastest among credit-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of solar wafers and cells consumed in residential installations worldwide, while the United States, Germany, and Australia absorb the highest per-capita volumes of rooftop capacity. This production-consumption divide shapes trade flows and domestic content requirements across major installation markets.
United States
Utility rate volatility in ERCOT territories and California's NEM 3.0 export compensation cuts are redirecting homeowner investment toward battery-coupled systems. The Inflation Reduction Act's 30% residential clean energy credit and domestic content bonus reshape supplier qualification thresholds. Installer networks concentrate in Houston, Dallas-Fort Worth, and Phoenix where interconnection timelines and permitting efficiency vary by municipal authority.
Germany
Building renovation mandates under the EU Green Deal national implementation framework accelerate solar-plus-storage retrofits in aging housing stock. The Federal Network Agency's market premium scheme and simplified registration for systems under 30 kW streamline residential adoption. Bavaria and Baden-Württemberg host the densest installer ecosystems, with Freiburg emerging as a testing ground for building-integrated photovoltaic deployment.
China
Rural electrification programs and distributed generation incentives in provincial pilot zones expand off-grid and grid-tied residential capacity beyond urban centers. The dual carbon goals framework and provincial feed-in tariff adjustments guide manufacturing capacity allocation toward higher-efficiency cell architectures. Yangtze River Delta industrial clusters supply wafer and cell capacity that feeds module assembly operations serving export markets.
Australia
High retail electricity tariffs and abundant solar irradiance compress payback periods for rooftop investments in Queensland and New South Wales. State-level battery rebate programs in Victoria and South Australia accelerate storage attachment rates. Perth and Brisbane exhibit the highest penetration rates among metropolitan areas, with regional Queensland showing rapid uptake in ground-mounted residential arrays.
India
Rooftop solar subsidies under the Ministry of New and Renewable Energy's Phase-II program target individual households and housing societies in urban agglomerations. The PLI scheme for solar module manufacturing incentivizes domestic cell and wafer capacity expansion. Gujarat and Rajasthan lead installation volumes, with Ahmedabad and Jaipur forming hub-and-spoke distribution networks for module supply into residential markets.
Residential Solar Panels Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers and geographic coverage. The vendor base spans vertically integrated cell-to-module manufacturers, pure-play module assemblers sourcing cells from merchant markets, and regional fabricators serving protected domestic markets. Three archetypes dominate: scale-driven cost leaders with captive wafer capacity, technology specialists commercializing advanced cell architectures, and regional champions leveraging local content requirements. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms position for domestic content bonus eligibility.
Within the technology-specialist tier, Maxeon and REC Group exemplify premium-positioned players focused on high-efficiency cell architectures for space-constrained rooftop applications. Qcells anchors the scale-driven archetype with North American manufacturing presence. These three occupy positions that bridge cost leadership and performance differentiation, reflecting the market's bifurcation between utility-scale procurement and residential premium positioning.
| Leading Market Players |
|---|
| REC Group |
| Qcells |
| Hyperion Solar |
| Maxeon |
| Canadian Solar |
| Jinko Solar |
| Silfab Solar |
| Trina Solar |
| Longi Solar |
| Others |
Pricing and Supply Chain Analysis
Polysilicon feedstock from metallurgical-grade silicon refineries in China and Germany flows through wafer slicing operations to module assembly tiers, with IRA domestic content bonuses redirecting procurement toward Southeast Asian cell facilities to capture tariff arbitrage.
Pricing Analysis
Margin tightening in standard-efficiency polycrystalline modules reflects polysilicon spot volatility and oversupply in Chinese wafer capacity. Three-tier pricing structure across premium monocrystalline, standard polycrystalline, and economy thin-film levels separates efficiency grades and certification tiers. Cost compression accelerates as PERC cell equipment depreciates against TOPCon conversion investments. Cash-purchase homeowners in high-rate states exhibit lowest price sensitivity; credit-constrained lease customers drive volume at thin-film entry points.
Supply Chain Analysis
Regional distribution centers in Houston, Phoenix, and Miami anchor hub-and-spoke patterns that feed installer inventory pools across deregulated utility territories. Manufacturing gravity centers on China, Vietnam, and Malaysia for cell and module assembly, with polysilicon sourcing from Xinjiang and Inner Mongolia. Supply chain risk hinges on UFLPA enforcement creating single-source vulnerability for wafers. Distribution runs through national distributor networks and direct OEM relationships with top-ten residential installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential solar market sits in a cell-architecture transition where TOPCon and heterojunction technologies displace legacy PERC production lines, compressing returns for undifferentiated module assemblers.
For Market Incumbents: Extend manufacturing presence into US Southeast assembly corridors to qualify for IRA domestic content bonus credits before phase-down schedules tighten. Anchor capacity in Georgia or South Carolina to defend against emerging pure-play specialists with captive wafer supply. Reinforce installer channel control through exclusive distribution agreements as customer acquisition costs rise.
For New Entrants and Emerging Players: Begin with battery-optimized system bundling in Texas ERCOT suburbs where wholesale rate volatility creates arbitrage demand underserved by legacy solar-only installers. Target ground-mounted bifacial configurations in rural Florida counties beyond interconnection queue congestion. Lead with direct-to-consumer financing platforms that bypass door-to-door sales infrastructure.
For Investors and Strategic Acquirers: California NEM 3.0 battery attachment rate acceleration is the leading indicator that storage-coupled system providers will capture disproportionate value creation. Position for mid-term consolidation around vertically integrated cell-to-module specialists with North American manufacturing footprints. Track interconnection queue clearance timelines as the signal for installer network viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | IRA bonus credit eligibility anchors procurement decisions for utility-scale offtakers and residential installers. |
| TOPCon Cell Conversion | Equipment upgrades at legacy PERC facilities defend efficiency positioning against heterojunction entrants. |
| Battery Supply Agreement | Locked lithium-ion cell volumes secure attachment rates under NEM 3.0 self-consumption economics. |
| Virtual Power Plant Platform | Utility-controlled dispatch contracts generate recurring revenue beyond hardware sales for aggregated residential fleets. |
| Direct-to-Consumer Financing Launch | Online marketplace models displace loan intermediaries and compress customer acquisition costs in competitive retail states. |
Research Methodology
Independent corroboration across utility interconnection databases, module shipment customs records, and installer permit filings underwrites the qualitative findings. Primary interviews with residential EPC contractors, distributed generation planners at ERCOT and CAISO, and procurement leads at national installation platforms combined with secondary validation from EIA capacity tracking, FERC interconnection queues, and state-level net metering rulemakings. Bottom-up project pipeline aggregation and top-down manufacturing capacity analysis triangulate market sizing.
Rate-of-change decomposition separates volume growth from pricing trajectory across the analysis window. Segmentation dimensions span cell technology architecture, installation type, financing structure, and regional regulatory framework. CAGRs derive from fitted growth curves against historical adoption patterns and policy incentive schedules. Forecast inputs incorporate interconnection queue clearance assumptions and battery cost learning curves.
Underlying measurement precision varies by segment; ground-mounted and off-grid installations carry tighter precision than building-integrated categories where project-level data remains sparse. Forecasts reflect documented assumptions around policy continuity and supply chain cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Europe Solar Blanket Market