
 India Solar Inverter Market | 2026-2036
India Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
India Solar Inverter Market Outlook
Market Overview
The capability gap between capital-heavy integrated manufacturers and asset-light traders is collapsing as module-level power electronics require dedicated fabrication facilities. Huawei Technology Co Ltd leverages its semiconductor design ecosystem to sustain cost leadership in string inverter architectures. Sungrow Power Supply Co., Ltd anchors its position through captive manufacturing scale in India, while Delta Electronics India Pvt. Ltd. differentiates via precision thermal management for utility-scale central inverter deployments.
Technology and Segment Analysis
A solar inverter converts direct current from photovoltaic modules into grid-synchronous alternating current, with efficiency thresholds typically exceeding 98% for utility-grade string models and isolation transformers managing harmonic distortion below 3%. String inverters dominate residential and commercial rooftop installations where modularity and rapid shutdown compliance matter, while central inverters occupy margin pools in utility-scale parks above 50 MW where balance-of-system economics favor concentrated conversion. Microinverters and power optimizers are gaining traction in premium residential segments shaded by rooftop structures or urban obstructions.
Regulatory Environment and Outlook
BIS certification mandates and CEA grid connectivity standards shape product eligibility for national solar tenders, while state-level renewable purchase obligations in Maharashtra and Karnataka direct utility procurement volumes. The PLI scheme's domestic value-add requirements are forcing inverter suppliers to localize assembly or forfeit central government-linked project access. Stakeholders must monitor how BIS updates efficiency testing protocols and whether CEA mandates reactive power capabilities that favor hybrid inverter architectures.
Market Dynamics
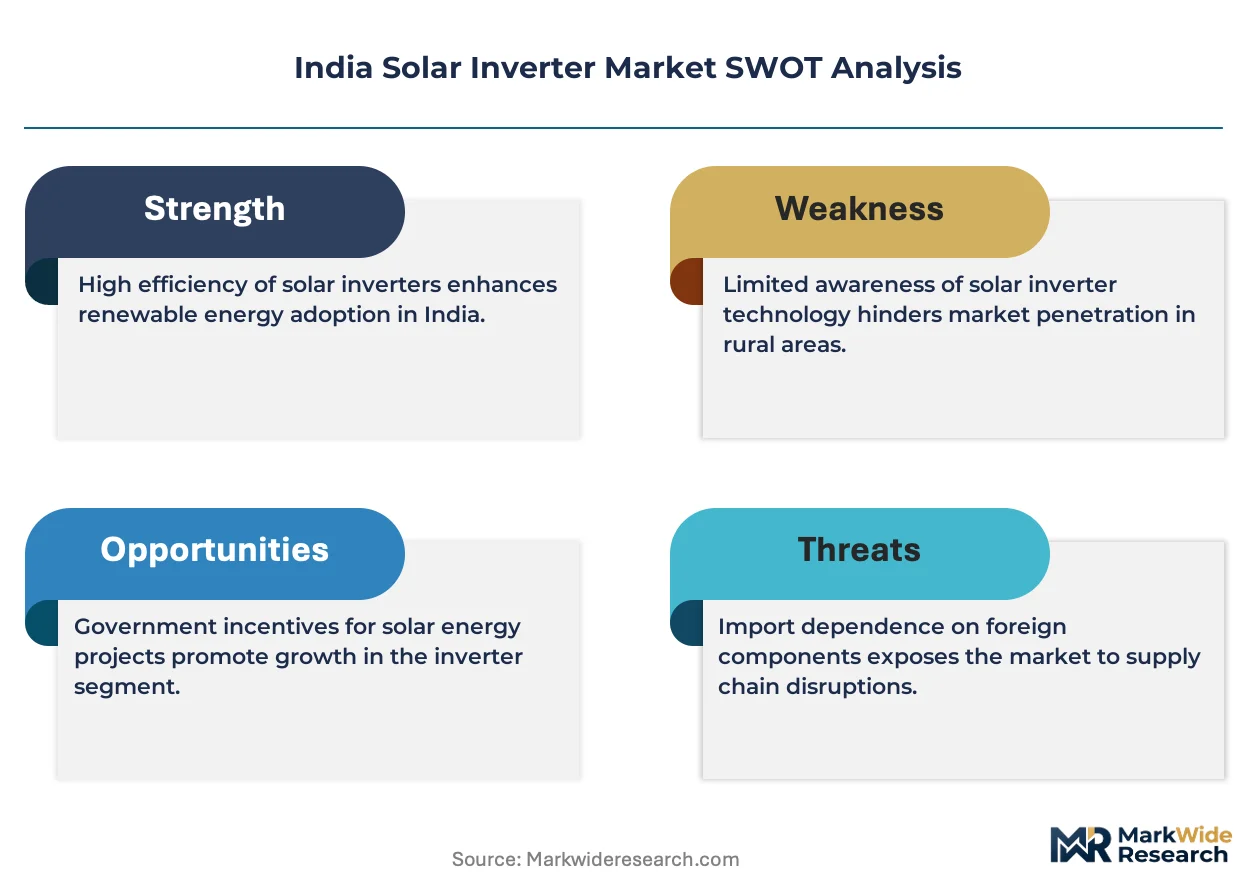
The PLI scheme's domestic value-add mandates are forcing inverter suppliers to localize assembly or surrender access to central government-linked tenders, collapsing the traditional import-reliant supply model.
Growth Catalysts
- CEA Grid Connectivity Standards:Mandatory reactive power capabilities and harmonic compliance are pulling advanced string and central inverter architectures into utility-scale parks across Rajasthan and Gujarat.
- Rooftop Solar Subsidies:Residential and commercial segments in Maharashtra and Karnataka are accelerating procurement of modular string inverters compliant with rapid shutdown requirements.
- Western and Southern Irradiation Clusters:Land availability and solar resource concentration in these states are concentrating project developer activity and inverter demand.
Market Restraints
- IGBT and SiC Semiconductor Import Dependence:Power electronics fabrication concentrates in China and Taiwan, exposing Indian assemblers to input cost volatility and supply disruption.
- BIS Certification Timelines:Efficiency testing protocol updates create product eligibility delays that freeze supplier participation in national tenders for 6-12 month windows.
- Central Inverter Technical Limitation:Large-scale conversion architectures face harmonic distortion management constraints below 3% thresholds in high-temperature desert deployments.
Strategic Opportunities
- Hybrid Inverter Architecture Convergence:Integration of solar conversion with battery storage management is opening product white space as CEA mandates storage-ready grid connectivity.
- Microinverter Underpenetration:Shaded urban rooftops in Delhi and Bangalore represent untapped residential segments where module-level power electronics outperform string alternatives.
- State-Level RPO Acceleration:Maharashtra and Karnataka renewable purchase obligations are creating procurement tailwinds independent of central tender cycles.
Industry Challenges
- Power Electronics Talent Scarcity:Semiconductor design and thermal engineering skill gaps constrain domestic R&D scale-up for inverter suppliers establishing captive fabrication.
- Legacy SCADA Integration Complexity:Utility-scale parks require protocol bridging between new inverter communication standards and existing grid management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Solar Inverter Market |
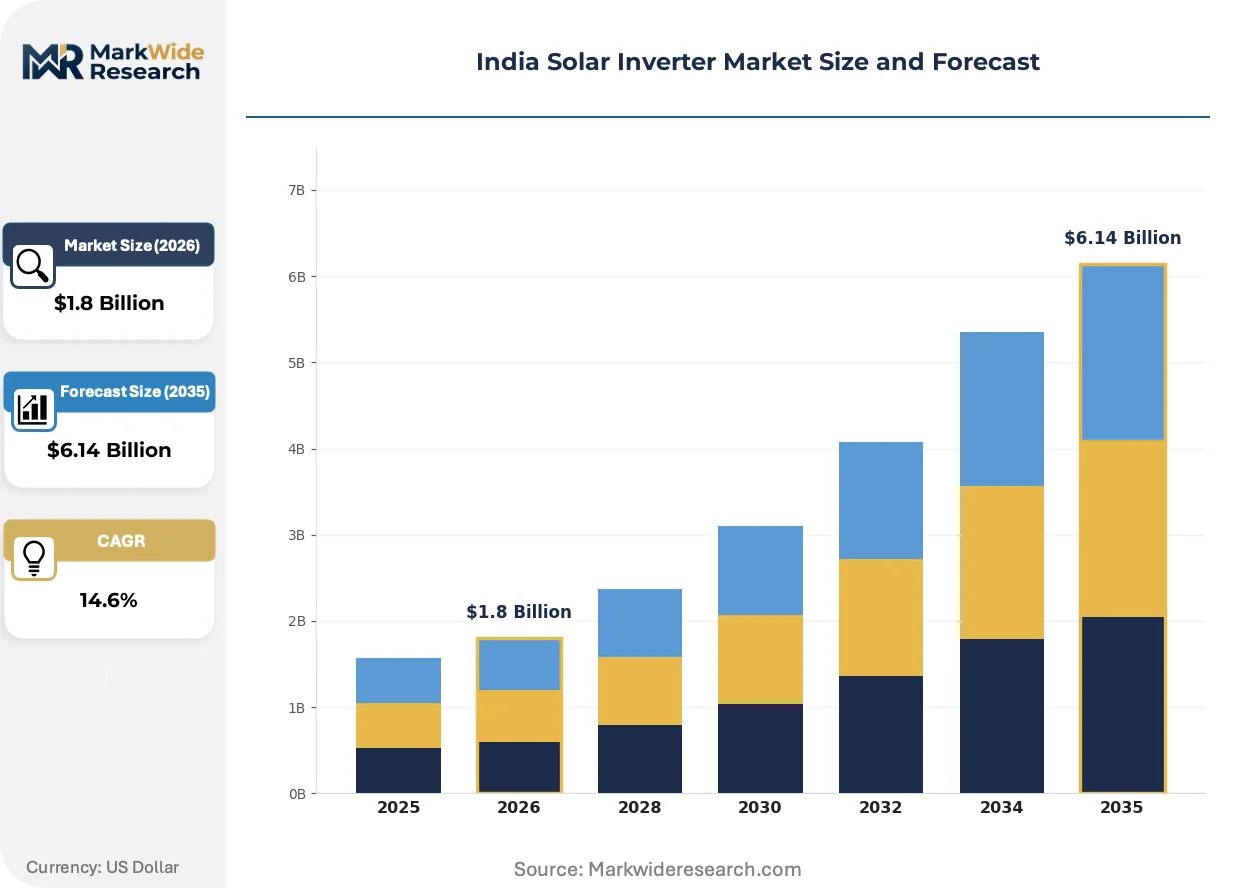
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Microinverters, Central Inverters, Power Optimizers End User: Residential, Commercial, Industrial, Utility Technology: Grid-Tied, Off-Grid, Hybrid, Battery Storage Installation: Roof-Mounted, Ground-Mounted, Wall-Mounted, Portable |
| Companies Covered | FIMER Ltd., SolarEdge, Huawei Technology Co Ltd, Enphase Energy, Fronius, Sungrow Power Supply Co., Ltd, Delta Electronics India Pvt. Ltd., Luminous Power Technologies, Havells India Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Solar Inverter Market Strategic Shifts
Module-level power electronics are fragmenting the traditional string-central dichotomy while regulatory pressure on domestic value-add accelerates supplier restructuring.
Silicon carbide (SiC) MOSFETs are replacing silicon IGBTs in high-frequency switching applications, enabling 99% peak efficiency in utility-grade string inverters. Large project developers in Gujarat are specifying SiC-based architectures for 1500V DC systems. This semiconductor transition is decomposing cost structures that previously favored centralized conversion economics.
BIS updated its IS 16221 standard for grid-tied inverter safety and efficiency testing, mandating enhanced electromagnetic compatibility verification. The regulation compresses product development cycles as suppliers redesign for compliance ahead of tender eligibility windows. String inverter portfolios face the heaviest recertification burden given their shorter replacement cycles.
Engineering-procurement-construction firms are consolidating inverter sourcing through multi-year framework agreements rather than project-specific tenders. This buyer concentration is displacing spot-market traders and favoring suppliers with captive Indian assembly capacity. The shift is most visible in Rajasthan utility-scale parks where Adani Green and Tata Power Renewable Energy dominate procurement volume.
India Solar Inverter Market Segmentation
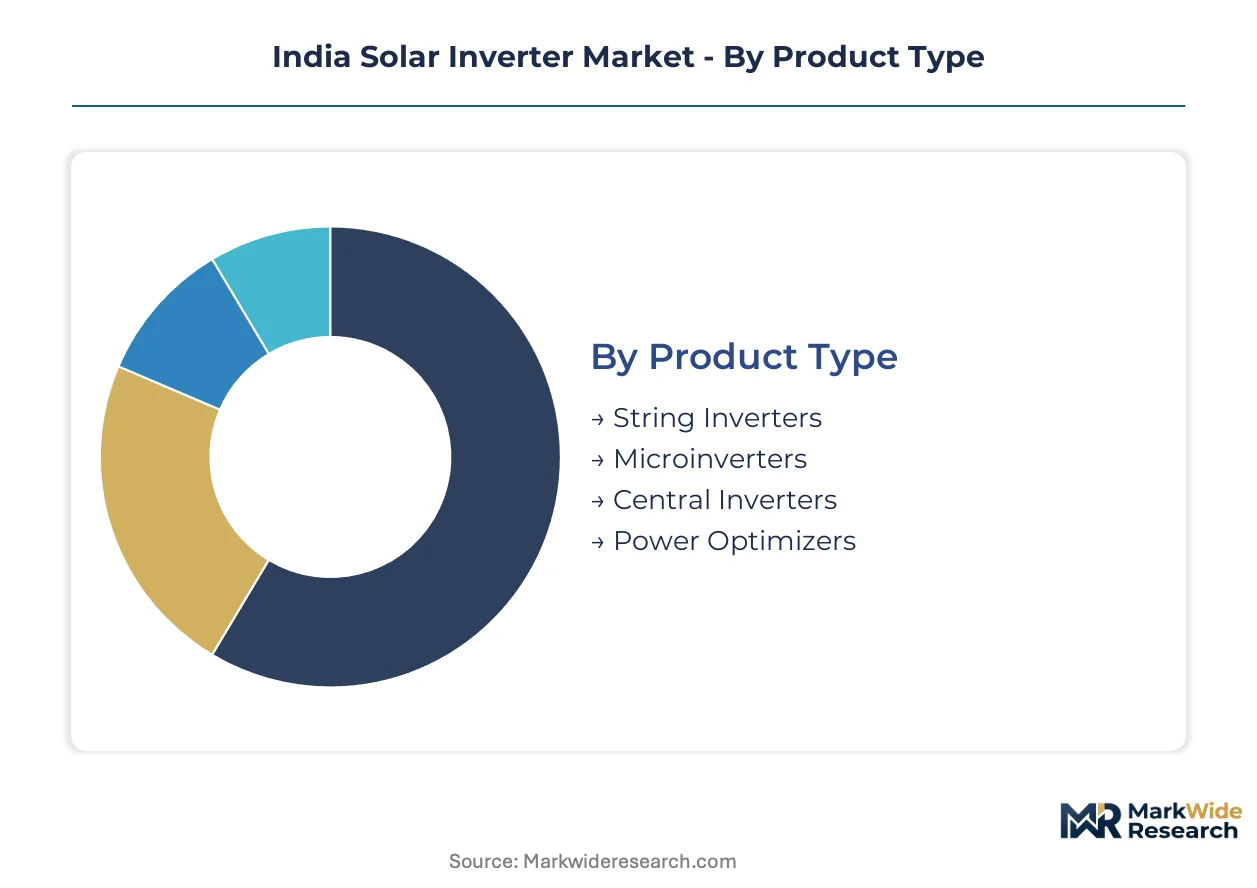
Segmentation in the India solar inverter market reveals how procurement patterns split between government-linked utility tenders and state-level rooftop programs. Each dimension—product architecture, end-use scale, grid interface, and mounting configuration—carries distinct certification requirements and margin profiles that reshape supplier positioning.
Product Type:
Domestic assembly under the PLI scheme concentrates in string and central inverter categories, while microinverters and power optimizers remain import-dependent due to semiconductor packaging constraints.
- String Inverters:Modular DC-to-AC conversion units rated 3-150kW deploy across distributed generation assets. Procurement clusters in Maharashtra and Karnataka residential and commercial rooftop segments where BIS IS 16221 compliance and rapid shutdown functionality determine eligibility.
- Central Inverters:Concentrated conversion architectures above 500kW serve utility-scale parks in Rajasthan and Gujarat. These units face harmonic distortion management challenges below 3% thresholds in high-temperature desert deployments, favoring suppliers with precision thermal engineering capabilities.
- Microinverters:Module-level power electronics enable per-panel MPPT in shaded urban rooftops across Delhi and Bangalore.
- Power Optimizers:DC conditioning devices paired with string inverters improve yield in partially obstructed installations.
Central inverters command the established base in utility-scale procurement. The steepest expansion runs through string inverters as state rooftop subsidies accelerate.
End User:
Volume concentration tilts toward utility-scale developers, though policy incentives are redistributing demand toward commercial and industrial self-consumption models.
- Residential:Individual rooftop systems below 10kW drive string inverter procurement through state subsidy portals. Maharashtra and Karnataka renewable purchase obligations channel utility procurement volume that indirectly funds residential program liquidity.
- Commercial:Mid-scale installations from 10kW to 1MW serve manufacturing facilities and office complexes seeking open access wheeling arrangements. These projects favor hybrid-ready inverters as CEA storage mandates approach.
- Industrial:Captive power plants above 1MW supply process loads with high tariff exposure.
- Utility:Grid-scale solar parks above 50MW anchor central inverter demand through engineering-procurement-construction framework agreements.
Utility-scale deployment captures the volume base. Commercial installations are climbing fastest as open access regulations mature.
Technology:
Grid interface requirements differentiate product architectures, with hybrid and storage-integrated systems gaining regulatory tailwind from CEA connectivity standards.
- Grid-Tied:Synchronous inverters feeding directly into distribution networks dominate installed capacity. BIS electromagnetic compatibility verification and CEA reactive power mandates shape product redesign cycles for tender eligibility.
- Off-Grid:Standalone systems with battery backup serve rural electrification and remote industrial loads in eastern and northeastern states with weak grid penetration.
- Hybrid:Dual-mode inverters managing solar generation alongside grid import/export are gaining specification in CEA storage-ready mandates.
- Battery Storage:Integrated storage inverters pair with lithium-ion or emerging sodium-ion chemistries for time-shifted dispatch.
Grid-tied systems hold the installed base. Hybrid architectures are expanding most quickly as storage mandates crystallize.
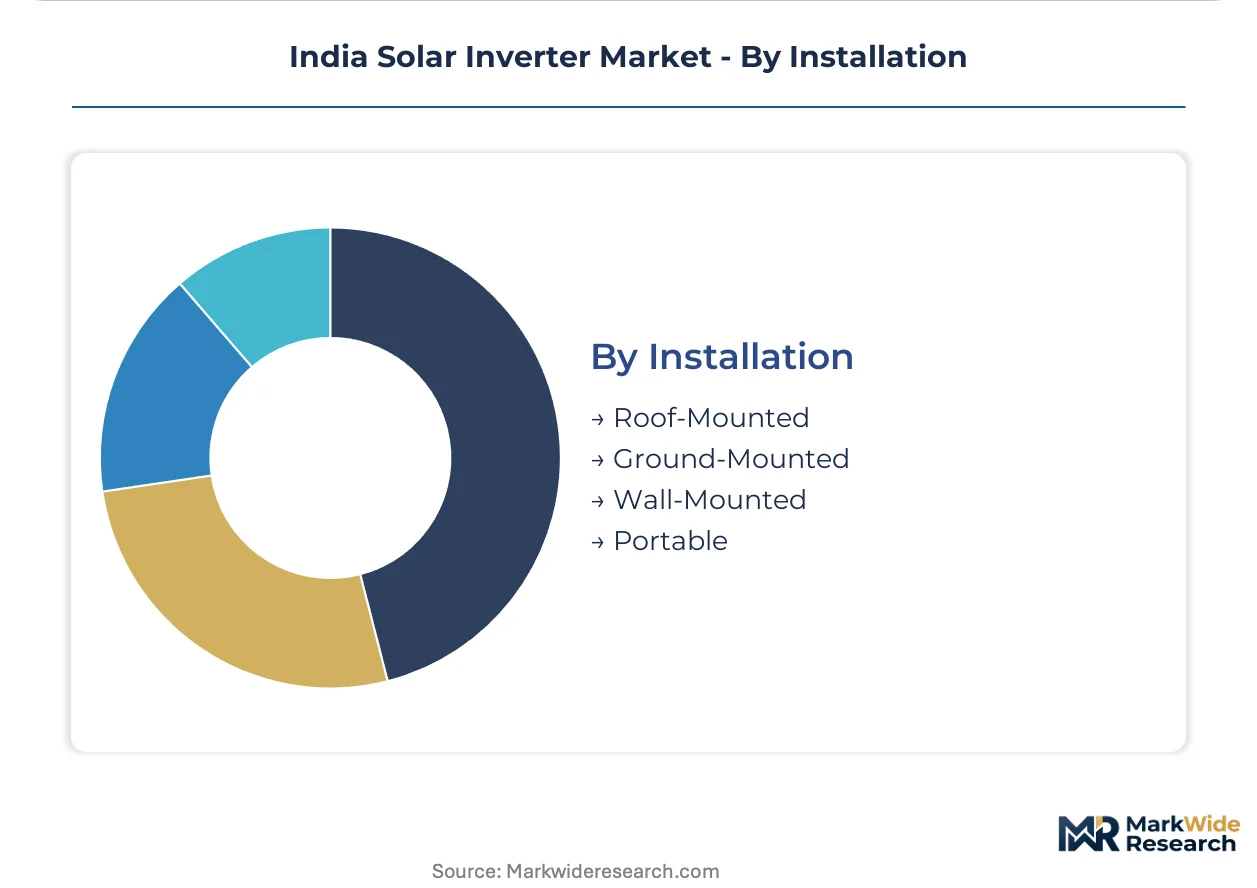
Installation:
Mounting configuration correlates with end-use scale and land constraints, with ground-mounted utility parks concentrating in western states and rooftop/wall-mounted systems dominating urban load centers.
- Roof-Mounted:Elevated installations on commercial and residential structures require lightweight string inverters with IP65 environmental sealing. Demand concentrates in Bangalore, Delhi, and Pune where urban land scarcity precludes ground arrays.
- Ground-Mounted:Utility-scale arrays on acquired land in Rajasthan and Gujarat accommodate central inverter compounds with dedicated access roads and thermal management infrastructure.
- Wall-Mounted:Vertical installation on building facades serves constrained commercial sites in dense urban cores.
- Portable:Mobile inverter systems for temporary power or disaster relief applications represent a nascent segment.
Ground-mounted systems anchor utility-scale deployment. Roof-mounted configurations are gaining share fastest as urban renewable purchase obligations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan commands pricing power through scale concentration while Karnataka extracts premiums through policy-backed rooftop procurement. Western and southern states concentrate inverter demand through irradiation advantages and land availability.
Rajasthan
Utility-scale solar parks above 100MW anchor central inverter procurement through engineering-procurement-construction framework agreements. CEA grid connectivity standards mandate reactive power capabilities that reshape product specifications for desert deployments. Bhadla and Phased Solar Park clusters concentrate developer activity where Adani Green and Tata Power Renewable Energy dominate sourcing volume.
Gujarat
Charanka and Dholera solar zones drive string and central inverter demand through state-backed renewable energy zones. Gujarat Urja Vikas Nigam Limited tenders specify domestic value-add requirements that filter supplier eligibility. Kutch and Patan districts host manufacturing-adjacent project development that reduces logistics costs for inverter delivery.
Maharashtra
State renewable purchase obligations channel utility procurement volume that indirectly funds residential rooftop program liquidity. Maharashtra State Electricity Distribution Company Limited net metering policies accelerate commercial and industrial self-consumption models. Pune and Nagpur industrial corridors favor hybrid-ready inverters as open access wheeling regulations mature.
Karnataka
Pavagada and Koppal solar parks concentrate utility-scale demand while Bangalore urban density drives rooftop string inverter procurement. Karnataka Renewable Energy Development Limited subsidies compress payback periods for residential installations below 10kW. Tumkur and Davanagere districts attract manufacturing facilities seeking proximity to project clusters.
Telangana
Central inverter demand concentrates in Mahbubnagar and Nalgonda utility parks where land aggregation supports 50MW-plus installations. Telangana State Renewable Energy Development Corporation tenders incorporate BIS IS 16221 compliance as baseline eligibility. Hyderabad industrial belt generates commercial rooftop demand through pharmaceutical and IT campus electrification.
India Solar Inverter Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with semiconductor design capabilities separating premium-tier suppliers from assembly-scale competitors. The vendor base organizes around three strategic archetypes: integrated manufacturers with captive fabrication, module-level power electronics specialists, and domestic assemblers serving price-sensitive tender segments. Competitive moves concentrate on PLI-linked localization investments and multi-year framework agreements with engineering-procurement-construction firms.
Among China-based integrated manufacturers, Huawei Technology Co Ltd and Sungrow Power Supply Co., Ltd anchor the scale-driven tier through semiconductor ecosystem control and captive Indian assembly capacity. Delta Electronics India Pvt. Ltd. occupies a position within the precision thermal management specialist archetype for utility-scale central inverter deployments. Domestic players including Luminous Power Technologies and Havells India Limited represent the tariff-responsive tier serving state-level rooftop subsidy programs.
| Leading Market Players |
|---|
| FIMER Ltd. |
| SolarEdge |
| Huawei Technology Co Ltd |
| Enphase Energy |
| Fronius |
| Sungrow Power Supply Co., Ltd |
| Delta Electronics India Pvt. Ltd. |
| Luminous Power Technologies |
| Havells India Limited |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide MOSFET substitution for silicon IGBTs is redrawing procurement geography toward East Asian wafer foundries while collapsing the cost advantage that once favored centralized inverter architectures over distributed string systems. This semiconductor transition simultaneously elevates BIS certification premiums for high-efficiency designs and compresses margins for legacy product tiers unable to meet 99% peak efficiency thresholds.
Pricing Analysis
The customization-premium spread between configured-to-order central inverters and standard string units spans certification grade, thermal engineering specification, and after-sales service bundling. Project-based pricing dominates utility-scale procurement through multi-year framework agreements with engineering-procurement-construction firms, while transactional per-unit sales persist in residential rooftop segments. Price differentiation hinges on BIS IS 16221 compliance tier and captive Indian assembly capacity under PLI scheme mandates. Margins are tightening in standard string inverter tiers due to supplier overcrowding in Maharashtra and Karnataka subsidy channels.
Supply Chain Analysis
China and Taiwan anchor power semiconductor fabrication for IGBT and SiC components, while South Korea supplies precision thermal management subsystems. Indian assemblers draw from these inputs for domestic value-add compliance, with raw material dependencies concentrated in wafer substrates, gate driver ICs, and magnetics. Single-source vulnerability in SiC wafer supply exposes manufacturers to allocation constraints as automotive and solar demand compete for limited foundry capacity. Distribution runs through engineering-procurement-construction framework agreements for utility-scale deployment and state subsidy portal channels for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India solar inverter market sits in early-cycle expansion as state renewable purchase obligations and PLI-linked domestic manufacturing mandates accelerate adoption ahead of grid parity maturation.
For Market Incumbents: Secure multi-year framework agreements with Adani Green and Tata Power Renewable Energy before EPC procurement consolidation freezes out spot-market suppliers. Deepen backward integration into semiconductor packaging through joint ventures with Taiwan-based foundries to mitigate SiC supply allocation risk. Prioritize BIS pre-certification for hybrid inverter architectures ahead of CEA storage-ready mandate finalization. For New Entrants and Emerging Players: After-sales service coverage gaps in Rajasthan desert deployments present white-space entry points where thermal engineering expertise commands premium pricing. Target microinverter penetration in shaded Bangalore and Delhi rooftops where string inverter underperformance creates module-level power electronics demand. Pursue direct partnerships with Karnataka Renewable Energy Development Limited for residential subsidy portal listing as the fastest certification pathway. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed domestic assemblers lacking captive fabrication but holding PLI-linked tender access. Five-to-ten year viability favors suppliers with semiconductor design ecosystems or precision thermal engineering capabilities rather than pure-play traders. Monitor BIS efficiency protocol update timing as the inflection signal for portfolio rebalancing toward hybrid-ready architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Packaging | Joint ventures with Taiwan foundries secure SiC wafer allocation for utility-grade string inverter production. |
| Hybrid Inverter Pre-Certification | BIS IS 16221 compliance for storage-ready designs captures CEA mandate tailwind ahead of competitors. |
| EPC Framework Agreements | Multi-year supply contracts with Rajasthan and Gujarat park developers displace spot-market procurement. |
| Microinverter Channel Partnerships | Direct listing on Karnataka and Maharashtra state subsidy portals accelerates residential segment penetration. |
| Thermal Engineering Service Centers | Desert deployment support infrastructure in Bhadla and Phased Solar Park clusters captures premium service revenue. |
Study Parameters
The analysis maps string inverter, central inverter, microinverter, and hybrid architecture sub-sectors, each validated through primary interviews with IPP project developers, EPC procurement leads, grid operators, and inverter supplier technical directors. Secondary validation draws from CEA grid connectivity filings, BIS certification registries, SECI tender documents, and state renewable purchase obligation notifications. Bottom-up project pipeline aggregation triangulates against top-down manufacturing capacity estimates from PLI scheme disclosures.
Consistency checks against IEA India energy outlook benchmarks and MNRE deployment statistics validate volume and value outputs across the projection horizon. The analytical framework models product type, end-user scale, grid interface technology, and installation configuration dimensions. CAGRs derive from segmented adoption curves weighted by state-level policy intensity and irradiation resource concentration. Forecast inputs include semiconductor cost decline trajectories and BIS protocol update implementation timelines.
Material uncertainties — PLI scheme extension decisions, SiC supply allocation shocks, and CEA storage mandate timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about policy continuity and technology cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Asia Pacific Solar Inverter Market