
 Brazil City Gas Distribution Market | 2026-2036
Brazil City Gas Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil City Gas Distribution Market Outlook
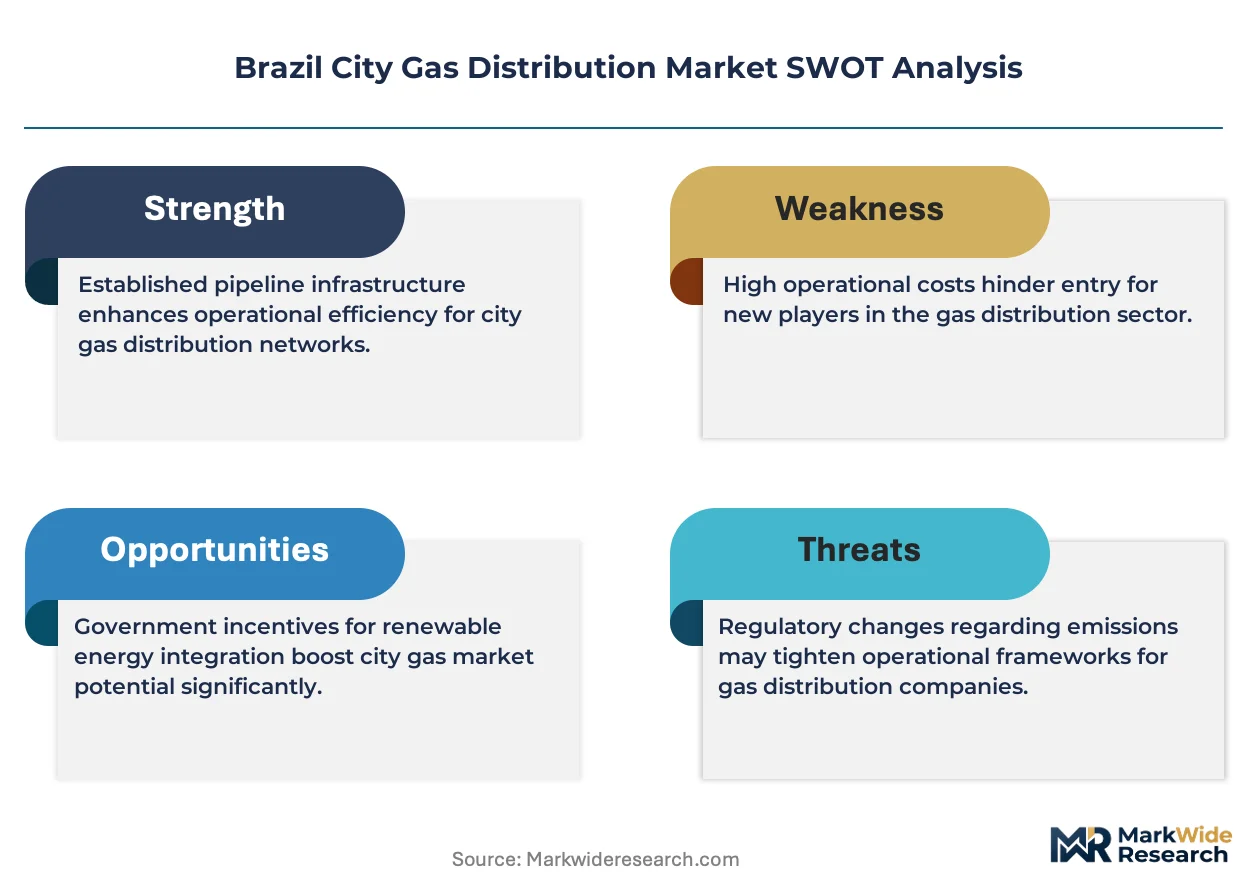
ANP Resolution 16/2019 is restructuring concession licensing by separating gas transport from distribution rights, raising capital requirements for new entrants. Comgás leverages its São Paulo pipeline density to sustain margin leadership across industrial zones. CEG Rio anchors Rio de Janeiro's residential conversion programs through dedicated network extensions. SCGÁS differentiates via Santa Catarina's compressed natural gas vehicle corridors.
City gas distribution comprises the localized pipeline network infrastructure, pressure regulation stations, and metering systems that deliver natural gas from transmission trunk lines to end users at pressures typically below 700 kPa. The primary purpose is to supply methane-based fuel for heating, process energy, and power generation across urbanized areas. Public utilities still dominate installed pipeline kilometers, though private providers capture fastest growth in greenfield industrial parks. Residential consumers generate stable base loads, while power generation segments offer highest volume per connection point.
ANP, Petrobras divestiture protocols, and state-level environmental licensing bodies collectively shape market access timelines and infrastructure investment rules. ANVISA standards for indoor gas appliance safety influence residential conversion eligibility criteria. Stakeholders must monitor ANP's secondary market gas pricing reforms and state concession re-bidding schedules to anticipate competitive repositioning cycles.
Market Dynamics
ANP's unbundling of transport and distribution concessions is fragmenting Brazil's historically concentrated city gas infrastructure, forcing new entrants to build standalone distribution networks without pipeline access guarantees from Petrobras legacy trunk lines.
Growth Catalysts
- Industrial Park Expansion:Greenfield manufacturing clusters in São Paulo's ABC Paulista corridor require dedicated gas distribution infrastructure, pulling private capital into concession bidding.
- ANP Resolution 16/2019:This regulatory separation of pipeline transport from local distribution rights creates entry points for specialized distributors previously blocked by vertically integrated incumbents.
- Compressed Natural Gas Corridors:Heavy freight routes connecting Santa Catarina's port terminals to interior agricultural processing centers are converting diesel truck fleets to CNG, demanding new refueling station networks.
Market Restraints
- Petrobras Pipeline Concentration:The state-owned operator controls over 90% of Brazil's high-pressure transmission backbone, leaving new distributors dependent on negotiated third-party access terms.
- Steel and Polymer Input Volatility:Distribution network construction relies on high-grade steel pipe and polyethylene tubing subject to commodity price swings that compress project IRRs during bidding phases.
- LNG Import Terminal Bottlenecks:Regasification capacity concentrates at four coastal facilities, limiting interior state access to competitively priced gas molecules during peak demand periods.
Strategic Opportunities
- Northeast Residential Conversion:Pernambuco and Ceará states maintain 85% LPG dependency for cooking, creating white space for piped natural gas penetration as distribution concessions expand beyond southeastern industrial cores.
- Power Generation Co-location:Embedded gas-fired generation at manufacturing facilities bypasses grid transmission constraints, offering distributors anchor loads with 8,000+ annual operating hours.
- ANP Secondary Market Pricing Reforms:Proposed spot market mechanisms for natural gas trading would reduce long-term take-or-pay rigidities, improving distributor margin predictability on variable industrial demand.
Industry Challenges
- Pipeline Welding Certification Delays:ANP-mandated ASME Section IX qualification requirements for high-pressure distribution construction create 4-6 month workforce bottlenecks during project ramp phases.
- Legacy LPG Infrastructure Stranding:Existing residential bottled gas distribution networks resist conversion to piped systems due to sunk distributor investments in cylinder logistics and retail relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil City Gas Distribution Market |
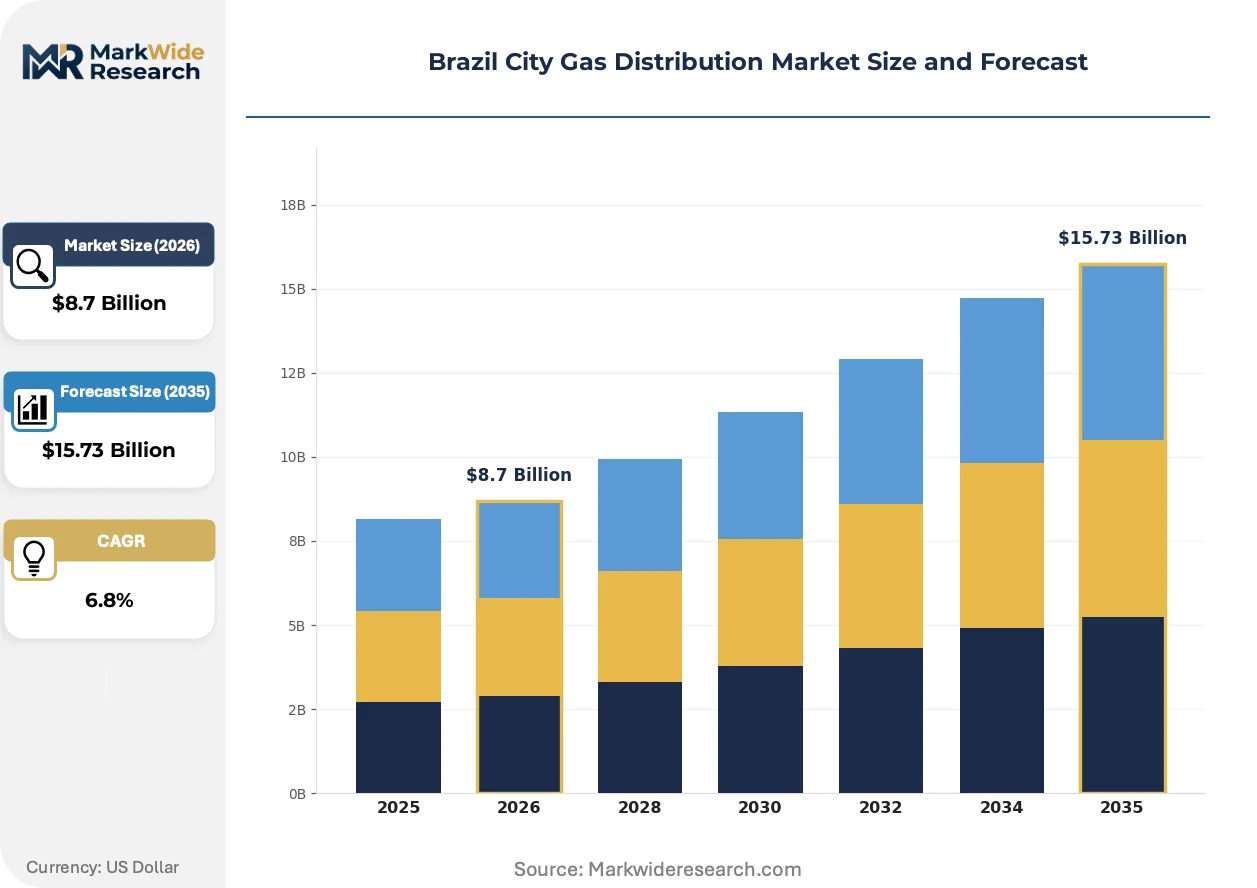
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Utility Type: Public Utilities, Private Providers, Cooperative Systems, Municipal Operators End User: Residential Consumers, Commercial Establishments, Industrial Facilities, Power Generation Service Type: Installation Services, Maintenance Services, Consulting Services, Metering Services Distribution Channel: Direct Sales, Retail Outlets, Partnerships, Third-Party Distributors |
| Companies Covered | CEG Rio, MSGÁS – Companhia de Gás do Estado de Mato Grosso do Sul, Companhia de Gás de São Paulo (Comgás), Potiguar Gas Company (Potigas), Gás Brasiliano Distribuidora S.A., Companhia Paranaense de Gás (Compagas), SCGÁS – Companhia de Gás de Santa Catarina, Companhia Paraibana de Gás, Bahiagás – Companhia de Gás da Bahia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil City Gas Distribution Market Strategic Shifts
Digital pressure monitoring and automated meter reading systems are replacing mechanical infrastructure across Brazil's city gas networks, compressing operational cost structures while enabling real-time demand forecasting for industrial offtake agreements.
Smart pressure regulation stations equipped with IoT sensors and remote valve control are integrating SCADA capabilities directly into distribution network nodes. São Paulo industrial distributors are deploying these systems at 40% of new connection points. This convergence is integrating predictive maintenance protocols that reduce emergency response times from hours to minutes.
ANP's proposed New Gas Market regulatory framework is mandating third-party access to Petrobras transmission pipelines on negotiated tariff terms. Industrial consumers in Minas Gerais and Rio de Janeiro states gain direct purchasing rights from LNG importers. Large chemical processors are responding by establishing dedicated procurement desks to arbitrage spot versus contract pricing.
Freight operators along Brazil's BR-101 coastal highway are consolidating fuel purchasing through fleet card platforms that aggregate CNG demand across multiple transport companies. This procurement consolidation pressures standalone station operators to join branded network affiliations. The shift is most visible in Santa Catarina's Itajaí Valley logistics cluster where 60% of heavy truck fleets now operate under managed fuel contracts.
Brazil City Gas Distribution Market Segmentation
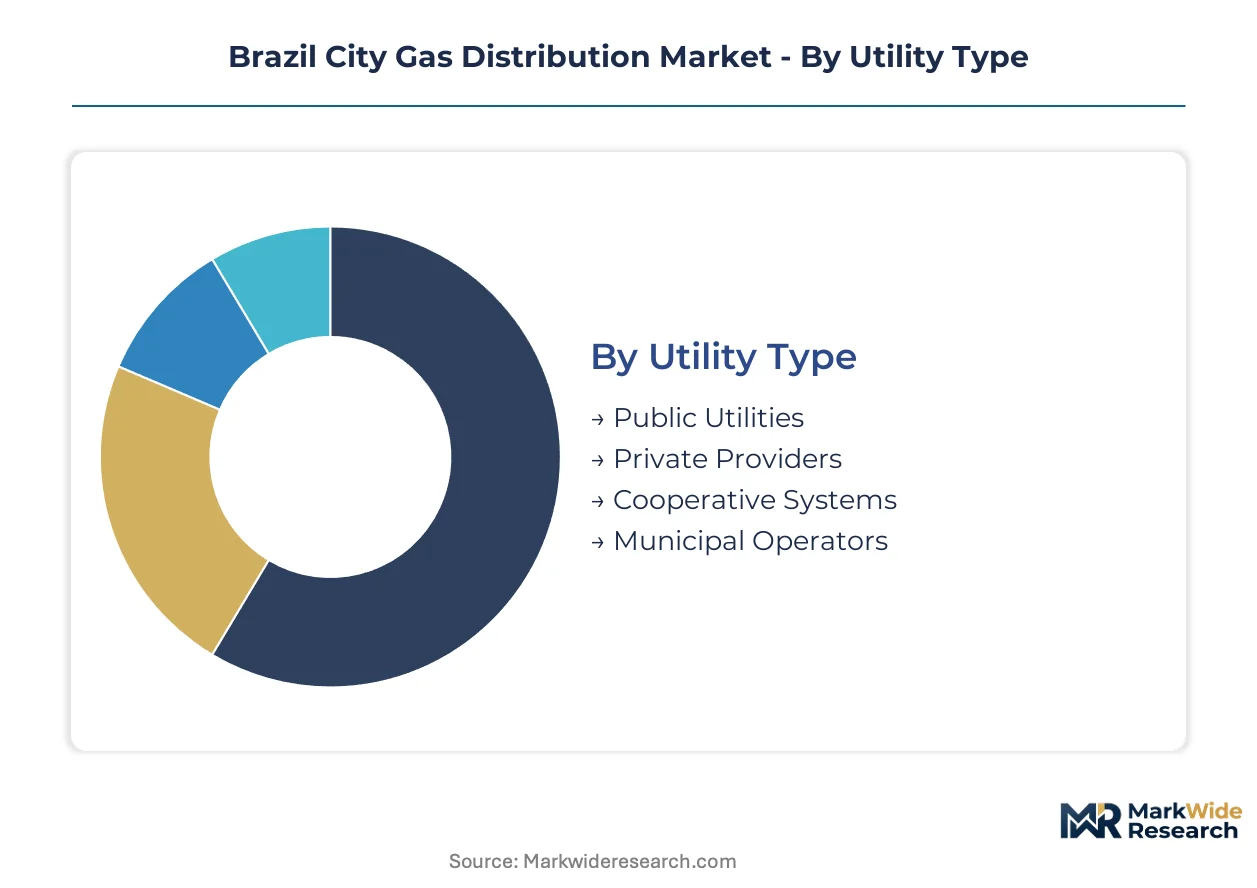
Segmentation in Brazil's city gas distribution market reveals how regulatory licensing, infrastructure ownership, and customer contracting structures fragment competitive positioning across concession zones. Understanding these divides clarifies where capital requirements, margin profiles, and growth trajectories diverge most sharply.
Utility Type:
ANP certification requirements vary substantially across ownership structures, with public utilities facing lighter environmental licensing burdens but heavier concession re-bidding obligations, while private entrants navigate stricter financial solvency proofs and standalone network build mandates.
- Public Utilities:State-controlled distributors operate under grandfathered concession agreements with integrated transport-distribution rights. São Paulo's Comgás leverages this legacy structure to maintain dense pipeline coverage across ABC Paulista industrial corridors without third-party access negotiations.
- Private Providers:New market entrants post-ANP Resolution 16/2019 must secure standalone distribution concessions and negotiate pipeline access terms with Petrobras. Greenfield industrial park developers in Minas Gerais favor these operators for customized pressure regulation and dedicated metering infrastructure.
- Cooperative Systems:Agricultural processing cooperatives in Santa Catarina's interior have formed buyer consortia to aggregate CNG demand and contract directly with distributors for fleet refueling station networks.
- Municipal Operators:Smaller city governments in Pernambuco and Ceará operate localized distribution systems serving residential conversion zones with simplified pressure regulation and basic metering infrastructure.
Public Utilities sit at the top of the volume ranking, with Private Providers climbing the fastest as ANP unbundling opens new concession bidding rounds.
End User:
Customer contracting structures determine tariff design complexity, with residential segments requiring standardized rate schedules under ANP oversight while industrial offtake permits negotiated volumetric discounts and interruptible supply clauses.
- Residential Consumers:Household cooking and water heating demand concentrates in Rio de Janeiro's CEG Rio service territory, where legacy LPG conversion programs drive steady connection growth. ANVISA appliance safety certification requirements govern eligibility for network access.
- Commercial Establishments:Restaurants, hotels, and retail facilities in São Paulo metropolitan zones require medium-pressure distribution infrastructure with automated meter reading for demand forecasting. CNG vehicle fleet operators in Santa Catarina's Itajaí Valley logistics cluster represent expanding commercial load profiles.
- Industrial Facilities:Chemical processors and steel manufacturers in Minas Gerais negotiate direct supply agreements with LNG importers under ANP's New Gas Market framework, bypassing traditional distributor procurement channels.
- Power Generation:Embedded gas-fired generation at manufacturing plants offers distributors anchor loads with continuous operating profiles, though power sector dispatch volatility creates demand forecasting challenges for network capacity planning.
Industrial Facilities command the highest revenue per connection point, with Power Generation gaining share fastest as embedded generation bypasses grid transmission constraints.
Service Type:
Service margins stratify sharply between capital-intensive installation work subject to steel and polymer input volatility versus recurring maintenance revenue with predictable cash flow profiles.
- Installation Services:Pipeline construction, pressure regulation station deployment, and residential connection infrastructure require ASME Section IX certified welding crews. São Paulo distributors face 4-6 month workforce bottlenecks during project ramp phases.
- Maintenance Services:Scheduled inspection, corrosion monitoring, and emergency leak response generate recurring revenue streams. IoT-enabled predictive maintenance protocols are compressing response times across SCGÁS networks in Santa Catarina.
- Consulting Services:Feasibility studies for greenfield industrial park gas infrastructure and regulatory compliance advisory support new concession bidding preparation.
- Metering Services:Automated meter reading system deployment and data analytics for demand forecasting are replacing mechanical infrastructure across southeastern distributor networks.
Installation Services dominate capital deployment, with Metering Services expanding most quickly as digital infrastructure replacement accelerates.
Distribution Channel:
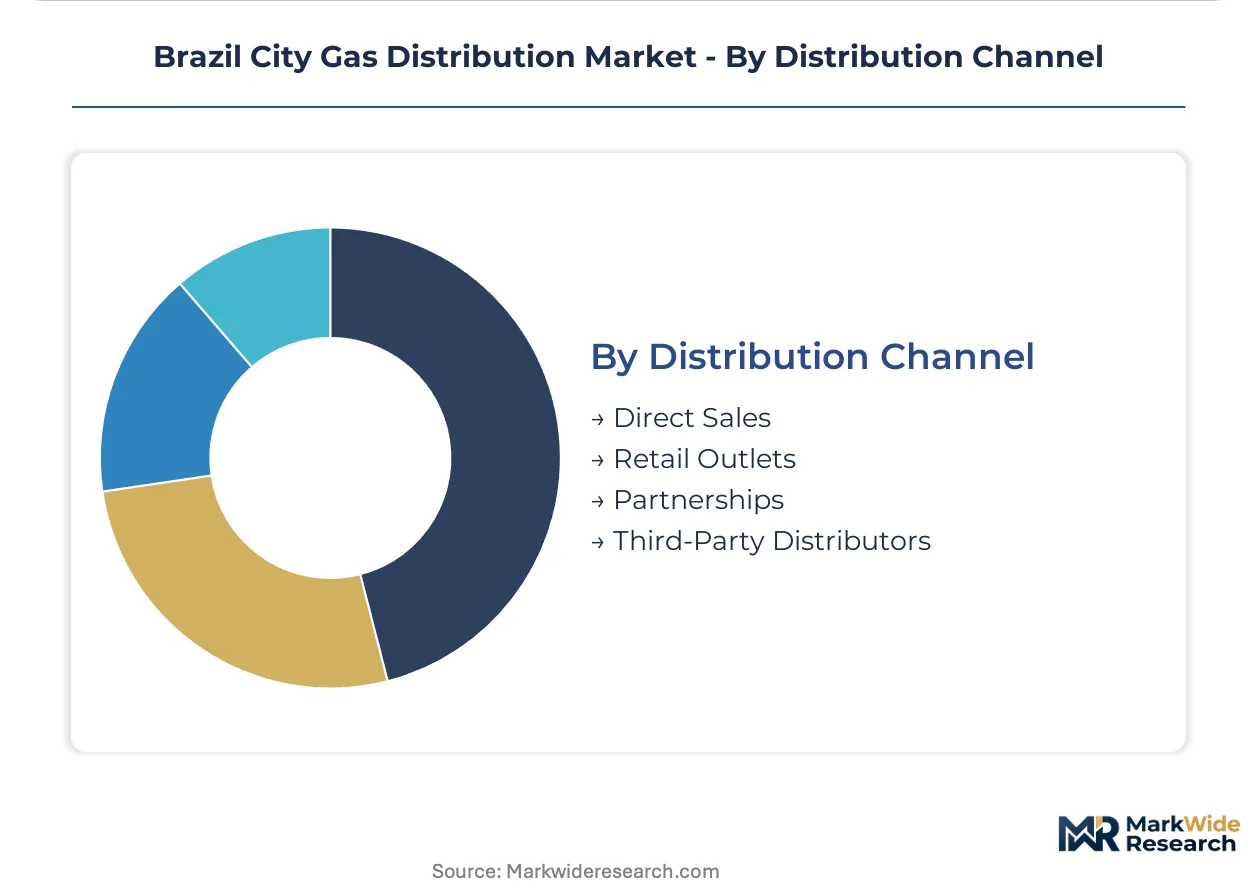
Channel economics reflect customer scale concentration, with direct sales capturing largest industrial accounts while partnership structures penetrate fragmented commercial and residential segments.
- Direct Sales:Large chemical processors and steel manufacturers negotiate bilateral supply agreements with distributors or LNG importers directly, particularly in Minas Gerais and Rio de Janeiro states under ANP secondary market reforms.
- Retail Outlets:CNG refueling stations serve fragmented freight operator demand along Santa Catarina's BR-101 corridor, with fleet card platforms consolidating purchasing across multiple transport companies.
- Partnerships:Industrial park developers integrate gas distribution infrastructure into master planning, pulling private distributor capital into greenfield concession zones.
- Third-Party Distributors:Specialized firms handle residential conversion program execution and cylinder logistics for legacy LPG customer migration in northeastern states.
Direct Sales anchor revenue concentration, with Partnerships climbing fastest as industrial park development accelerates across southeastern Brazil.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's city gas distribution infrastructure traces its modern origins to Petrobras's state-led pipeline construction programs of the 1960s-1970s, which established the southeastern corridor as the industry's operational and regulatory heartland.
São Paulo
Industrial manufacturing clusters in the ABC Paulista corridor anchor national demand volume. ANP Resolution 16/2019 unbundling protocols force new entrants to negotiate third-party pipeline access from Petrobras legacy infrastructure. Comgás maintains dense network coverage across metropolitan São Paulo, leveraging grandfathered concession rights to serve chemical processors and automotive manufacturers.
Rio de Janeiro
CEG Rio drives residential conversion programs targeting legacy LPG dependency in urban favelas and middle-class districts. ANVISA appliance safety certification requirements govern household eligibility for network connections. The Duque de Caxias petrochemical complex generates anchor industrial loads with continuous operating profiles.
Minas Gerais
Steel manufacturers and mining processors in the Belo Horizonte industrial ring negotiate direct supply agreements under ANP's New Gas Market secondary pricing reforms. Greenfield industrial park developers favor private distributors for customized pressure regulation infrastructure. The Jeceaba steel corridor pulls dedicated pipeline extensions from southeastern trunk lines.
Santa Catarina
SCGÁS anchors compressed natural gas vehicle adoption along the BR-101 coastal freight corridor connecting Itajaí Valley port terminals to interior agricultural processing centers. Fleet card platforms consolidate purchasing across fragmented transport operators. Joinville and Blumenau manufacturing clusters add industrial base loads.
Bahia
Bahiagás extends distribution networks toward the Camaçari petrochemical complex while penetrating Salvador's residential conversion zones. LNG import terminal proximity at the Pecém facility offers cost advantages over interior states dependent on pipeline transmission. State environmental licensing bodies shape project approval timelines.
Brazil City Gas Distribution Market Competitive Environment
The competitive structure tilts toward state-controlled incumbents with vertically integrated legacy concessions. Public utilities retain grandfathered transport-distribution rights, while private entrants navigate standalone network build mandates and third-party access negotiations. Three archetypes dominate: state-controlled incumbents with dense metropolitan coverage, private specialists targeting greenfield industrial parks, and regional cooperatives aggregating CNG fleet demand. Competitive repositioning concentrates on concession re-bidding preparation and digital infrastructure deployment.
Among state-controlled incumbents, CEG Rio and Comgás exemplify the integrated utility archetype with metropolitan pipeline density. SCGÁS occupies a differentiated position within the CNG vehicle corridor specialization tier. Private providers including Gás Brasiliano Distribuidora S.A. represent the new entrant segment navigating ANP unbundling protocols. The market exhibits tiered competitive dynamics where legacy concession holders defend position through network coverage, while challengers penetrate greenfield zones with customized industrial infrastructure.
| Leading Market Players |
|---|
| CEG Rio |
| MSGÁS – Companhia de Gás do Estado de Mato Grosso do Sul |
| Companhia de Gás de São Paulo (Comgás) |
| Potiguar Gas Company (Potigas) |
| Gás Brasiliano Distribuidora S.A. |
| Companhia Paranaense de Gás (Compagas) |
| SCGÁS – Companhia de Gás de Santa Catarina |
| Companhia Paraibana de Gás |
| Bahiagás – Companhia de Gás da Bahia |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ASME Section IX qualified infrastructure and standard municipal piping creates tiered margin structures that simultaneously stratify distributor pricing power and determine procurement sourcing strategies across Brazilian state concession zones.
Pricing Analysis
Bundled transport-distribution concessions command premium tariffs under grandfathered ANP licensing, while unbundled standalone distributors negotiate third-party access terms with Petrobras that compress margins on variable industrial offtake. Price differentiation hinges on pipeline density coverage and interruptible supply clause flexibility, with residential conversion programs showing highest price sensitivity due to legacy LPG cost comparisons. Pricing pressure intensifies in greenfield industrial parks where private entrants undercut public utility rates to secure anchor manufacturing loads.
Supply Chain Analysis
Direct-to-industrial-plant channels handle hyperscale chemical processor demand, while retail CNG station networks fragment across Santa Catarina freight corridors. High-grade steel pipe and polyethylene tubing draw from South Korean and Chinese metallurgical suppliers, with ASME-certified welding equipment anchored in German and US manufacturing bases. Single-source vulnerability concentrates in Petrobras-controlled high-pressure transmission backbone access. Distribution runs through state concession holders with third-party logistics partnerships for cylinder conversion logistics in northeastern residential zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's city gas distribution market offers geographic-arbitrage value where ANP regulatory unbundling in southeastern industrial corridors contrasts with permissive state-level environmental licensing timelines in Pernambuco and Ceará conversion zones.
For Market Incumbents: Lock in pipeline density advantages through preemptive concession re-bidding preparation and accelerated digital meter deployment before ANP secondary market pricing reforms erode long-term contract security. Vertical integration into embedded power generation co-location projects defends margin position against LNG importer direct supply encroachment. For New Entrants and Emerging Players: The premium-to-economy service gap in northeastern residential conversion zones offers white-space penetration where municipal operators lack capital for network extension. Target Pernambuco's LPG-dependent cooking market with simplified pressure regulation infrastructure and ANVISA-certified appliance bundling partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone private distributors face Petrobras access negotiation bottlenecks and ASME welding certification workforce constraints. Mid-cap specialists with greenfield industrial park relationships and IoT-enabled maintenance platforms represent acquisition targets with defensive positioning. Watch ANP concession re-bidding announcement timing as inflection signal for competitive repositioning cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Re-bidding Preparation | Grandfathered transport-distribution rights determine long-term tariff structures under ANP Resolution 16/2019 protocols. |
| IoT Infrastructure Deployment | Smart pressure regulation stations at São Paulo industrial nodes compress emergency response times below fifteen minutes. |
| Backward Integration into Embedded Generation | Captive gas-fired power at Minas Gerais steel plants secures anchor loads with 8,000+ annual operating hours. |
| CNG Corridor Network Expansion | Fleet card platform consolidation across Santa Catarina's BR-101 logistics cluster locks in freight operator demand. |
| Residential Conversion Program Scaling | ANVISA-certified appliance partnerships in Rio de Janeiro favelas accelerate LPG-to-piped gas migration timelines. |
Study Parameters
Direct dialogue with ANP regulatory officers, concession planning directors at state-controlled utilities, private distributor procurement heads, and industrial park development executives combined with secondary validation from ANP resolution filings, Petrobras divestiture protocol disclosures, and state environmental licensing databases. Bottom-up connection point modeling triangulated against top-down regional gas demand projections from Brazilian Institute of Geography and Statistics consumption surveys.
Segmented volume outputs across utility type, end user category, and service tier dimensions were generated through the projection horizon using elasticity-adjusted CAGR derivation anchored in historical concession expansion rates and greenfield industrial park pipeline commissioning timelines. Forecast inputs incorporated ANP secondary market pricing reform implementation probability and LNG import terminal capacity utilization assumptions.
The model assumes a particular technology adoption path; alternative pathways for hydrogen blending in distribution networks or accelerated biomethane injection would alter the outlook for carbon intensity scoring and residential conversion eligibility. Forecasts reflect documented assumptions about Petrobras third-party access tariff negotiation outcomes and state-level environmental licensing velocity. Periodic stress-testing of base assumptions against ANP regulatory announcement timing and commodity price volatility bands is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Distribution Panel Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Distribution Board Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
Global Power Distribution Component Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market
Power Distribution
Power Distribution Cables Market