
 Full-Cell Solar Module Market | 2026-2036
Full-Cell Solar Module Market Size, Share, and Industry Trends Forecast 2026-2036
Full-Cell Solar Module Market Insights
Photovoltaic engineering talent scarcity is reorganizing production geography as manufacturers chase qualified process engineers and cell metallization specialists. JinkoSolar Holding Co., Ltd. leverages its integrated n-type wafer-to-module footprint to control cost curves across multiple continents. LONGi Green Energy Technology Co., Ltd. anchors its competitive edge through relentless R&D intensity in silicon heterojunction architectures. Canadian Solar Inc. competes by sustaining diversified manufacturing bases that navigate tariff and logistics volatility.
Full-cell solar modules integrate complete, uncut photovoltaic cells into laminated glass-backsheet or glass-glass assemblies, typically achieving 60, 72, or 144-cell configurations with power outputs ranging from 400W to over 700W in commercial formats; their primary purpose is maximizing active silicon area and reducing resistive losses at cell boundaries for ground-mounted and rooftop energy generation. Monocrystalline product types dominate installed capacity due to sustained efficiency premiums and declining wafer costs, while bifacial variants capture margin pools in utility-scale solar farms where albedo gain justifies structural complexity. PERC technology retains manufacturing scale leadership though HJT lines attract new capital for higher conversion ceilings.
FERC's interconnection queue reforms in the United States, the EU Green Deal's embodied carbon thresholds, and China's GB standards for module efficiency and recycling compliance collectively reshape market access and product design requirements across major demand centers. Stakeholders must monitor how regulatory divergence between these jurisdictions affects module certification costs and supply chain routing decisions.
Market Dynamics
Cell metallization engineering scarcity is redrawing manufacturing maps as producers chase qualified process engineers across Jiangsu Province, Vietnam's northern industrial zones, and emerging Southeast Asian clusters.
Growth Catalysts
- EU Green Deal renewable mandates:Binding efficiency thresholds under EU Green Deal regulations are accelerating procurement of high-output monocrystalline units across European utility-scale portfolios.
- Heterojunction cell architectures:Conversion ceiling advantages in silicon heterojunction designs are pulling fresh capital away from legacy PERC lines toward next-generation production equipment.
- India's PLI scheme:Production-linked incentive disbursements are concentrating module assembly capacity in Gujarat and Tamil Nadu manufacturing corridors.
Market Restraints
- Polysilicon input volatility:Price swings in metallurgical-grade silicon feedstock compress margin predictability for wafer-to-module producers.
- Jiangsu supply concentration:Overreliance on a single Chinese province for cell and module output creates geopolitical and logistics contingency exposure.
- Albedo dependency of bifacial formats:Site-specific ground reflectance requirements limit deployability in low-reflectance terrain.
Strategic Opportunities
- Saudi Arabia's renewable auctions:Underpenetrated Middle Eastern solar procurement is opening volume contracts for glass-glass bifacial suppliers with desert-proven thermal cycling credentials.
- Agrivoltaic dual-use installations:Elevated mounting configurations for agricultural land integration are creating specialized module form-factor demand.
- US IRA domestic content bonuses:Adder payments for domestically manufactured cells are incentivizing North American wafer capacity expansion.
Industry Challenges
- Cell metallization specialist shortage:Screen printing and plating process engineering expertise gaps are extending line commissioning timelines and raising talent acquisition costs.
- Multi-jurisdiction certification complexity:Divergent IEC, UL, and GB standards testing protocols are lengthening product qualification cycles for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full-Cell Solar Module Market |
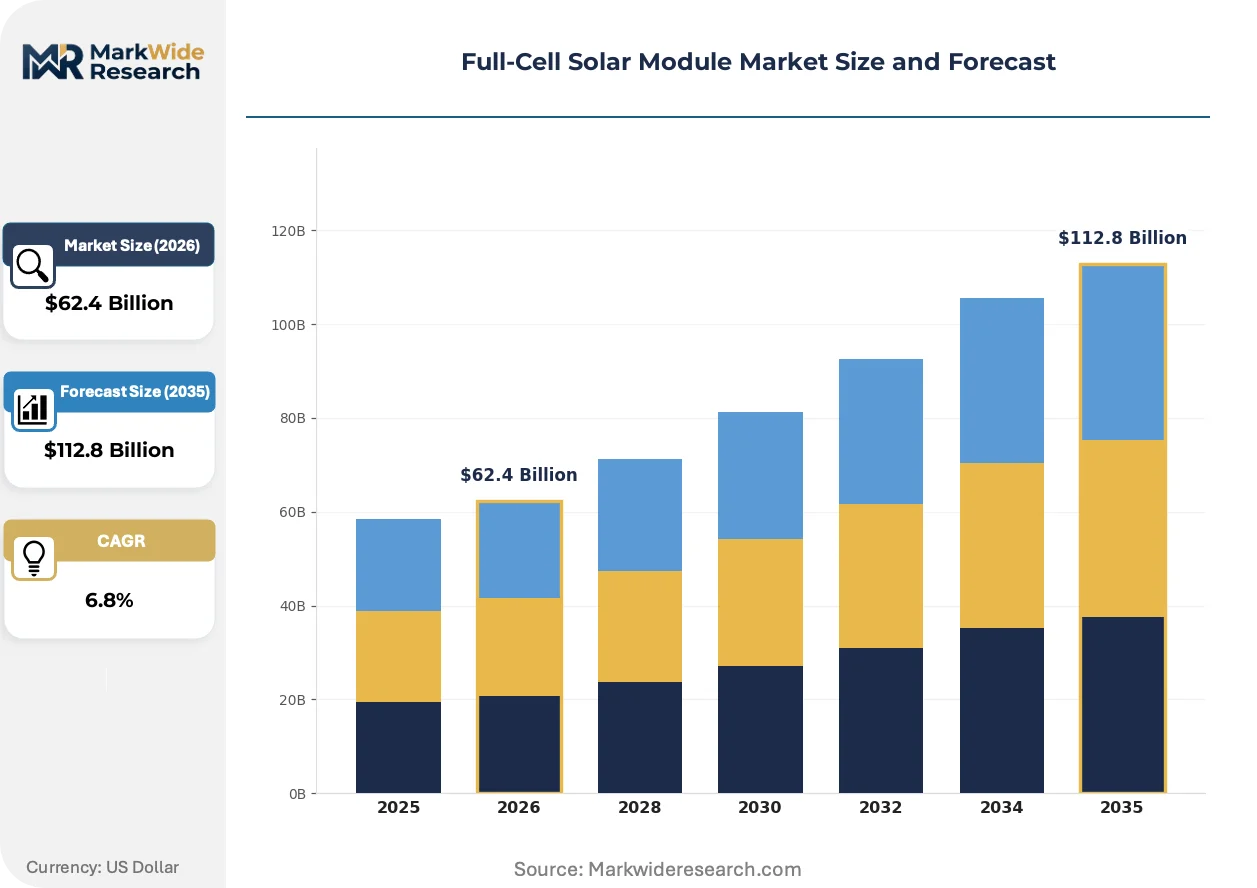
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Technology: PERC, HJT, CdTe, Organic Photovoltaic End User: Residential, Commercial, Industrial, Utility Scale Application: On-Grid, Off-Grid, Floating Solar, Solar Farms |
| Companies Covered | JinkoSolar Holding Co., Ltd., LONGi Green Energy Technology Co., Ltd., JA Solar Holdings Co., Ltd., Trina Solar Co., Ltd., Tongwei Solar, Hanwha Q CELLS, Canadian Solar Inc., Astronergy, First Solar, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full-Cell Solar Module Market Trends and Innovations
Module architecture is splitting along efficiency-versus-cost fault lines as heterojunction and TOPCon processes mature against entrenched PERC scale advantages. Regulatory carbon accounting is embedding into procurement criteria faster than supply chains can adapt certification infrastructure.
Silicon heterojunction cell technology is bifurcating module competitive tiers. The architecture deposits amorphous silicon layers on crystalline wafers to suppress recombination losses. European and Japanese utility buyers are prioritizing heterojunction modules for premium-tariff projects despite 15-20% manufacturing cost premiums. The technology is bifurcating vendor positioning into efficiency-led premium suppliers and cost-optimized PERC incumbents.
FERC interconnection queue reforms in the United States are compressing project approval timelines. The 2023 rule changes mandate cluster studies and firm milestone requirements. Utility-scale developers in Texas and California are restructuring procurement schedules to align with accelerated grid connection windows.
Buyers are consolidating supplier relationships around integrated wafer-to-module producers. Large independent power producers are reducing vendor counts from twelve to four qualified sources. This concentration is most visible in India's utility-scale segment where developers prioritize bankability and domestic content compliance over pure price competition.
Full-Cell Solar Module Market Segmentation
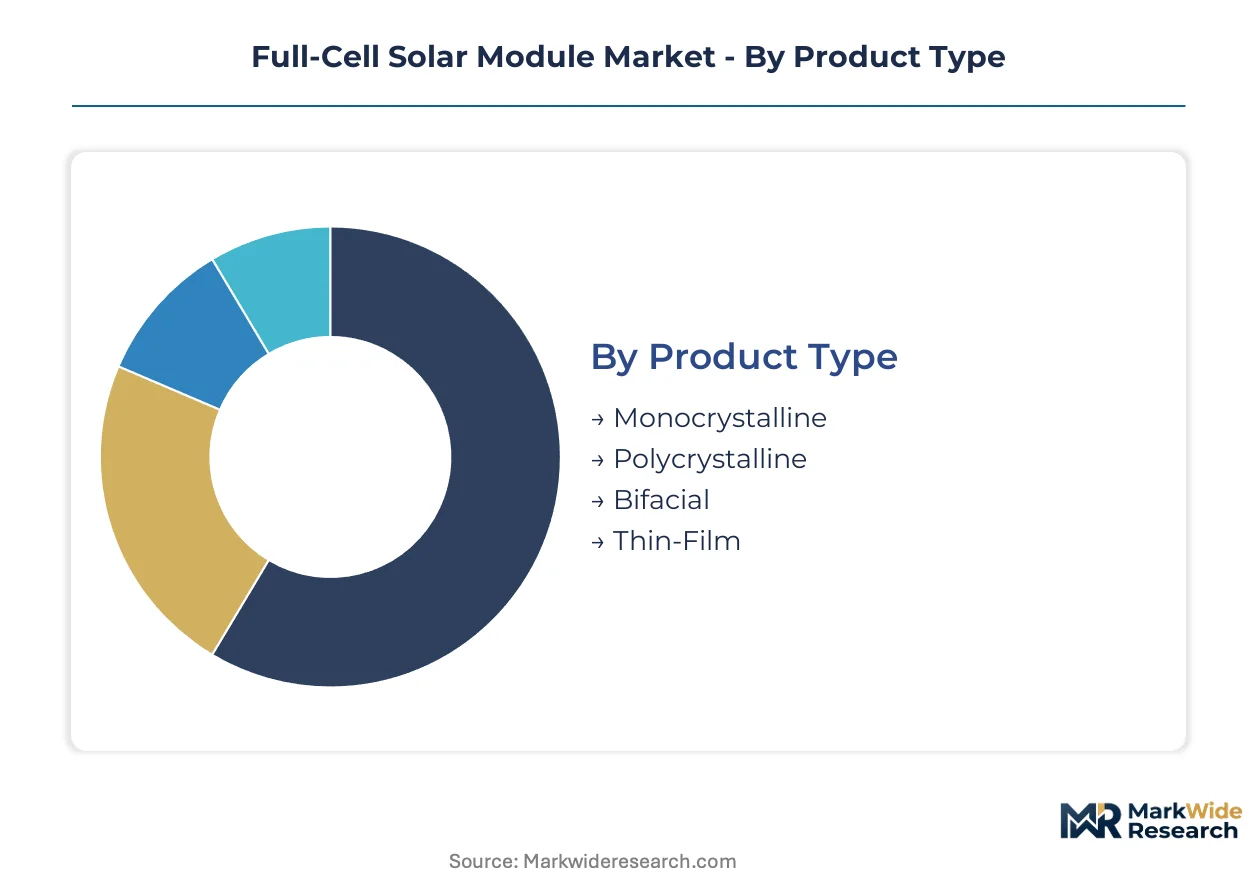
Full-cell solar module procurement splits along efficiency certification tiers and grid-connection regimes. Regulatory divergence between EU Green Deal carbon thresholds, India's PLI domestic content rules, and US IRA manufacturing bonuses forces suppliers to maintain parallel product lines optimized for distinct compliance environments.
Product Type:
EU Green Deal efficiency mandates and India's BIS certification requirements create divergent product qualification pathways across crystalline and thin-film formats.
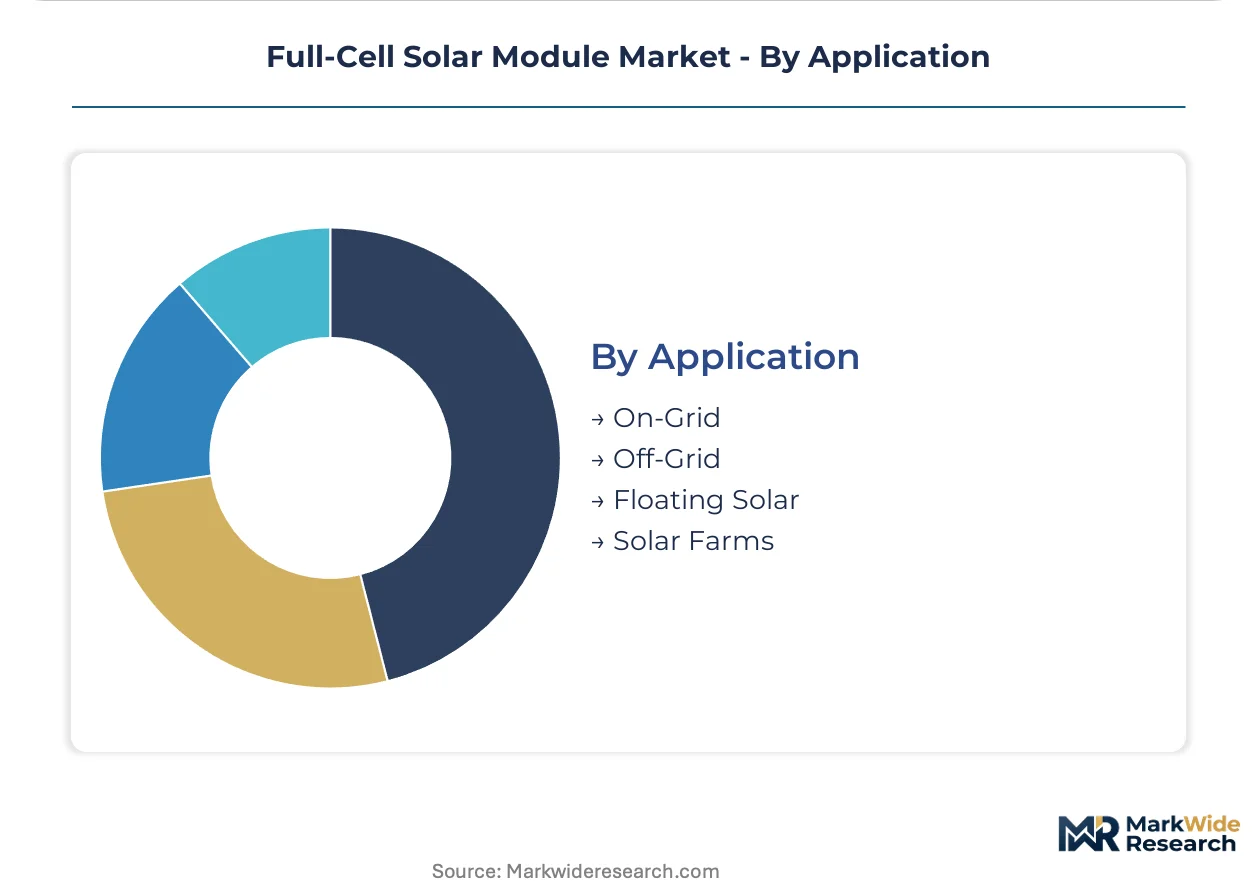
- Monocrystalline:Single-crystal silicon wafers deliver the highest conversion efficiencies in commercial formats, typically exceeding 21% in PERC architectures and 24% in heterojunction designs. Utility-scale developers in India, China, and the United States prioritize monocrystalline units for projects where land constraints or tariff structures reward maximum output per square meter.
- Bifacial:Dual-glass laminates capture direct irradiance on the front face plus ground-reflected albedo on the rear, adding 5-20% energy yield in high-reflectance desert or snow environments. Saudi Arabia's renewable auctions and Chilean Atacama installations are driving procurement of desert-proven bifacial modules with enhanced thermal cycling credentials.
- Polycrystalline:Multi-crystal silicon cells trade efficiency for manufacturing simplicity, retaining cost-competitive positions in price-sensitive distributed generation markets.
- Thin-Film:Cadmium-telluride and CIGS absorber layers enable lightweight, flexible form factors for building-integrated and weight-constrained rooftop applications.
Monocrystalline handles the majority of throughput; bifacial is gaining share fastest in utility-scale procurement.
Technology:
Capital allocation splits between mature PERC scale advantages and next-generation conversion ceilings, with equipment depreciation schedules and talent scarcity shaping technology migration timelines.
- PERC:Passivated emitter and rear contact architecture dominates installed manufacturing capacity through process maturity and equipment availability. Jiangsu Province and Vietnam's northern industrial zones maintain the densest concentrations of operational PERC lines, though cell metallization specialist shortages are extending commissioning timelines for greenfield expansions.
- HJT:Silicon heterojunction deposits intrinsic amorphous silicon layers on crystalline wafers to suppress surface recombination, achieving laboratory efficiencies above 26%. European and Japanese utility buyers accept 15-20% manufacturing cost premiums for HJT modules in premium-tariff projects where efficiency translates directly to land-area savings.
- CdTe:Cadmium-telluride thin-film technology bypasses silicon supply chains entirely, with First Solar's integrated manufacturing commanding utility-scale volumes in the United States where domestic content bonuses apply.
- Organic Photovoltaic:Solution-processed organic absorbers enable ultra-lightweight, semi-transparent modules for building-integrated and portable power applications.
PERC retains the largest installed base; HJT is climbing the fastest on new capital deployment.
End User:
Customer scale determines financing structures, certification requirements, and supplier consolidation patterns across the value chain.
- Utility Scale:Independent power producers and renewable energy developers procure multi-hundred-megawatt volumes through competitive auctions and power purchase agreements. India's utility-scale segment demonstrates the sharpest supplier consolidation, with developers reducing qualified vendor counts from twelve to four sources to prioritize bankability and domestic content compliance.
- Industrial:Manufacturing facilities and data centers deploy rooftop and carport installations to hedge electricity price volatility and meet corporate sustainability commitments.
- Commercial:Office buildings, retail chains, and logistics warehouses balance installation costs against available roof area and net-metering tariff structures.
- Residential:Single-family and multi-family housing installations depend on installer network density, permitting streamlining, and interconnection queue efficiency.
Utility scale commands the dominant procurement volume; industrial is expanding most quickly on corporate renewable targets.
Application:
Grid-connection topology and site constraints dictate module form-factor, mounting architecture, and electrical configuration requirements.
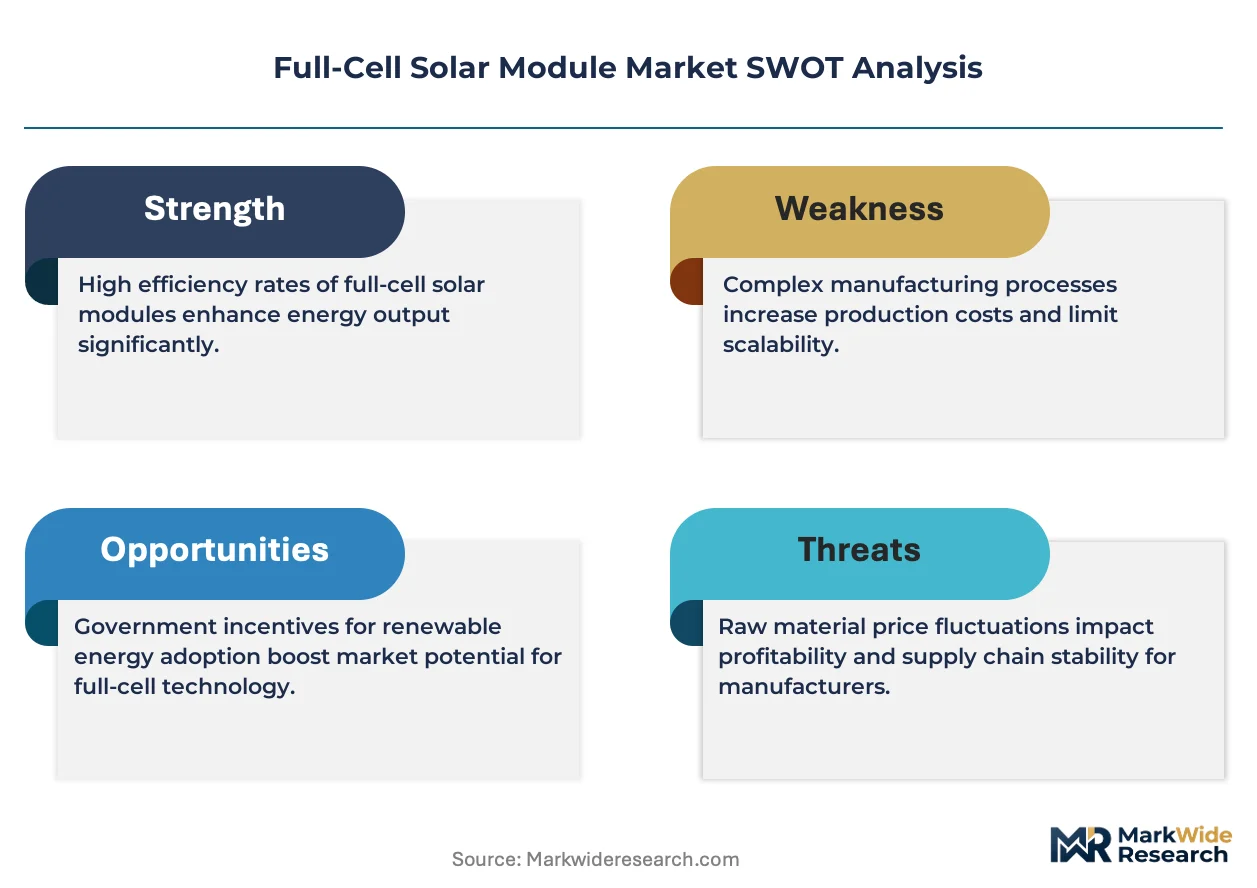
- Solar Farms:Ground-mounted utility-scale installations deploy standardized 72-cell and 144-cell modules in fixed-tilt or tracking configurations across thousands of hectares. FERC interconnection queue reforms in the United States are compressing project approval timelines, with Texas and California developers restructuring procurement schedules to align with accelerated grid connection windows.
- On-Grid:Distributed generation systems export surplus electricity to utility networks under net-metering or feed-in tariff arrangements, requiring grid-code compliance and anti-islanding protection.
- Floating Solar:Pontoon-mounted arrays on reservoirs and quarry lakes reduce land-use conflicts and benefit from evaporative cooling effects that boost module efficiency.
- Off-Grid:Stand-alone systems with battery storage serve remote telecommunications, mining operations, and rural electrification programs beyond distribution network reach.
Solar farms account for the dominant deployment capacity; floating solar is showing the steepest expansion trajectory on land-constrained Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers in the United States, China, and India deploy full-cell modules at radically different scales and efficiency thresholds, while European procurement prioritizes embodied carbon metrics over raw wattage economics. This consumption-mix differential shapes distinct certification requirements and supply chain routing across major demand centers.
United States
Independent power producers in Texas and California are restructuring procurement schedules around FERC's accelerated interconnection queue timelines. IRA domestic content bonuses are incentivizing North American wafer capacity expansion beyond legacy assembly operations. Arizona and Georgia manufacturing corridors attract greenfield cell metallization investments.
China
Jiangsu Province hosts the densest concentration of operational PERC and heterojunction lines globally, though talent scarcity extends commissioning timelines. GB standards for module efficiency and recycling compliance are tightening under dual carbon goals. Anhui and Sichuan provinces emerge as alternative production bases.
India
PLI scheme disbursements concentrate module assembly in Gujarat and Tamil Nadu manufacturing corridors, with developers reducing qualified vendor counts from twelve to four sources. BIS certification requirements filter import flows. Rajasthan and Karnataka solar parks drive procurement volume.
Germany
EU Green Deal embodied carbon thresholds reshape procurement criteria for utility-scale portfolios, favoring high-output monocrystalline units. REACH and RoHS compliance adds qualification layers for Asian suppliers. Saxony-Anhalt and Brandenburg industrial zones host module testing and certification facilities.
Saudi Arabia
Underpenetrated Middle Eastern solar procurement opens volume contracts for glass-glass bifacial suppliers with desert-proven thermal cycling credentials. Renewable auction structures prioritize bankable technology packages. NEOM and Riyadh industrial city developments concentrate project pipelines.
Full-Cell Solar Module Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling wafer-to-module cost curves and the latter competing on niche form factors or regional compliance expertise. The market structure rewards backward integration into polysilicon and cell metallization capacity. Three archetypes dominate: integrated Chinese conglomerates with multi-continent manufacturing footprints, Korean-Japanese technology licensors, and North American thin-film specialists. Competitive moves center on capacity expansion in tariff-advantaged jurisdictions and technology licensing agreements to access heterojunction process IP.
Among integrated Chinese producers, JinkoSolar Holding Co., Ltd., LONGi Green Energy Technology Co., Ltd., and Canadian Solar Inc. occupy positions that exemplify divergent strategic postures. JinkoSolar represents the n-type wafer-to-module integration archetype with multi-continent manufacturing control. LONGi anchors the relentless R&D intensity model in silicon heterojunction architectures. Canadian Solar sits within the diversified manufacturing base archetype that navigates tariff and logistics volatility through geographic dispersion.
| Leading Market Players |
|---|
| JinkoSolar Holding Co., Ltd. |
| LONGi Green Energy Technology Co., Ltd. |
| JA Solar Holdings Co., Ltd. |
| Trina Solar Co., Ltd. |
| Tongwei Solar |
| Hanwha Q CELLS |
| Canadian Solar Inc. |
| Astronergy |
| First Solar, Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates above eighty percent in Jiangsu Province cell fabs are compressing marginal cost curves and anchoring global price floors for monocrystalline modules. This scale concentration simultaneously tightens supply availability during polysilicon input volatility and amplifies pricing power for integrated producers with captive wafer supply.
Pricing Analysis
Long-term offtake contracts dominate utility-scale procurement, with project-based spot purchases filling interstitial demand during commissioning accelerations. Pricing stratifies across premium HJT, standard PERC, and economy polycrystalline tiers based on efficiency certification and bankability ratings. Cost compression in standard PERC modules is intensifying because equipment depreciation schedules are shortening faster than process yields improve. Distributed generation buyers in residential and commercial segments exhibit highest price sensitivity, while utility-scale independent power producers prioritize domestic content compliance and grid-connection certainty over unit cost minimization.
Supply Chain Analysis
China and Vietnam anchor cell and module assembly, while Malaysia and Thailand host expanding backsheet and junction box fabrication. Metallurgical-grade polysilicon, silver paste for screen-printed metallization, and tempered solar glass constitute critical input dependencies. Single-source vulnerability concentrates in Jiangsu Province for high-efficiency cell output, creating contingency exposure during regional logistics disruptions or regulatory inspections. Distribution runs through direct manufacturer-to-developer contracts for utility volumes, with regional distributors and EPC contractors handling fragmented commercial and residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology bifurcation between PERC incumbents and HJT aspirants is fragmenting competitive tiers, creating specialist niches for cell metallization engineering services and regional certification consultancies.
For Market Incumbents: Secure backward integration into n-type wafer capacity to defend margin structures against polysilicon price volatility and emerging heterojunction specialists. Anchor cell metallization engineering talent in Arizona and Georgia manufacturing corridors to capture IRA domestic content bonuses. Prioritize multi-jurisdiction certification infrastructure to compress product qualification cycles for cross-border supply.
For New Entrants and Emerging Players: Anchor in Saudi Arabia's renewable auction pipeline and Chilean Atacama installations where bifacial thermal cycling credentials command premium positioning. Target agrivoltaic dual-use configurations as the most penetrable application segment, leveraging elevated mounting expertise to differentiate from commodity module suppliers. Pursue technology licensing agreements with Korean-Japanese heterojunction IP holders to bypass R&D capital intensity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with captive polysilicon and demonstrated HJT yield ramp capabilities over pure-play assemblers. Long-term viability hinges on five-to-ten year windows for PERC-to-HJT transition completion and recycling compliance infrastructure maturation. Monitor FERC interconnection queue processing velocity as the critical inflection signal for utility-scale procurement acceleration or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell Metallization Capacity Expansion | Captures scarce engineering talent in Arizona and Georgia corridors to satisfy IRA domestic content thresholds. |
| Heterojunction Technology Licensing | Accelerates access to amorphous silicon deposition IP without multi-year R&D capital commitment. |
| Desert-Proven Bifacial Certification | Unlocks Saudi Arabian and Atacama procurement where thermal cycling credentials filter supplier pools. |
| Multi-Jurisdiction Testing Infrastructure | Compresses IEC, UL, and GB qualification cycles for cross-border utility-scale contracts. |
| Agrivoltaic Form-Factor Development | Addresses specialized elevated mounting demand from agricultural land integration projects. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation against EIA generation data, IEA renewable technology reports, FERC interconnection filings, and project development databases. Bottom-up module shipment tallies by technology and top-down capacity utilization estimates by manufacturing cluster were triangulated to anchor volume and value outputs.
Variance decomposition across the projection horizon isolates drivers by technology migration timelines, regulatory incentive phase-out schedules, and raw material input volatility. Segmentation dimensions modeled include cell architecture, product efficiency tier, end-use scale, application topology, and regional regulatory framework. CAGRs were derived from installed capacity buildout trajectories and learning curve effects on manufacturing cost structures. Forecast inputs incorporate polysilicon spot price volatility bands and interconnection queue processing velocity assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained IRA domestic content bonuses and EU Green Deal efficiency threshold enforcement; material deviation in either policy regime would warrant model refresh. Specific risk factors that could revise forecasts include abrupt polysilicon supply disruptions, heterojunction yield ramp failures, or interconnection queue reform reversals. Recalibration cycles align with material shifts in federal incentive structures and grid-connection regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Australia Solar Power Market