
 Asia-Pacific Solar Tracker Market | 2026-2036
Asia-Pacific Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Solar Tracker Market Analysis
IEC 62817 certification for solar tracker design qualification is unwinding the competitive field, filtering out suppliers lacking validated structural and control-system testing. NexTracker sustains technology leadership through its distributed drive architecture and software-optimized row tracking. Trina Solar anchors supply security through backward integration into steel torque tubes and control electronics manufacturing. GameChange Solar competes on installation velocity with its pre-assembled tracker systems designed for high-labor-cost environments.
A solar tracker is a mechanical racking system that orients photovoltaic modules toward the sun throughout the day, typically achieving 20-35% additional energy yield over fixed-tilt configurations through single-axis rotation along a north-south path. The primary commercial purpose is maximizing specific energy production per hectare for utility-scale and commercial ground-mounted installations where land and interconnection costs dominate project economics. Single-axis trackers dominate ground-mounted utility installations across the Asia-Pacific region due to superior levelized cost of energy performance on flat terrain. Smart trackers incorporating machine-learning-based predictive positioning and self-cleaning actuation represent the fastest-expanding technology segment, capturing margin pools from operations-and-maintenance cost reduction. Dual-axis systems retain niche positioning in concentrated solar-thermal hybrid applications and high-latitude Japanese installations where solar elevation angles vary substantially across seasons.
India's Bureau of Indian Standards mandates structural load testing and corrosion resistance verification for tracker systems deployed under national solar mission tenders, directly shaping supplier qualification and local manufacturing requirements. China's Ministry of Ecology and Environment enforces dual carbon compliance timelines that accelerate tracker adoption in state-owned utility portfolios while GB standards govern steel galvanization and electronic control reliability. Australia's Clean Energy Council maintains approved product lists that gate market access for tracker inverter integration packages. Stakeholders must monitor evolving domestic content thresholds and carbon-border adjustment mechanisms as these regulatory instruments increasingly determine competitive viability across national procurement programs.
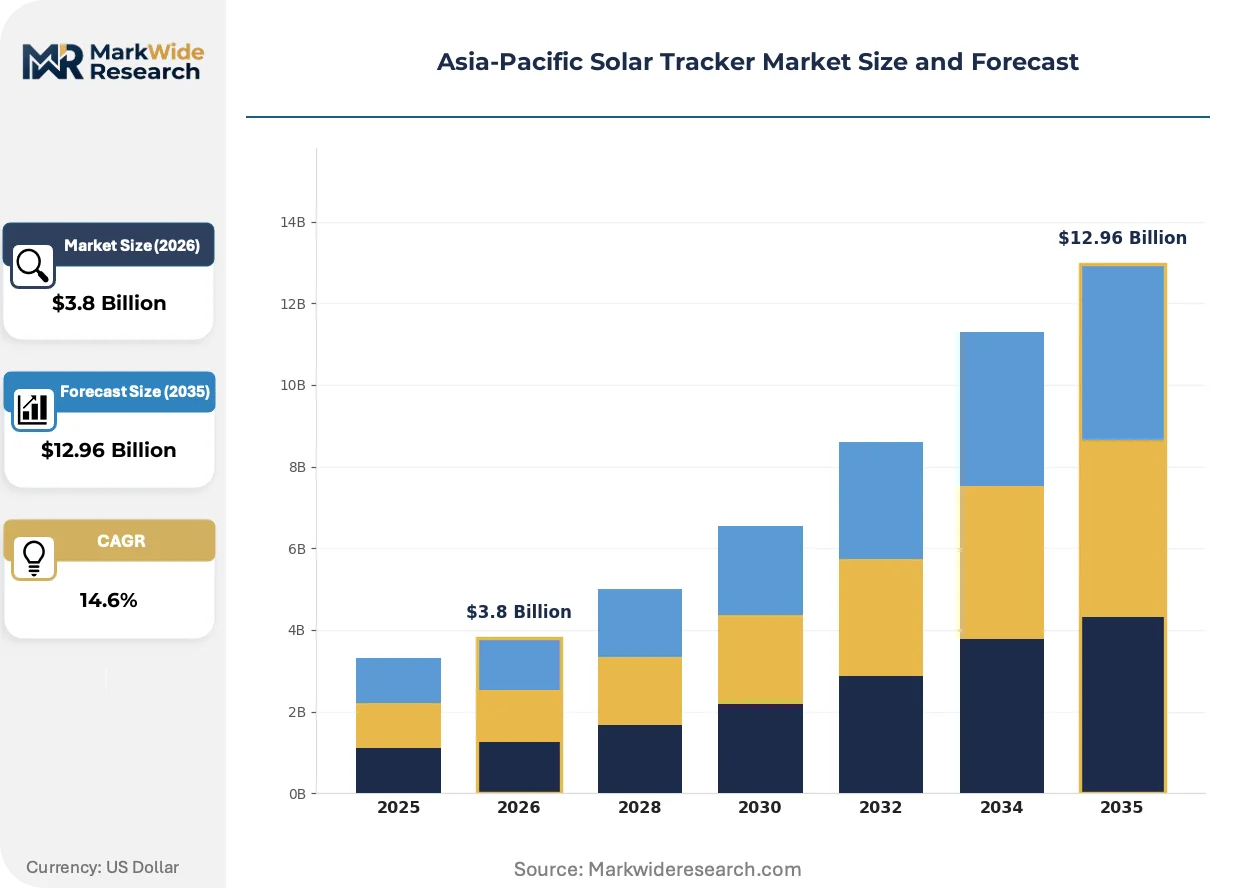
Market Dynamics
Utility-scale developers across the Asia-Pacific region are consolidating procurement around IEC 62817-certified tracker platforms, compressing supplier margins while elevating technical qualification barriers for new entrants.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic content mandates for national solar mission tenders are accelerating local tracker production capacity in Gujarat and Rajasthan.
- Machine-learning predictive positioning:Smart tracker algorithms that anticipate cloud cover and optimize row synchronization are capturing O&M cost reduction pools.
- Arid land availability:High-irradiance zones in Australia's Queensland and Western Australia are enabling gigawatt-scale single-axis tracker deployment with superior LCOE performance.
Market Restraints
- Steel price volatility:Torque tube galvanization costs fluctuate with Chinese GB-standard steel output, squeezing tracker margin structures.
- Supplier concentration:Control electronics and drive motor sourcing concentrates among a limited set of East Asian component specialists.
- Grid interconnection queues:Transmission access delays in India's renewable-rich states freeze project commissioning timelines regardless of tracker readiness.
Strategic Opportunities
- Vietnam's utility-scale pipeline:Feed-in tariff transitions toward auction-based procurement are creating openings for tracker-integrated EPC offerings.
- Agrivoltaic convergence:Elevated tracker architectures that maintain agricultural activity underneath are penetrating Japan's land-constrained prefectures.
- Carbon-border adjustment preparation:Chinese dual carbon compliance timelines are pressuring state-owned utilities to document embodied carbon in tracker steel sourcing.
Industry Challenges
- Structural engineering talent scarcity:Wind load modeling and geotechnical assessment capabilities lag tracker deployment velocity in emerging markets.
- IEC 62817 certification timelines:Extended third-party validation cycles for new tracker designs delay market entry by 12-18 months.
- Legacy SCADA integration:Retrofitting predictive positioning algorithms into existing plant control architectures demands custom protocol bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Solar Tracker Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axis, Dual-Axis, Fixed Tilt, Smart Trackers Technology: Vertical Axis, Horizontal Axis, Active Control, Passive Control End User: Utilities, Commercial, Residential, Industrial Installation: Ground-Mounted, Rooftop, Floating, Others |
| Companies Covered | Soltec Energias Renovables S.L., PV Hardware Solutions S.L.U., NexTracker Inc., Antaisolar, SunPower Corporation, Array Technologies Inc., Trina Solar, GameChange Solar, Arctech Solar Holding Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Solar Tracker Market Emerging Trajectories
Software-defined tracker control is displacing mechanical hardware as the primary value differentiator, with algorithmic optimization and predictive maintenance commanding premium positioning in utility procurement.
Distributed drive architectures are displacing centralized motor-and-linkage systems across utility-scale installations. Indian and Australian developers facing high-labor-cost environments or remote site access constraints are adopting self-powered row controllers with wireless mesh communication. This topology is displacing trenching-intensive cabling and reducing civil balance-of-system costs by eliminating central drive foundations.
China's Ministry of Ecology and Environment dual carbon enforcement is tightening embodied carbon disclosure requirements for steel components in state-owned utility tenders. GB standards for galvanization are expanding to cover carbon intensity certification, forcing tracker suppliers to requalify domestic torque tube sources. Projects in China's northwestern renewable bases are now prioritizing suppliers with verified low-carbon steel supply chains.
Integrated EPC-tracker procurement bundles are consolidating vendor relationships as developers seek single-point accountability for energy yield guarantees. Australian utility-scale projects are leading this consolidation, with Clean Energy Council approved product lists gating inverter-tracker package eligibility. This bundling is compressing standalone tracker hardware margins while expanding software and O&M service attachment rates.
Asia-Pacific Solar Tracker Market Segmentation
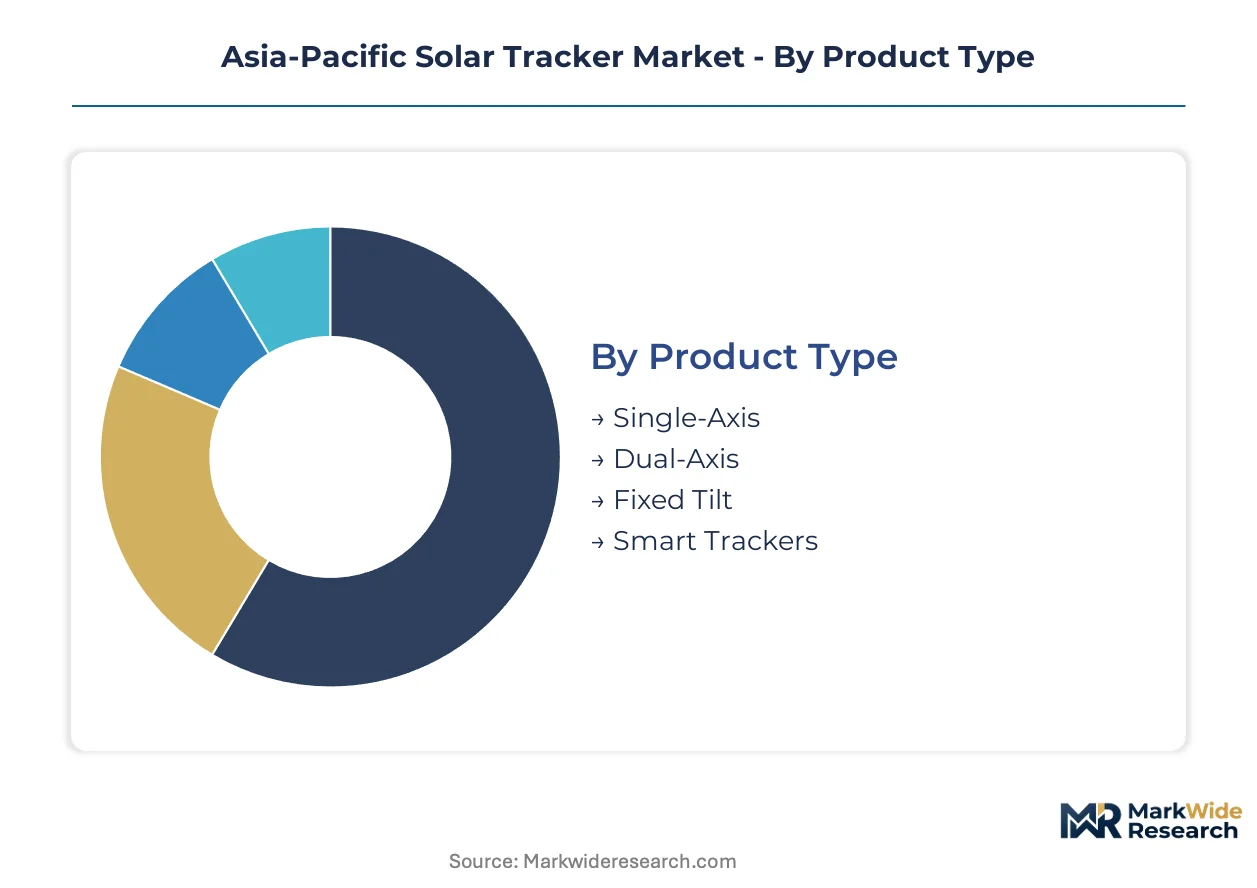
Solar tracker segmentation in the Asia-Pacific region reveals how technology choices map to project economics and regulatory environments. Product architecture, control systems, and installation topology each create distinct margin pools that suppliers target through specialized engineering and certification strategies.
Product Type:
Margin concentration follows the complexity gradient from basic mechanical systems to software-integrated platforms, with premium capture shifting toward predictive control capabilities.
- Single-Axis:Horizontal rotation along a north-south axis delivers 20-35% energy yield improvement over fixed-tilt configurations. Demand concentrates in India's Rajasthan and Gujarat states where gigawatt-scale parks on flat arid terrain maximize levelized cost of energy performance. IEC 62817 certification requirements from India's BIS are filtering supplier qualification and compressing hardware margins.
- Smart Trackers:Machine-learning-based predictive positioning algorithms anticipate cloud cover and optimize row synchronization for operations-and-maintenance cost reduction. Australia's Clean Energy Council approved product lists are gating market access for these integrated control packages, elevating software and service attachment rates.
- Dual-Axis:Azimuth and elevation tracking for concentrated solar-thermal hybrid applications and high-latitude Japanese installations where seasonal solar elevation variation is substantial.
- Fixed Tilt:Non-tracking racking for cost-constrained distributed generation and rooftop applications where mechanical complexity outweighs yield benefits.
The dominant share belongs to Single-Axis, while Smart Trackers is closing the gap fastest.
Technology:
Control methodology differentiation separates commodity hardware from value-capturing software platforms across procurement categories.
- Active Control:Motorized drive systems with real-time sensor feedback and programmable positioning algorithms. Indian developers facing high-labor-cost environments are adopting self-powered row controllers with wireless mesh communication, displacing trenching-intensive cabling and reducing civil balance-of-system costs.
- Horizontal Axis:Single-axis rotation geometry dominating ground-mounted utility installations across the Asia-Pacific region due to superior terrain adaptability and structural efficiency.
- Vertical Axis:Alternative rotation geometry for specialized terrain constraints and concentrated solar power applications with different optical requirements.
- Passive Control:Thermal or mechanical tracking without external power, limited to niche applications with extreme remote access constraints or minimal maintenance capability.
Active Control commands the largest installed base, with Horizontal Axis expanding most quickly through standardization.
End User:
Customer type determines procurement scale, contract structure, and service integration depth across national markets.
- Utilities:State-owned and independent power producers operating gigawatt-scale solar parks with 25-year power purchase agreements. China's MEE dual carbon compliance timelines are accelerating tracker adoption in state-owned portfolios while GB standards govern steel galvanization and electronic control reliability.
- Commercial:Corporate off-takers and distributed generation developers seeking behind-the-meter energy solutions with shorter payback horizons.
- Industrial:Manufacturing facilities and data centers with high baseload consumption and sustainability procurement mandates.
- Residential:Individual property owners with limited scale economics, rarely deploying trackers due to cost-to-yield ratios favoring fixed-tilt or building-integrated solutions.
Utilities retain the dominant procurement volume, though Commercial is gaining share fastest through corporate renewable energy certificates.
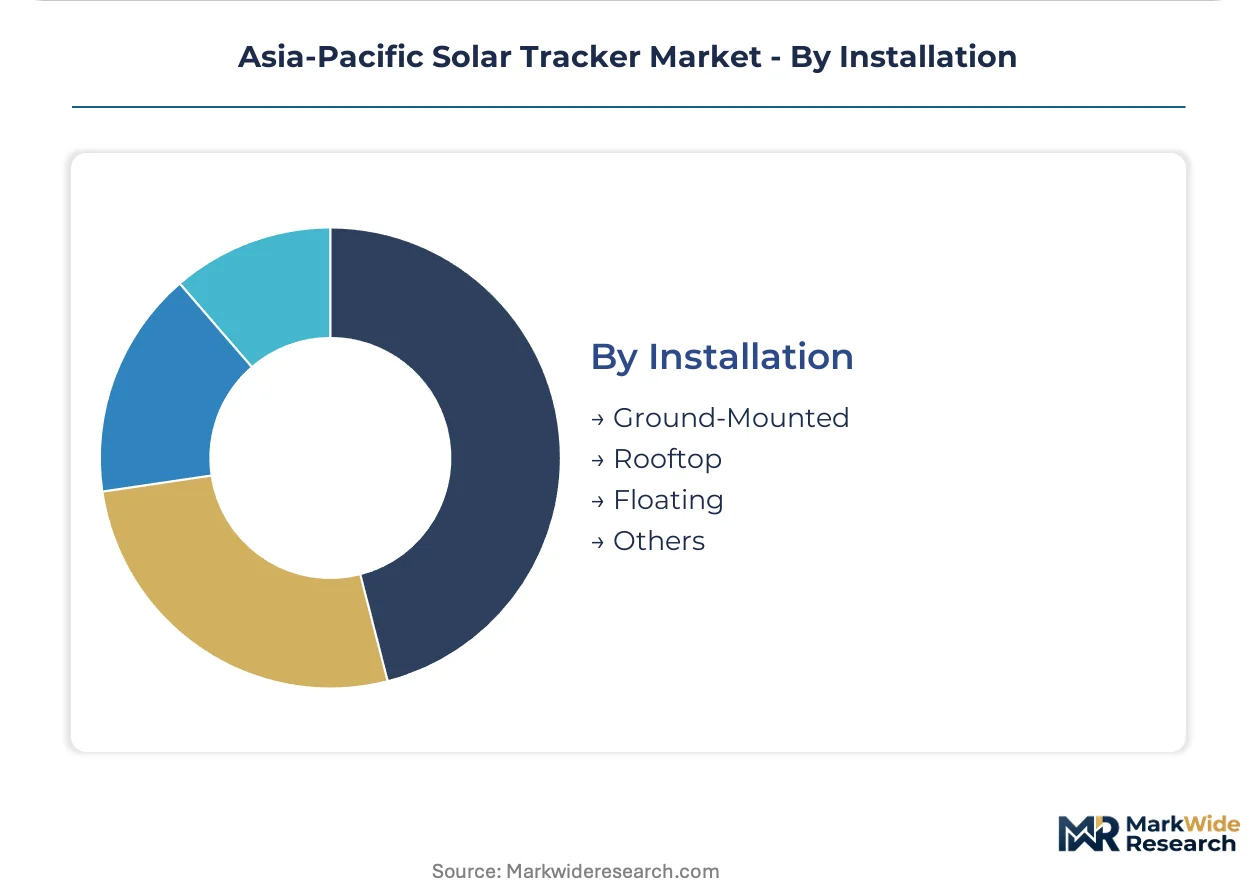
Installation:
Site topology dictates structural engineering requirements and balance-of-system cost allocation across deployment environments.
- Ground-Mounted:Terrestrial foundation systems for utility-scale and commercial installations on available land. Australia's Queensland and Western Australia are enabling gigawatt-scale single-axis deployment with superior LCOE performance on flat high-irradiance terrain.
- Floating:Pontoon or mooring-based systems for reservoir and coastal applications with land constraints or cooling synergies.
- Rooftop:Building-integrated or attached systems for commercial and industrial facilities with limited ground space.
- Others:Agrivoltaic elevated architectures and specialized mounting for agricultural co-use penetrating Japan's land-constrained prefectures.
Ground-Mounted holds the dominant share, while Floating is climbing the fastest through reservoir deployment programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for solar manufacturing and China's dual carbon policy are redirecting procurement toward domestic tracker production across the region. State-owned utilities in both countries now embed local content thresholds into gigawatt-scale tenders. Australia's Clean Energy Council certification requirements are similarly reshaping supplier qualification.
China
State-owned utility portfolios are accelerating tracker deployment under MEE dual carbon enforcement timelines. GB standards now govern steel galvanization carbon intensity disclosure for northwestern renewable base projects. Xinjiang and Inner Mongolia clusters are prioritizing suppliers with verified low-carbon torque tube supply chains.
India
Rajasthan and Gujarat states concentrate gigawatt-scale single-axis installations on flat arid terrain with superior irradiance. BIS mandates IEC 62817 certification and structural load testing for national solar mission tenders. Domestic manufacturing capacity is expanding in Mundra and Bhuj industrial corridors under PLI scheme incentives.
Australia
Queensland and Western Australia are enabling utility-scale deployment with high-irradiance flat terrain yielding superior LCOE performance. Clean Energy Council approved product lists gate inverter-tracker package eligibility. Integrated EPC-tracker procurement bundles are consolidating vendor relationships in the NEM grid zone.
Japan
Land-constrained prefectures are adopting elevated agrivoltaic tracker architectures that maintain agricultural activity underneath. METI feed-in tariff transitions are pressuring project economics toward yield-maximizing technologies. Kyushu and Hokkaido installations favor dual-axis systems where seasonal solar elevation variation is substantial.
Vietnam
Feed-in tariff transitions toward auction-based procurement are creating openings for tracker-integrated EPC offerings. Central Highlands provinces offer flat terrain suitable for single-axis deployment at scale. The national utility is revising technical standards to accommodate smart tracker control systems in upcoming renewable auctions.
Asia-Pacific Solar Tracker Market Vendor Landscape
Listed leaders compete with private specialists across certification and software integration capabilities. The supplier base concentrates around IEC 62817-validated platforms with three archetypes emerging: integrated solar manufacturers with captive tracker production, pure-play tracker engineering specialists, and EPC-origin fabricators with installation-optimized designs. Competitive moves center on backward integration into steel torque tube manufacturing and strategic bundling with inverter and O&M service packages.
Within the integrated manufacturer tier, Trina Solar exemplifies upstream control over control electronics and structural components. NexTracker Inc. and Array Technologies Inc. represent the pure-play engineering specialist archetype with distributed drive architectures. GameChange Solar anchors the installation-velocity focused segment with pre-assembled system approaches.
| Leading Market Players |
|---|
| Soltec Energias Renovables S.L. |
| PV Hardware Solutions S.L.U. |
| NexTracker Inc. |
| Antaisolar |
| SunPower Corporation |
| Array Technologies Inc. |
| Trina Solar |
| GameChange Solar |
| Arctech Solar Holding Co. |
| Others |
Supply Flow & Price Mechanics
IEC 62817 certification gates both supplier qualification and price differentiation across the Asia-Pacific solar tracker market, compressing margins for uncertified hardware while elevating software-integrated platforms to premium positioning. India's BIS mandates and Australia's Clean Energy Council approved product lists create parallel compliance cost structures that suppliers must absorb or pass through to utility-scale developers.
Pricing Analysis
Certification level creates the primary spread between commodity hardware and value-capturing software platforms across procurement categories. Three-tier pricing structure separates IEC 62817-validated smart trackers with predictive positioning algorithms from standard single-axis systems and uncertified fixed-tilt alternatives. Cost compression in standard hardware tiers is intensifying because Indian PLI scheme domestic content mandates are forcing margin absorption by suppliers without captive steel production. Utility-scale developers with 25-year power purchase agreements demonstrate lowest price sensitivity, while commercial behind-the-meter projects prioritize upfront capital minimization over yield optimization.
Supply Chain Analysis
China and India anchor structural component manufacturing, with Chinese GB-standard steel mills supplying torque tubes and Indian Mundra-Bhuj industrial corridors expanding domestic tracker assembly capacity. Control electronics and drive motors draw from East Asian component specialists concentrated in Taiwan and South Korea. Single-source vulnerability in precision motor sourcing creates supply chain risk given limited qualified suppliers for IEC 62817-validated drive systems. Distribution runs through integrated EPC-tracker procurement bundles that consolidate vendor relationships and compress standalone hardware margins while expanding software and O&M service attachment rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates white-space opportunities as machine-learning predictive positioning displaces mechanical hardware differentiation, enabling specialist software providers to capture margin pools outside traditional structural engineering. Demand-side procurement consolidation around single-point accountability for energy yield guarantees is fragmenting the supplier base across certification tiers and service integration depths.
For Market Incumbents: Secure backward integration into steel torque tube manufacturing to absorb GB-standard galvanization cost volatility and defend margin structures against emerging EPC-origin fabricators with installation-optimized designs. Lock in IEC 62817 certification renewal cycles ahead of India's BIS mandate expansion and Australia's Clean Energy Council approved product list revisions. Prioritize captive supply of control electronics over distributed drive motor sourcing to reduce single-source vulnerability exposure. For New Entrants and Emerging Players: Anchor in Vietnam's auction-based procurement transition where feed-in tariff restructuring creates openings for tracker-integrated EPC offerings without incumbent relationship lock-in. Target Japan's agrivoltaic elevated tracker architectures where land constraints and METI feed-in tariff pressure favor yield-maximizing technologies with agricultural co-use certification. Lead with software-defined predictive positioning capabilities rather than mechanical hardware differentiation to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play tracker engineering specialists lacking captive steel production or inverter integration capabilities. Long-term viability hinges on software and O&M service attachment rates rather than hardware shipment volumes across the 5-10 year projection horizon. Watch for carbon-border adjustment mechanism enforcement in Chinese state-owned utility tenders as the inflection indicator for low-carbon steel supply chain requalification investments.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62817 Certification Investment | BIS mandates and Australia's Clean Energy Council lists gate market access for uncertified suppliers. |
| Backward Integration into Steel Production | GB-standard galvanization cost volatility squeezes margin structures for non-captive suppliers. |
| Predictive Positioning Software Development | Machine-learning algorithms capture O&M cost reduction pools and command procurement premiums. |
| Integrated EPC-Tracker Procurement Bundles | Single-point accountability for energy yield guarantees consolidates vendor relationships in Australian NEM grid zone. |
| Low-Carbon Steel Supply Chain Documentation | China's MEE dual carbon enforcement prioritizes verified supply chains in northwestern renewable base tenders. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, incorporating utility planning officers at state-owned portfolios, IPP project developers in Rajasthan and Gujarat, EPC contractors with Clean Energy Council accreditation, and tracker engineering specialists with IEC 62817 validation experience. Secondary validation drew from IEA renewable deployment databases, India's Ministry of New and Renewable Energy tender documentation, China's MEE dual carbon policy circulars, and Australia's Clean Energy Council approved product registers. Bottom-up project pipeline aggregation triangulated against top-down national renewable capacity targets to establish market sizing boundaries.
Across the analysis window, the forecasting framework modeled product type segmentation alongside control methodology differentiation, end-user procurement scale tiers, and installation topology constraints. CAGRs were derived from project commissioning timelines, interconnection queue progression, and domestic manufacturing capacity buildout under India's PLI scheme. Forecast inputs incorporated steel price volatility indices, grid parity achievement trajectories, and evolving domestic content threshold schedules across national procurement programs.
Material uncertainties — steel price volatility, grid interconnection delays, and regulatory revision to domestic content thresholds — sit outside the modeled envelope and could accelerate or compress deployment timelines. Forecasts reflect assumptions about certification timeline standardization and carbon-border adjustment mechanism implementation pacing. Recalibration cycles align with material shifts in national renewable auction schedules and MEE dual carbon enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
High-Efficiency Solar Modules Market