
 Global Wood Fuel Pellets Market | 2026-2036
Global Wood Fuel Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Fuel Pellets Market Outlook
ENplus A1 certification is reorganizing procurement standards across residential and industrial buyers. Enviva leverages its Atlantic Coast terminal network to sustain export volumes into European power stations. Drax Group anchors its Yorkshire power complex with dedicated biomass supply chains. Graanul Invest dominates Baltic Sea production capacity, controlling feedstock access across Estonia and Latvia.
Wood fuel pellets are densified biomass cylinders, typically 6-8 millimeters in diameter and 10-40 millimeters in length, manufactured through mechanical pressing of dried sawdust and wood residues at pressures exceeding 100 bar. Their primary purpose is to deliver standardized, high-energy-density fuel for automated combustion systems in power generation and heating. Premium Pellets command the strongest residential margins due to stringent ash-content thresholds below 0.7 percent. Industrial Pellets represent the fastest-expanding application segment as coal-replacement mandates intensify across European utilities. Heating Pellets remain the most mature category, with pricing power constrained by seasonal demand fluctuations.
The EU Green Deal and its Renewable Energy Directive II shape pellet demand by mandating sustainability certification for biomass feedstocks entering member-state energy systems. EPA regulations in the United States govern residential stove emissions, indirectly influencing pellet quality standards for export-bound production. Japan's METI feed-in tariff program for biomass power creates a parallel demand corridor for industrial-grade supply. Stakeholders must monitor certification fragmentation between ENplus, PFI, and emerging national schemes as compliance costs diverge across destination markets.
Market Dynamics
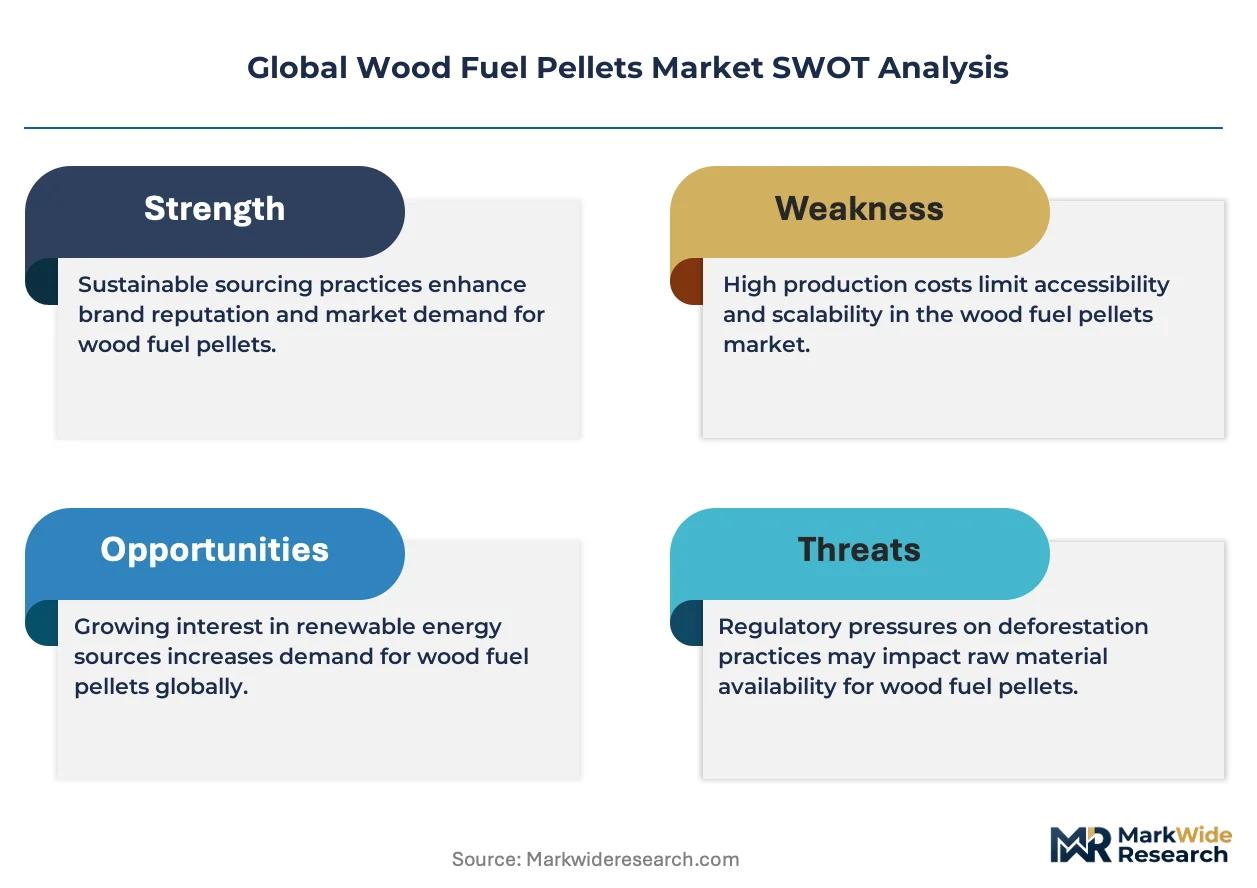
European utilities are accelerating coal-to-biomass conversions under binding EU Green Deal emissions targets, concentrating procurement power among a handful of certified industrial pellet suppliers while residential buyers face fragmented certification schemes.
Growth Catalysts
- EU Green Deal mandates:Coal-replacement deadlines in Germany, Poland, and the Netherlands are pulling industrial-grade pellet volumes into dedicated power generation contracts.
- Japan METI feed-in tariffs:Biomass power subsidies create a parallel demand corridor for industrial pellets, diversifying offtake beyond European utilities.
- District heating densification:Scandinavian and Baltic district heating networks are expanding feedstock intake, locking in long-term supply agreements with pellet producers.
Market Restraints
- Feedstock cost volatility:Sawdust and forest residue prices fluctuate with construction cycles and lumber demand, compressing producer margins without pass-through mechanisms.
- Baltic supply concentration:Estonian and Latvian producers control disproportionate export capacity, creating single-point-of-failure risk for European utility procurement.
- ENplus-PFI certification divergence:Competing quality standards between European and North American schemes raise compliance costs for cross-border suppliers.
Strategic Opportunities
- Underpenetrated US residential heating:Northeastern states with oil-dependent heating infrastructure present conversion potential as EPA stove-emission standards tighten.
- South Korean biomass power auctions:New renewable portfolio standards are opening procurement channels for industrial pellet suppliers outside traditional European-Japanese corridors.
- Torrefied pellet co-firing:Higher-energy-density torrefaction technology enables deeper coal substitution ratios in existing plant infrastructure.
Industry Challenges
- Certification timeline compression:EU Renewable Energy Directive II sustainability verification requirements demand traceability systems that smaller producers cannot deploy rapidly.
- Logistics capex intensity:Dedicated pellet export terminals require capital commitments that only integrated producers with captive port access can justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Fuel Pellets Market |
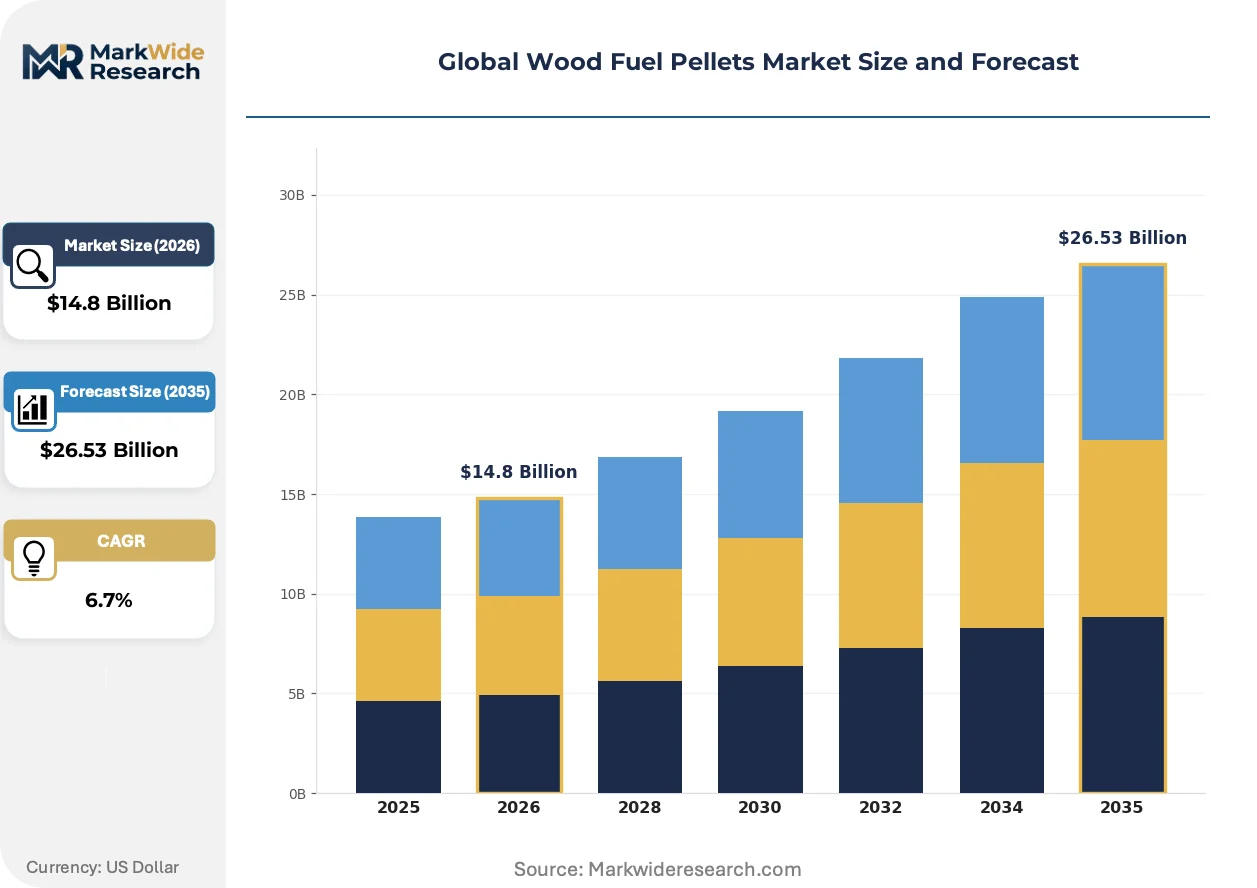
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Pellets, Industrial Pellets, Heating Pellets, Animal Bedding Pellets Application: Residential Heating, Industrial Power Generation, Commercial Heating, Animal Bedding Production Process: Direct Thermal Processing, Indirect Thermal Processing, Mechanical Pressing, Cold Pressing Distribution Channel: Direct Sales, Retailers, Wholesalers, Online Platforms |
| Companies Covered | Enviva, Drax Group, Pinnacle Renewable Energy, Graanul Invest, The Westervelt Company, Lignetics, Fram Fuels, Highland Pellets, German Pellets GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Fuel Pellets Market Strategic Shifts
Torrefaction and advanced densification processes are reshaping fuel specifications, while regulatory fragmentation around sustainability certification is forcing procurement systems to multiply compliance layers.
Torrefaction technology applies mild pyrolysis to raw biomass, stripping volatiles and raising energy density above standard pellets. German and Dutch utilities are piloting torrefied pellet blends at 20-30 percent substitution ratios in converted coal units. This thermal upgrading is decomposing the traditional premium-industrial pellet quality boundary, enabling fuel interchangeability across combustion systems.
The EU Renewable Energy Directive II sustainability criteria now mandate chain-of-custody documentation for biomass entering member-state energy systems. Industrial buyers in Germany and Italy are rejecting uncertified supply, forcing Baltic producers to upgrade traceability infrastructure. Residential markets feel secondary effects as certification costs propagate through ENplus-labeled distribution channels.
Long-term offtake contracting is displacing spot-market purchasing among European power utilities. Drax, RWE, and Orsted are locking in 5-10 year supply agreements with dedicated pellet producers, compressing merchant market liquidity. This procurement consolidation is most visible in the UK and Netherlands, where coal-phaseout deadlines have eliminated fuel-switching flexibility.
Global Wood Fuel Pellets Market Segmentation
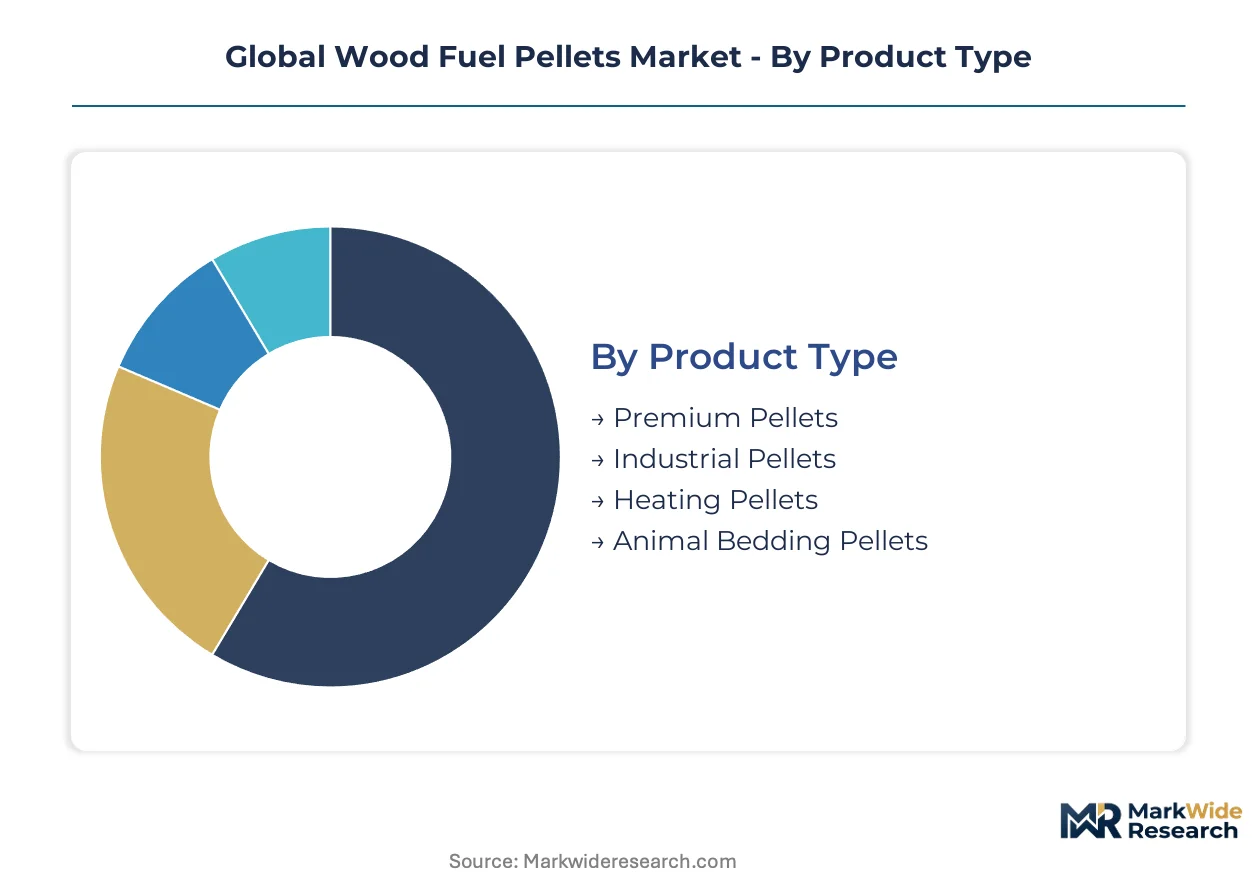
Pellet classification determines compliance pathways, margin structures, and procurement relationships across residential, industrial, and agricultural end-uses. Distinct certification regimes and combustion specifications fragment supply chains into non-interchangeable product tiers.
Product Type:
Premium Pellets serve domestic heating markets in Germany and Austria, while Industrial Pellets flow to converted coal stations across the Netherlands and Denmark. Animal Bedding Pellets remain almost entirely domestic-sourced due to low value-to-weight ratios.
- Premium Pellets:Manufactured from debarked softwood sawdust with ash content below 0.7 percent and moisture below 10 percent. ENplus A1 certification commands price premiums in German and Austrian residential markets where automated pellet boilers require low-slag fuel. Stringent certification limits supplier pools.
- Industrial Pellets:Higher ash tolerance (1-3 percent) and larger diameter variants (8-10 millimeters) optimized for utility-scale pulverized fuel systems. Demand concentrates at Drax, RWE, and Orsted facilities in the UK and Netherlands under long-term offtake contracts tied to coal-phaseout deadlines.
- Heating Pellets:Mid-grade residential fuel with 0.7-1.5 percent ash content, serving manual-feed stoves and small-scale district heating in Baltic states and Poland.
- Animal Bedding Pellets:Absorbent softwood cylinders with minimal chemical treatment, produced and consumed within national markets due to transport cost sensitivity.
Heating Pellets hold the largest share; momentum sits with Industrial Pellets.
Application:
Volume concentration varies sharply by customer scale — utility procurement aggregates into decade-long contracts while residential purchasing fragments across thousands of retail points.
- Residential Heating:Single-family and multi-unit buildings in Germany, Austria, and Italy drive seasonal demand spikes. Boiler replacement subsidies in Italy and France accelerate conversion from oil heating. Cold winters in Nordic countries sustain baseline consumption.
- Industrial Power Generation:Coal-to-biomass conversions at Drax, Lynemouth, and Maasvlakte facilities anchor demand. Dedicated handling infrastructure and 5-10 year supply agreements lock in procurement relationships.
- Commercial Heating:Hotels, schools, and municipal buildings in Scandinavia and Baltics deploy mid-scale automated systems. District heating networks in Denmark and Sweden integrate pellet-fired peak-load boilers.
- Animal Bedding:Equine and poultry operations in UK, Germany, and France source absorbent pellets for stable and coop hygiene. Demand tracks agricultural commodity cycles rather than energy policy.
Industrial Power Generation captures the steepest expansion trajectory; Residential Heating maintains volume dominance.
Production Process:
Technology choice reflects feedstock moisture, scale economics, and end-use certification requirements rather than geographic patterning.
- Direct Thermal Processing:Hot gas contact drying of raw biomass in rotary drum systems. Dominates large-scale Baltic production where wet sawmill residues require rapid moisture reduction. Energy integration with CHP plants improves thermal efficiency.
- Indirect Thermal Processing:Steam or thermal oil heat exchange prevents combustion gas contamination of feedstock. Preferred for Premium Pellet production where flavor-neutral output matters for residential certification.
- Mechanical Pressing:High-pressure densification (100-150 bar) using ring-die or flat-die presses. Standard across all grades; die specification and compression ratio vary by pellet diameter requirements.
- Cold Pressing:Lower-pressure extrusion of pre-dried feedstocks with lignin binders. Niche application for agricultural residue pellets with non-wood composition.
Mechanical Pressing underpins all volume; Direct Thermal Processing is climbing fastest at utility scale.
Distribution Channel:
Channel selection tracks customer concentration — bulk utility procurement bypasses intermediaries while fragmented residential demand requires retail density.
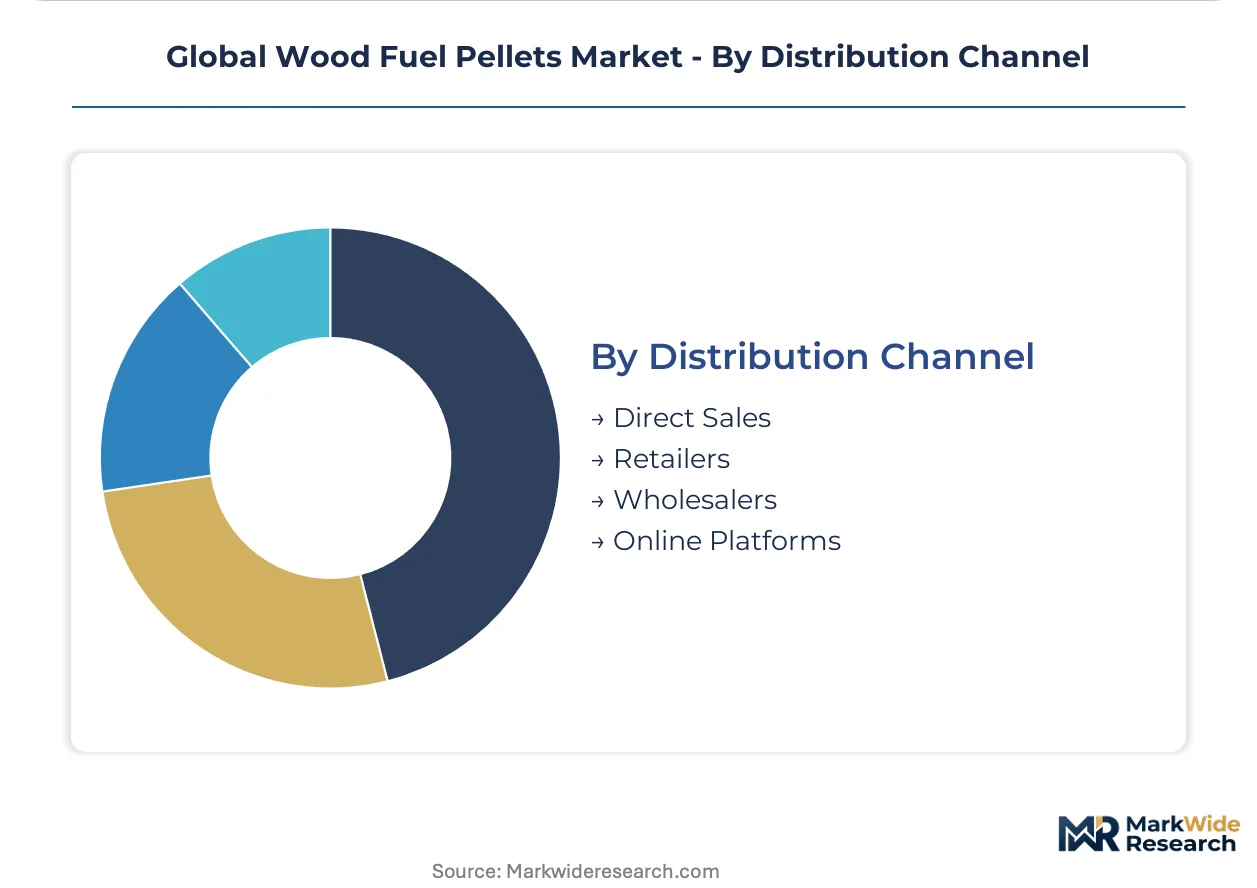
- Direct Sales:Producer-to-utility contracts dominate Industrial Pellet flow. Enviva, Graanul Invest, and Drax supply chain subsidiaries deliver FOB terminal or CIF power station volumes without intermediary markup.
- Retailers:Agricultural supply stores, building merchants, and specialized pellet dealers serve bagged Premium Pellet demand. ENplus-certified retail networks in Germany and Austria enforce quality traceability to end-user.
- Wholesalers:Regional distributors aggregate truckload volumes for commercial heating and small-scale district heating operators. Inventory holding buffers seasonal demand swings.
- Online Platforms:Emerging channel for residential price comparison and subscription delivery in UK and France. Limited penetration due to bulk logistics constraints.
Direct Sales commands industrial volume; Retailers anchor residential monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baltic producers control disproportionate export capacity to European utilities, while North American suppliers leverage Atlantic terminal networks for transatlantic flows. Japan and South Korea are opening parallel demand corridors through feed-in tariff programs. Each geography presents distinct certification requirements and procurement consolidation patterns.
Germany
District heating networks in Bavaria and North Rhine-Westphalia source industrial-grade pellets under long-term supply agreements tied to coal-phaseout deadlines. The EU Green Deal mandates sustainability certification through the Renewable Energy Directive II, forcing traceability upgrades across supplier bases. Hamburg and Berlin clusters concentrate procurement power among ENplus-certified distributors serving residential boiler markets.
United Kingdom
Drax Group's Yorkshire power complex anchors national demand through dedicated biomass supply chains with 5-10 year offtake contracts. The UK Renewables Obligation and Contracts for Difference schemes subsidize coal-to-biomass conversions at Lynemouth and other converted stations. Teesside and Humber ports host specialized pellet handling infrastructure serving utility procurement.
Japan
Biomass power auctions under METI feed-in tariffs create premium pricing corridors for industrial-grade supply from North American and Southeast Asian exporters. The country's feed-in tariff program guarantees fixed prices for 20-year contract periods, attracting dedicated supply chain investments. Port clusters in Kansai and Kyushu regions concentrate import handling capacity for utility offtake.
United States
Southeastern producers leverage Atlantic Coast terminal networks to sustain export volumes into European power stations, while Northeastern states present residential heating conversion potential from oil-dependent infrastructure. EPA stove-emission standards tighten quality requirements for export-bound production. Virginia and Georgia clusters concentrate production capacity with captive port access.
Netherlands
Maasvlakte facilities anchor industrial demand through converted coal units serving Rotterdam port hinterland. The Dutch coal-phaseout deadline of 2030 compresses procurement timelines into dedicated long-term contracts with certified Baltic and North American suppliers. Eemshaven and Amsterdam clusters integrate pellet handling with existing coal terminal infrastructure.
Global Wood Fuel Pellets Market Competitive Environment
Concentration sits with integrated producers possessing captive terminal access and certified supply chains. The market structures around three tiers: Atlantic-basin exporters with dedicated port infrastructure, Baltic Sea producers controlling feedstock-rich catchment areas, and regional specialists serving fragmented residential heating demand. Competitive moves center on backward integration into forest residue sourcing and multi-year utility offtake contracting that locks in volume visibility.
Among integrated Atlantic exporters, Enviva and Drax Group occupy positions exemplifying terminal-network scale advantages. Enviva leverages its Southeastern US production base with dedicated export capacity, while Drax Group anchors demand through its Yorkshire power station complex. Graanul Invest represents the Baltic production archetype with Estonian and Latvian feedstock control. These three names illustrate how geography and infrastructure access determine competitive positioning.
| Leading Market Players |
|---|
| Enviva |
| Drax Group |
| Pinnacle Renewable Energy |
| Graanul Invest |
| The Westervelt Company |
| Lignetics |
| Fram Fuels |
| Highland Pellets |
| German Pellets GmbH |
| Others |
Value Chain & Pricing Dynamics
Coal-to-biomass substitution at European utilities is redrawing supply geography while compressing pricing economics across the Atlantic-Baltic corridor. This feedstock transition concentrates procurement power among certified producers with captive terminal access, forcing price differentiation by certification tier rather than commodity grade.
Pricing Analysis
The EU Renewable Energy Directive II dictates the pricing tier structure by mandating chain-of-custody documentation that separates certified from uncertified supply. Three-tier pricing structure across ENplus A1, industrial utility-grade, and unlabeled economy levels reflects ash-content thresholds and traceability investments. Cost compression in premium residential tiers is intensifying because Baltic producers are absorbing certification upgrades without full pass-through to German and Austrian boiler markets. Small-scale residential buyers exhibit highest price sensitivity, while Drax and RWE anchor long-term offtake contracts with cost-plus mechanisms that insulate utility procurement.
Supply Chain Analysis
Inventory cycles stretch 45-60 days from Baltic production to Rotterdam discharge, compressing working capital for non-integrated traders. Supply concentrates in Estonia, Latvia, and the Southeastern United States, with each node feeding distinct certification corridors. Raw material draws from sawmill residues, forest thinnings, and construction wood waste, all tethered to lumber demand cycles. Single-source vulnerability runs through Estonian export terminals that handle disproportionate European utility volume. Distribution runs through dedicated pellet export terminals at Riga, Pärnu, and Virginia Beach, bypassing general bulk commodity infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion as coal-phaseout deadlines accelerate utility procurement beyond current certified supply capacity. Japanese and South Korean feed-in tariff programs extend demand visibility beyond European anchors.
For Market Incumbents: Fortify backward integration into forest residue sourcing across Estonia and Latvia to lock in feedstock access before competitor terminal investments materialize. Prioritize ENplus A1 certification maintenance as smaller Baltic producers face compliance timeline compression that will disqualify uncertified supply from German district heating networks. Expand torrefaction pilot capacity to capture premium positioning for higher-density fuel blends. For New Entrants and Emerging Players: ENplus certification fast-track through accredited Baltic laboratories offers entry into fragmented Polish and Italian residential markets where distributor networks lack certified supply depth. Target underpenetrated US Northeastern states with oil-to-pellet conversion programs as EPA stove-emission standards tighten. Pursue toll-processing arrangements with existing Baltic producers to bypass terminal infrastructure capex requirements. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated producers with captive port access and long-term utility offtake visibility. Five-to-ten year viability rests on sustainability certification durability rather than commodity fuel pricing. Acquisition screening should prioritize Estonian and Latvian producers with unencumbered forest lease access. The signal to watch is South Korean biomass auction participation rates as a proxy for demand corridor diversification beyond European and Japanese anchors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Residue Sourcing | Captive feedstock supply insulates Graanul Invest and Enviva from sawmill residue price volatility. |
| Torrefaction Technology Scale-Up | German utilities at Maasvlakte pilot higher-density blends that enable deeper coal substitution ratios. |
| Long-Term Utility Offtake Contracting | Drax and RWE lock in 5-10 year supply agreements that compress merchant market liquidity. |
| ENplus Certification Infrastructure Investment | Traceability systems satisfy EU Renewable Energy Directive II requirements for German residential distribution. |
| Atlantic Coast Terminal Network Expansion | Virginia and Georgia export capacity sustains transatlantic flows into Rotterdam and UK power stations. |
Study Parameters
Cross-validation between utility procurement officer interviews and customs trade data anchors the qualitative findings in observable volume flows. Primary discussions with biomass supply specialists, district heating network planners, ENplus certification auditors, and port terminal operators combined with secondary validation against EIA wood pellet export statistics, EUROSTAT energy balances, and IEA bioenergy reports. Bottom-up capacity aggregation across Baltic and North American production facilities triangulates against top-down utility demand modeling.
Sensitivity analysis around coal-phaseout deadline timing and feed-in tariff renewal probabilities frames the projection uncertainty. Segmentation dimensions span product grade tier, end-use application, production process technology, and regional regulatory cluster across the modeling period. CAGRs derive from installed base conversion rates and new capacity absorption curves, incorporating torrefaction adoption assumptions and certification compliance cost trajectories as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or Japanese METI tariff continuity would require recalibration. Forecasts reflect documented assumptions about utility conversion timelines and sustainability verification scalability. Feedstock cost volatility, Baltic supply concentration, and certification scheme fragmentation represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market