
 Soil Treatment Market | 2026-2036
Soil Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Treatment Market Intelligence
Premium-grade biological soil amendments is bifurcating the competitive landscape as growers separate performance-validated products from commodity inputs. Syngenta Group leverages its integrated seed-and-soil platform to bundle biologicals with germplasm. BASF SE anchors its position through microbial strain libraries developed for specific soil microbiome deficits. FMC Corporation differentiates via precision application technologies that tie soil treatment timing to crop growth stages.
Soil treatment encompasses the mechanical, chemical, and biological modification of soil properties to optimize plant growth, including pH correction through lime or sulfur application, organic matter enhancement via compost or biochar incorporation, and biological inoculation with targeted microbial consortia. Organic Amendments command the largest value pool as carbon-sequestering practices attract premium crop contracts and government incentive programs. Biopesticides represent the fastest-expanding product category, driven by residue-limit protocols in export-oriented agricultural zones. Agricultural Use dominates application volumes, though Lawn Care generates higher per-acre margins through specialized retail channel positioning.
The EPA regulates soil treatment inputs under FIFRA pesticide and device provisions, while the EU REACH framework governs chemical soil conditioner registration across member states. India's FSSAI and BIS standards increasingly govern heavy metal limits in organic amendments applied to food crops. Stakeholders must monitor evolving residue thresholds and carbon credit qualification criteria as these dual mechanisms reshape product development priorities and market access conditions.
Market Dynamics
Biological amendment validation protocols are bifurcating procurement criteria as growers separate performance-verified microbial consortia from uncharacterized commodity inputs. This structural force is compressing margins for undifferentiated suppliers while rewarding strain-library owners with recurring formulation contracts.
Growth Catalysts
- EU Fertilizing Products Regulation:Accelerated registration pathways for soil improvers are compressing time-to-market for microbial inoculant developers, stimulating R&D investment in standardized efficacy dossiers.
- Brazilian Cerrado soybean expansion:Acidity correction requirements across Mato Grosso and Goiás are pulling lime and sulfur application volumes upward as double-cropping intensifies.
- Carbon credit qualification:Biochar and compost amendments are securing premium crop contracts through verified soil carbon sequestration protocols in voluntary offset markets.
Market Restraints
- Phosphate rock supply concentration:Moroccan and Chinese state-controlled producers dominate elemental phosphorus feedstock, exposing formulated amendment manufacturers to price volatility and export quota disruptions.
- Microbial shelf-life limitations:Viability decay in liquid biological formulations constrains distribution radius and cold-chain economics, favoring regional blenders over national suppliers.
- Heavy metal accumulation thresholds:India's FSSAI and BIS standards for cadmium and arsenic in organic amendments are disqualifying municipal compost streams from food-crop applications.
Strategic Opportunities
- California specialty crop biological programs:Almond and grape producers are expanding microbial inoculation budgets as residue-limit protocols tighten for export-oriented harvests.
- Precision application convergence:Integration of soil sensor data with variable-rate equipment is creating subscription revenue pools for treatment-timing optimization services.
- Retail lawn care channel premiumization:Specialized packaging and seasonal merchandising in garden center networks capture per-acre margins exceeding agricultural benchmarks by threefold.
Industry Challenges
- Microbiome analytical talent scarcity:Commercial laboratories lack sufficient bioinformaticians to process strain identification and functional gene assays for product registration dossiers.
- Legacy equipment incompatibility:Biological inoculant tank-mixing with conventional chemistries requires dedicated plumbing and cleanout protocols that retrofit poorly into existing applicator fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Treatment Market |
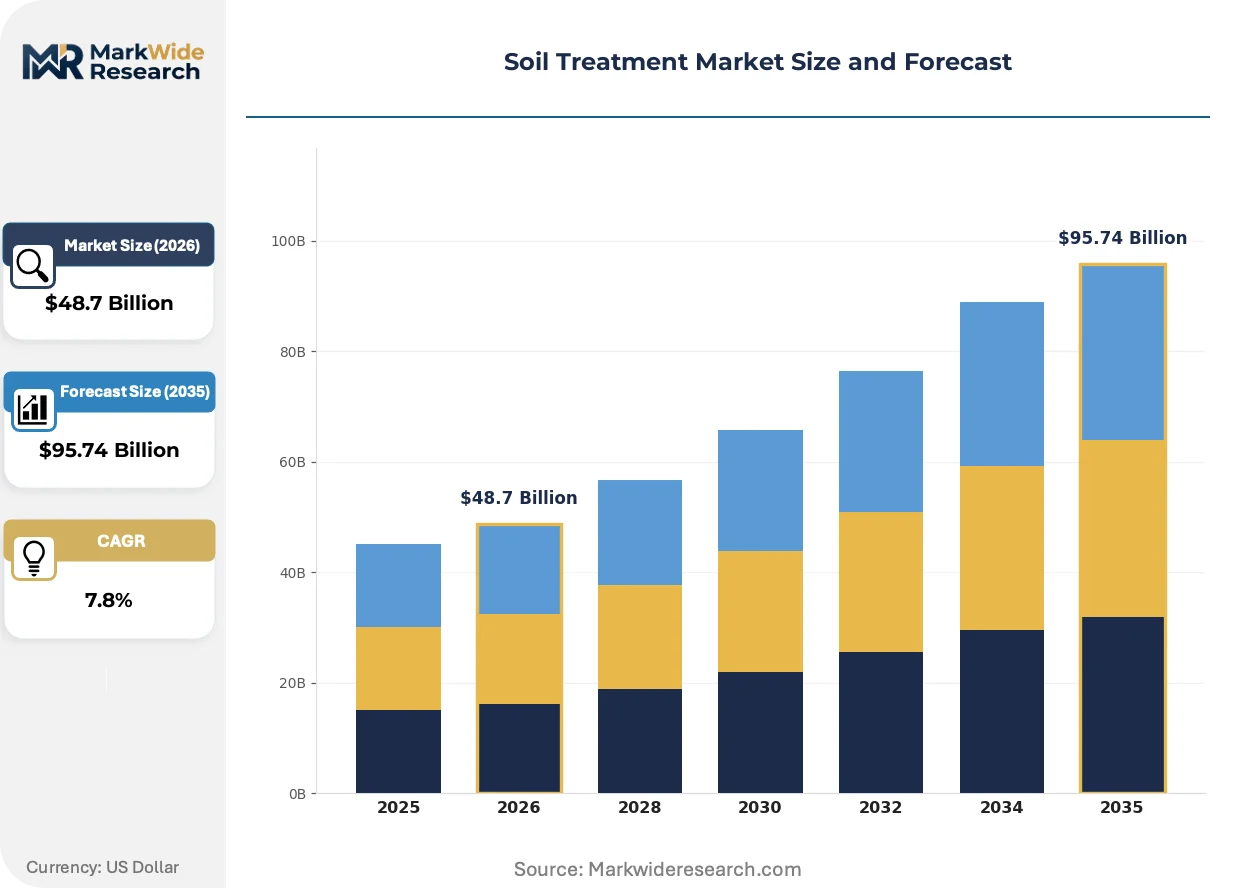
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $95.74 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Amendments, Synthetic Inputs, Biopesticides, Soil Conditioners Application: Agricultural Use, Lawn Care, Landscaping, Erosion Control End User: Farmers, Gardeners, Landscapers, Government Agencies Distribution Channel: Online Retail, Specialty Stores, Wholesale Dealers, Agricultural Cooperatives |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, FMC Corporation, ADAMA Agricultural Solutions Ltd, AMVAC Chemical Corporation, Corteva Agriscience, Arkema, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Treatment Market Strategic Shifts & Innovations
Next-generation soil treatment is converging around biological specificity, regulatory data transparency, and outcome-linked procurement. These forces are compressing commodity input margins while expanding service-integrated revenue pools.
RNA-interference biopesticides targeting soil-borne nematodes and fungal pathogens are fragmenting the nematicide category as seed-treatment formulations displace fumigant applications. Row-crop operators in the US Corn Belt are piloting these platforms at scale. The technology is fragmenting established chemistries into niche, trait-specific solutions with shorter development cycles and localized registration strategies.
REACH framework amendments governing chemical soil conditioner persistence and ecotoxicity are extending data requirements for legacy active ingredients. Formulators face retrospective dossier supplementation or market withdrawal decisions. The regulation is compressing supplier counts in Western Europe while accelerating biological substitution investments.
Outcome-based amendment contracts are displacing tonnage-based purchasing as large-scale growers demand yield-verified performance guarantees. Agronomy service providers in Brazil's Mato Grosso are bundling soil treatment with remote sensing validation. This model concentrates procurement authority with integrated platform operators and marginalizes independent commodity distributors.
Soil Treatment Market Segmentation
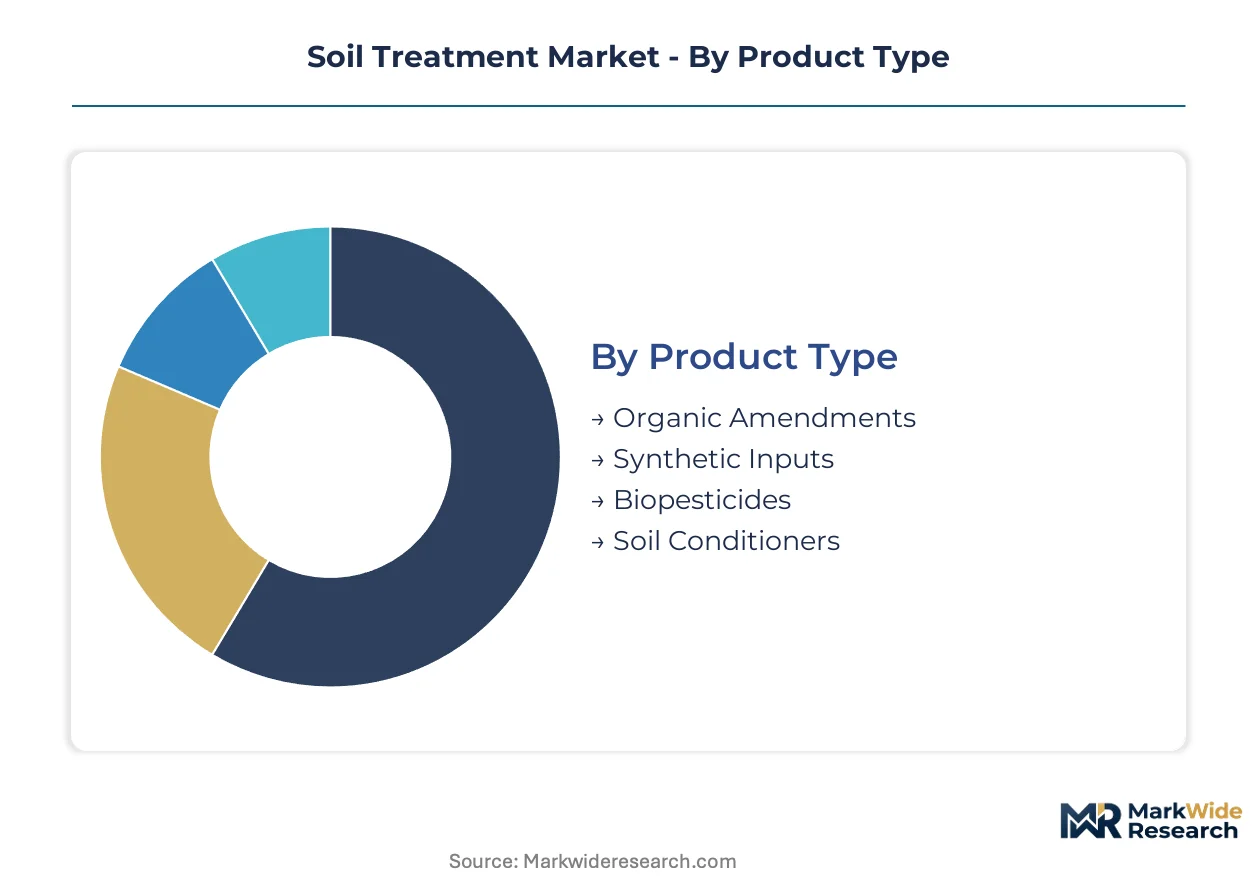
Soil treatment procurement splits sharply between carbon-credit-qualified biological programs and commodity chemical applications. Regulatory frameworks in the EU, India, and Brazil are accelerating this bifurcation by tightening residue thresholds and registration requirements.
Product Type:
EU REACH amendments and India's FSSAI heavy metal standards are forcing reformulation decisions across all four product classes, with biological inputs gaining accelerated pathways while legacy chemistries face retrospective dossier burdens.
- Organic Amendments:Compost, biochar, and manure-based materials sequester soil carbon while improving water retention. California almond growers and Brazilian soybean operators are expanding procurement of verified carbon-credit-qualified amendments to secure premium export contracts and offset program revenues.
- Biopesticides:RNA-interference formulations and microbial inoculants target soil-borne nematodes and fungal pathogens with residue profiles compatible with EU MRL protocols and US EPA tolerances. US Corn Belt operators are piloting seed-treatment platforms at commercial scale, displacing fumigant applications.
- Synthetic Inputs:Lime, sulfur, and elemental phosphorus formulations dominate acidity correction in Brazil's Cerrado expansion zones.
- Soil Conditioners:Polymer-based water retention and aggregation agents serve arid-zone horticulture in California and the Middle East.
Established volume favors synthetic inputs; emerging adoption favors biopesticides.
Application:
Margin structures diverge threefold between agricultural tonnage contracts and lawn care retail premiums, reshaping channel investment priorities for formulated product suppliers.
- Agricultural Use:Row-crop and specialty crop operators in Brazil, California, and the US Midwest drive bulk amendment volumes through cooperative procurement networks. Double-cropping intensification in Mato Grosso and Goiás pulls lime and sulfur application rates upward.
- Lawn Care:Seasonal merchandising through garden center networks captures per-acre margins exceeding agricultural benchmarks substantially. Packaging specialization and consumer branding investments concentrate in US and European retail channels.
- Landscaping:Commercial property maintenance contracts in urban centers specify organic amendment quotas for LEED certification compliance.
- Erosion Control:Infrastructure-adjacent revegetation projects in China and India specify polymer-stabilized topsoil systems.
Volume concentration remains with agricultural use; margin expansion concentrates in lawn care.
End User:
Procurement authority is consolidating around integrated platform operators while independent commodity distributors face marginalization from outcome-based contract structures.
- Farmers:Large-scale growers in Brazil's Mato Grosso are displacing tonnage-based purchasing with yield-verified performance guarantees bundled with remote sensing validation. Cooperative membership determines pricing tier and technical service access.
- Gardeners:Residential consumers in US and European markets respond to seasonal promotional cycles and organic certification labeling.
- Landscapers:Commercial contractors specify amendment blends for municipal and corporate sustainability mandates.
- Government Agencies:Public works departments in China and India administer erosion control and soil rehabilitation programs with BIS and GB standard compliance requirements.
Contract value aggregates with farmers; transaction frequency concentrates with gardeners.
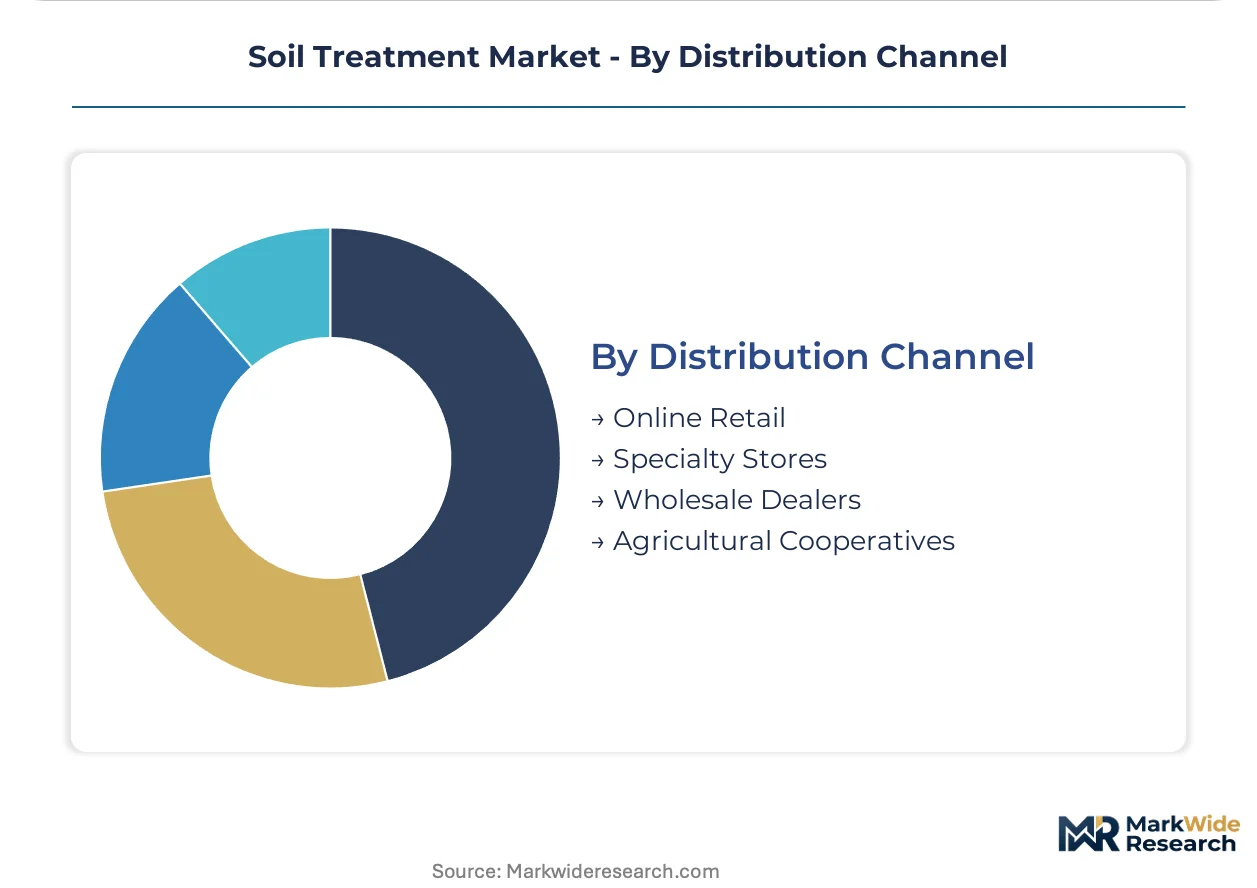
Distribution Channel:
Cold-chain economics and microbial shelf-life limitations constrain biological formulation distribution radius, favoring regional blenders over national suppliers in liquid inoculant categories.
- Agricultural Cooperatives:Brazil's Mato Grosso and US Corn Belt cooperatives aggregate farmer demand for bulk lime, sulfur, and biological inoculants, negotiating formulation contracts with strain-library owners.
- Wholesale Dealers:Independent distributors serve mid-scale operators with generic amendment portfolios facing margin compression from performance-validated product procurement criteria.
- Specialty Stores:Garden center networks in California, Germany, and Japan merchandise premium biological amendments with technical consultation services.
- Online Retail:Direct-to-consumer channels capture residential lawn care and small-scale gardener demand with subscription replenishment models.
Biological supply reliability favors cooperatives; convenience purchasing favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented agricultural zones drive amendment procurement patterns, with residue-limit protocols in destination markets shaping domestic formulation requirements. Import dependency for elemental phosphorus feedstock concentrates pricing power among state-controlled producers in Morocco and China.
United States
California almond and grape producers expand biological inoculation budgets to meet EU MRL protocols for export harvests. The EPA regulates soil treatment inputs under FIFRA pesticide and device provisions. The Central Valley cluster anchors specialty crop biological program adoption.
Brazil
Soybean growers in Mato Grosso and Goiás confront acidity correction needs across double-cropped Cerrado expansion zones. ANVISA governs agrochemical registration alongside Ministry of Agriculture MAPA standards. The Sorriso-Sinop corridor concentrates lime and sulfur application volumes.
Germany
REACH framework amendments extend data requirements for legacy soil conditioner active ingredients, compressing supplier counts. ECHA governs chemical persistence and ecotoxicity dossiers. The Rhineland industrial corridor hosts biological substitution R&D investments.
China
GB standards and MIIT regulations govern polymer-based soil conditioner manufacturing for domestic horticulture and Middle East export. NMPA oversight extends to microbial inoculant safety assessments. Shandong Peninsula clusters concentrate water retention agent production.
India
FSSAI and BIS heavy metal thresholds for cadmium and arsenic disqualify municipal compost streams from food-crop applications. DGFT import policies shape elemental phosphorus access for formulated amendments. Punjab and Haryana agricultural belts drive bulk organic amendment demand.
Soil Treatment Market Key Industry Players
Listed leaders compete with private specialists across biological strain ownership and precision application technology. The vendor base concentrates around integrated seed-and-soil platforms, microbial library owners, and regional formulation blenders. Three archetypes dominate: germplasm-integrated biological bundlers, strain-library-based microbial developers, and precision equipment-linked service providers. Competitive moves center on M&A for microbial IP and strategic partnerships for sensor-data integration.
Within the integrated platform tier, Syngenta Group and Bayer AG exemplify seed-and-soil bundling strategies. BASF SE anchors the microbial specialization vector through strain library investments. FMC Corporation occupies the precision application convergence position, linking treatment timing to crop growth stages.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd |
| AMVAC Chemical Corporation |
| Corteva Agriscience |
| Arkema |
| The Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
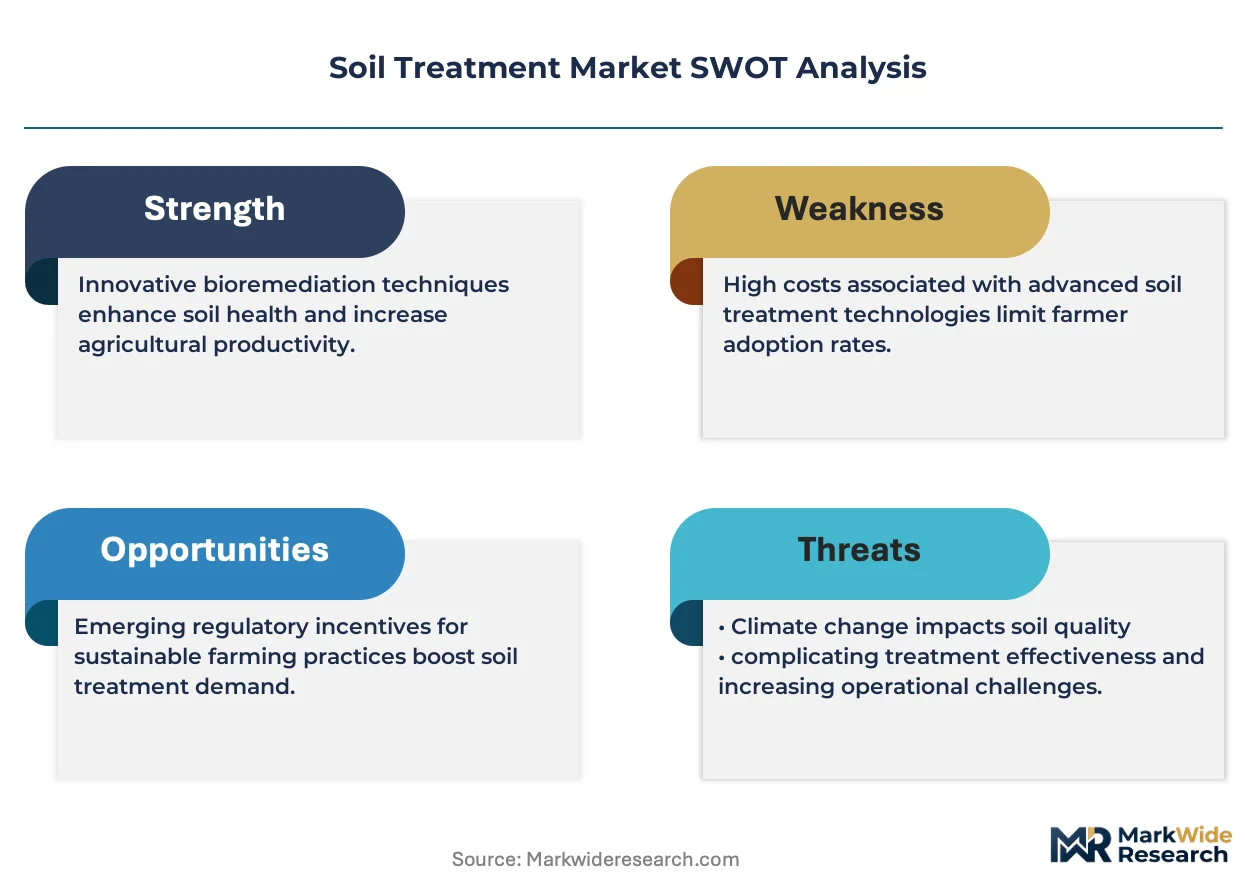
EU REACH amendments governing chemical soil conditioner persistence and ecotoxicity simultaneously gate supply qualification and stratify price tiers, as legacy formulators face retrospective dossier supplementation costs that biological developers bypass through accelerated registration pathways.
Pricing Analysis
Large-scale growers in Brazil's Mato Grosso anchor pricing structures through outcome-based amendment contracts that displace tonnage-based purchasing. Three-tier pricing structure across performance-validated biologicals, standard synthetic inputs, and commodity lime-sulfur applications separates strain-library owners from undifferentiated suppliers. Cost compression in commodity chemical tiers is intensifying as Moroccan and Chinese state-controlled phosphate rock producers exercise pricing power. Cooperative procurement networks demonstrate highest price sensitivity, while specialty crop operators in California accept premiums for carbon-credit-qualified amendments.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underwrites elemental phosphorus feedstock security concerns for formulated amendment manufacturers. Supply concentrates in Morocco, China, and Russia for phosphate rock, while microbial strain libraries concentrate in Germany, Switzerland, and the Netherlands. Raw material dependencies span phosphate rock, lignocellulosic biomass for biochar, and cryopreserved microbial cultures. Single-source vulnerability in Moroccan state-controlled producers exposes formulators to export quota disruptions. Distribution runs through agricultural cooperatives in Brazil and the US Corn Belt, with cold-chain constraints favoring regional blenders over national suppliers for liquid biological formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil treatment procurement is pivoting toward service-attach models where precision application timing subscriptions and remote sensing validation layers expand faster than commodity amendment volumes.
For Market Incumbents: Secure microbial strain library acquisitions to defend formulation contract renewals against emerging biological specialists with accelerated EU Fertilizing Products Regulation pathways. Deepen backward integration into lignocellulosic feedstock supply for carbon-credit-qualified biochar production. Channel control through cooperative procurement network exclusivity agreements protects margin position from outcome-based contract displacement.
For New Entrants and Emerging Players: EU Fertilizing Products Regulation accelerated pathways for microbial inoculants create white-space entry points for strain-library developers with standardized efficacy dossiers. Target California specialty crop biological programs where almond and grape producers expand microbial inoculation budgets. Go-to-market through precision application convergence partnerships ties treatment timing to crop growth stages, displacing independent commodity distributors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biological formulation segments as distributed blending models replace centralized manufacturing. Long-term viability favors platform operators bundling seed-and-soil solutions over standalone amendment suppliers. Acquisition target archetype: regional blenders with cold-chain infrastructure and cooperative network relationships. Signal to watch: carbon credit qualification protocol adoption rates in voluntary offset markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Strain Library Acquisition | Strain ownership secures recurring formulation contracts with Brazil's agricultural cooperatives. |
| Precision Application Technology Integration | Sensor-data convergence creates subscription revenue pools for treatment-timing optimization services. |
| Carbon Credit Qualification Investment | Verified sequestration protocols unlock premium crop contracts in California export markets. |
| Regional Blending Capacity Expansion | Cold-chain proximity overcomes microbial shelf-life constraints limiting national distribution radius. |
| Outcome-Based Contract Structuring | Yield-verified performance guarantees consolidate procurement authority with integrated platform operators. |
Research Approach
Initial hypotheses were tested against primary input from agronomy service providers, agricultural cooperative procurement managers, microbial formulation R&D directors, and precision equipment engineers, and refined through secondary validation against EU ECHA dossier databases, ANVISA registration filings, US EPA FIFRA tolerance decisions, and customs trade data for phosphate rock and lignocellulosic biomass. Bottom-up triangulation across strain-library ownership, formulation capacity, and cooperative network penetration was cross-checked with top-down market sizing from amendment application rates and crop acreage expansion.
Variance decomposition across product type, application method, and end-user procurement authority shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include amendment chemistry class, crop type specificity, distribution channel cold-chain requirements, and regional regulatory cluster. CAGRs were derived from intensity-of-use trajectories in double-cropping expansion zones and biological substitution rates in EU REACH-regulated markets. Industry-specific forecast inputs incorporated carbon credit protocol adoption curves and precision application equipment installed base expansion.
Underlying assumptions cover residue-limit protocol stringency in export markets, microbial viability decay rates in liquid formulations, and phosphate rock export quota stability, with deviation risk concentrated in regulatory acceleration timelines and voluntary carbon market liquidity. Practitioners should keep alternative scenarios live as EU Fertilizing Products Regulation implementation pace and Brazilian Cerrado expansion limits evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
Asia Pacific Fungicide Market