
 United States Feed Amino Acids Market | 2026-2036
United States Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
United States Feed Amino Acids Market Outlook
Contract poultry growers is reorganizing procurement patterns across the United States feed amino acids landscape, shifting volume commitments toward integrator-direct supply agreements. Evonik Industries AG anchors production scale through its backward integration into methionine precursors, while Adisseo leverages dedicated U.S. manufacturing assets to compete on delivery reliability. Alltech, Inc. differentiates through yeast-derived natural amino acid platforms that target antibiotic-free feed programs.
United States feed amino acids comprise supplemental nitrogenous compounds added to livestock diets to optimize protein synthesis, with lysine, methionine, threonine, and tryptophan serving as the most commercially significant inputs formulated at precise inclusion rates of 0.1% to 0.5% by weight. Essential amino acids dominate volume consumption because corn-soybean meal basements remain deficient in lysine and methionine for monogastric species. Poultry feed applications command the largest share of demand, while aquaculture feed represents the fastest-growing application segment as inland recirculating systems expand across the Midwest and Delta regions.
The FDA Veterinary Feed Directive restricts medically important antimicrobial use in feed, redirecting formulation investment toward amino acid balancing as a performance alternative, while the USDA National Organic Program and various state-level nutrient management regulations in Iowa and North Carolina constrain application rates near watershed boundaries. The EPA's concentrated animal feeding operation permitting framework shapes facility expansion timelines and thus regional feed amino acid demand density. Stakeholders must monitor state-level phosphorus indexing requirements and emerging carbon accounting protocols for feed sourcing decisions.
Market Dynamics
Contract poultry growers in the Southeast are reorganizing procurement patterns toward integrator-direct supply agreements, compressing traditional distributor margins and reshaping volume allocation across the value chain.
Growth Catalysts
- FDA Veterinary Feed Directive:Restrictions on medically important antimicrobials redirect formulation investment toward amino acid balancing as a performance alternative in ruminant and swine channels.
- Corn-soybean meal basements:Persistent lysine and methionine deficiencies in standard monogastric feed formulations sustain baseline demand for supplemental nitrogenous compounds.
- Midwest aquaculture expansion:Inland recirculating aquaculture systems across Iowa, Indiana, and Ohio generate new demand for threonine-enriched feed formulations.
Market Restraints
- Petrochemical feedstock volatility:Methionine production relies on propylene and methyl mercaptan derivatives exposed to natural gas price swings.
- EPA concentrated animal feeding operation permitting:Facility expansion timelines in North Carolina and Iowa delay regional feed amino acid demand density growth.
- Phytogenic feed additives:Essential oils and plant extracts gain traction as partial substitutes for growth-promoting amino acid programs in antibiotic-free poultry operations.
Strategic Opportunities
- Delta region aquaculture:Catfish and hybrid striped bass operations in Mississippi and Arkansas remain underpenetrated for species-specific amino acid formulations.
- USDA National Organic Program:Certification requirements for organic livestock create premium pricing tiers for naturally derived amino acid sources.
- Precision fermentation:Microbial cell factories for amino acid production converge with carbon accounting protocols to attract sustainability-linked procurement.
Industry Challenges
- Phosphorus indexing compliance:State-level nutrient management regulations in watershed-adjacent counties constrain application rates and require reformulation expertise.
- Legacy feed mill integration:Automated amino acid dosing systems face retrofit complexity with existing batching infrastructure across independent Midwest facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Feed Amino Acids Market |
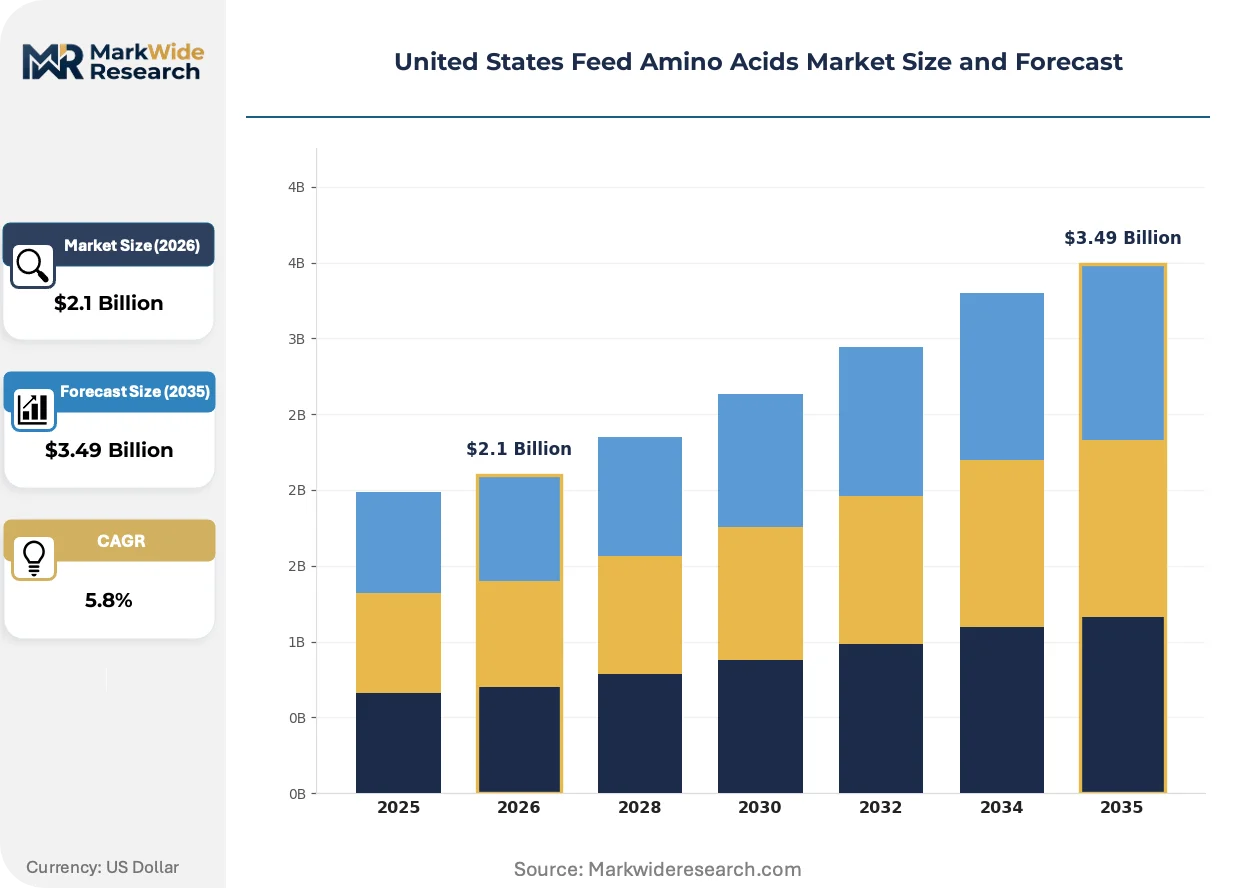
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Amino Acids, Non-Essential Amino Acids, Synthetic Amino Acids, Natural Amino Acids Application: Poultry Feed, Swine Feed, Ruminant Feed, Aquaculture Feed Form: Powder, Liquid, Granular, Pellet Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Ajinomoto Co., Inc., Land O'Lakes, Novus International Inc., Adisseo, IFF (Danisco Animal Nutrition), Evonik Industries AG, Kemin Industries, Alltech, Inc., Archer Daniel Midland Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Feed Amino Acids Market Strategic Shifts
Formulation science and regulatory compliance are actively reshaping competitive positioning in United States feed amino acids, with technology convergence and procurement model evolution driving vendor differentiation.
Precision fermentation-derived amino acids is supplanting petrochemical-sourced methionine in premium feed formulations. Vertically integrated poultry operators in the Southeast are adopting microbial cell factory outputs at pilot scale. This technology is compressing the cost differential between synthetic and bio-based nitrogenous compounds.
The EPA's concentrated animal feeding operation permitting framework tightens facility expansion timelines in Iowa and North Carolina watersheds. Operators must demonstrate nutrient management plans before feed amino acid demand density increases materialize. Pork integrators in these states are pre-positioning amino acid premix commitments to secure supply ahead of permitting approvals.
Buyer concentration among contract poultry growers is consolidating procurement authority with Southeast integrators. Traditional distributor networks face disintermediation as direct supply agreements capture volume commitments. This pattern is most visible in Georgia and Alabama, where Tyson Foods and Pilgrim's Pride operators negotiate amino acid pricing at corporate rather than farm level.
United States Feed Amino Acids Market Segmentation
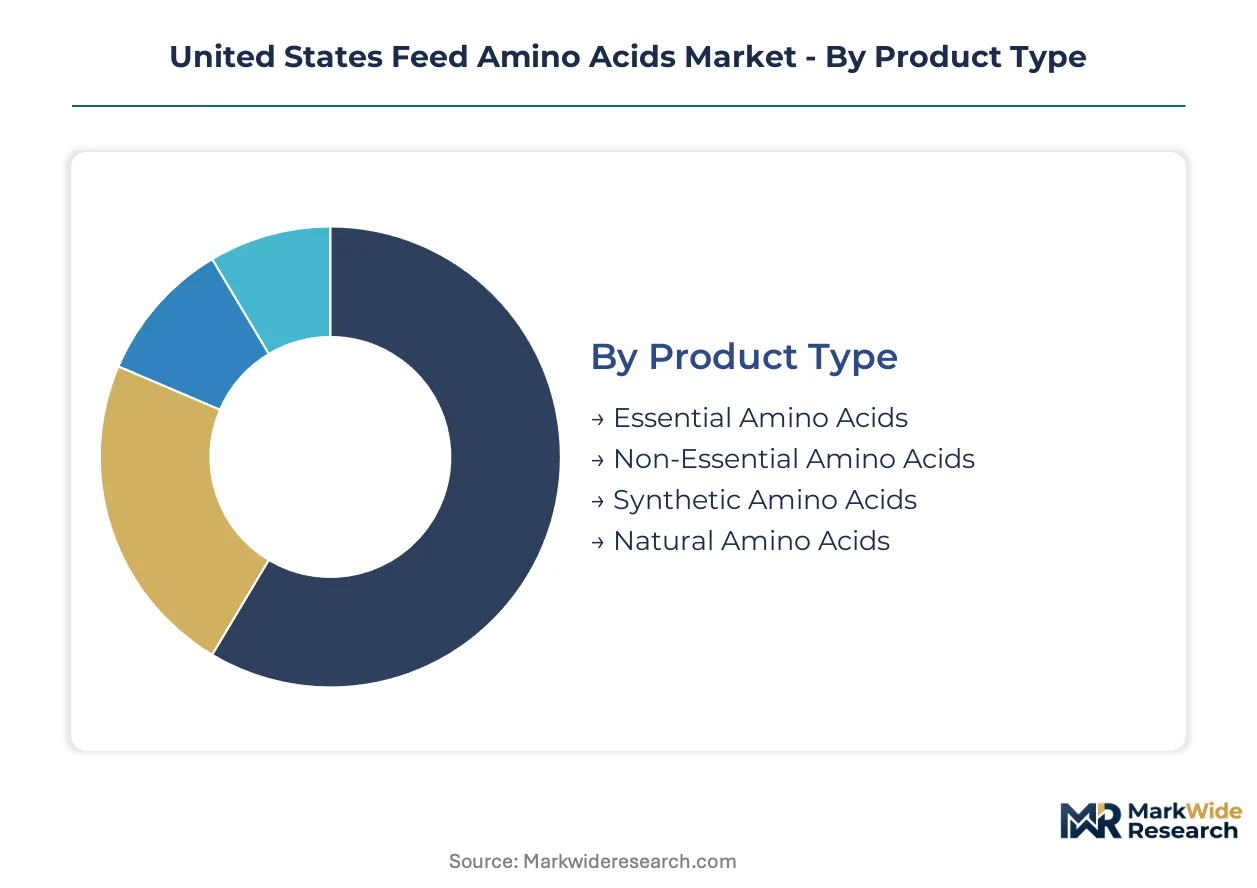
Feed amino acid suppliers in the United States configure product portfolios around species-specific nutritional deficits and integrator procurement preferences. Segmentation discipline separates commodity volume plays from premium formulation services.
Product Type:
Natural amino acid platforms face intensifying substitution pressure from precision fermentation outputs and phytogenic alternatives in antibiotic-free feed programs.
- Essential Amino Acids:Lysine, methionine, threonine, and tryptophan formulations address corn-soybean meal deficiencies in monogastric diets. Iowa and North Carolina pork integrators sustain baseline demand through standardized 0.1% to 0.5% inclusion protocols. The FDA Veterinary Feed Directive redirects ruminant channel investment toward lysine and methionine balancing as antimicrobial replacements.
- Synthetic Amino Acids:Petrochemical-derived methionine precursors dominate cost-sensitive poultry formulations. Propylene and methyl mercaptan feedstock volatility compresses margin predictability for Southeast broiler integrators.
- Non-Essential Amino Acids:Glutamic acid and alanine supplements support stress recovery in high-density confinement operations.
- Natural Amino Acids:Yeast-derived nitrogenous compounds command organic certification premiums under USDA National Organic Program standards.
Essential amino acids retain volume leadership; natural amino acids hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity poultry formulations from precision aquaculture nutrition requiring species-specific threonine enrichment.
- Poultry Feed:Broiler and layer operations in Georgia and Alabama consume the largest share through integrator-direct procurement. Tyson Foods and Pilgrim's Pride negotiate corporate-level amino acid commitments, compressing traditional distributor margins.
- Aquaculture Feed:Inland recirculating systems across Iowa, Indiana, and Ohio generate new demand for threonine-enriched formulations. Mississippi and Arkansas catfish operations remain underpenetrated for species-specific amino acid programs.
- Swine Feed:Vertically integrated Iowa and North Carolina operations cluster near feed milling infrastructure, sustaining lysine demand density.
- Ruminant Feed:Dairy and beef operations face FDA restrictions on growth-promoting premixes, redirecting formulation investment toward amino acid balancing.
Poultry feed retains volume leadership; aquaculture feed holds the steepest expansion curve.
Form:
Customer type preferences diverge between automated feed mill operators demanding powder precision and smaller independents favoring liquid handling convenience.
- Powder:Fine-mesh lysine and methionine derivatives enable precise dosing in automated batching systems. Legacy Midwest feed mills face retrofit complexity integrating powder handling infrastructure.
- Liquid:Methionine hydroxy analogue solutions simplify handling for smaller independent operations lacking pneumatic conveying systems.
- Granular:Dust-reduced formulations improve worker safety compliance under OSHA standards.
- Pellet:Co-extruded amino acid premixes reduce segregation in finished feed transport.
Powder retains volume leadership; liquid holds the steepest expansion curve.
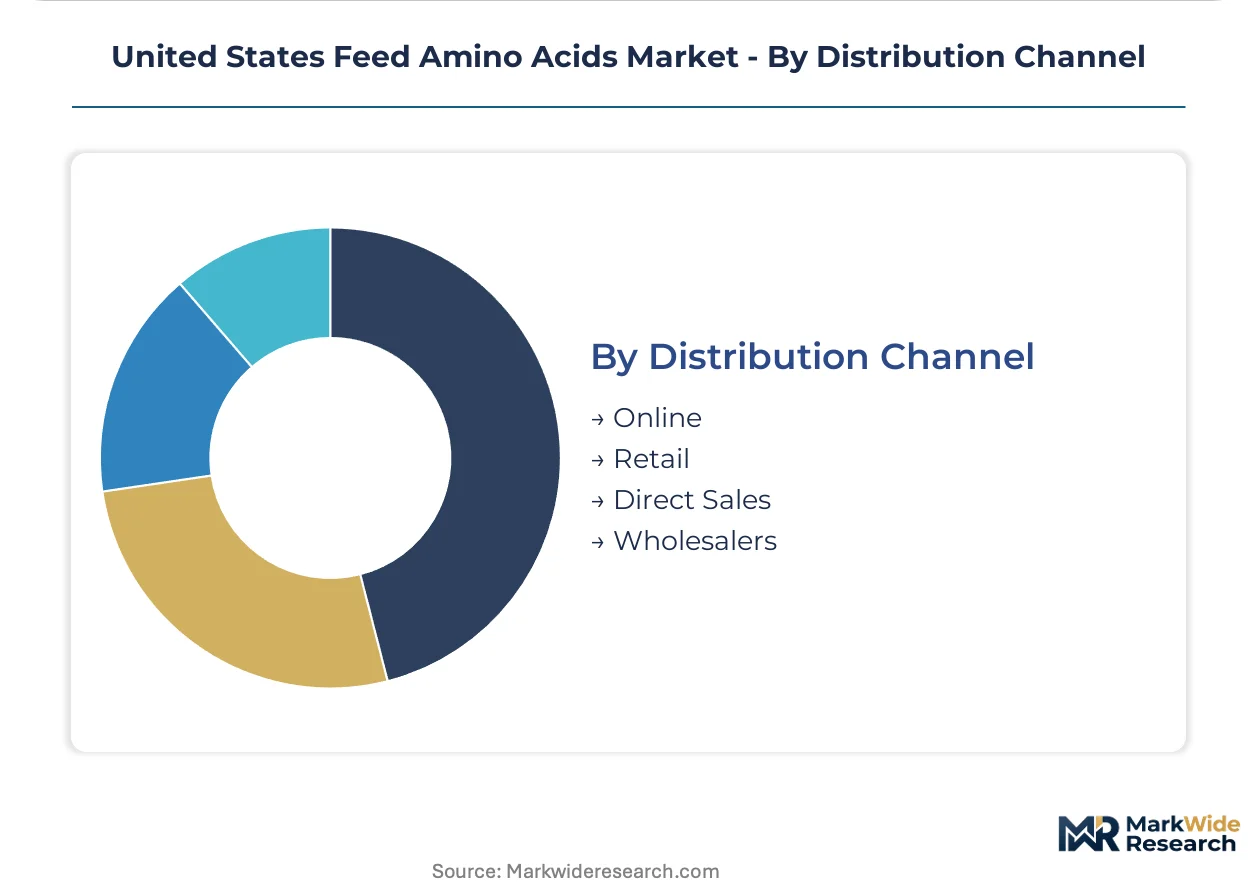
Distribution Channel:
Supply concentration in integrator-dominated geographies accelerates channel disintermediation, compressing wholesaler relevance.
- Direct Sales:Southeast poultry integrators consolidate procurement authority through corporate-level amino acid supply agreements. Evonik Industries AG and Adisseo leverage dedicated U.S. manufacturing assets to compete on delivery reliability.
- Wholesalers:Independent Midwest pork operations sustain residual demand through regional feed distribution networks.
- Online:Digital procurement platforms gain traction among specialty aquaculture operators seeking small-batch threonine formulations.
- Retail:Farm supply stores serve hobbyist and small-scale livestock producers with packaged amino acid supplements.
Direct sales retains volume leadership; online holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Class I rail corridors linking Iowa feed mills to Gulf Coast export terminals underwrite the Midwest's dominance in U.S. feed amino acid logistics.
Southeast
Georgia and Alabama contract poultry operations drive lysine and methionine consumption through integrator-direct procurement agreements. The FDA Veterinary Feed Directive redirects broiler formulation investment toward amino acid balancing as antimicrobial alternatives. Corporate-level negotiations by Tyson Foods and Pilgrim's Pride operators compress traditional distributor margins across the region.
Midwest
Iowa and Indiana vertically integrated pork operations cluster near automated feed milling infrastructure, sustaining standardized inclusion protocols. State-level phosphorus indexing requirements in watershed-adjacent counties constrain application rates and demand reformulation expertise. Inland recirculating aquaculture systems across Ohio generate emerging demand for threonine-enriched formulations.
Mid-Atlantic
North Carolina pork integrators face EPA concentrated animal feeding operation permitting delays that postpone regional feed amino acid demand density growth. The state's nutrient management regulations require demonstration of comprehensive nutrient management plans before facility expansion approvals. Operators pre-position amino acid premix commitments to secure supply ahead of permitting decisions.
Delta
Mississippi and Arkansas catfish and hybrid striped bass operations remain underpenetrated for species-specific amino acid formulations. USDA National Organic Program certification requirements create premium pricing tiers for naturally derived amino acid sources in organic livestock channels. Regional feed distributors serve independent aquaculture operators through small-batch procurement platforms.
Pacific Northwest
Oregon and Washington dairy operations navigate state-level carbon accounting protocols that influence feed sourcing decisions for amino acid procurement. The region's smaller-scale livestock base sustains residual demand through regional feed distribution networks rather than integrator-direct channels. Precision fermentation-derived amino acids attract sustainability-linked procurement from coastal organic dairy cooperatives.
United States Feed Amino Acids Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and formulation expertise, producing a tiered structure where global chemical conglomerates anchor volume supply while regional nutrition firms capture premium niches. Three archetypes dominate: petrochemical-integrated methionine producers, yeast-derived natural amino acid specialists, and diversified agricultural processors with captive feed milling networks. Capacity expansion and backward integration into precursors represent the dominant competitive moves as firms defend margin position against feedstock volatility.
Among the petrochemical-integrated tier, Evonik Industries AG and Adisseo occupy positions defined by dedicated U.S. manufacturing assets and delivery reliability competition. Alltech, Inc. exemplifies the natural amino acid archetype through yeast-derived platforms targeting antibiotic-free feed programs. Archer Daniel Midland Co. represents diversified agricultural processors with upstream control over grain supply chains and captive feed formulation infrastructure.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Land O'Lakes |
| Novus International Inc. |
| Adisseo |
| IFF (Danisco Animal Nutrition) |
| Evonik Industries AG |
| Kemin Industries |
| Alltech, Inc. |
| Archer Daniel Midland Co. |
| Others |
Value Chain & Pricing Dynamics
Integrator-direct supply agreements lock in multi-year volume commitments for Southeast poultry operators, securing methionine and lysine access while compressing price visibility for independent distributors. This contract structure concentrates procurement authority with Tyson Foods and Pilgrim's Pride, stripping traditional wholesalers of margin leverage.
Pricing Analysis
Volume-discount tiering separates corporate amino acid commitments from spot-market purchases by independent Midwest pork operations. Pricing stratifies across premium, standard, and economy tiers based on certification grade and delivery reliability guarantees. Cost compression in synthetic methionine is intensifying because propylene feedstock volatility feeds through from Gulf Coast petrochemical complexes. Contract poultry integrators exhibit lowest price sensitivity due to captive supply agreements, while small-scale aquaculture operators in the Delta region face acute margin pressure from threonine spot pricing.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Antwerp methionine precursor terminals face intermittent congestion on trans-Atlantic container lanes, extending lead times for Adisseo and Evonik Industries AG coastal manufacturing assets. Geographic supply concentration centers on Germany, Belgium, and Singapore for methionine precursors, with U.S. methionine hydroxy analogue production drawing from methyl mercaptan feedstocks. Single-source vulnerability runs through propylene supply contracts tied to natural gas pricing. Distribution runs through barge networks on the Mississippi River linking Iowa feed mills to Gulf export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phytogenic feed additives present a credible substitution threat to growth-promoting amino acid programs, forcing incumbents to defend formulation share through differentiated service layers and certification investments.
For Market Incumbents: Compound formulation expertise in phosphorus-indexed watershed compliance to lock in Iowa and North Carolina pork integrators facing EPA permitting delays. Deepen backward integration into methionine precursors to buffer margin pressure from propylene volatility. Prioritize automated dosing system retrofit partnerships with legacy Midwest feed mills to entrench equipment relationships ahead of distributor disintermediation.
For New Entrants and Emerging Players: Species-specific formulation services for underpenetrated Mississippi and Arkansas catfish operations offer white-space entry where incumbents lack aquaculture technical support. Precision fermentation-derived threonine for organic dairy cooperatives in the Pacific Northwest represents a certification-premium segment with limited synthetic competition. Pursue digital procurement platform partnerships with inland recirculating aquaculture systems seeking small-batch, rapid-turn amino acid fulfillment.
For Investors and Strategic Acquirers: Regional yeast-derived amino acid specialists with USDA National Organic Program certification infrastructure and existing distributor relationships in watershed-adjacent counties present consolidation targets. Long-term viability hinges on carbon accounting protocol alignment as coastal organic livestock channels expand. Monitor FDA enforcement patterns on Veterinary Feed Directive compliance as an inflection signal for amino acid substitution velocity in ruminant channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methionine Precursors | Captive propylene supply from Gulf Coast petrochemical complexes insulates margin volatility. |
| Precision Fermentation Capacity Buildout | Microbial cell factory outputs attract sustainability-linked procurement from organic dairy cooperatives. |
| Automated Dosing System Partnerships | Retrofit alliances with legacy Midwest feed mills entrench equipment relationships ahead of distributor displacement. |
| Species-Specific Aquaculture Formulation Services | Technical support layers for Mississippi catfish operations penetrate under-served Delta demand. |
| USDA Organic Certification Investment | Premium pricing tiers under National Organic Program standards capture antibiotic-free feed program growth. |
Study Parameters
A spread of perspectives from broiler integrator procurement directors, feed mill operations managers, amino acid manufacturing technical leads, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA Veterinary Feed Directive guidance documents, EPA concentrated animal feeding operation permitting records, USDA National Organic Program certification databases, and SEC 10-K filings from listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis.
Segmentation dimensions modeled include product type, livestock application, physical form, and distribution channel across the analysis window. CAGRs were computed from year-over-year growth trajectories applied to baseline volume estimates. Industry-specific forecast inputs incorporated state-level phosphorus indexing compliance timelines and inland recirculating aquaculture system expansion permits across Iowa, Indiana, and Ohio.
Forecasts assume regulatory continuity in FDA Veterinary Feed Directive enforcement and EPA nutrient management frameworks; material policy shifts would require re-modeling. Commodity feedstock volatility, phytogenic substitution acceleration, and carbon accounting protocol adoption represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
North America Feed Minerals Market