
 Global Silage Inoculants Market | 2026-2036
Global Silage Inoculants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silage Inoculants Market Foresight
Dairy farmer end-user demand is consolidating as livestock operations scale forage preservation programs. Chr. Hansen leverages specialized microbial strain libraries to dominate European supply channels. Cargill Incorporated anchors North American distribution through integrated feed manufacturing networks. BASF SE competes on formulation stability across variable harvest conditions.
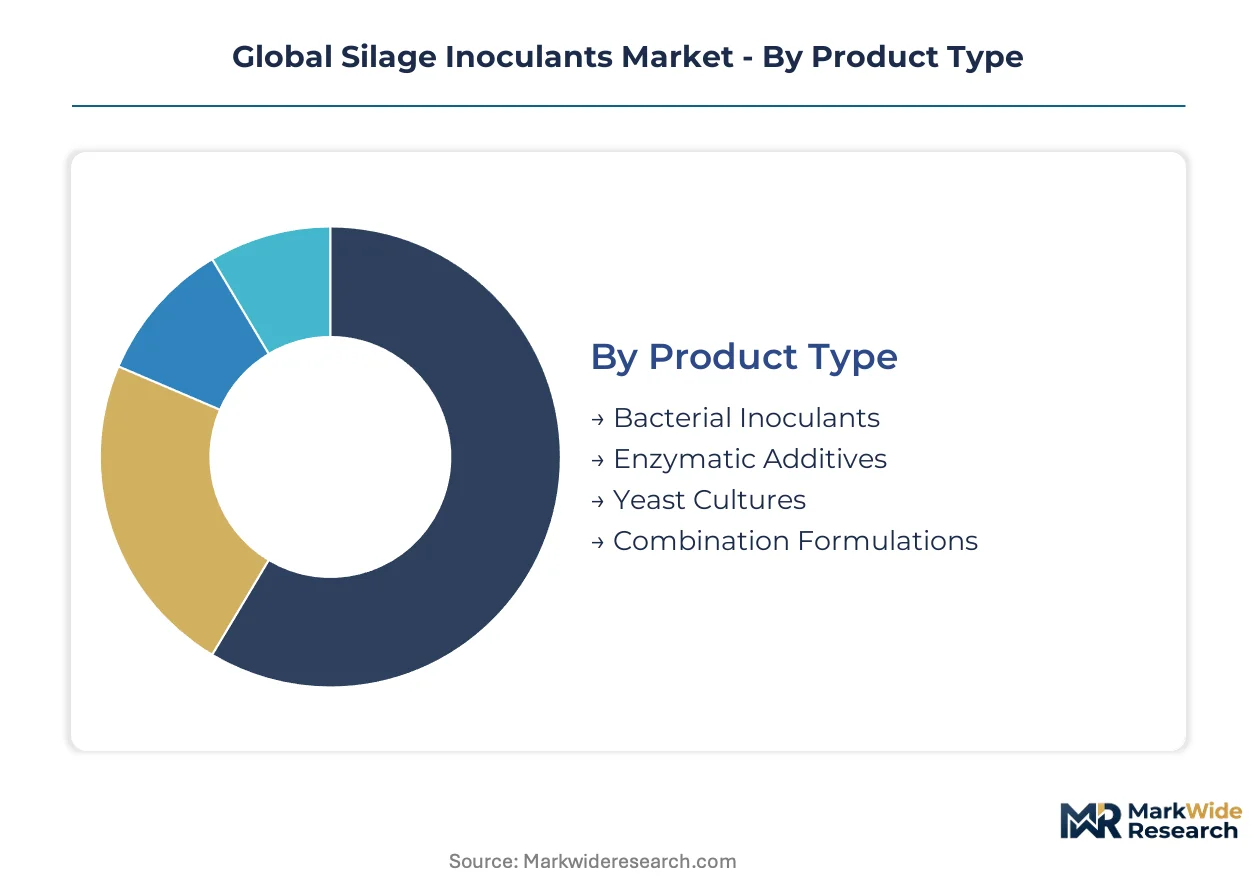
Silage inoculants are live microbial preparations, typically containing Lactobacillus plantarum, Pediococcus pentosaceus, or Lactobacillus buchneri at concentrations exceeding 100,000 colony-forming units per gram, applied to chopped forage to accelerate lactic acid fermentation, reduce pH below 4.2, and inhibit spoilage organisms during anaerobic storage. Bacterial inoculants occupy the largest share of product type revenue due to proven efficacy in corn and grass silage preservation, while enzymatic additives represent the fastest-expanding category as producers seek fiber digestibility improvements without synthetic chemical residues. Liquid formulation leads volume sales among dairy farmers for uniform spray application at harvest, though powder alternatives gain traction with smaller agricultural cooperatives seeking extended shelf stability.
The European Food Safety Authority evaluates microbial strains under Qualified Presumption of Safety protocols, while the FDA regulates silage additives as GRAS substances or feed ingredients depending on bacterial species composition. China's Ministry of Agriculture and Rural Affairs enforces strain registration for imported microbial products, creating compliance thresholds for foreign suppliers. Stakeholders must monitor evolving strain approval timelines and regional residue testing protocols to secure market access across jurisdictions.
Market Dynamics
The EU Green Deal's agricultural sustainability mandates are compressing synthetic additive use and accelerating microbial strain development timelines across European forage preservation supply chains.
Growth Catalysts
- EU Green Deal agricultural mandates:The framework's Farm to Fork strategy requires 50% reduction in chemical pesticide use by 2030, redirecting dairy operations toward microbial fermentation aids.
- Large-scale dairy consolidation:Operations exceeding 1,000 head in the United States Corn Belt are standardizing inoculant protocols to reduce dry matter loss during anaerobic storage.
- Fiber digestibility engineering:Enzymatic additive formulations containing cellulase and hemicellulase complexes are unlocking greater metabolizable energy from grass and legume silages.
Market Restraints
- Strain registration timelines:China's Ministry of Agriculture and Rural Affairs enforces 18-24 month approval windows for imported microbial products, freezing supplier market entry.
- Harvest condition volatility:Variable moisture content in forage crops degrades Lactobacillus buchneri viability, forcing reformulation investments.
- Synthetic acid preservative substitution:Propionic acid and formic acid blends retain cost advantages for smallholder producers with limited capital for live culture storage infrastructure.
Strategic Opportunities
- Brazilian pasture expansion:Conversion of degraded cattle ranges to intensive dairy in Mato Grosso and Goiás creates first-time inoculant demand among 50,000+ mid-scale producers.
- CRISPR-edited strain development:Precision microbiology is converging with anaerobic fermentation science to engineer temperature-tolerant Lactobacillus variants for tropical silage conditions.
- Veterinary telemedicine channels:Remote forage consulting platforms are bypassing traditional feed dealer networks to deliver strain-specific recommendations directly to farm managers.
Industry Challenges
- Microbial quality assurance staffing:Commercial laboratories capable of enumerating colony-forming units per gram at harvest-site conditions remain scarce outside the Netherlands and Wisconsin.
- Multi-strain formulation stability:Maintaining synergistic activity between Lactobacillus plantarum and Pediococcus pentosaceus across 18-month shelf life requirements demands capital-intensive lyophilization infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silage Inoculants Market |
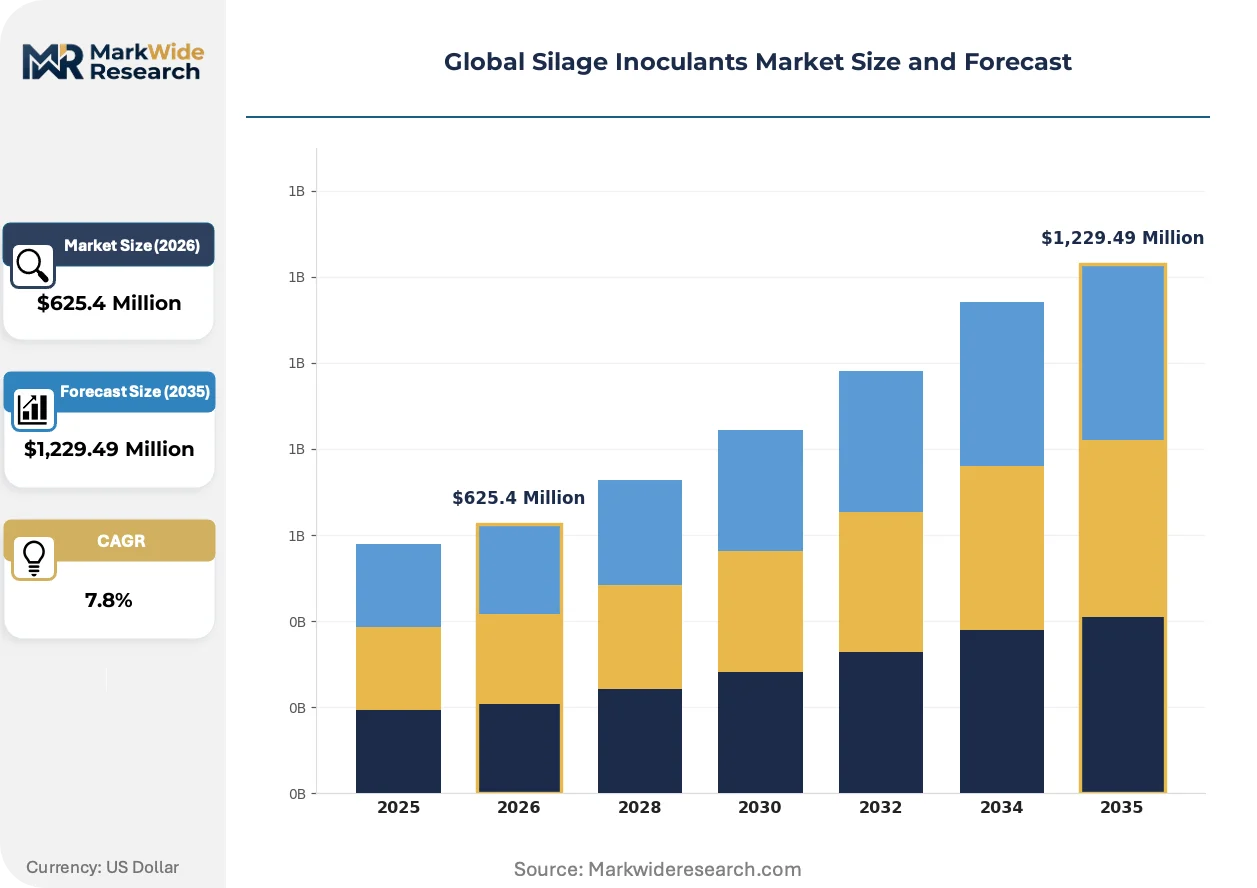
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,229.49 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Inoculants, Enzymatic Additives, Yeast Cultures, Combination Formulations Application: Corn Silage, Grass Silage, Alfalfa Silage, Sorghum Silage End User: Dairy Farmers, Livestock Producers, Agricultural Cooperatives, Feed Manufacturers Formulation: Liquid, Powder, Granular, Pelleted |
| Companies Covered | Archer-Daniels-Midland Company, Chr. Hansen, Corteva Agriscience, Cargill Incorporated, DuPont, Kemin Industries, Lallemand, BASF SE, Volac International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silage Inoculants Market Shifts & Advancements
Formulation science and regulatory biology are converging to redefine how live microbial products reach field application, with preservation efficiency becoming a measurable output rather than an assumed input.
Multi-strain consortia containing Lactobacillus buchneri for aerobic stability and Lactobacillus plantarum for rapid pH drop are absorbing market share from single-species preparations. Dairy cooperatives in Denmark and the Netherlands are adopting these combinations at harvest, compressing the performance gap between commodity and premium inoculant tiers. The technology is absorbing R&D investment that previously flowed toward chemical acidification alternatives.
EFSA's Qualified Presumption of Safety protocols are tightening documentation requirements for novel microbial strains entering European feed channels. Manufacturers must now submit whole-genome sequencing data and toxigenicity assessments before market authorization. Small strain development houses in France and Germany are responding by pooling toxicology resources through cooperative pre-competitive research frameworks.
Direct-to-farm digital procurement platforms are fragmenting traditional feed dealer control over inoculant distribution. Large Wisconsin and California dairies are subscribing to season-long forage management programs that bundle strain selection, application timing, and fermentation monitoring. This behavioral shift is most visible in the United States Corn Belt, where 500+ head operations bypass cooperative purchasing to negotiate volume contracts with microbial suppliers.
Global Silage Inoculants Market Segmentation
Silage inoculant procurement patterns diverge sharply across microbial composition, crop substrate, and operational scale. EFSA's strain approval protocols and China's registration timelines create compliance friction that reshapes competitive positioning within each segment tier.
Product Type:
EFSA's Qualified Presumption of Safety protocols and China's 18-24 month strain registration windows impose divergent compliance burdens across microbial categories, with live bacterial preparations facing the heaviest documentation requirements.
- Bacterial Inoculants:Live preparations of Lactobacillus plantarum, Pediococcus pentosaceus, or Lactobacillus buchneri exceeding 100,000 colony-forming units per gram dominate commercial volumes. Large-scale dairy operations in Wisconsin and the Netherlands standardize these for rapid pH suppression below 4.2 during anaerobic storage, though harvest moisture volatility degrades viability and forces reformulation investments.
- Enzymatic Additives:Cellulase and hemicellulase complexes target fiber digestibility improvements without synthetic chemical residues. Danish dairy cooperatives and California feedlots are expanding procurement of these additives as the EU Green Deal's Farm to Fork strategy compresses synthetic acid use.
- Yeast Cultures:Saccharomyces cerevisiae-based preparations support rumen fermentation efficiency in high-producing dairy herds.
- Combination Formulations:Multi-strain consortia merge bacterial and enzymatic activity for pH drop acceleration plus fiber degradation.
Leading the category by volume: Bacterial Inoculants. Growing fastest: Enzymatic Additives.
Application:
Moisture content and sugar availability at harvest determine which inoculant chemistries perform reliably, creating geographic clustering around dominant crop types.
- Corn Silage:High-sugar, high-moisture substrate supports aggressive Lactobacillus plantarum fermentation across the United States Corn Belt. Iowa and Illinois operations exceeding 1,000 head apply liquid formulations uniformly via spray equipment at chopper discharge.
- Grass Silage:Lower sugar content and variable dry matter demand specialized strain selection. German and French dairy cooperatives in Lower Saxony and Brittany favor multi-strain consortia with Lactobacillus buchneri for aerobic stability.
- Alfalfa Silage:Buffering capacity from high protein complicates pH reduction. Specialized inoculant formulations with elevated bacterial loading rates address this challenge.
- Sorghum Silage:Drought-tolerant crop expansion in Kansas and Nebraska creates emerging demand for temperature-tolerant microbial strains.
Corn Silage commands the largest application share. Alfalfa Silage climbs the fastest as dairy nutritionists prioritize protein preservation.
End User:
Capital intensity and technical staffing separate procurement behavior across operational categories, with scale determining whether buyers negotiate direct or through intermediaries.
- Dairy Farmers:Operations exceeding 500 head in Wisconsin and California subscribe to season-long forage management programs bundling strain selection with fermentation monitoring. Direct-to-farm digital procurement platforms are fragmenting traditional feed dealer control.
- Livestock Producers:Beef cattle backgrounding operations in the Texas Panhandle and Nebraska Sandhills apply inoculants less systematically due to lower feed cost sensitivity.
- Agricultural Cooperatives:Smaller member dairies in France and Germany pool purchasing power for powder formulations with extended shelf stability.
- Feed Manufacturers:Cargill Incorporated and integrated compounders anchor North American distribution through manufacturing networks embedding inoculants into complete rations.
Dairy Farmers absorb the highest end-user volume. Feed Manufacturers are expanding most quickly as premix integration accelerates.
Formulation:
Application equipment compatibility and storage infrastructure constraints dictate format selection across climate zones and operational sizes.
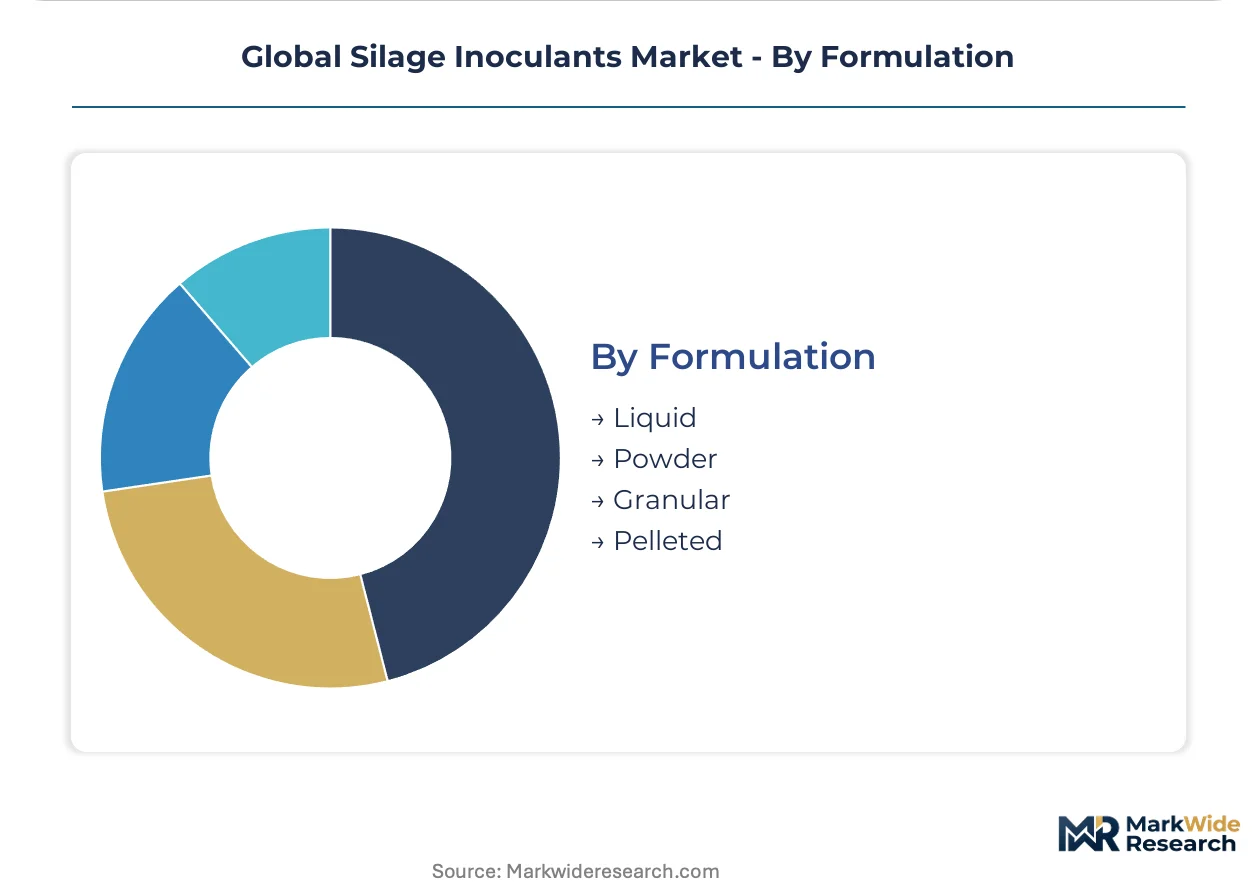
- Liquid:Uniform spray application at harvest dominates among large-scale operations with calibrated applicators. Tank-mix stability requirements limit distribution radius from production facilities.
- Powder:Extended shelf stability benefits smaller cooperatives with limited cold chain infrastructure. Reconstitution at point of use demands precise water quality management.
- Granular:Free-flowing characteristics suit automated dispensing systems in commercial feed mills.
- Pelleted:Compressed formats minimize dust exposure and improve handler safety in high-volume operations.
Liquid formulation leads by volume. Powder alternatives gain share fastest among mid-scale producers seeking supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for agricultural biotechnology in Denmark and the Netherlands concentrate microbial strain development infrastructure, while dairy belt expansion in the United States and Brazil drives field application demand.
United States
The Corn Belt's consolidation of dairies exceeding 1,000 head creates standardized inoculant procurement protocols. FDA regulates silage additives as GRAS substances or feed ingredients depending on bacterial species composition. Iowa and Wisconsin operations apply liquid formulations uniformly via spray equipment calibrated to chopper discharge rates.
Germany
Lower Saxony dairy cooperatives favor multi-strain consortia with Lactobacillus buchneri for aerobic stability in grass silage preservation. EFSA's Qualified Presumption of Safety protocols mandate whole-genome sequencing data and toxigenicity assessments before market authorization. Bavarian feed manufacturers embed inoculants into complete rations through integrated compounder networks.
Brazil
Conversion of degraded cattle ranges to intensive dairy in Mato Grosso and Goiás creates first-time inoculant demand among mid-scale producers. ANVISA enforces strain registration for imported microbial products, creating compliance thresholds for foreign suppliers. São Paulo-based agricultural cooperatives pool purchasing power for powder formulations with extended shelf stability.
China
Large-scale dairy operations in Hebei and Shandong provinces are expanding microbial additive adoption for feed preservation efficiency. The Ministry of Agriculture and Rural Affairs enforces 18-24 month approval windows for imported microbial products, freezing supplier market entry. Yangtze River Delta feed mills are developing domestic strain capabilities to bypass registration delays.
Netherlands
Dutch dairy cooperatives are adopting combination formulations that merge bacterial and enzymatic activity for pH drop acceleration plus fiber degradation. EU Green Deal Farm to Fork strategy mandates 50% reduction in chemical pesticide use by 2030, redirecting operations toward microbial fermentation aids. Wageningen clusters host commercial laboratories capable of enumerating colony-forming units per gram at harvest-site conditions.
Global Silage Inoculants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with microbial strain developers commanding premium positioning in European supply channels while integrated feed compounders anchor North American distribution. The vendor base organizes around three strategic archetypes: specialized microbial houses with proprietary strain libraries, diversified agricultural conglomerates with manufacturing scale, and regional cooperatives with localized fermentation expertise. Capacity expansion and geographic licensing agreements represent the dominant competitive moves as players seek to bypass China's extended registration timelines.
Within the specialized microbial tier, Chr. Hansen and Lallemand exemplify strain-development-focused positioning, while Cargill Incorporated occupies a position among integrated agricultural conglomerates with captive feed manufacturing networks. BASF SE sits within the diversified chemical-biological hybrid archetype, competing on formulation stability across variable harvest conditions. These three anchors collectively represent the competitive spectrum from pure-play microbiology to backward-integrated supply chain control.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Chr. Hansen |
| Corteva Agriscience |
| Cargill Incorporated |
| DuPont |
| Kemin Industries |
| Lallemand |
| BASF SE |
| Volac International |
| Others |
Supply & Pricing Matrix
Lyophilization energy costs anchor the cost stack for live microbial preparations, flowing from Dutch and Wisconsin production clusters through three-tier pricing structures that separate premium multi-strain consortia from standard single-species formulations and economy-tier generic bacterial preparations.
Pricing Analysis
Short lead-time premiums of 15-25% apply to harvest-season spot orders when dairy operations face chopper-ready urgency without advance procurement. The market runs on a contract-based long-term offtake model with annual volume commitments securing preferential strain access. Price differentiation stems from certification tier—EFSA QPS-approved strains command premiums over generic GRAS equivalents—and from after-sales bundling of fermentation monitoring services. Cost compression in the economy tier is intensifying because Brazilian and Chinese domestic strain developers are bypassing import registration costs. Smallholder cooperatives in France and Germany exhibit highest price sensitivity, while 1,000+ head Corn Belt operations prioritize performance consistency over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements from large dairy cooperatives mandate qualified supplier lists spanning at least two of the Netherlands, Denmark, and Wisconsin to mitigate single-source vulnerability during peak harvest windows. Geographic supply concentration centers on Denmark and the Netherlands for strain development infrastructure, with Wisconsin anchoring North American formulation and distribution. Raw material dependencies include pharmaceutical-grade fermentation media, specialized cryoprotectants for lyophilization, and food-grade carrier substrates. Tariff exposure on European-manufactured live cultures entering Brazil and China creates compliance cost layering. Distribution runs through integrated feed compounder networks in North America and agricultural cooperative purchasing pools in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
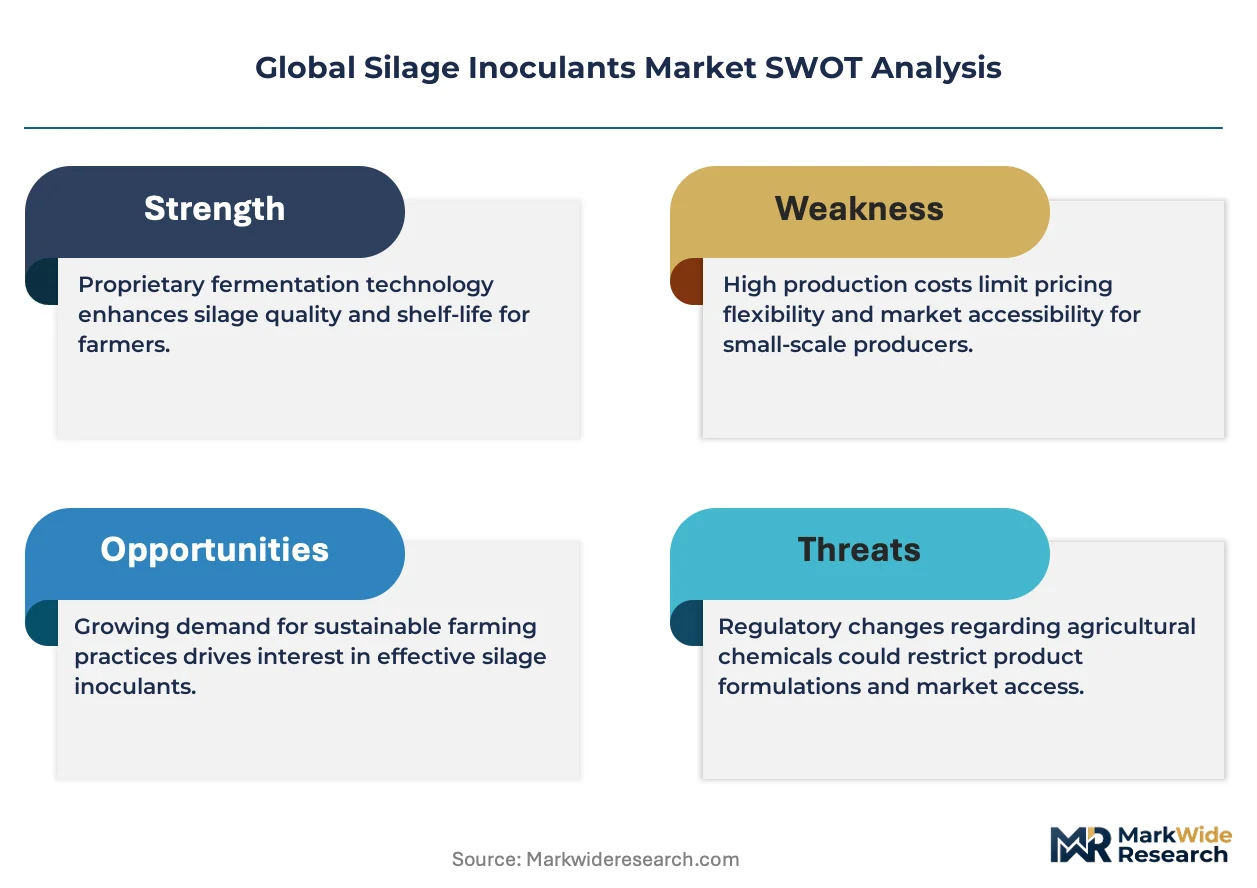
EFSA's whole-genome sequencing mandate under QPS protocols has erected a cost-of-compliance barrier that freezes out sub-scale strain developers, entrenching incumbent advantage for houses with dedicated toxicology documentation teams.
For Market Incumbents: Anchor strain library value through exclusive licensing agreements with Wageningen and Wisconsin academic microbiology programs, locking up temperature-tolerant Lactobacillus variants before CRISPR-edited competitors reach field trials. Defend against synthetic acid preservative substitution by embedding fermentation monitoring services into multi-year supply contracts, raising switching costs for Corn Belt dairies. Prioritize backward integration into lyophilization capacity to capture margin currently flowing to Dutch toll manufacturers.
For New Entrants and Emerging Players: Mid-scale Brazilian dairy converters in Mato Grosso represent the most penetrable buyer archetype, with first-time inoculant demand unclaimed by established dealer networks. Bypass ANVISA registration delays by partnering with São Paulo-based agricultural cooperatives for domestic strain co-development. Target veterinary telemedicine channels as the go-to-market angle, delivering remote forage consulting that fragments traditional feed dealer control over technical recommendations.
For Investors and Strategic Acquirers: China's Ministry of Agriculture and Rural Affairs granting expedited registration to domestic strain developers is the leading indicator that import substitution will accelerate, compressing foreign supplier market share. Frame long-term viability around 5-10 year windows where microbial quality assurance laboratory scarcity—currently concentrated in the Netherlands and Wisconsin—creates acquisition value for facilities capable of harvest-site CFU enumeration. Target vertically integrated strain developers with captive lyophilization infrastructure and existing EFSA QPS dossiers.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Edited Strain Development | Precision microbiology enables temperature-tolerant Lactobacillus variants for tropical silage conditions in Brazil. |
| Domestic Strain Registration | Yangtze River Delta feed mills bypass China's 18-24 month import approval windows through indigenous R&D. |
| Direct-to-Farm Digital Platforms | Wisconsin and California dairies subscribe to bundled strain selection and fermentation monitoring services. |
| Multi-Strain Consortium Expansion | Danish cooperatives absorb market share from single-species preparations through synergistic bacterial-enzymatic combinations. |
| Lyophilization Capacity Addition | Capital-intensive preservation infrastructure secures 18-month shelf stability for powder formulations targeting mid-scale cooperatives. |
Research Methodology
Document review covered EFSA QPS strain approval databases, FDA GRAS notifications, Chinese Ministry of Agriculture registration filings, and trade customs records for microbial product imports, complemented by interviews with strain development scientists at Dutch and Danish biotechnology clusters, procurement directors at Wisconsin dairy cooperatives, regulatory affairs leads navigating ANVISA and SAMR pathways, and feed mill technical managers in Iowa and São Paulo. Secondary validation drew from SEC 10-K disclosures of integrated agricultural conglomerates, EU Farm to Fork strategy implementation reports, and academic fermentation science publications. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Segmented outputs across bacterial, enzymatic, yeast, and combination product types; corn, grass, alfalfa, and sorghum applications; liquid, powder, granular, and pellet formulations; and dairy farmer, livestock producer, cooperative, and feed manufacturer end users fed into the analytical framework over the projection horizon. CAGRs derived from logistic adoption curves modeling microbial penetration rates against synthetic acid displacement trajectories, with inputs including dairy herd consolidation velocity, EU Green Deal compliance deadlines, and tropical dairy expansion patterns in Brazil.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CRISPR regulatory classification shifts and China domestic strain development acceleration. Deviation in EFSA QPS documentation requirements or ANVISA registration timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
India Feed Enzymes Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market