
 Glyphosate Market | 2026-2036
Glyphosate Market Size, Share, and Industry Trends Forecast 2026-2036
Glyphosate Market Analysis
EU Green Deal chemical sustainability targets are rebalancing registration costs for generic manufacturers against incumbent formulators. Bayer AG anchors its position through backward integration into glyphosate acid production and proprietary surfactant systems. Zhejiang Xinan Chemical Industrial Group Co., Ltd. competes on manufacturing scale, operating one of the world's largest glyphosate technical facilities. BASF SE differentiates through formulated product portfolios that bundle glyphosate with resistance-management chemistries.
Glyphosate is a broad-spectrum, post-emergent phosphonic acid herbicide that inhibits the 5-enolpyruvylshikimate-3-phosphate (EPSP) synthase enzyme in plants, typically manufactured through a dialkyl phosphite dialkylation process with subsequent hydrolysis to the active acid form. Its primary commercial purpose is weed control in agronomic and non-crop settings where total vegetation management or selective tolerance via genetic modification enables in-crop application. The herbicide product type dominates value capture given its direct linkage to row-crop acreage, while liquid formulations lead volume throughput due to compatibility with aerial and ground spray equipment across large-scale farming operations. Agricultural application channels sustain the deepest margin pools, though non-agricultural use in industrial rights-of-way generates premium pricing through specialized formulation requirements.
The EPA governs glyphosate tolerance levels and ecological risk assessments in the United States, while China's MEE enforces emission standards on glyphosate technical production facilities under dual carbon goals. Brazil's national health surveillance agency, ANVISA, regulates maximum residue limits that directly shape import acceptance criteria for soybean and corn exports. Stakeholders must monitor evolving co-formulant disclosure requirements and pollinator risk assessments as regulatory bodies tighten the evidentiary burden for continued registration.
Market Dynamics
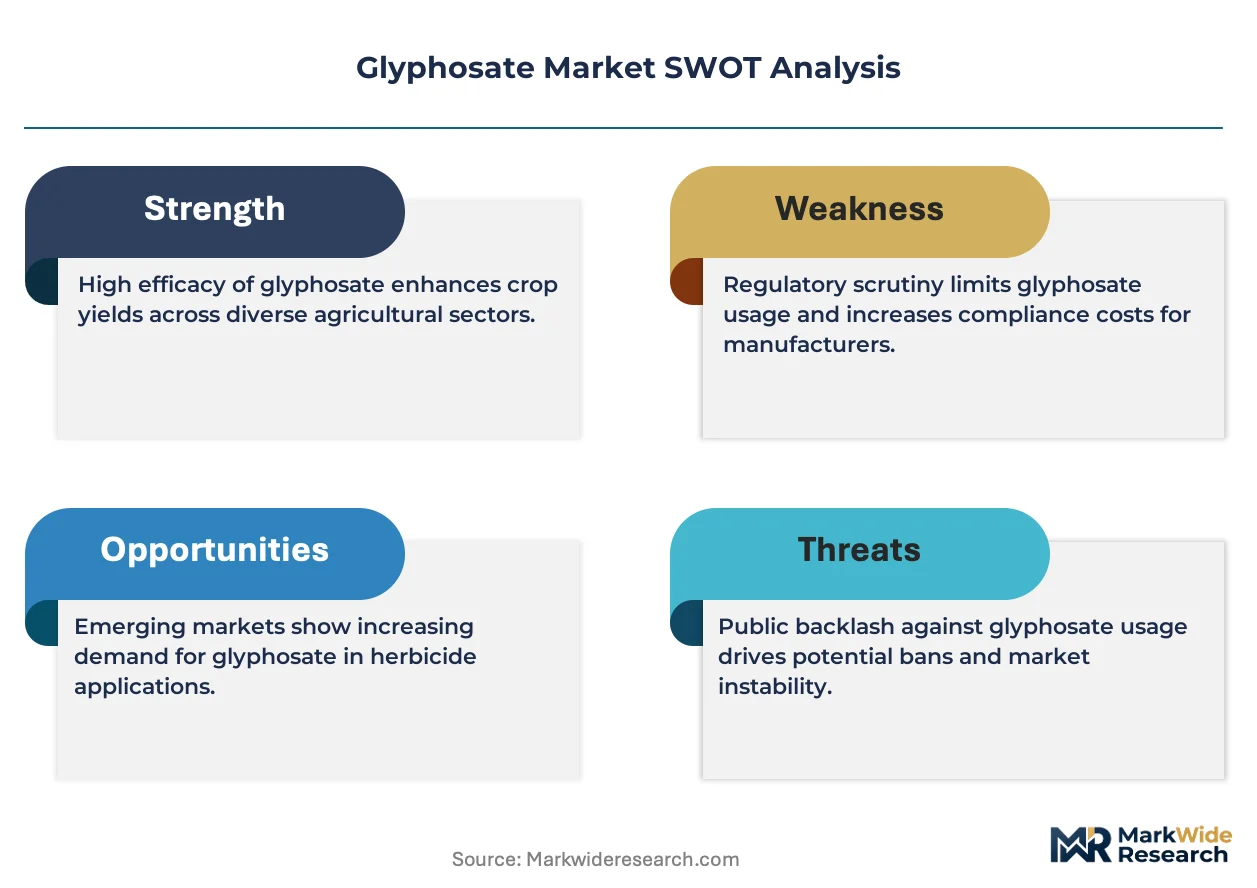
EU Green Deal chemical sustainability targets are rebalancing registration costs for generic manufacturers against incumbent formulators, forcing capital reallocation toward co-formulant safety testing and buffer-zone compliance infrastructure.
Growth Catalysts
- Genetically modified seed adoption:Soybean farmers across Brazil, Argentina, and the United States deploy glyphosate-tolerant varieties that enable in-crop broadcast application, locking in herbicide demand.
- ANVISA residue limit harmonization:Brazil's national health surveillance agency aligns maximum residue limits with import market standards, securing export acceptance for soybean and corn shipments.
- No-till farming expansion:Agricultural operations in the U.S. Corn Belt and Mato Grosso state depend on glyphosate-based weed management to eliminate mechanical cultivation.
Market Restraints
- ECHA hazard classification friction:The European Chemicals Agency's phased restriction of glyphosate under carcinogenicity assessments redirects formulation investments toward compliance without revenue recovery.
- Phosphorus feedstock concentration:Technical-grade glyphosate acid production depends on concentrated phosphate rock processing capacity concentrated in specific mining jurisdictions.
- Herbicide resistance proliferation:Weed biotypes resistant to EPSP synthase inhibition spread through continuous monoculture systems, degrading product efficacy and application rates.
Strategic Opportunities
- Co-formulant innovation:Proprietary surfactant systems that reduce aquatic toxicity open differentiation pathways as regulators tighten ecotoxicological standards.
- Resistance-management bundling:Formulated product portfolios combining glyphosate with alternative modes of action capture premium positioning as farmers rotate chemistries.
- Rural distributor consolidation:Independent agricultural retail networks in Brazil's interior states present acquisition targets for integrated supply control.
Industry Challenges
- Co-formulant disclosure compliance:Regulatory bodies demand full ingredient transparency for pollinator risk assessments, extending registration timelines and testing burdens.
- Emission standard retrofitting:China's Ministry of Ecology and Environment enforces dual carbon goals on technical production facilities, requiring capital-intensive scrubber and wastewater upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glyphosate Market |
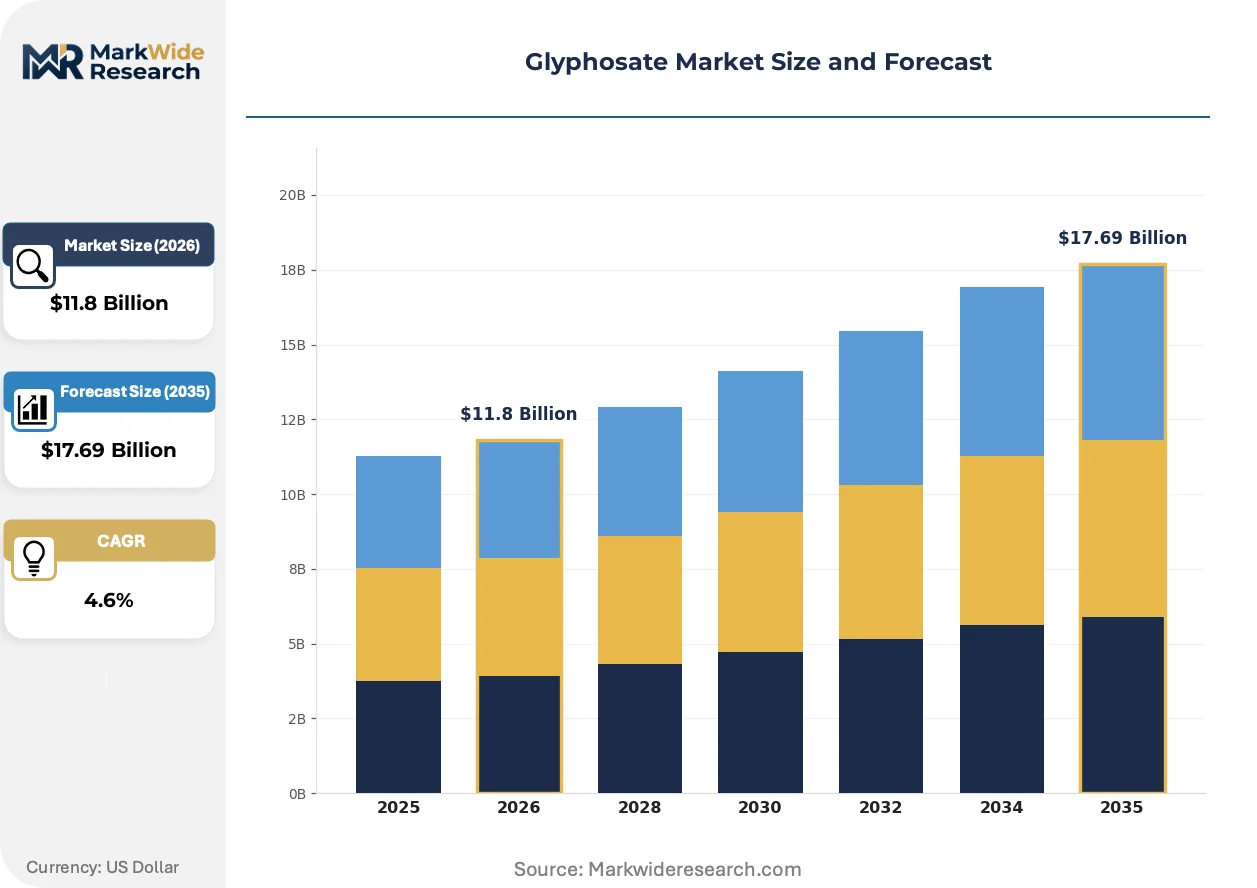
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicide, Adjuvant, Insecticide, Fungicide Application: Agricultural, Non-Agricultural, Forestry, Aquatic Formulation: Liquid, Granular, Powder, Concentrate Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale |
| Companies Covered | Zhejiang Xinan Chemical Industrial Group Co., Ltd., BASF SE, Bayer AG, FMC Corporation, Corteva Agriscience, Syngenta Group, Albaugh, LLC, Zhejiang Wynca Chemical, UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glyphosate Market Emerging Trajectories
Formulation chemistry and application precision are converging to reduce per-hectare active ingredient loads while maintaining weed control efficacy in resistance-prone geographies.
Precision spray application technology is modularizing field operations. Variable-rate nozzles coupled with drone-mounted sensors enable targeted glyphosate deposition on weed patches rather than broadcast coverage. Large-scale farming cooperatives in Brazil's Mato Grosso state pilot these systems to cut chemical volumes. The technology is modularizing equipment procurement decisions, separating sensor hardware from chemical supply contracts.
EPA ecological risk reassessments are tightening aquatic exposure thresholds. The agency's updated endangered species consultations mandate expanded buffer zones around water bodies, directly constraining aerial application windows. Row-crop operators in the Mississippi River watershed face the most restrictive seasonal limitations, driving demand for ground-based precision rigs.
Buyer consolidation among agricultural retailers is compressing procurement cycles. National distributor networks in the United States now negotiate annual glyphosate supply agreements with volume-tiered pricing, displacing spot-market purchases. This concentration is most visible in the U.S. Corn Belt, where three distributor groups control majority storage terminal access.
Glyphosate Market Segmentation
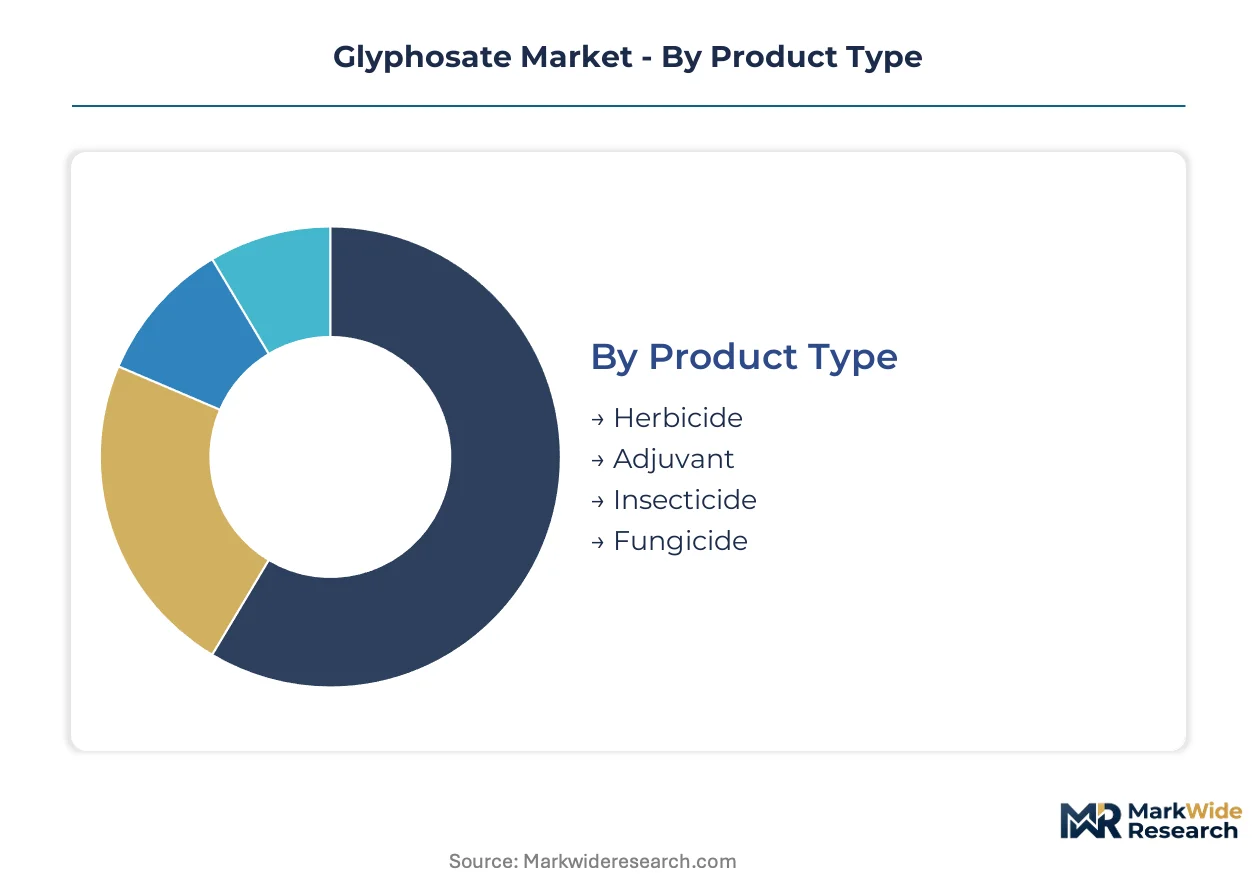
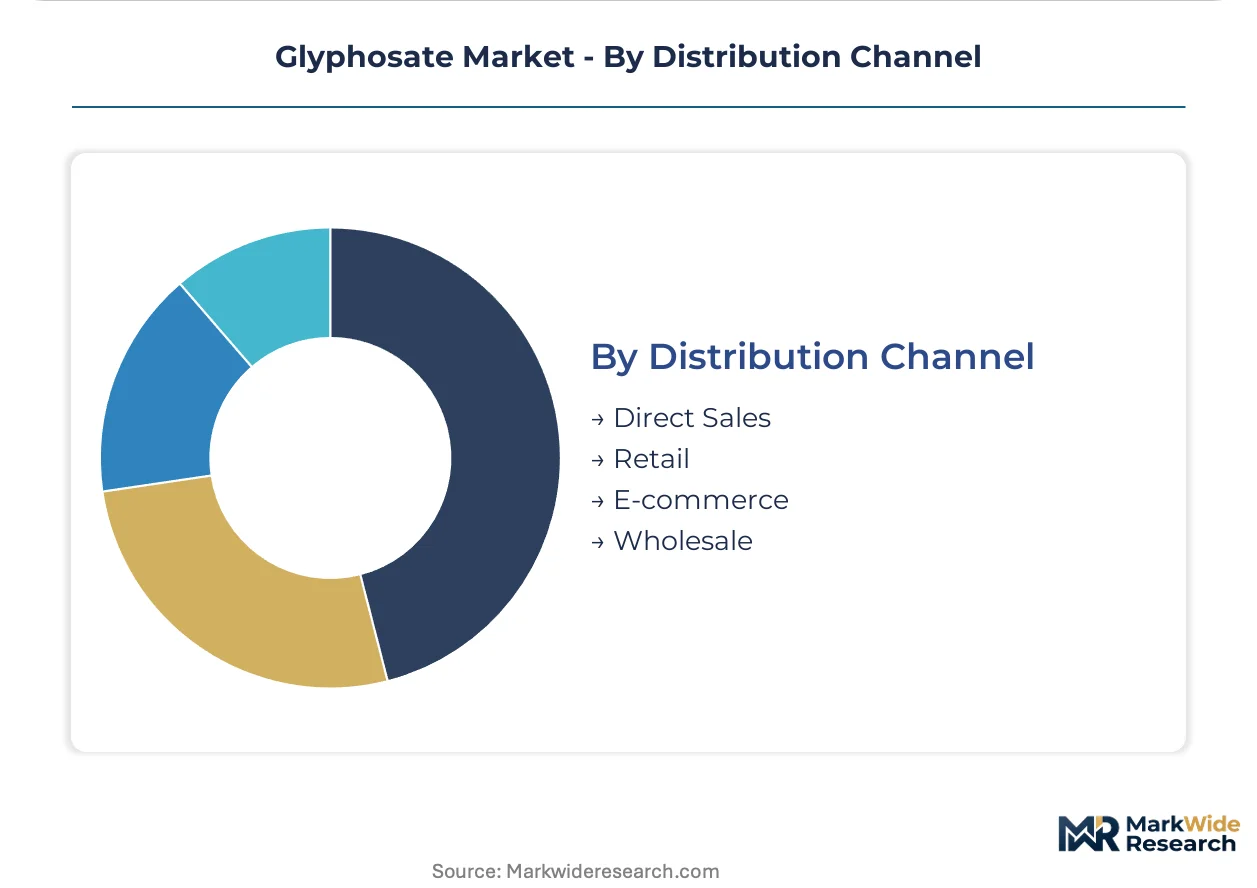
Glyphosate value capture varies sharply across formulation chemistry and distribution pathways. Supply chain configuration determines margin distribution between technical manufacturers, formulators, and agricultural retailers.
Product Type:
Manufacturing concentration in phosphonate chemistry favors herbicide-active producers with backward integration into glyphosate acid.
- Herbicide:Formulations containing glyphosate acid as the active ingredient dominate commercial volumes. Demand concentrates in Brazil's Mato Grosso soybean belt and the U.S. Corn Belt, where no-till systems require broadcast weed control. EPSP synthase inhibition remains the primary mode of action for row-crop vegetation management.
- Adjuvant:Surfactant and drift-control additives that enhance glyphosate uptake and deposition. Tank-mix compatibility drives specification in aerial application contracts across Argentina's Pampas region. Proprietary adjuvant systems differentiate formulators facing ECHA co-formulant disclosure requirements.
- Insecticide:Bundled crop protection products combining glyphosate with insect-active chemistries for single-pass application.
- Fungicide:Disease-control agents paired with glyphosate in resistance-management protocols.
Herbicide absorbs the bulk of installed capacity; adjuvant is expanding most quickly as regulators tighten ecotoxicological standards for co-formulants.
Application:
End-use economics separate high-volume agricultural procurement from premium-priced specialty channels.
- Agricultural:Row-crop and specialty crop operations consuming formulated glyphosate for pre-plant burndown and in-crop weed control. Soybean, corn, and cotton systems in Brazil, Argentina, and the United States lock in recurring demand through genetically modified seed adoption. ANVISA residue limit harmonization secures export market access for Brazilian soybean shipments.
- Non-Agricultural:Industrial vegetation management along rights-of-way, railroad corridors, and utility infrastructure. Specialized high-concentrate formulations command premium pricing through distributor networks serving municipal and industrial buyers.
- Forestry:Site preparation and release treatments in plantation timber operations.
- Aquatic:Submerged and emergent weed control in irrigation systems and water management districts.
Agricultural channels sustain the deepest margin pools; non-agricultural applications generate the steepest pricing premiums per liter of active ingredient.
Formulation:
Equipment compatibility and handling economics drive farmer preference between liquid and dry delivery systems.
- Liquid:Ready-to-use and soluble concentrate formulations compatible with aerial and ground spray equipment. Large-scale farming cooperatives in Brazil's Mato Grosso state favor liquid glyphosate for variable-rate application through self-propelled sprayers. Tank-mix flexibility with adjuvants and companion chemistries supports formulation dominance.
- Granular:Dry dispersible granules for specific aquatic and forestry applications requiring controlled release.
- Powder:Wettable powder formulations for specialized industrial vegetation management.
- Concentrate:High-load acid equivalents reducing transportation cost per unit active ingredient.
Liquid formulations lead volume throughput; concentrate formats are climbing the fastest as freight economics reshape procurement decisions.
Distribution Channel:
Channel power is consolidating around national distributor networks with storage terminal access and credit capacity.
- Direct Sales:Manufacturer-to-farmer contracts for large cooperative and plantation operators. Volume-tiered pricing agreements displace spot-market purchases among corn and soybean growers in the U.S. Corn Belt. Direct relationships enable formulation customization for resistance-management protocols.
- Retail:Independent agricultural dealers and farm supply stores serving mid-scale operators. Rural distributor consolidation in Brazil's interior states presents acquisition targets for integrated supply control.
- E-commerce:Digital procurement platforms emerging for specialty and smaller-volume purchases.
- Wholesale:Bulk supply to regional distributors and formulators without captive manufacturing.
Direct sales capture the largest contract values; retail networks are gaining share fastest through distributor consolidation and credit bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Brazil's interior and China's coastal chemical corridors concentrate glyphosate formulation capacity. Agricultural demand clusters follow genetically modified seed adoption curves.
United States
Soybean and corn growers across Iowa, Illinois, and Indiana drive bulk procurement through direct sales contracts. EPA ecological risk reassessments mandate expanded buffer zones around water bodies, constraining aerial application windows in the Mississippi River watershed. Precision spray cooperatives in Mato Grosso pilot variable-rate systems that reduce per-hectare active ingredient loads.
Brazil
ANVISA residue limit harmonization secures export market access for soybean shipments from Mato Grosso and Goiás states. The national health surveillance agency aligns maximum residue limits with EU and Chinese import standards. Large-scale farming cooperatives in Brazil's interior states consolidate procurement through volume-tiered annual agreements.
China
Zhejiang and Jiangsu provinces host the world's largest glyphosate technical manufacturing facilities. MEE emission standards enforce dual carbon goals on production facilities, requiring capital-intensive scrubber and wastewater upgrades. Technical-grade acid output supplies global formulators through captive export channels.
Argentina
Pampas region soybean operations deploy glyphosate-tolerant varieties across continuous monoculture systems. The country's national agricultural regulator monitors herbicide resistance proliferation through field surveillance programs. Tank-mix adjuvant specifications dominate aerial application contracts in Buenos Aires and Córdoba provinces.
Germany
ECHA hazard classifications under REACH trigger phased restriction timelines for glyphosate formulations. Bayer AG anchors European supply through backward integration into glyphosate acid production and proprietary surfactant systems. Formulation investments redirect toward co-formulant safety testing and buffer-zone compliance infrastructure.
Glyphosate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and technical manufacturing tiers. The vendor base separates into three strategic archetypes: integrated agrochemical conglomerates with captive acid production, regional formulators sourcing technical grade inputs, and generic manufacturers competing on manufacturing scale. Dominant competitive moves include backward integration into glyphosate acid production and proprietary surfactant system development.
Among Chinese technical manufacturers, Zhejiang Xinan Chemical Industrial Group Co., Ltd. and Zhejiang Wynca Chemical occupy positions exemplifying scale-driven production archetypes. Bayer AG and BASF SE represent the integrated conglomerate tier with European headquarters and formulation specialization. These anchors illustrate how competitive positioning splits between manufacturing-scale efficiency and proprietary chemistry differentiation.
| Leading Market Players |
|---|
| Zhejiang Xinan Chemical Industrial Group Co., Ltd. |
| BASF SE |
| Bayer AG |
| FMC Corporation |
| Corteva Agriscience |
| Syngenta Group |
| Albaugh, LLC |
| Zhejiang Wynca Chemical |
| UPL Limited |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap formulators in Brazil's interior states and sovereign-backed Chinese technical manufacturers anchor divergent pricing disciplines across the glyphosate value chain. Their capital structures shape inventory holding patterns and contract tenor preferences that ripple through agricultural procurement cycles.
Pricing Analysis
Short lead-time premiums attach to spot inventory purchases during Brazil's compressed planting windows, while annual contract discounts reward U.S. Corn Belt cooperatives with predictable offtake volumes. Three-tier pricing structure across premium, standard, and economy levels separates proprietary surfactant formulations from generic acid equivalents and bulk technical imports. Pricing pressure stems from distributor consolidation in Mato Grosso, where volume-tiered negotiations compress formulator margins. Mid-scale Brazilian soybean operators exhibit acute price sensitivity, whereas industrial rights-of-way buyers absorb premium formulations with limited elasticity.
Supply Chain Analysis
Empty container return flows and formulation tank refurbishment circuits reduce per-unit packaging costs for liquid glyphosate distributors serving Argentina's Pampas region. Manufacturing gravity centers on China's Zhejiang and Jiangsu provinces, with secondary formulation nodes in Brazil's São Paulo state and Germany's Ludwigshafen chemical corridor. Technical-grade glyphosate acid production draws from concentrated phosphate rock processing and dialkyl phosphite feedstocks. Single-source vulnerability concentrates in China's MEE-regulated technical facilities facing dual carbon compliance deadlines. Distribution runs through national retailer networks with captive storage terminal access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision spray technology is displacing broadcast application equipment, compressing per-hectare chemical volumes while raising sensor and nozzle hardware requirements. This transition phase rewards formulators who bundle application advisory services with product supply.
For Market Incumbents: Acquire rural distributor networks in Brazil's Goiás and Mato Grosso states to lock in volume-tiered procurement relationships. Integrate backward into glyphosate acid production to offset margin compression from generic technical imports. Resistance-management bundling with alternative chemistries defends positioning against herbicide-tolerant weed biotype proliferation. For New Entrants and Emerging Players: Begin with co-formulant innovation targeting ECHA disclosure compliance and aquatic toxicity reduction. White-space concentrates in proprietary surfactant systems for European buffer-zone restrictions and drone-compatible low-drift formulations. Direct sales to precision spray cooperatives in Brazil bypass consolidated retail networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor Chinese technical manufacturers facing MEE emission retrofit capital calls in Jiangsu province. Five-to-ten year viability hinges on dual carbon goal adaptation and captive export channel preservation. Monitor ANVISA residue limit alignment with EU standards as inflection signal for Brazilian export volume sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid Production | Bayer AG's captive glyphosate acid supply insulates margin from Chinese technical price volatility. |
| Co-formulant Safety Certification | ECHA REACH compliance investments open differentiated positioning in restricted European application windows. |
| Precision Spray Technology Partnership | Variable-rate nozzle integration with Mato Grosso cooperatives reduces per-hectare active ingredient volumes. |
| Rural Distributor Acquisition | Consolidated retail networks in Brazil's interior states enable volume-tiered annual contract negotiation. |
| Resistance-Management Bundling | Formulated portfolios combining glyphosate with alternative modes of action capture premium farmer rotation demand. |
Methodological Framework
Document review covered customs trade databases, ANVISA regulatory filings, and SEC 10-K disclosures, complemented by interviews with glyphosate plant managers, agricultural cooperative procurement leads, Brazilian distribution channel partners, and ECHA regulatory affairs specialists. Secondary validation drew from EPA ecological risk assessments, China's MEE emission standards, and Brazilian soybean export documentation. Bottom-up field-level demand estimates and top-down technical manufacturing capacity assessments underwent cross-triangulation.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between genetically modified seed adoption curves, formulation chemistry transitions, and distributor consolidation patterns. Segmentation dimensions included product type, application channel, formulation format, and regional production hub clustering. CAGRs derived from regression analysis against planted acreage forecasts and resistance-management protocol penetration. Industry-specific inputs incorporated ANVISA residue limit harmonization timelines and EPA endangered species consultation outcomes.
Underlying measurement precision varies by segment; liquid herbicide formulations in Brazil and the United States carry tighter precision than granular aquatic applications in fragmented municipal markets. Forecasts embed assumptions regarding ECHA restriction phase-in schedules and MEE enforcement consistency. Material deviation in Chinese dual carbon policy implementation or ANVISA-EU residue alignment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Global Agricultural Fumigants Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market