
 Plant Activator Market | 2026-2036
Plant Activator Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Activator Market Analytics
Biological active ingredients derived from chitosan and microbial fermentation are hardening cost competitiveness against synthetic analogs in row-crop applications. Syngenta Group leverages its integrated seed-treatment pipeline to bundle microbial activators with proprietary germplasm. BASF SE anchors European supply through captive fermentation capacity at its Ludwigshafen complex. UPL Limited competes on price through backward integration into Indian-sourced natural extracts.
Plant activators are biologically active compounds or microbial formulations that trigger induced systemic resistance (ISR) or systemic acquired resistance (SAR) pathways in plants, typically applied at concentrations between 0.1–2.0 g/L active ingredient depending on crop and stress target. Their primary commercial purpose is to reduce yield losses from biotic and abiotic stress without direct pesticidal toxicity, thereby preserving pollinator populations and export market access. Microbial and biochemical product types command expanding acreage as residue-conscious European retailers tighten produce specifications. Synthetic formulations still dominate volume in broad-acre cereals where cost per hectare governs procurement decisions. Natural extracts occupy niche premium positions in organic-certified supply chains with limited price elasticity.
EPA biopesticide registration requirements under FIFRA Section 3(c)(5) shape product development timelines and label claims for US market entry, while REACH compliance governs active substance authorization across EU member states. India's Central Insecticides Board mandates separate registration for microbial strains under the Insecticides Act, creating dual-track regulatory complexity for multinational portfolios. Stakeholders must monitor divergence between EPA fast-track biopesticide pathways and EU precautionary data requirements, as this regulatory asymmetry will determine which product portfolios achieve scalable geographic deployment.
Market Dynamics
Biological plant activators are hardening cost competitiveness against synthetic analogs as EPA fast-track biopesticide pathways compress registration timelines and Indian state-level organic farming missions redirect procurement from chemical inputs.
Growth Catalysts
- EPA FIFRA Section 3(c)(5) fast-track pathways:Accelerated biopesticide registration timelines are enabling microbial and biochemical formulations to reach California specialty crop producers ahead of conventional synthetic alternatives.
- India's FSSAI-aligned residue limits:Maharashtra and Gujarat state organic farming missions are mandating procurement shifts toward biochemical and microbial plant activators in export-oriented horticulture.
- Chitosan fermentation scale-up:Advances in microbial fermentation capacity are reducing production costs for biological active ingredients in row-crop applications.
Market Restraints
- Dual-track regulatory complexity:India's Central Insecticides Board mandates separate microbial strain registration under the Insecticides Act, fragmenting multinational portfolio deployment.
- Fermentation input cost volatility:Molasses and nitrogen source price swings compress margins for biological plant activator manufacturers dependent on Indian-sourced natural extracts.
- Synthetic cost-per-hectare dominance:Broad-acre cereal producers in price-sensitive geographies maintain procurement preference for synthetic formulations despite residue concerns.
Strategic Opportunities
- EU REACH compliance arbitrage:Divergence between EPA biopesticide pathways and EU precautionary data requirements creates portfolio deployment advantages for firms with parallel regulatory capabilities.
- Seed-treatment bundling convergence:Integration of microbial activators with proprietary germplasm pipelines is opening acreage in high-value specialty crop segments.
- Organic-certified supply chain premiums:Natural extract formulations command price inelastic positioning in residue-conscious European retail produce specifications.
Industry Challenges
- ISR/SAR pathway validation expertise:Shortage of plant pathologists capable of documenting induced systemic resistance and systemic acquired resistance mechanisms under EPA and ECHA data requirements.
- Multi-jurisdiction label harmonization:Divergent residue limit definitions between FSSAI, EFSA, and EPA complicate single-product global deployment strategies.
- Microbial strain stability at scale:Maintaining fermentation viability across captive Ludwigshafen-type complexes and contract manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Activator Market |
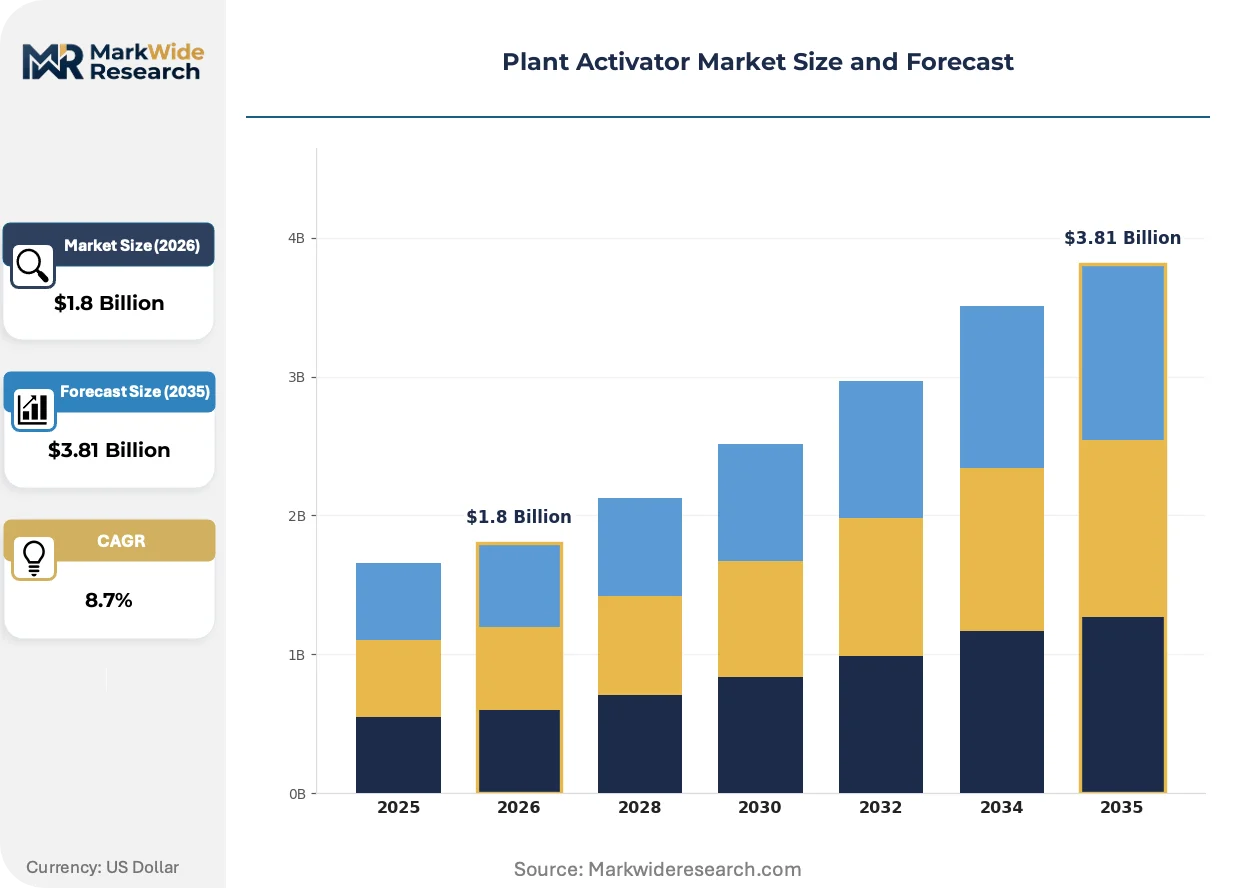
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Biochemical, Natural Extracts, Synthetic Active Ingredient: Acibenzolar-S-methyl, Salicylic Acid, Chitosan, Fulvic Acid Application: Crop Protection, Soil Health, Stress Response, Yield Enhancement Distribution Channel: Online, Retail, Distributors, Farm Supply Stores |
| Companies Covered | Syngenta Group, BASF SE, Bayer AG, UPL Limited, Sumitomo Chemical Co., Ltd, Plant Health Care plc, Isagro S.p.A., Nihon Nohyaku Co., Ltd, Certis USA LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Activator Market Evolving Landscape
Formulation science and regulatory science are converging to compress development cycles, while buyer procurement criteria harden around residue documentation and pollinator safety certification.
RNA interference and peptide-based plant activators are consolidating around seed-treatment application methods as Syngenta-type integrated pipelines bundle microbial strains with proprietary germplasm. Specialty crop producers in California's Central Valley are adopting these bundled offerings at accelerating pace. The technology is consolidating supplier power around germplasm-activator combinations that lock in multi-season procurement contracts.
REACH active substance authorization requirements are tightening data packages for biochemical plant activators seeking EU market entry. ECHA's precautionary stance on microbial strain metabolite characterization is extending development timelines relative to EPA fast-track pathways. Biochemical formulations targeting European export markets are responding by front-loading toxicology and ecotoxicology studies ahead of US registration.
Retailer-driven residue specifications are compressing switching cycles for specialty crop producers supplying European supermarkets. Procurement departments at major UK and German retail chains are unbundling after-sales agronomic support from product supply, demanding standalone residue certification. This pattern is most visible in Maharashtra and Gujarat export-oriented grape and pomegranate operations seeking FSSAI-EU dual compliance.
Plant Activator Market Segmentation
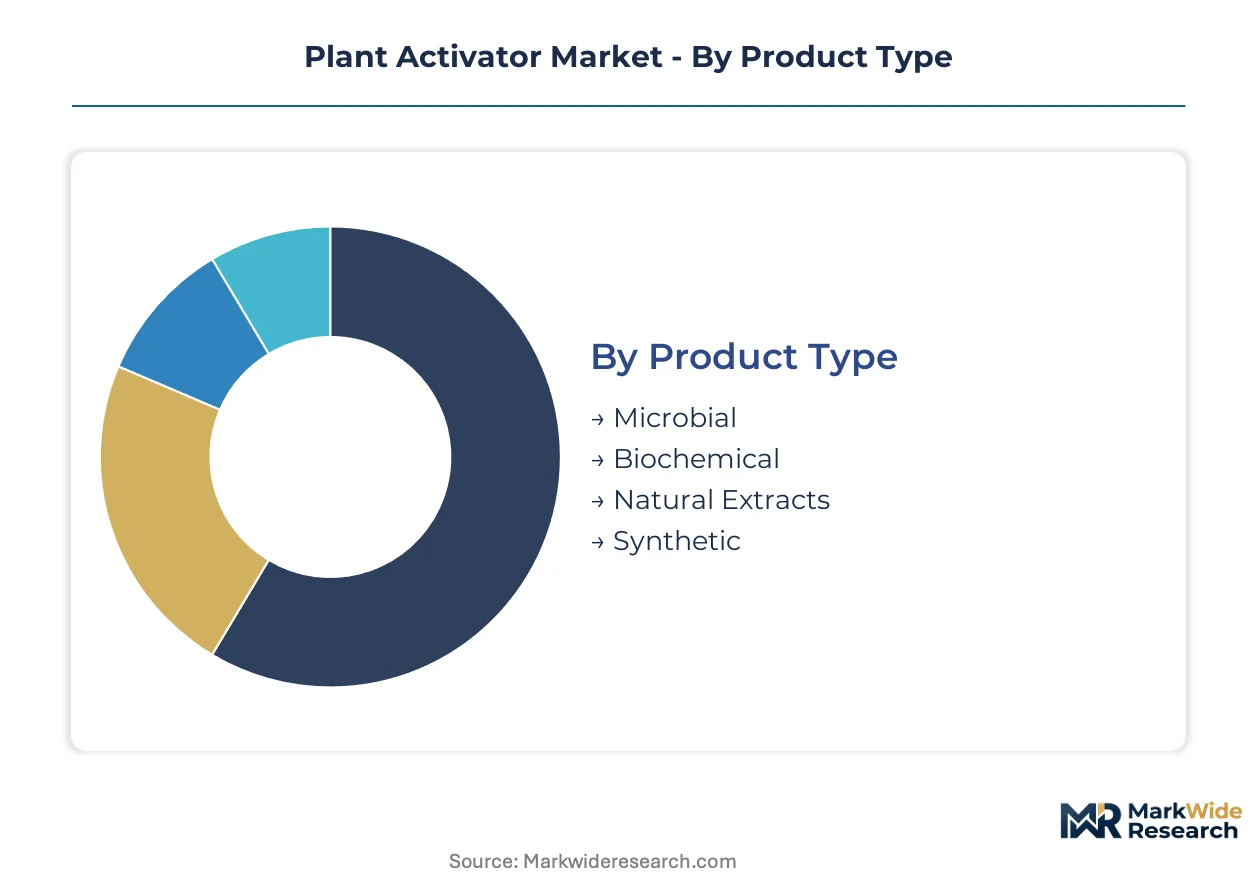
Plant activator procurement splits between standalone foliar applications and integrated seed-treatment systems, with regulatory registration pathways determining which product architectures achieve scalable deployment. Segmentation clarity enables suppliers to match formulation science with jurisdiction-specific compliance requirements and end-use agronomic protocols.
Product Type:
Microbial and biochemical formulations dominate embedded seed-treatment pipelines, while natural extracts and synthetics serve standalone application markets with distinct residue documentation requirements.
- Microbial:Fermentation-derived bacterial and fungal strains trigger ISR pathways through colonization of root rhizospheres. Demand concentrates in California Central Valley specialty crops where EPA biopesticide fast-track registration enables rapid market entry ahead of synthetic alternatives.
- Biochemical:Chitosan and peptide-based compounds activate SAR signaling without live organism persistence. Maharashtra and Gujarat export-oriented horticulture operations are redirecting procurement toward these formulations to meet FSSAI-aligned residue limits for European supermarket supply chains.
- Natural Extracts:Plant-derived elicitors from seaweed and botanical sources command organic-certified premiums with limited price elasticity.
- Synthetic:Acibenzolar-S-methyl analogs maintain cost-per-hectare advantages in broad-acre cereal production despite pollinator safety scrutiny.
Synthetic formulations lead volumes today; microbial segments are gaining share fastest.
Active Ingredient:
Ingredient selection tracks regulatory data requirements, with microbial metabolites facing divergent characterization standards between EPA and ECHA frameworks.
- Acibenzolar-S-methyl:Synthetic benzothiadiazole compound with established SAR pathway documentation. Dominates conventional row-crop applications where registration data packages predate modern biopesticide pathways.
- Salicylic Acid:Endogenous plant hormone mimetic triggering systemic resistance signaling. Expanding adoption in greenhouse vegetable operations seeking same-harvest-interval flexibility.
- Chitosan:Deacetylated chitin polymer from crustacean shell fermentation. Indian-sourced material supplies cost-competitive feedstock for Ludwigshafen-type captive production complexes.
- Fulvic Acid:Humic substance enhancing nutrient uptake alongside stress priming. Niche positioning in organic viticulture and premium fruit segments.
Acibenzolar-S-methyl anchors current revenue; chitosan climbs the fastest on fermentation scale-up economics.
Application:
Application segmentation reflects agronomic integration depth, from reactive crop protection to predictive yield enhancement protocols.
- Crop Protection:Biotic stress mitigation against fungal and bacterial pathogens through induced resistance priming. California specialty crop producers deploy these protocols to satisfy export phytosanitary certification without synthetic pesticide residues.
- Soil Health:Microbial inoculants improving rhizosphere biology and nutrient cycling. Adoption concentrates in Gujarat organic farming mission zones transitioning from chemical-intensive cotton systems.
- Stress Response:Abiotic stress priming against drought, heat, and salinity. Expanding acreage in Maharashtra grape and pomegranate operations facing climate volatility.
- Yield Enhancement:Growth promotion and fruit quality optimization beyond stress protection. Premium positioning in export-oriented supply chains with supermarket residue specifications.
Crop protection commands current acreage; soil health applications show steepest expansion trajectory.
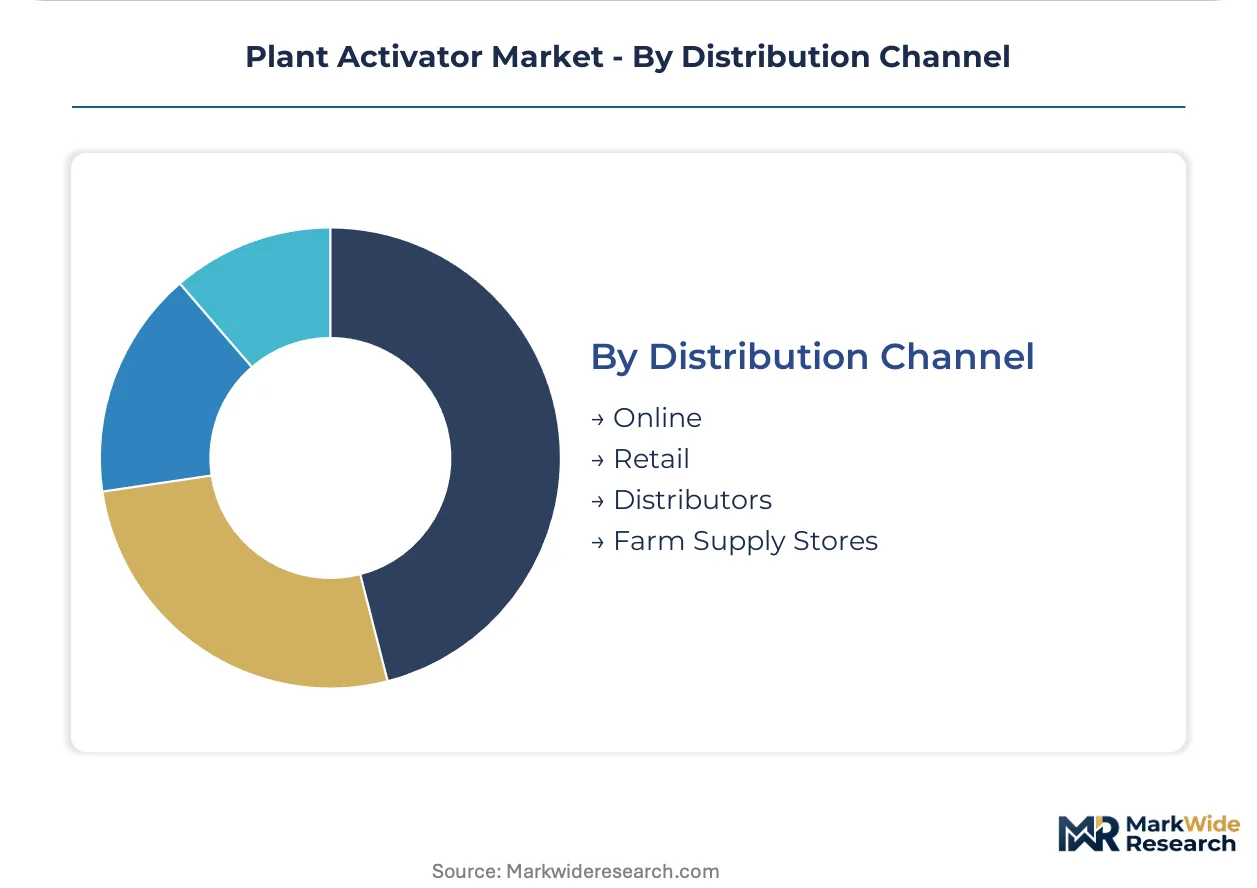
Distribution Channel:
Channel structure mirrors buyer sophistication segmentation, with bundled agronomic support separating distributor networks from transactional retail.
- Distributors:Technical sales networks providing application training and residue documentation support. Anchor channel for Maharashtra and Gujarat export-oriented operations requiring FSSAI-EU dual compliance verification.
- Farm Supply Stores:Local agronomic retailers serving conventional broad-acre producers with established synthetic procurement relationships.
- Online:Direct-to-grower platforms gaining traction in smallholder organic segments with certification transparency requirements.
- Retail:Mass-market garden center channels for hobbyist and small-scale horticulture applications.
Distributor networks dominate commercial volumes today; online channels are expanding most quickly in certified organic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley anchors procurement intensity for biological plant activators, with specialty crop producers expanding acreage under EPA biopesticide registration pathways. Regulatory divergence between jurisdictions is reshaping supplier deployment priorities across major agricultural economies.
United States
California specialty crop producers drive biological activator procurement to satisfy export phytosanitary requirements. EPA FIFRA Section 3(c)(5) fast-track pathways compress registration timelines for microbial formulations. Fresno and Kern County operations are transitioning from synthetic inputs toward chitosan-based SAR triggers for stone fruit and nut exports.
Germany
REACH active substance authorization requirements tighten data packages for biochemical formulations seeking EU market entry. ECHA's precautionary stance on microbial metabolite characterization extends development timelines relative to US pathways. Ludwigshafen-based captive fermentation capacity anchors European supply for row-crop biologicals.
India
Maharashtra and Gujarat export-oriented horticulture operations redirect procurement toward biochemical formulations. FSSAI-aligned residue limits and state-level organic farming missions mandate shifts from synthetic crop inputs. Nashik grape and pomegranate clusters are adopting microbial ISR triggers for dual EU-FSSAI compliance.
Brazil
Soybean and corn producers in Mato Grosso and Paraná are expanding biological activator trials amid pollinator safety scrutiny on conventional pesticides. ANVISA registration pathways for microbial strains create parallel approval tracks distinct from synthetic agrochemicals. Campinas research clusters are validating chitosan fermentation scale-up for tropical row-crop applications.
China
Domestic producers in Shandong and Jiangsu provinces are scaling microbial fermentation capacity for chitosan and peptide-based active ingredients. MEE environmental compliance standards are tightening discharge requirements for biological manufacturing facilities. Yangtze River Delta agrochemical clusters are integrating plant activator production with existing biopesticide infrastructure.
Plant Activator Market Competitive Landscape
Global majors compete with regional champions across regulatory science capabilities and fermentation scale. The market structures around three tiers: integrated agrochemical conglomerates with seed-treatment pipelines, specialized biological firms with microbial strain libraries, and regionally anchored extract processors leveraging local sourcing. Consolidation pressures concentrate among mid-scale fermentation operators lacking captive germplasm partnerships. Dominant competitive moves include backward integration into natural extract supply and parallel EPA-ECHA regulatory team builds.
Within the integrated agrochemical tier, Syngenta Group and BASF SE occupy positions defined by seed-treatment bundling capabilities and captive fermentation infrastructure. UPL Limited exemplifies regional champion strategy through Indian-sourced natural extract backward integration. These three anchors represent divergent pathways: germplasm-activator convergence, European REACH compliance scale, and price-competitive biochemical supply.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer AG |
| UPL Limited |
| Sumitomo Chemical Co., Ltd |
| Plant Health Care plc |
| Isagro S.p.A. |
| Nihon Nohyaku Co., Ltd |
| Certis USA LLC |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between residue-conscious European retail specifications and price-sensitive broad-acre cereal procurement manifests in divergent pricing architectures and supply chain configurations. Premium biochemical formulations command captive fermentation capacity at Ludwigshafen-type complexes, while commodity synthetic analogs flow through distributed contract manufacturing networks.
Pricing Analysis
Input-cost pass-through from molasses and nitrogen source volatility compresses margins for biological plant activator manufacturers dependent on Indian-sourced natural extracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier and after-sales agronomic support bundling. Pricing pressure stems from synthetic cost-per-hectare dominance in broad-acre cereals, with Maharashtra and Gujarat export-oriented operations showing least price sensitivity due to FSSAI-EU dual compliance premiums.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Campinas, and the Yangtze River Delta anchor hub-and-spoke patterns for microbial fermentation outputs. Supply concentration centers on Germany, India, and China for chitosan feedstock and peptide-based active ingredients. Raw material dependencies include crustacean shell waste, molasses carbon sources, and nitrogen-rich fermentation media. Single-source vulnerability runs through Indian-sourced natural extract supply chains. Distribution runs through technical distributor networks providing residue documentation support for export-oriented horticulture operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA fast-track biopesticide pathways compressing US registration timelines and ECHA precautionary data requirements extending EU development cycles.
For Market Incumbents: To counter regulatory asymmetry fragmenting multinational portfolio deployment, incumbents should build parallel EPA-ECHA regulatory science capabilities and anchor captive fermentation capacity in REACH-compliant jurisdictions. Backward integration into Indian-sourced natural extracts defends margin position against input-cost volatility. For New Entrants and Emerging Players: Enter via Maharashtra and Gujarat state organic farming mission zones where FSSAI-aligned procurement mandates create white-space demand for biochemical formulations. Target online direct-to-grower channels in certified organic segments with certification transparency requirements, bypassing established distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fermentation operators lack captive germplasm partnerships and parallel regulatory capabilities. Long-term viability hinges on seed-treatment bundling convergence and residue-documentation expertise. Acquisition targets include specialized biological firms with microbial strain libraries and EPA-ECHA dual-track registration experience. The signal to watch is divergence between EPA biopesticide approval velocity and ECHA metabolite characterization requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Scale-Up | Ludwigshafen-type complexes anchor European REACH compliance for biological active ingredient supply. |
| Seed-Treatment Bundling Convergence | Syngenta-type integrated pipelines lock in multi-season procurement contracts through germplasm-activator combinations. |
| Parallel Regulatory Team Build | Dual EPA-ECHA capabilities arbitrage registration timeline divergence for scalable geographic deployment. |
| Backward Integration into Natural Extracts | UPL-type Indian sourcing strategies compress feedstock costs for price-competitive biochemical formulations. |
| Residue Documentation Infrastructure | Standalone certification capabilities satisfy unbundled procurement demands from UK and German retail chains. |
Research Methodology
Bottom-up acreage modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors at agrochemical firms, technical sales leads at distributor networks, and procurement officers at Maharashtra and Gujarat export cooperatives combined with secondary validation from EPA biopesticide registration databases, ECHA active substance authorization records, and FSSAI residue limit notifications. Trade data from Indian DGFT export filings and EU import certification records anchored supply-side triangulation.
Historical trendline analysis of biological versus synthetic activator procurement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, active ingredient class, application protocol, and distribution channel structure. CAGRs derived from weighted average of acreage expansion rates and price trajectory assumptions. Industry-specific forecast inputs incorporated EPA registration pipeline velocity and state-level organic farming mission budget allocations.
Inputs from regulatory filing databases and trade statistics were available through the study window; gaps in real-time microbial strain stability performance data introduce uncertainty bands around fermentation scale-up assumptions. Forecasts reflect documented assumptions regarding EPA-ECHA regulatory divergence persistence and residue specification tightening trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Organic Bromide Market