
 Spain Greenhouse Horticulture Market | 2026-2036
Spain Greenhouse Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Greenhouse Horticulture Market Insights
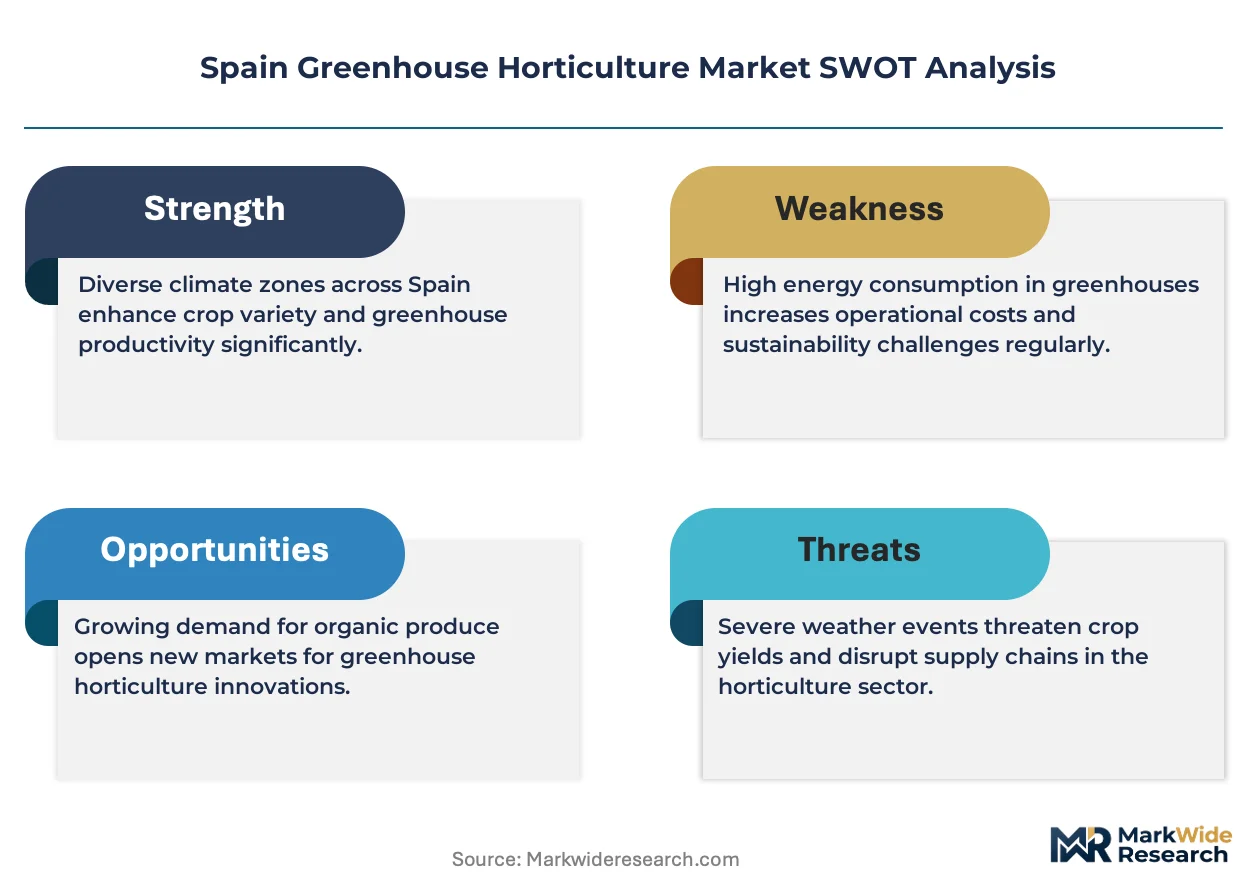
Almería's grower cooperative network is pivoting toward semi-closed greenhouse architectures with integrated climate buffers. J. Huete Greenhouses leverages its engineering footprint to dominate turnkey project deliveries across the Levante region. Novagric anchors its position through specialized hydroponic system design for arid-zone vegetable production. Grupo Hortofrutícola Paloma sustains competitive differentiation via backward integration into propagation and varietal trialing.
Greenhouse horticulture in Spain denotes soilless and soil-based crop production within climate-controlled enclosures, typically employing polyethylene or glass glazing with active ventilation, CO2 enrichment, and drip-fed nutrient delivery to achieve yield densities of 30-50 kg per square meter annually for solanaceous vegetables. The primary commercial purpose centers on counter-seasonal supply to Northern European retail chains and domestic fresh-produce markets. Tomatoes and peppers command the dominant product value pools, while hydroponic technology captures the fastest expansion trajectory as water-stressed regions retire flood-irrigated soil beds. Vertical farming remains nascent in Spain, constrained by electricity costs and limited premium channel penetration relative to Dutch or Nordic benchmarks.
Spain's greenhouse sector operates under the EU Green Deal's Farm to Fork strategy, national implementation of the Water Framework Directive, and Andalusian regional codes governing agricultural plastics recycling and phytosanitary discharge. These frameworks are forcing capital replacement cycles toward closed-loop irrigation and renewable-powered climate systems. Coexphal and the broader cooperative federation navigate compliance through pooled investment in collective wastewater treatment and photovoltaic canopy integration. Stakeholders must weigh varietal licensing costs against the margin compression from escalating energy and regulatory compliance expenditures.
Market Dynamics
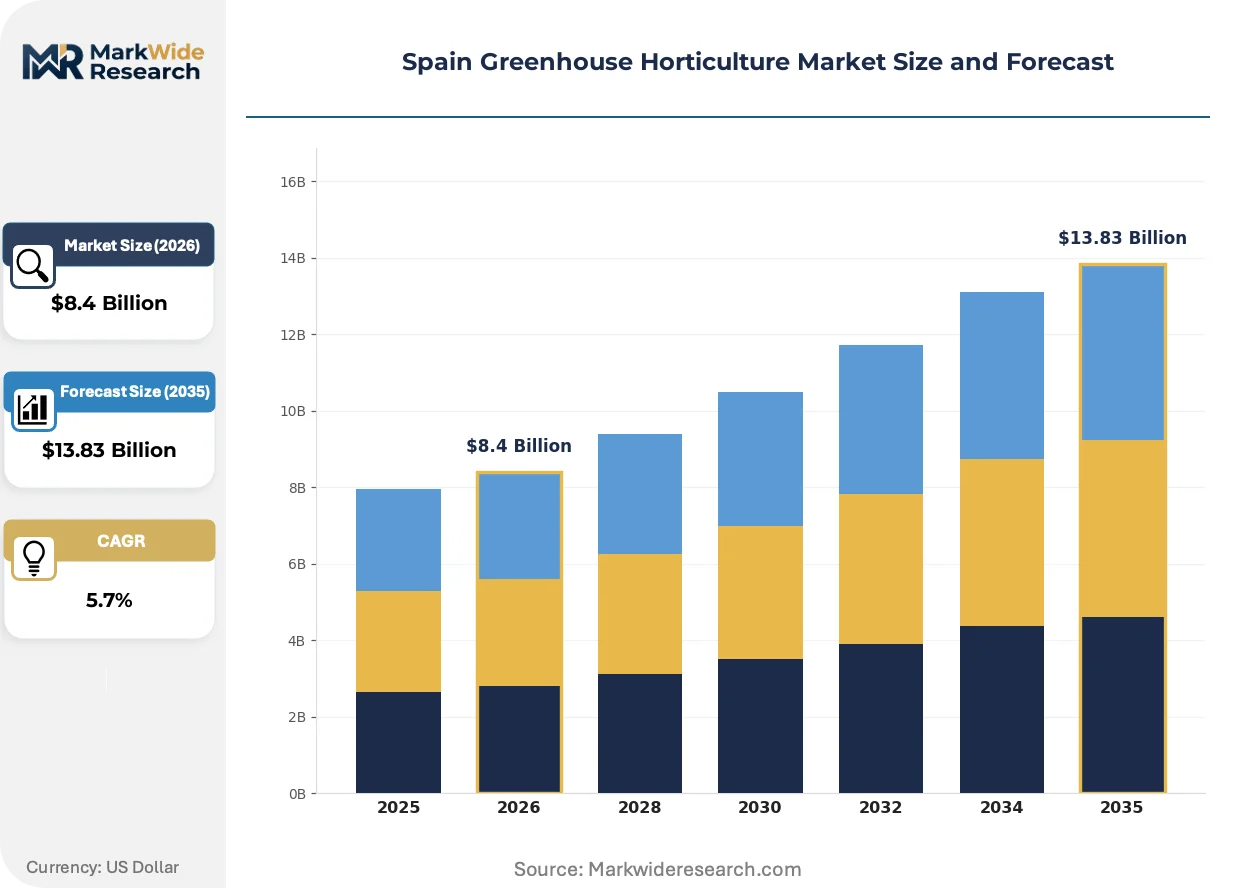
Spain's greenhouse horticulture sector is compressing capital replacement cycles under the EU Green Deal's Farm to Fork mandates, forcing Almería's cooperative networks to pool investment in closed-loop irrigation and photovoltaic canopy integration before regulatory deadlines tighten.
Growth Catalysts
- EU Green Deal water-efficiency mandates:Andalusian operators are accelerating semi-closed greenhouse retrofits to preempt enforcement of the Water Framework Directive's discharge limits.
- Almería port logistics infrastructure:Clustered cold-chain capacity at Almería-Marítima terminal sustains year-round pepper and tomato export volumes to Northern European retail chains.
- Hydroponic substrate systems:Rockwool and coconut coir cultivation is displacing flood-irrigated soil beds across water-stressed Campo de Dalías and Níjar sub-regions.
Market Restraints
- Electricity cost volatility:Natural gas-indexed power tariffs compress operating margins for climate-controlled glasshouse operators in Murcia's Arco Sur belt.
- Phytosanitary input concentration:Three specialized biocide suppliers dominate Spain's protected-crop pesticide channel, exposing growers to price coordination risk.
- Semi-closed architecture technical limits:Humidity buffer design failures in Mediterranean summer conditions restrict adoption to coastal microclimates with reliable sea-breeze ventilation.
Strategic Opportunities
- Andalusian photovoltaic canopy mandates:Regional agricultural plastics recycling codes are creating subsidy pools for solar-integrated greenhouse roofing retrofits.
- Propagation varietal licensing:Backward integration into tomato rootstock trialing captures margin pools currently extracted by Dutch breeding houses.
- Levante region turnkey engineering:Valencia and Alicante provinces present white-space demand for integrated climate-buffer greenhouse construction services.
Industry Challenges
- Climate-system technician scarcity:Andalusia's vocational pipeline produces insufficient HVAC and irrigation automation specialists for semi-closed facility maintenance.
- Cooperative governance complexity:Pooled wastewater treatment investments require alignment across Coexphal member farms with divergent balance-sheet capacities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Greenhouse Horticulture Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tomatoes, Cucumbers, Peppers, Herbs Technology: Hydroponics, Aeroponics, Traditional Soil, Vertical Farming End User: Commercial Growers, Small Scale Farmers, Research Institutions, Cooperative Societies Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesale Markets |
| Companies Covered | J. Huete Greenhouses, Grodi Tech, Novagric, SUNCAN Pharma, VerticalGreen, Enza Zaden, Grupo Hortofrutícola Paloma, Solaris Vita Renovables, Coexphal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Greenhouse Horticulture Market Trends and Innovations
Spanish greenhouse operators are integrating digital climate control with renewable energy architectures to meet tightening EU sustainability verification requirements for fresh produce exports.
Sensor-driven fertigation management is converging with blockchain-based provenance tracking. Large Almería cooperatives are deploying combined hardware-software stacks to automate nutrient dosing while generating audit trails for supermarket ESG compliance. This technology convergence is compressing the cost gap between premium-certified and conventional greenhouse operations.
The EU Green Deal's Farm to Fork strategy is mandating 50% pesticide reduction targets by 2030. Spanish protected-crop operators are responding with biological control agent expansion and pollinator habitat integration. Tomato and pepper propagation facilities face the steepest compliance cost curves due to historical chemical dependency.
Retail procurement is consolidating through direct-contracted acreage programs. German and Dutch supermarket chains are bypassing traditional wholesale markets to lock multi-season supply commitments with Almería grower cooperatives. This channel shift is most visible in cherry tomato and snack pepper categories where shelf-life specifications favor integrated cold-chain partnerships.
Spain Greenhouse Horticulture Market Segmentation
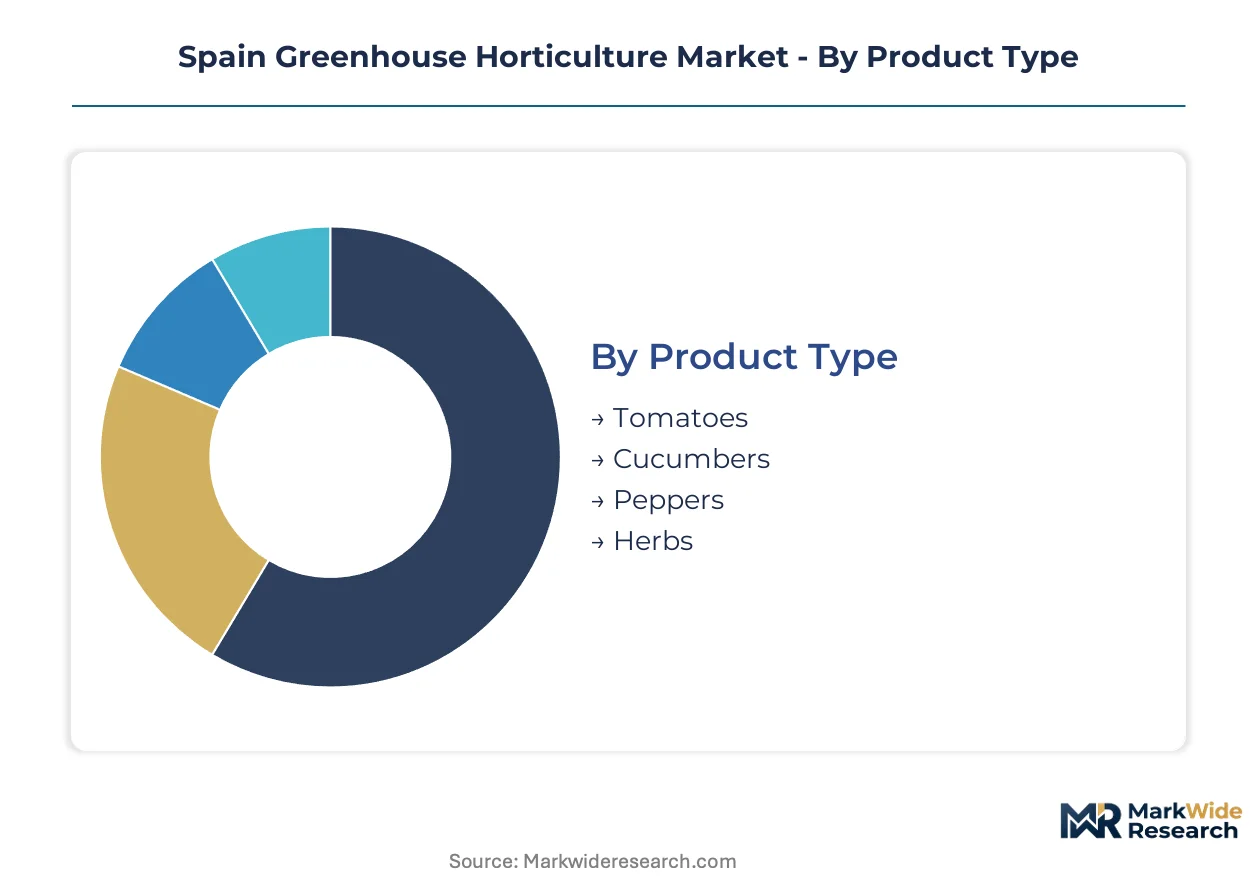
Product differentiation across Spain's greenhouse sector determines capital intensity and export eligibility. Technology choices separate water-stressed Almería operators from Murcia's energy-intensive glasshouse belt. Distribution channel selection locks in margin structure and cold-chain investment requirements.
Product Type:
Standardization dominates tomato and pepper cultivation through supermarket quality protocols, while herbs retain customization flexibility for niche gastronomy channels.
- Tomatoes:Cherry and beefsteak varieties command premium shelf space in German and Dutch retail chains. Almería's Campo de Dalías cluster concentrates 60% of national tomato export volume under integrated cold-chain partnerships with Northern European supermarkets.
- Peppers:Snack pepper categories drive contracted acreage expansion through direct procurement programs. Murcia's Arco Sur belt specializes in red and yellow bell varieties with extended shelf-life specifications for UK and Scandinavian distribution.
- Cucumbers:Standardized length and curvature grades align with wholesale market auction systems.
- Herbs:Basil and coriander cultivation serves domestic gastronomy and pharmaceutical extraction channels with varietal trialing flexibility.
Leading the category by volume: Tomatoes. Growing fastest: Peppers.
Technology:
Cost tier separation runs from photovoltaic-integrated semi-closed systems to flood-irrigated soil beds facing EU Green Deal phase-out.
- Hydroponics:Rockwool and coconut coir substrates enable closed-loop irrigation compliance with Water Framework Directive discharge limits. Campo de Níjar operators are retrofitting 40% of pepper acreage annually to capture subsidy pools for water-efficient infrastructure.
- Traditional Soil:Flood-irrigated beds dominate older greenhouse stock in Granada's Poniente sub-region. Rising energy costs and tightening phytosanitary discharge rules are accelerating abandonment rates among smallholder cooperatives.
- Aeroponics:Mist-based nutrient delivery remains experimental for tomato rootstock propagation in research station trials.
- Vertical Farming:Rack-stacked cultivation is constrained by electricity tariffs above €0.15 per kWh in Mediterranean zones, limiting deployment to R&D facilities near Valencia's polytechnic cluster.
Steepest expansion trajectory: Hydroponics. Largest installed base: Traditional Soil.
End User:
Customer type determines scale economies and compliance burden distribution across Andalusia's cooperative federation structure.
- Commercial Growers:Integrated operations above 10 hectares dominate export volume through direct retail contracts. Coexphal member farms pool wastewater treatment and photovoltaic canopy investments to amortize EU Green Deal compliance costs.
- Cooperative Societies:Federated smallholders share varietal licensing and cold-chain infrastructure. Almería's grower cooperatives negotiate collective supply agreements with German supermarket chains, bypassing traditional wholesale markets.
- Small Scale Farmers:Sub-five-hectare operations concentrate on domestic wholesale auction channels with limited quality certification.
- Research Institutions:CEBAS-CSIC and regional agricultural stations conduct semi-closed architecture trials for humidity buffer optimization.
Highest revenue concentration: Commercial Growers. Fastest policy-driven growth: Cooperative Societies.
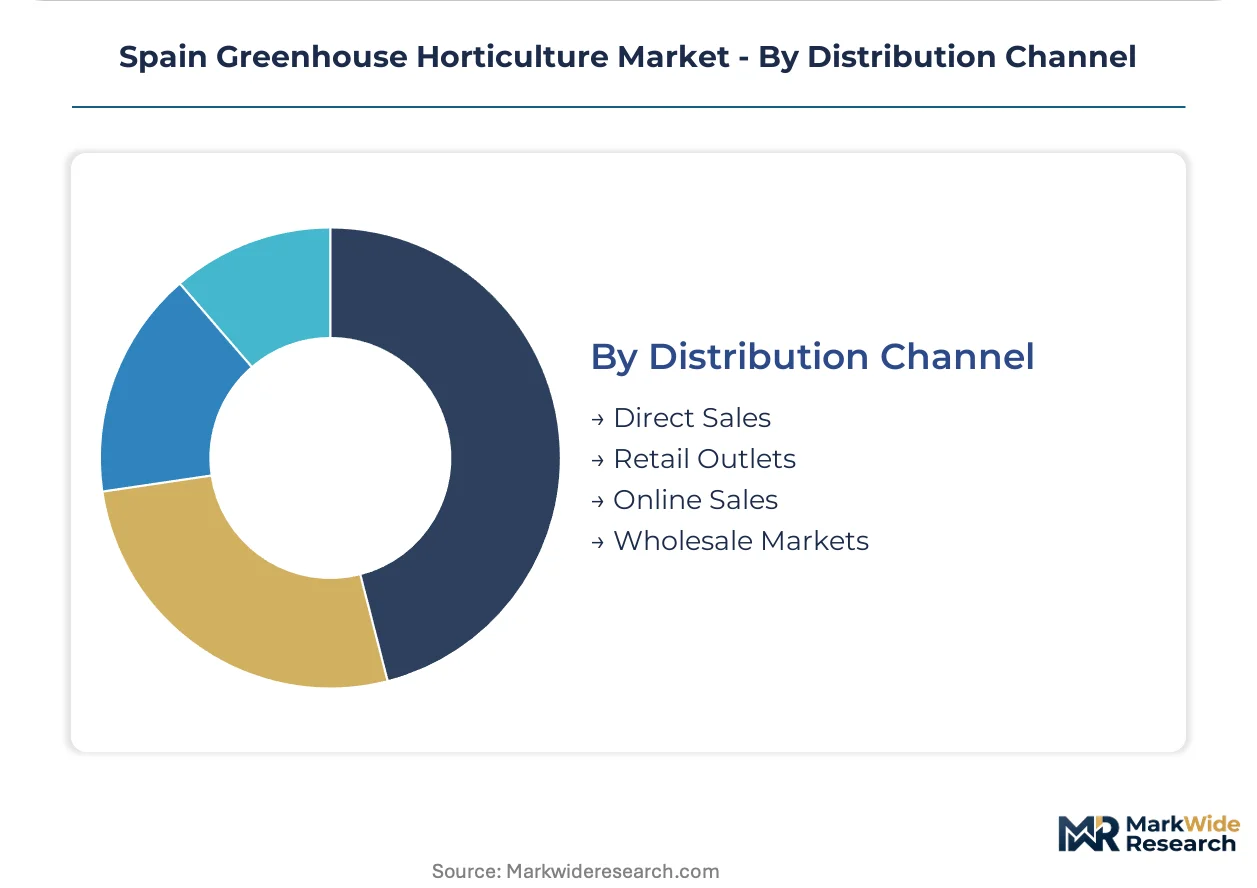
Distribution Channel:
Margin structure diverges between integrated cold-chain partnerships and spot-market wholesale exposure.
- Direct Sales:Contracted acreage programs with Northern European retailers capture 25-30% price premiums over wholesale auction levels. Almería-Marítima terminal logistics enable year-round pepper and tomato supply commitments to Dutch and German chains.
- Wholesale Markets:Mercamadrid and Mercabarna auction systems serve domestic retail and foodservice with price volatility exposure. Smallholder cooperatives without cold-chain integration default to this channel.
- Retail Outlets:Domestic supermarket listings require GLOBALG.A.P. certification and ESG audit trails.
- Online Sales:Direct-to-consumer platforms remain marginal due to perishability constraints and last-mile cost structures.
Dominant volume channel: Wholesale Markets. Fastest margin expansion: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almería's Campo de Dalías anchors Spain's greenhouse concentration through coastal microclimates and integrated port logistics. The province's polyethylene-clad acreage generates the bulk of national tomato and pepper export volumes. Water-stressed soil conditions and EU Green Deal mandates are accelerating technology substitution across Mediterranean growing belts.
Andalusia
Almería's cooperative networks dominate solanaceous vegetable exports through direct retail contracts with German and Dutch chains. The EU Green Deal's Water Framework Directive is forcing pooled investment in closed-loop irrigation infrastructure across Coexphal member farms. Campo de Níjar operators are retrofitting 40% of pepper acreage annually to hydroponic substrates.
Murcia
Arco Sur belt growers specialize in extended-shelf-life bell varieties for UK and Scandinavian distribution channels. Natural gas-indexed electricity tariffs are compressing operating margins for climate-controlled glasshouse operators. Cartagena's logistics corridor supports year-round supply commitments through integrated cold-chain partnerships.
Valencia
Levante provinces present white-space demand for integrated climate-buffer greenhouse construction services. Regional agricultural plastics recycling codes are creating subsidy pools for solar-integrated roofing retrofits. Valencia's polytechnic cluster hosts experimental vertical farming R&D facilities constrained by electricity costs above €0.15 per kWh.
Catalonia
Mercabarna wholesale auction systems serve domestic retail and foodservice with price volatility exposure. Barcelona's gastronomy channels sustain herb cultivation flexibility for basil and coriander varietal trialing. Catalan operators face escalating compliance costs from national phytosanitary discharge regulations.
Madrid
Mercamadrid auction infrastructure connects smallholder cooperatives without cold-chain integration to domestic wholesale markets. Central plateau climatic extremes limit protected cultivation to research station trials. Madrid-based propagation facilities confront the steepest EU Green Deal pesticide reduction compliance curves.
Spain Greenhouse Horticulture Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue semi-closed architecture engineering and photovoltaic integration services. The vendor base separates into turnkey greenhouse constructors, hydroponic system designers, and cooperative federation networks. Three strategic archetypes dominate: engineering-led project deliverers, specialized substrate technology providers, and backward-integrated propagation operators. Competitive moves concentrate on cooperative wastewater treatment pooling and collective photovoltaic canopy investment.
Within the engineering-led tier, J. Huete Greenhouses and Novagric exemplify divergent specialization vectors. J. Huete Greenhouses occupies a position across Levante region turnkey project deliveries. Novagric anchors hydroponic system design for arid-zone vegetable production. Grupo Hortofrutícola Paloma represents backward integration into propagation and varietal trialing within the cooperative federation structure.
| Leading Market Players |
|---|
| J. Huete Greenhouses |
| Grodi Tech |
| Novagric |
| SUNCAN Pharma |
| VerticalGreen |
| Enza Zaden |
| Grupo Hortofrutícola Paloma |
| Solaris Vita Renovables |
| Coexphal |
| Others |
Pricing and Supply Chain Analysis
HVAC and irrigation automation specialists in Andalusia's Campo de Dalías corridor command wage premiums that compress margin spreads between premium-certified and economy-tier greenhouse operations. Labor-cost differentials between Almería's cooperative networks and Murcia's Arco Sur belt operators feed directly into pricing-tier stratification across export-bound tomato and pepper categories.
Pricing Analysis
Turnkey engineering warranties bundle climate-system commissioning with two-year maintenance coverage, while unbundled hardware-only sales dominate smallholder cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates GLOBALG.A.P.-certified direct retail contracts from wholesale auction channels. Cost compression in standard-tier hydroponic retrofits is intensifying because photovoltaic canopy subsidies pool unevenly across Coexphal member farms. German supermarket chains exhibit lowest price sensitivity; domestic wholesale buyers face highest margin pressure.
Supply Chain Analysis
Direct-to-retail channels handle Northern European hyperscale buyer demand through Almería-Marítima terminal cold-chain partnerships. Geographic supply concentration centers on Spain's Andalusia and Murcia regions, with Dutch breeding houses anchoring varietal propagation inputs. Raw material dependencies rest on rockwool substrate, polyethylene glazing, and natural gas-indexed electricity tariffs. Single-source vulnerability concentrates in three specialized biocide suppliers dominating Spain's protected-crop pesticide channel. Distribution runs through integrated cooperative networks pooling wastewater treatment and photovoltaic infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork strategy functions as a cost-of-compliance barrier, erecting capital moats that favor incumbent cooperative networks with pooled infrastructure investment capacity over fragmented smallholder operations.
For Market Incumbents: Lock in varietal licensing agreements with Dutch breeding houses before propagation backward integration spreads. Consolidate cold-chain partnerships at Almería-Marítima terminal to preempt emerging engineering-led entrants from capturing Levante region white-space demand. Prioritize collective photovoltaic canopy investment across Coexphal member farms to amortize Water Framework Directive compliance costs. For New Entrants and Emerging Players: German supermarket procurement teams represent the most penetrable channel partner type for bypassing traditional wholesale auction structures. Target Valencia and Alicante provinces for integrated climate-buffer greenhouse construction services where J. Huete Greenhouses has not established turnkey dominance. Pursue semi-closed architecture engineering specialization to capture subsidy pools from Andalusian agricultural plastics recycling codes. For Investors and Strategic Acquirers: Re-rating potential sits with hydroponic system designers given EU Green Deal water-efficiency mandate acceleration. Long-term viability across the projection horizon favors operators with captive substrate technology and cooperative federation membership. Monitor enforcement timelines for Water Framework Directive discharge limits as the inflection signal for compliance-cost winner-take-all dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Canopy Integration | Coexphal cooperative networks pool solar-integrated roofing retrofits to meet Andalusian agricultural plastics recycling codes. |
| Backward Integration into Propagation | Grupo Hortofrutícola Paloma captures margin pools from Dutch breeding houses through captive tomato rootstock trialing. |
| Semi-Closed Architecture Engineering | J. Huete Greenhouses dominates turnkey project deliveries across Levante region water-stressed growing belts. |
| Direct Retail Contracting | Almería cooperatives bypass Mercamadrid auctions through multi-season supply commitments to German supermarket chains. |
| Biological Control Agent Expansion | Novagric's specialized hydroponic systems enable 50% pesticide reduction targets under EU Green Deal mandates. |
Research Methodology
Independent corroboration across cooperative federation executives, greenhouse engineering firms, Dutch breeding house licensing managers, and Northern European supermarket procurement directors underwrites the qualitative findings. Primary interviews with Coexphal member farm operators, HVAC automation specialists, and Almería-Marítima terminal logistics coordinators combined with secondary validation from EU Green Deal implementation documents, Water Framework Directive enforcement schedules, and Andalusian regional agricultural plastics recycling codes. Bottom-up acreage and yield estimates triangulate against top-down export volume data from customs and wholesale auction records.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user scale, and distribution channel structure. CAGRs derive from trend extrapolation of hydroponic retrofit adoption curves, photovoltaic subsidy pool allocation, and cooperative governance consolidation patterns. Industry-specific forecast inputs incorporate Water Framework Directive compliance cost trajectories and German retail direct-contracting penetration rates.
Caveats apply where EU Green Deal enforcement acceleration, natural gas price volatility, or biological control agent efficacy failures could materially shift the outlook. Forecasts reflect documented assumptions regarding subsidy pool continuity and cooperative federation governance stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Garlic Market
Vegetables
Sweet Potatoes Market
Vegetables
Garden Cress Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Asparagus Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
North America Peas Market
Vegetables
Sprouts Market
Vegetables
Potato Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Global Mushroom Market
Vegetables
Europe Pea Market
Vegetables
North America Christmas Tree Market
Vegetables
Yarrow Market