
 Global Soil Wetting Agents Market | 2026-2036
Global Soil Wetting Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soil Wetting Agents Market Foresight
Consolidation among commercial growers and large-scale turf management contractors is recalibrating procurement patterns across the soil wetting agents value chain. BASF SE leverages its agricultural chemical distribution network to sustain bulk supply relationships with North American golf course operators. Evonik Industries anchors high-performance surfactant R&D through specialized alkoxylate chemistry platforms. The Aquatrols Company dominates the premium turf segment with concentrated liquid formulations tailored for hydrophobic soil conditions.
Soil wetting agents are surface-active compounds, typically nonionic or anionic surfactants with hydrophilic-lipophilic balance values between 7 and 18, that reduce surface tension at the soil-water interface to improve moisture penetration and retention in water-repellent substrates. Their primary commercial purpose centers on eliminating localized dry spot in turfgrass systems and optimizing irrigation efficiency in drought-prone agricultural soils. Nonionic surfactants occupy the largest formulation share due to superior compatibility with agrochemical tank mixes and lower phytotoxicity profiles. Liquid formulations lead volume consumption in turf management applications where spray uniformity commands priority, while granular forms sustain growth in agricultural fields where broadcast spreading integrates with fertilizer programs. Turf management concentrates margin pools through premium pricing tied to aesthetic performance guarantees on golf courses and sports fields.
The United States Environmental Protection Agency governs surfactant registration under FIFRA, requiring ecotoxicity data that shapes formulation thresholds for agricultural and turf applications. The European Chemicals Agency enforces REACH registration obligations for surfactant imports, compelling suppliers to submit comprehensive biodegradation dossiers that filter out legacy chemistries. China's Ministry of Ecology and Environment implements GB standards for agricultural chemical adjuvants, creating compliance layers for multinational suppliers accessing domestic growers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across these jurisdictions, as precursor chemistries face escalating scrutiny that could force surfactant backbone redesigns.
Market Dynamics
Consolidation among California and Florida golf course operators is compressing supplier margins while redirecting procurement toward concentrated liquid formulations with performance guarantees. This buyer concentration is forcing formulation specialists to absorb certification costs and extend technical service commitments.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:The mandate for biodegradable surfactants is redirecting R&D budgets toward amphoteric chemistries, opening formulation premiums for compliant suppliers.
- Precision agriculture adoption:Commercial growers in Australia's Murray-Darling Basin are expanding application intensity through variable-rate irrigation systems that require wetting agent integration.
- Hydrophobic soil prevalence:Extended drought cycles in Arizona and Nevada are expanding addressable acreage for localized dry spot treatments across municipal and private turf.
Market Restraints
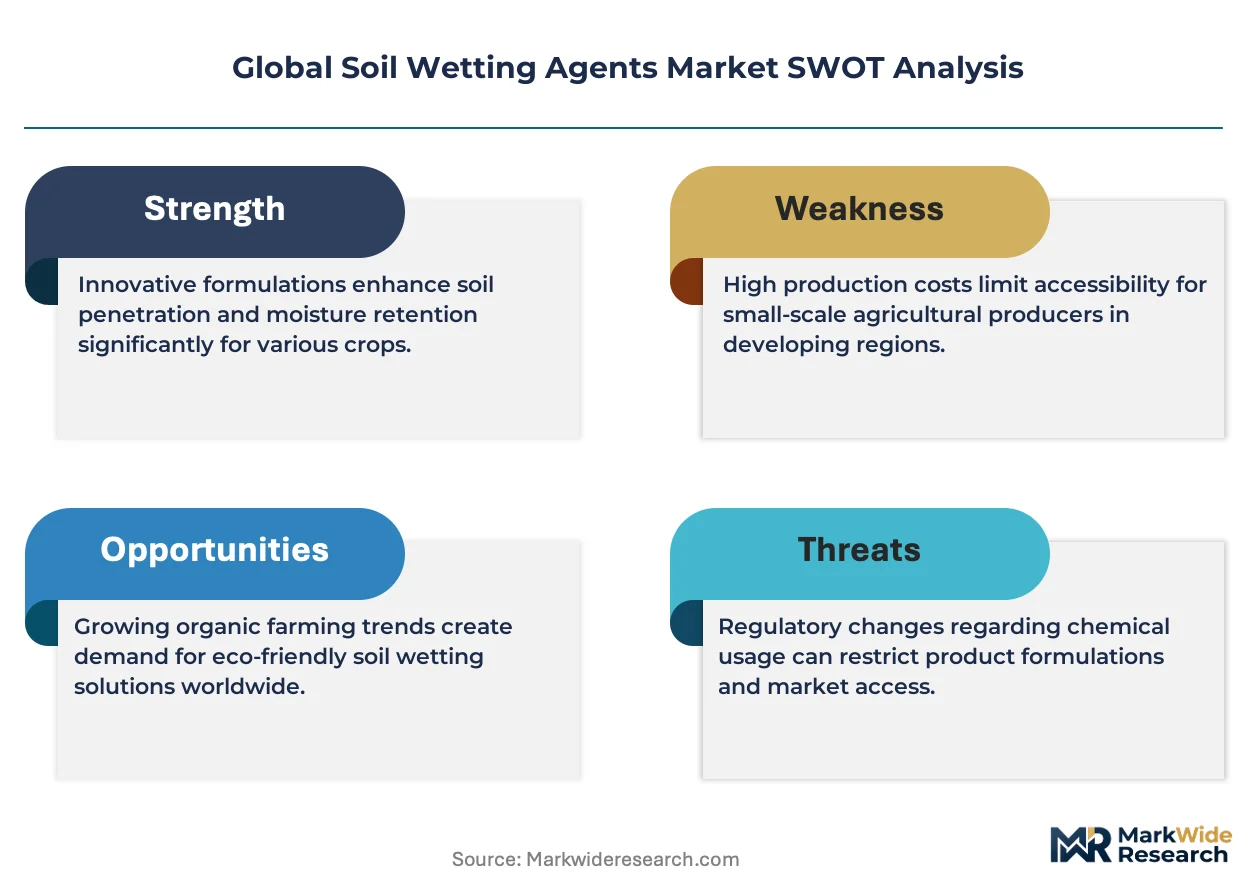
- Ethylene oxide feedstock volatility:Alkoxylate surfactant production faces margin compression from petrochemical price swings that resist hedging at mid-scale formulation volumes.
- REACH registration concentration:European surfactant import compliance costs filter out smaller suppliers, consolidating viable import channels through established distributors with dossier capabilities.
- Biological soil amendment substitution:Compost-based water retention products are capturing price-sensitive agricultural segments where surfactant performance premiums cannot be justified.
Strategic Opportunities
- India's PLI scheme for agrochemicals:Domestic manufacturing incentives are opening localized production pathways for multinational surfactant suppliers seeking tariff avoidance.
- Drone application integration:Aerial spray systems for turf and row crops are creating demand for ultra-low-volume wetting agent concentrates with drift reduction properties.
- China's dual carbon goals:Provincial water efficiency mandates in Hebei and Shandong are accelerating wetting agent adoption in wheat and corn irrigation systems.
Industry Challenges
- Surfactant ecotoxicology certification:EPA FIFRA registration timelines for new chemistries now exceed 24 months, freezing formulation pipelines and extending payback periods for R&D investments.
- Tank-mix compatibility validation:Expanding pesticide adjuvant portfolios require wetting agent suppliers to maintain compatibility databases across hundreds of active ingredient combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soil Wetting Agents Market |
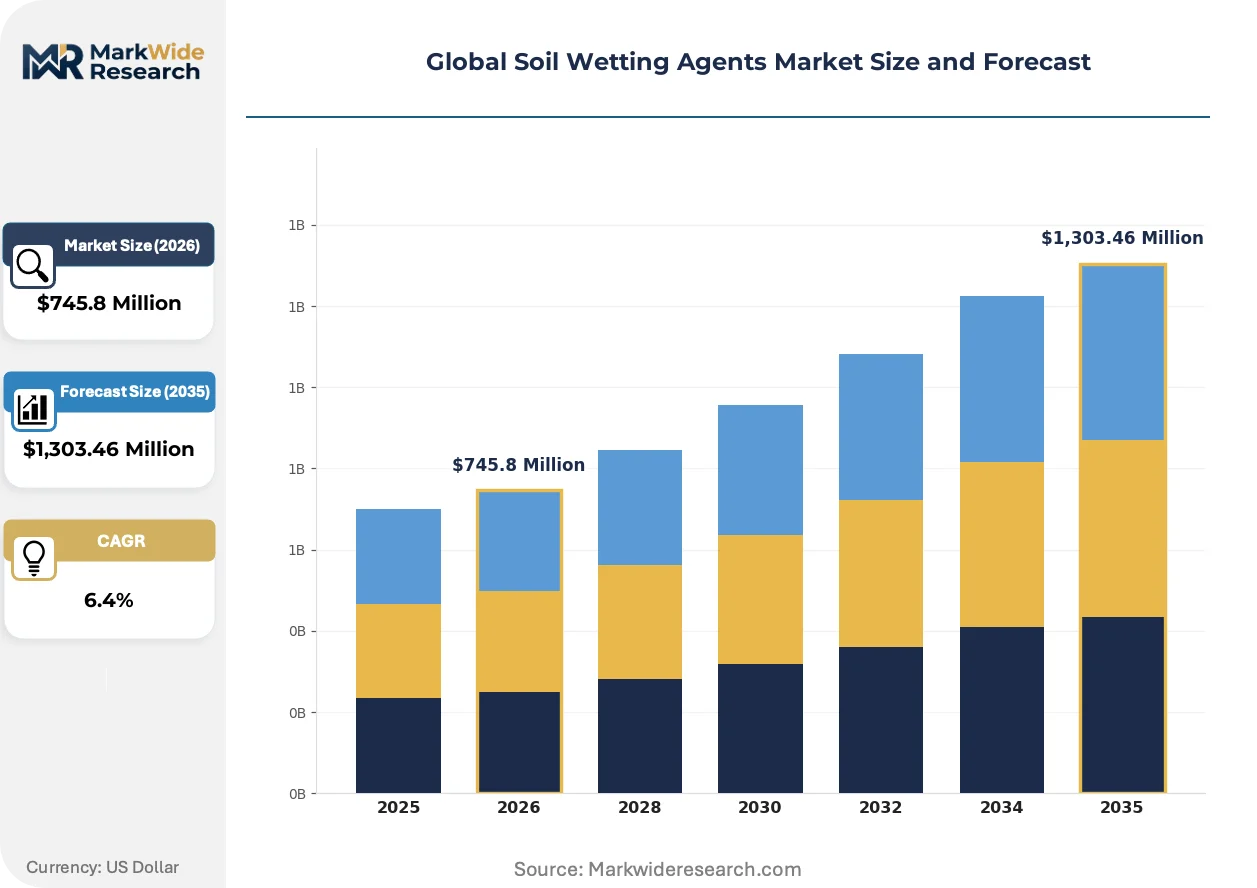
| Market Size in 2026 | $745.8 Million |
| Market Size in 2035 | $1,303.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic Surfactants, Nonionic Surfactants, Cationic Surfactants, Amphoteric Surfactants Application: Agricultural Fields, Turf Management, Forestry, Landscaping Form: Liquid, Granular, Powder, Emulsifiable Concentrate End User: Commercial Growers, Municipal Authorities, Nurseries, Research Institutions |
| Companies Covered | The Aquatrols Company, Evonik Industries, BASF SE, Clariant, Croda International Plc, Wilbur-Ellis Company, Syngenta AG, Helena Agri-Enterprises, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soil Wetting Agents Market Shifts & Advancements
Formulation chemistry and application hardware are converging to redefine performance benchmarks across turf and agricultural segments. Suppliers now compete on integration depth rather than standalone surfactant efficacy.
Block-copolymer surfactant architectures are unifying wetting, spreading, and retention functions in single-molecule designs that outperform legacy blended formulations. Golf course superintendents in Florida and Arizona are adopting these chemistries at accelerated replacement cycles for renovation projects. The technology is unifying what were previously separate product categories into premium single-tank solutions that compress supplier SKU counts.
REACH registration obligations enforced by the European Chemicals Agency are filtering out surfactant chemistries with incomplete biodegradation dossiers. Industrial consequence includes forced retirement of certain anionic workhorses that dominated agricultural applications for decades. Turf management formulations face the tightest substitution pressure, as golf course operators cannot absorb regulatory discontinuity risks during peak season demand windows.
California and Texas golf course operators are consolidating purchases through national maintenance contractors who negotiate master service agreements with embedded wetting agent supply. These procurement models displace traditional distributor relationships and demand outcome-based performance clauses with penalty structures. The shift is most visible in the southwestern United States, where drought-driven irrigation audits now tie contractor compensation to measured water efficiency gains.
Global Soil Wetting Agents Market Segmentation
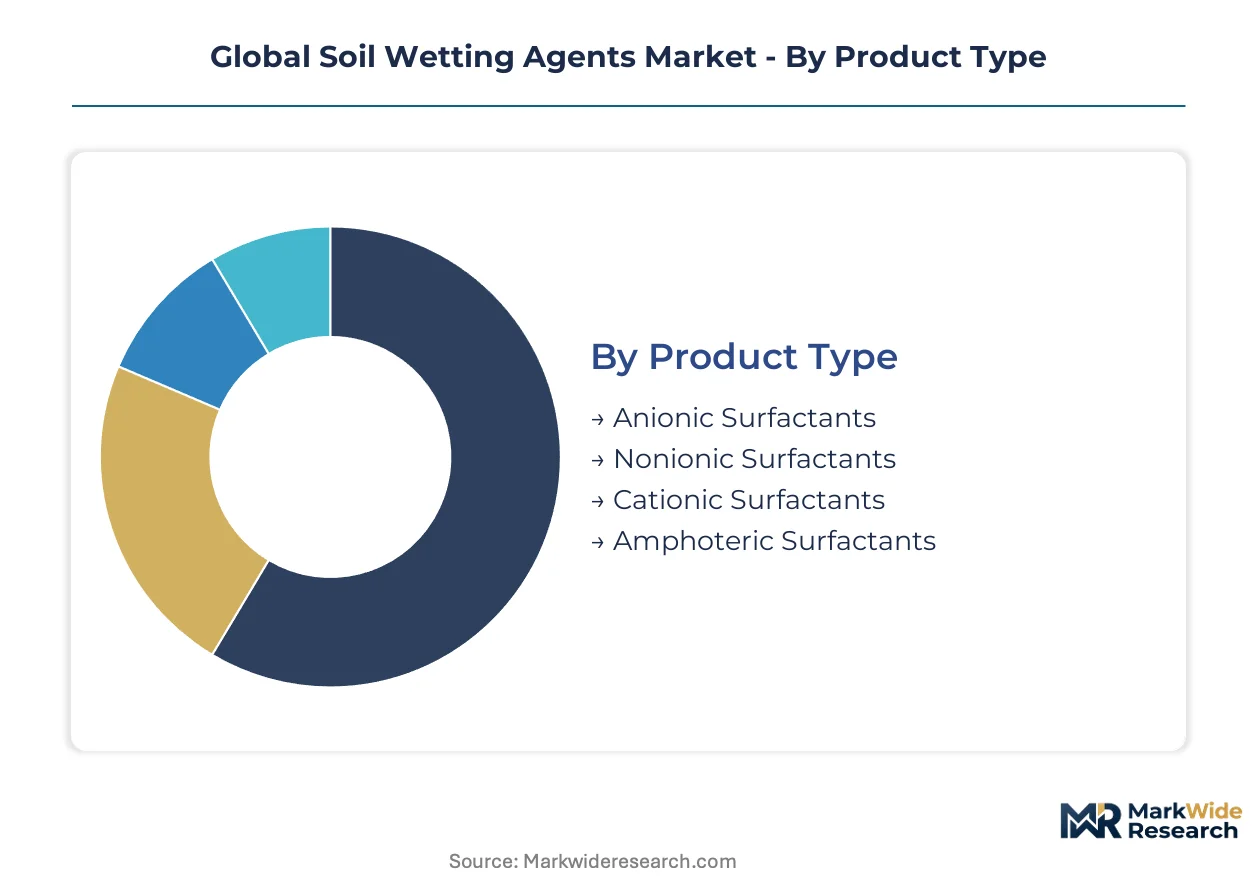
Segmentation in soil wetting agents reveals how formulation chemistry, application method, and customer procurement power fragment value capture across the value chain. Suppliers must align R&D spend and distribution architecture to the capital requirements and performance guarantees of each segment cluster.
Product Type:
Capital intensity varies sharply across surfactant chemistries, with alkoxylate production requiring dedicated ethylene oxide handling infrastructure that filters out mid-scale entrants.
- Nonionic Surfactants:These ethoxylated alcohol or alkylphenol derivatives dominate formulation portfolios due to superior tank-mix compatibility with agrochemicals and minimal phytotoxicity risk. Golf course operators in Florida and Arizona specify nonionic chemistries for localized dry spot treatments where aesthetic performance guarantees command premium pricing.
- Anionic Surfactants:Sulfonate and sulfate-based structures offer cost-efficient wetting for broadacre agricultural applications. Commercial growers in Australia's Murray-Darling Basin favor anionic formulations for variable-rate irrigation systems where input cost control outweighs premium performance requirements.
- Cationic Surfactants:Quaternary ammonium compounds serve niche antimicrobial-wetting dual functions in turf disease management programs.
- Amphoteric Surfactants:Betaine and imidazoline structures are gaining formulation share as REACH-compliant replacements for legacy anionic workhorses.
Nonionic surfactants absorb the bulk of installed capacity; amphoteric surfactants are expanding most quickly.
Application:
Margin structures diverge by application based on performance verification requirements and buyer procurement concentration.
- Turf Management:Golf courses, sports fields, and municipal parks demand concentrated liquid formulations with documented water efficiency outcomes. Consolidated maintenance contractors in California negotiate master service agreements that embed wetting agent supply with penalty clauses tied to irrigation audit results.
- Agricultural Fields:Row crop and specialty crop operations prioritize cost-efficient granular or liquid broadcast applications integrated with fertilizer programs. China's provincial water efficiency mandates in Hebei and Shandong are accelerating wetting agent adoption in wheat and corn irrigation systems.
- Forestry:Reforestation and plantation timber operations use wetting agents for seedling establishment in hydrophobic post-fire soils.
- Landscaping:Commercial and residential landscape contractors represent a price-sensitive segment where compost-based soil amendments compete for water retention function.
Turf management commands the steepest pricing premiums; agricultural fields deliver the highest volume throughput.
Form:
Production asset requirements separate liquid formulation specialists from dry product manufacturers with blending and granulation capabilities.
- Liquid:Concentrated aqueous solutions dominate turf management where spray uniformity and drift reduction properties determine application efficacy. Drone integration for aerial turf and row crop spraying is creating demand for ultra-low-volume concentrates with optimized viscosity profiles.
- Granular:Clay or polymer-carried formulations integrate with dry fertilizer spreading equipment in broadacre agriculture. Broadcast application compatibility sustains growth in agricultural fields where labor constraints favor mechanical spreading over spray operations.
- Powder:Dust-form surfactants serve specialty nursery and research applications requiring precise dose calibration.
- Emulsifiable Concentrate:Oil-based carriers with surfactant payloads offer extended residual activity in water-repellent soil profiles.
Liquid formulations anchor revenue concentration; granular forms are climbing the fastest on agricultural mechanization trends.
End User:
Procurement sophistication and technical service demands stratify the customer base from institutional research buyers to consolidated commercial operators.
- Commercial Growers:Large-scale specialty crop and broadacre operators negotiate volume contracts with embedded technical support and compatibility validation. India's PLI scheme for agrochemicals is opening localized production pathways for multinational suppliers targeting tariff-sensitive commercial grower segments.
- Municipal Authorities:Parks departments and water districts procure wetting agents through public tender processes with sustainability scoring criteria. The EU Green Deal's Farm to Fork strategy is redirecting municipal procurement toward biodegradable surfactant formulations with comprehensive ecotoxicology dossiers.
- Nurseries:Container and field nursery operations require precise dose control for seedling and transplant establishment.
- Research Institutions:University and government agricultural experiment stations drive formulation innovation through controlled efficacy trials.
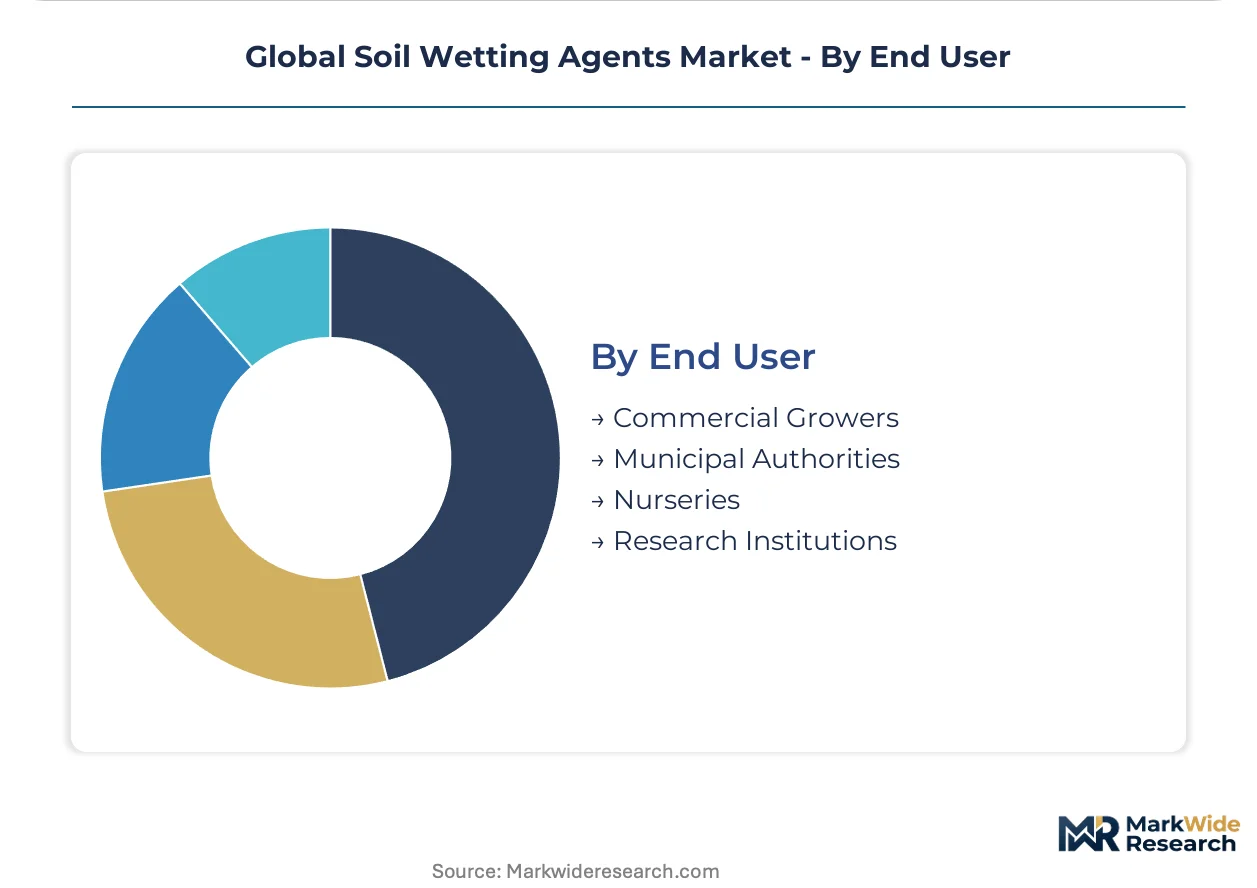
Commercial growers absorb the bulk of formulation volume; municipal authorities are gaining share fastest on climate adaptation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers in California and Australia's Murray-Darling Basin concentrate demand for precision application systems. Golf course operators across Florida and Arizona drive premium formulation consumption through renovation cycles. Municipal water districts in drought-prone provinces of China and the southwestern United States are embedding wetting agents into conservation mandates.
United States
Consolidated golf course operators in Florida and Arizona negotiate master service agreements with embedded wetting agent supply and penalty clauses tied to irrigation audit results. The EPA governs surfactant registration under FIFRA, requiring ecotoxicity data that shapes formulation thresholds for agricultural and turf applications. California's Central Valley commercial growers expand application intensity through variable-rate irrigation systems.
Australia
Commercial growers in the Murray-Darling Basin integrate wetting agents into precision agriculture systems to optimize water use efficiency across drought-prone broadacre operations. The country's national chemical regulator enforces agricultural chemical adjuvant standards that filter import channels through established distributors with compliance dossiers. Sydney and Melbourne municipal turf managers specify concentrated liquid formulations for sports field localized dry spot treatments.
China
Provincial water efficiency mandates in Hebei and Shandong accelerate wetting agent adoption in wheat and corn irrigation systems under the country's dual carbon goals. The Ministry of Ecology and Environment implements GB standards for agricultural chemical adjuvants, creating compliance layers for multinational suppliers. Yangtze River Delta commercial nursery operations demand precise dose control for seedling establishment in container systems.
Germany
Specialty crop operators in Bavaria and Baden-Württemberg specify REACH-compliant amphoteric surfactants as replacements for legacy anionic chemistries. The European Chemicals Agency enforces registration obligations that filter out surfactant imports with incomplete biodegradation dossiers. BASF SE leverages its agricultural chemical distribution network from Ludwigshafen to sustain bulk supply relationships across European turf management contractors.
India
The PLI scheme for agrochemicals opens localized production pathways for multinational surfactant suppliers seeking tariff avoidance in price-sensitive agricultural segments. The Bureau of Indian Standards and Central Insecticides Board regulate adjuvant quality parameters that shape import substitution strategies. Maharashtra and Gujarat commercial cotton and sugarcane growers expand broadcast application of granular formulations integrated with fertilizer programs.
Global Soil Wetting Agents Market Competitive Landscape
German chemical conglomerates anchor one tier through integrated surfactant R&D and agricultural distribution networks; United States-based turf specialists hold premium positioning through concentrated liquid formulations with performance guarantees. The vendor base fragments across mid-scale alkoxylate producers lacking ethylene oxide hedging capabilities and regional blenders serving price-sensitive agricultural segments. Three archetypes dominate: integrated chemical majors with captive surfactant production, formulation specialists with technical service depth, and regional distributors with tank-mix compatibility databases. Competitive moves concentrate on strategic partnerships with precision irrigation hardware suppliers and portfolio diversification into drone-compatible ultra-low-volume concentrates.
Within the integrated chemical tier, BASF SE and Evonik Industries exemplify archetypes built on alkoxylate chemistry platforms and specialized surfactant architectures respectively. The Aquatrols Company occupies a distinct position among turf-focused formulation specialists. These three entities represent the concentration of R&D capability and distribution scale that smaller regional blenders cannot replicate without ethylene oxide handling infrastructure or REACH dossier competencies.
| Leading Market Players |
|---|
| The Aquatrols Company |
| Evonik Industries |
| BASF SE |
| Clariant |
| Croda International Plc |
| Wilbur-Ellis Company |
| Syngenta AG |
| Helena Agri-Enterprises |
| Nufarm |
| Others |
Supply & Pricing Matrix
Ethylene oxide price volatility cascades through alkoxylate surfactant production into three distinct pricing tiers that separate premium turf formulations from agricultural commodity grades. Feedstock cost swings compress margins at mid-scale formulation volumes while consolidating procurement power among integrated chemical majors with captive ethylene oxide handling infrastructure.
Pricing Analysis
Volume throughput concentrates in agricultural broadcast applications where granular formulations compete on input cost, while margin pools concentrate in turf management through performance-guaranteed liquid concentrates. Price differentiation rests on certification grade—REACH-compliant amphoteric chemistries command formulation premiums—and volume scale, with consolidated golf course operators extracting bulk discounts. Pricing pressure intensifies from biological soil amendment substitution in price-sensitive agricultural segments. Commercial growers exhibit highest price sensitivity; golf course superintendents prioritize aesthetic outcome guarantees over unit cost.
Supply Chain Analysis
Specialized chemical workforce availability in Germany's Ludwigshafen cluster and India's Gujarat chemical belt anchors integrated surfactant production capacity. Raw material dependencies center on ethylene oxide, natural alcohol feedstocks, and specialized quaternary ammonium compounds. Supply chain risk concentrates in single-source vulnerability for ethylene oxide derivatives subject to petrochemical price cycles. Distribution runs through agricultural chemical distributors with tank-mix compatibility databases and technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soil wetting agents market is transitioning from legacy anionic surfactants toward block-copolymer and amphoteric chemistries that unify wetting, spreading, and retention functions. This technology shift rewards suppliers with REACH dossier capabilities and penalizes mid-scale blenders lacking biodegradation certification infrastructure.
For Market Incumbents: Extend formulation R&D into drone-compatible ultra-low-volume concentrates to capture precision agriculture integration. Deepen backward integration into ethylene oxide handling infrastructure to hedge feedstock volatility that threatens mid-tier competitors. Lock in master service agreements with consolidated California and Florida golf course operators before procurement shifts fully to national maintenance contractors. For New Entrants and Emerging Players: The EU Green Deal's Farm to Fork strategy in Europe opens a window for REACH-compliant amphoteric surfactant specialists to displace legacy anionic workhorses. Target India's price-sensitive agricultural segments through PLI scheme-enabled localized production that avoids tariff exposure. Pursue technical partnerships with precision irrigation hardware suppliers rather than building standalone distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale alkoxylate producers in Germany and India lacking ethylene oxide hedging capabilities but holding REACH registration dossiers. Long-term viability hinges on surfactant backbone redesign capabilities as per- and polyfluoroalkyl substance restrictions escalate across jurisdictions. Watch EPA FIFRA registration timeline extensions beyond 24 months as the inflection signal freezing formulation pipelines and extending R&D payback periods.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates BASF SE and Evonik Industries from petrochemical price volatility compressing mid-scale competitors. |
| REACH Dossier Investment | Comprehensive biodegradation documentation filters out legacy anionic imports and opens formulation premiums for compliant amphoteric replacements. |
| Drone-Compatible Concentrate Development | Ultra-low-volume formulations with optimized viscosity profiles capture aerial application growth in California and Australian broadacre operations. |
| Master Service Agreement Expansion | Outcome-based contracts with embedded wetting agent supply and irrigation audit penalty clauses lock in consolidated golf course procurement. |
| India PLI-Enabled Localization | Domestic manufacturing incentives allow multinational suppliers to serve price-sensitive Maharashtra and Gujarat cotton growers through tariff-avoiding production. |
Research Methodology
Trade databases, EU REACH registration filings, and agricultural chemical customs records formed the secondary backbone for supply-side mapping. Primary interviews with formulation R&D directors, golf course superintendents in Florida and Arizona, and procurement leads at Australian Murray-Darling Basin commercial growers validated demand-side assumptions. Bottom-up segmentation modeling triangulated against top-down chemical industry production capacity data.
Historical trendline analysis of surfactant production volumes and pricing indices established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include surfactant chemistry type, application method, formulation form, and regional regulatory cluster. CAGRs derived from ethylene oxide feedstock cost trajectories, precision agriculture hardware adoption curves, and golf course renovation cycle timing. Industry-specific forecast inputs incorporated EPA FIFRA registration pipeline delays and EU Green Deal implementation pace.
The model assumes a particular technology adoption path; alternative pathways for block-copolymer surfactant architectures would alter the outlook if tank-mix compatibility validation timelines extend materially. Forecasts reflect assumptions about REACH registration concentration effects and biological soil amendment substitution rates. Material deviation in ethylene oxide price volatility or EPA registration timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
North America Feed Amino Acids Market