
 GCC Feed Premix Market | 2026-2036
GCC Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Feed Premix Market Foresight
Phytase enzyme additives is rebalancing mineral premix economics by reducing inorganic phosphorus dependence and lowering raw material costs. Nutreco N.V. leverages its Dutch R&D base to transfer precision nutrition protocols into Saudi broiler operations. Arasco Feed anchors supply security through captive grain milling and backward integration into feedstock procurement. Adisseo specializes in methionine and enzyme technologies that differentiate its premix portfolio from commodity blenders.
Feed premix denotes a homogeneous mixture of micro-ingredients — vitamins, minerals, amino acids, and feed additives — diluted into a carrier substance and dosed at 0.1% to 1.0% of total ration weight to ensure uniform nutrient distribution across bulk feed. The product functions as a precision delivery vehicle for micronutrients that prevent deficiency disorders and optimize feed conversion ratios in intensive livestock systems. Vitamin premixes command the dominant margin pool due to stability-sensitive formulation requirements and cold-chain handling premiums, while amino acid premixes represent the fastest-expanding category as Saudi and UAE poultry producers adopt low-protein, crystalline amino acid-supplemented diets to meet sustainability targets. Poultry farmers constitute the anchor end-user segment, absorbing the majority of volume through direct sales channels that bypass distributor markups for large integrated operations.
The Saudi Food and Drug Authority enforces maximum residue limits and feed hygiene standards that compel premix manufacturers to maintain ISO 22000-certified production facilities and batch-level traceability systems. The UAE's Ministry of Climate Change and Environment aligns with GCC standardization protocols for imported feed additives, creating a harmonized but stringent approval pathway for new premix entrants. The EU REACH framework indirectly shapes supplier qualification criteria for European multinationals operating Gulf subsidiaries, extending compliance burdens to local blenders. Stakeholders must monitor how Saudi Arabia's domestic wheat and barley substitution programs alter carrier substrate availability and pricing dynamics for locally compounded premixes.
Market Dynamics
Phytase enzyme adoption is restructuring mineral premix economics across Saudi Arabia and the UAE, slashing inorganic phosphorus dependence while compressing raw material costs for integrated poultry operations.
Growth Catalysts
- SFDA Mycotoxin Limits:The Saudi Food and Drug Authority's tightened maximum residue thresholds compel feed producers toward higher-specification vitamin and mineral blends, accelerating premium premix procurement.
- Qassim Poultry Cluster Expansion:Integrated broiler complexes in Saudi Arabia's central region concentrate near grain handling infrastructure, creating dense demand nodes that justify localized premix production investments.
- Precision Nutrition Protocols:Dutch-developed feed formulation technologies transfer into Gulf operations, enabling amino acid optimization that improves feed conversion ratios in intensive systems.
Market Restraints
- Carrier Substrate Volatility:Saudi Arabia's domestic wheat and barley substitution programs destabilize grain availability for locally compounded premixes, forcing unpredictable reformulation cycles.
- Import Dependency Concentration:The UAE's Ministry of Climate Change and Environment harmonizes with GCC standardization protocols, yet critical vitamin raw materials remain concentrated among European and Asian suppliers.
- Cold-Chain Infrastructure Gaps:Vitamin premix stability requirements demand temperature-controlled logistics that remain underdeveloped outside Riyadh and Dubai corridors.
Strategic Opportunities
- Low-Protein Diet Adoption:Crystalline amino acid-supplemented rations gain traction among sustainability-targeted Saudi poultry producers, opening fastest-expanding premix category growth.
- Direct Channel Penetration:Large integrated operations bypass distributor markups through direct manufacturer relationships, compressing channel costs and capturing margin pool redistribution.
- ISO 22000 Certification Arbitrage:Batch-level traceability mandates create competitive differentiation for early-compliant blenders against commodity competitors.
Industry Challenges
- Formulation Talent Scarcity:Precision nutrition expertise remains concentrated among European-trained specialists, constraining local premix manufacturer technical capabilities.
- REACH Compliance Burden:EU REACH framework qualification criteria extend to European multinational Gulf subsidiaries, imposing documentation costs on local blenders serving these supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Feed Premix Market |
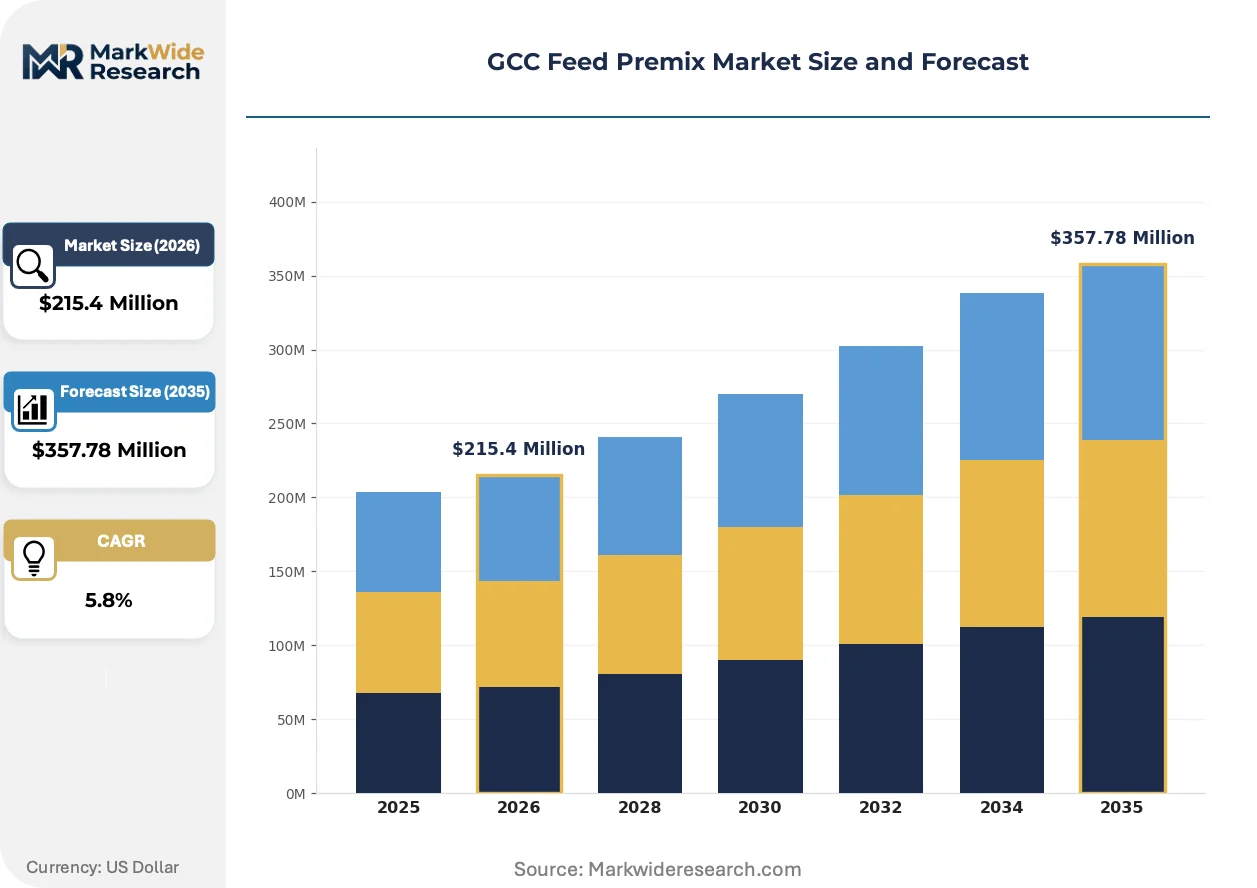
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin Premixes, Mineral Premixes, Amino Acid Premixes, Antibiotic Premixes End User: Poultry Farmers, Aquaculture Producers, Dairy Farmers, Swine Producers Application: Animal Nutrition, Livestock Feed, Aquatic Feed, Specialty Feed Distribution Channel: Direct Sales, Online Retail, Distributors, Supermarkets |
| Companies Covered | IFFCO Animal Nutrition, Nutreco N.V., Al-Sayer Group, Trouw Nutrition, Adisseo, AL Ghurair Foods, Archer Daniels Midland Company, Saudi Mix, Arasco Feed, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Feed Premix Market Shifts & Advancements
Enzyme-driven nutrient density optimization and regulatory traceability mandates are converging to reshape premix formulation priorities across Gulf livestock operations.
Phytase enzyme technology is decentralizing mineral premix supply chains by enabling poultry producers to slash inorganic phosphate inputs by 30-40% without performance penalty. Saudi integrated operations are adopting this reformulation approach fastest, drawn by simultaneous cost reduction and environmental compliance gains. The structural consequence is compressing traditional phosphate supplier margins while elevating enzyme-specialist premix blenders.
SFDA feed hygiene standards now enforce ISO 22000-certified production facilities and batch-level traceability systems across all Saudi premix manufacturing. This regulatory tightening disqualifies informal compounders from supplying licensed feed mills, consolidating volume toward certified producers. Vitamin premix manufacturers face the steepest compliance investment given stability-sensitive cold-chain handling requirements.
Integrated poultry complexes in Qassim and Riyadh are consolidating procurement through direct manufacturer contracts that disintermediate traditional distributor networks. Large Saudi operations now negotiate annual volume agreements with premix specialists, capturing price transparency unavailable through fragmented wholesale channels. This purchasing concentration is most visible among broiler producers exceeding 500,000 bird weekly capacity.
GCC Feed Premix Market Segmentation
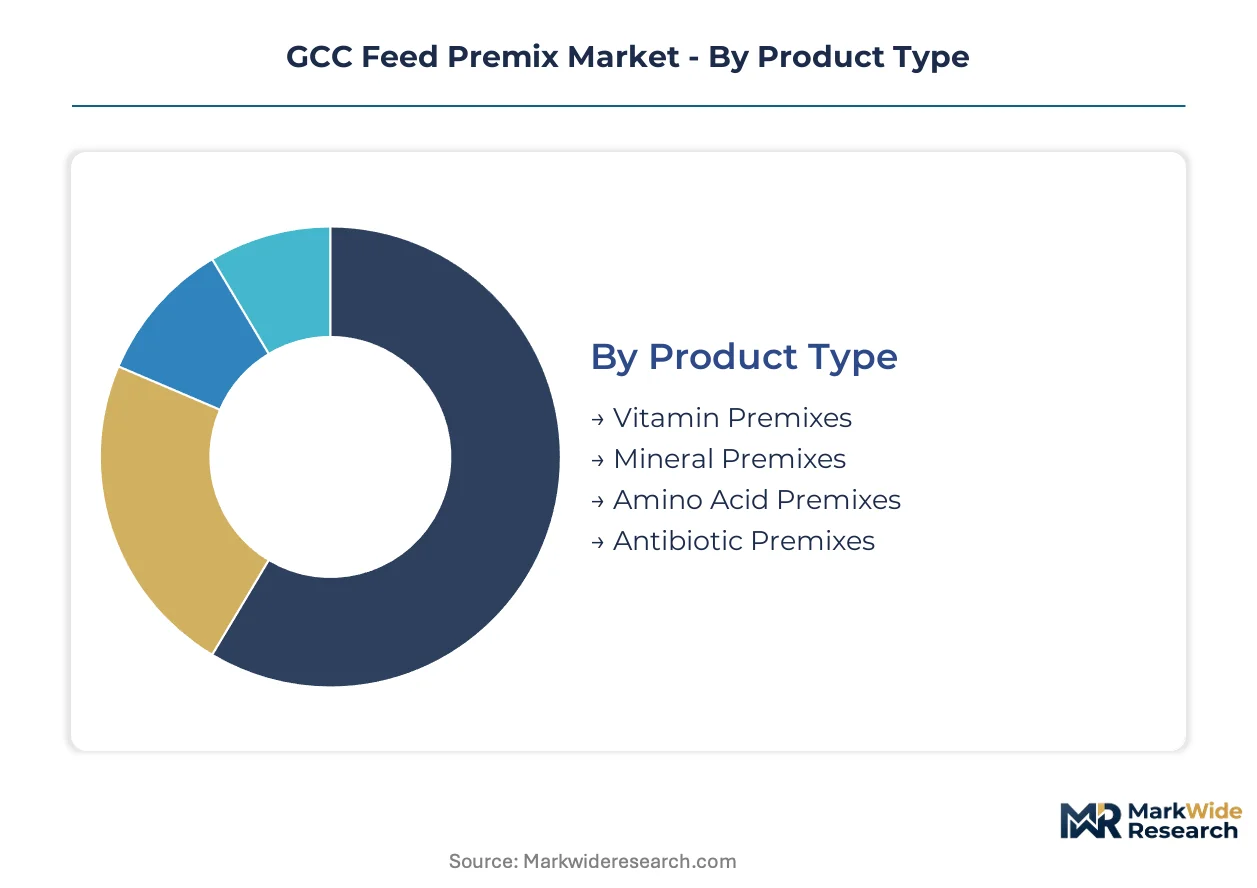
Feed premix segmentation in the GCC reveals divergent capital requirements across formulation technologies. Product type stratification determines cold-chain infrastructure investments, while end-user concentration shapes channel economics for manufacturers serving Saudi Arabia's integrated poultry clusters.
Product Type:
Vitamin premixes demand the steepest upfront capital outlay for stability-sensitive production facilities and temperature-controlled logistics networks across Riyadh and Dubai corridors.
- Vitamin Premixes:Micro-encapsulated blends of fat-soluble and water-soluble vitamins requiring ISO 22000-certified facilities and batch-level traceability systems. Saudi Arabia's Qassim poultry complexes absorb the majority of high-specification procurement as SFDA mycotoxin limits tighten. Cold-chain handling premiums elevate margin capture for certified producers.
- Mineral Premixes:Inorganic and chelated mineral blends dosed for bone development and metabolic function in intensive broiler systems. Phytase enzyme adoption across Saudi integrated operations is restructuring traditional phosphate economics and compressing raw material costs.
- Amino Acid Premixes:Crystalline lysine, methionine, and threonine formulations enabling low-protein diet adoption.
- Antibiotic Premixes:Growth-promoter and therapeutic blends facing regulatory contraction across Gulf feed hygiene protocols.
Vitamin premixes absorb the bulk of installed capacity; amino acid premixes are expanding most quickly.
End User:
Poultry farmers concentrate procurement volume through direct manufacturer relationships that bypass traditional distributor markups.
- Poultry Farmers:Broiler and layer operations across Saudi Arabia's central region and UAE emirates constitute the anchor demand segment. Operations exceeding 500,000 bird weekly capacity negotiate annual volume agreements with premix specialists.
- Dairy Farmers:Ruminant nutrition programs in Saudi Arabia's dairy clusters near Al Kharj and Al Ahsa drive mineral and vitamin premix procurement for milk yield optimization.
- Aquaculture Producers:Shrimp and finfish farms along UAE coastlines and Saudi Red Sea developments.
- Swine Producers:Limited regional presence concentrated in non-GCC Middle East supply chains with minimal Gulf penetration.
Poultry farmers dominate volume absorption; aquaculture producers are climbing the fastest as marine protein demand intensifies.
Application:
Livestock feed applications command the densest formulation expertise requirements given precision nutrition protocols transferring from Dutch R&D centers.
- Livestock Feed:Cattle, sheep, and goat nutrition programs across Saudi Arabia's pastoral zones and UAE dairy operations. Backward integration into captive grain milling anchors supply security for large compounders.
- Animal Nutrition:Broad-species micronutrient delivery spanning poultry, ruminant, and companion animal segments.
- Aquatic Feed:Marine and freshwater species formulations with specialized palatability and digestibility requirements.
- Specialty Feed:Breeder, starter, and finisher phase-specific premixes for performance-tier differentiation.
Livestock feed captures the deepest technical investment; aquatic feed is gaining share fastest on aquaculture expansion.
Distribution Channel:
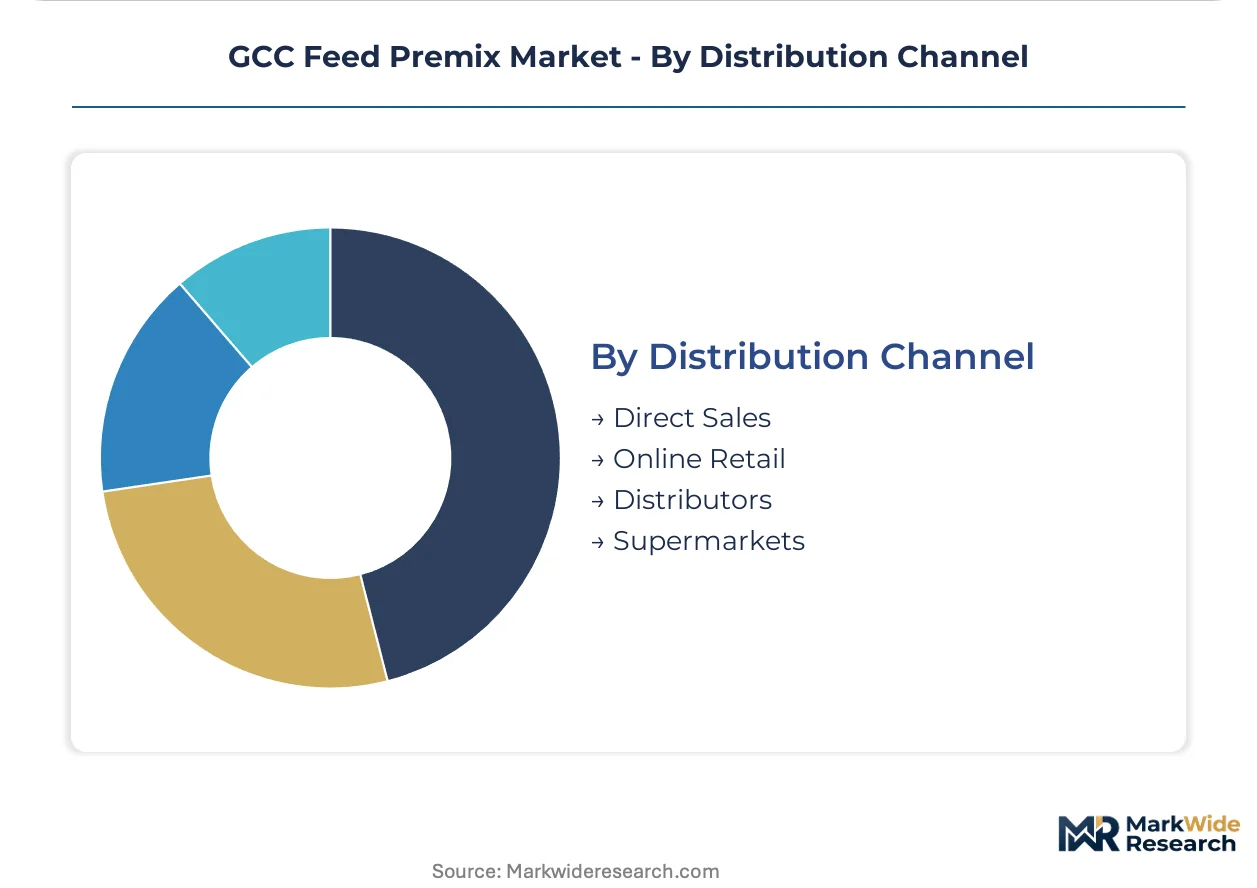
Direct sales channels reward scale concentration among integrated operations while distributor networks serve fragmented mid-tier producers.
- Direct Sales:Manufacturer-to-producer contracts eliminating intermediary margins for Saudi integrated complexes and UAE large-scale operations. Annual volume agreements deliver price transparency unavailable through wholesale channels.
- Distributors:Regional wholesalers serving mid-cap poultry farms and independent dairy operations across secondary GCC markets.
- Online Retail:Emerging platform-based procurement for smallholder and hobby farm segments.
- Supermarkets:Minimal premix penetration limited to specialty companion animal supplements.
Direct sales absorb the majority of value throughput; online retail is expanding most quickly on platform digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated poultry complexes in Saudi Arabia's Qassim region concentrate the densest demand for high-specification premix formulations, while UAE aquaculture developments along the Red Sea coast are accelerating procurement of marine-specific micronutrient blends.
Saudi Arabia
Broiler operations exceeding 500,000 bird weekly capacity anchor premix volume absorption through direct manufacturer contracts. The SFDA enforces tightened mycotoxin maximum residue limits that compel reformulation toward premium vitamin and mineral blends. Qassim's central region clusters integrated poultry complexes near grain handling infrastructure, justifying localized production investments by major compounders.
United Arab Emirates
Marine protein demand intensifies procurement of aquatic feed premixes for shrimp and finfish farms along the Red Sea coastline. The Ministry of Climate Change and Environment harmonizes with GCC standardization protocols for imported feed additives, creating stringent approval pathways. Dubai and Abu Dhabi corridors maintain the region's most developed cold-chain infrastructure for stability-sensitive vitamin premix logistics.
Kuwait
Dairy operations in Al Jahra and Al Ahmadi governorates drive mineral premix procurement for milk yield optimization in intensive ruminant systems. The national food safety authority aligns feed hygiene standards with broader GCC regulatory frameworks. Smallholder poultry segments remain dependent on distributor networks rather than direct manufacturer relationships.
Oman
Pastoral livestock zones in Dhofar and Al Batinah regions sustain demand for broad-spectrum animal nutrition premixes. The Ministry of Agriculture and Fisheries enforces feed import regulations that concentrate supply among established GCC compounders. Salalah's port infrastructure facilitates maritime distribution to Yemen and Horn of Africa markets.
Qatar
Food security initiatives accelerate domestic poultry production capacity, expanding premix procurement for newly commissioned broiler facilities. The national standards body adopts GCC harmonized protocols for feed additive approvals. Doha's concentrated retail distribution network limits direct channel penetration compared to Saudi integrated operations.
GCC Feed Premix Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vitamin premix concentration favoring certified producers while mineral blending tolerates more fragmented supply. The vendor base organizes around three strategic archetypes: European multinationals transferring precision nutrition protocols, Gulf-based integrated compounders with captive grain milling, and Asian suppliers competing on amino acid raw material cost. M&A activity targets ISO 22000-certified facilities, while capacity expansion concentrates in Saudi Arabia's Qassim corridor to serve clustered poultry demand.
Within the European multinational tier, Nutreco N.V. and Trouw Nutrition represent precision nutrition technology transfer into Gulf operations, exemplifying the Dutch R&D-to-field protocol model. Among Gulf-based integrated compounders, Arasco Feed anchors supply security through backward integration into feedstock procurement and captive grain milling. Adisseo occupies a specialist position in methionine and enzyme technologies that differentiate its portfolio from commodity blenders.
| Leading Market Players |
|---|
| IFFCO Animal Nutrition |
| Nutreco N.V. |
| Al-Sayer Group |
| Trouw Nutrition |
| Adisseo |
| AL Ghurair Foods |
| Archer Daniels Midland Company |
| Saudi Mix |
| Arasco Feed |
| Others |
Supply & Pricing Matrix
Backward integration into captive grain milling anchors both supply security and pricing power for Saudi integrated compounders serving Qassim poultry clusters. Arasco Feed's in-house feedstock procurement insulates margin capture against carrier substrate volatility while compressing procurement costs for vitamin and mineral premix formulations.
Pricing Analysis
Volume concentration versus margin capture splits sharply across the premix tier structure. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 22000 certification grade and cold-chain handling capability. Pricing pressure stems from phytase enzyme adoption compressing traditional mineral premix margins. Large integrated operations exceeding 500,000 bird weekly capacity exhibit lowest price sensitivity due to annual volume agreements, while mid-tier distributor-dependent farms face acute cost compression.
Supply Chain Analysis
Saudi Arabia's domestic wheat and barley substitution programs are reshaping sourcing patterns for locally compounded premix carriers. Critical vitamin raw materials draw from European and Asian supply bases, while enzyme technologies rest on Dutch and French specialist manufacturers. Single-source vulnerability concentrates in methionine and lysine feedstock channels. Distribution runs through direct manufacturer contracts for integrated operations and regional wholesalers for fragmented mid-tier producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SFDA mycotoxin limits and ISO 22000 certification mandates erect barrier-to-entry moats for early-compliant blenders against informal compounders.
For Market Incumbents: Deepen backward integration into feedstock procurement to anchor supply security against Saudi grain substitution volatility. Expand ISO 22000-certified production capacity in Qassim corridor to capture volume concentration from clustered poultry operations. Defend margin position by accelerating phytase enzyme formulation expertise before Asian amino acid suppliers commoditize mineral premix tiers. For New Entrants and Emerging Players: Launch via direct sales contracts targeting UAE aquaculture developments along Red Sea coastline where marine-specific micronutrient demand outpaces established supply. Exploit distributor network gaps in Kuwait's smallholder poultry segment. Prioritize methionine and enzyme technology licensing partnerships to differentiate from commodity vitamin blenders. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of ISO 22000-certified facilities by European multinationals seeking Gulf production footholds. Long-term viability favors blenders with cold-chain infrastructure in Riyadh and Dubai corridors. Watch phytase enzyme adoption rates as inflection indicator for mineral premix margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Procurement | Arasco Feed's captive grain milling anchors supply security against Saudi substitution program volatility. |
| ISO 22000 Certification Investment | SFDA batch-level traceability mandates disqualify informal compounders from licensed feed mill supply. |
| Phytase Enzyme Formulation Expansion | Nutreco's Dutch R&D protocols transfer precision nutrition capabilities into Saudi broiler operations. |
| Direct Channel Penetration | Annual volume agreements with Qassim integrated complexes bypass distributor markups and capture price transparency. |
| Aquaculture Premix Portfolio Development | UAE Ministry of Climate Change and Environment protocols create stringent but navigable approval pathway for marine formulations. |
Research Methodology
Independent corroboration across feed mill procurement directors, poultry farm operations managers, and regulatory affairs specialists at SFDA and UAE Ministry of Climate Change and Environment underwrites the qualitative findings. Secondary validation draws from customs trade data, SFDA feed hygiene standards documentation, GCC standardization protocols, and integrated compounder capacity disclosures. Bottom-up volume triangulation against top-down market sizing reconciles segment-level estimates.
Rate-of-change decomposition across product type, end-user concentration, and distribution channel dimensions structures the analytical framework throughout the forecast period. CAGRs derive from segment-level growth trajectories weighted by base-year value shares. Phytase enzyme adoption curves and low-protein diet penetration rates among Saudi poultry producers constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for phytase enzyme mineral premix reformulation would alter the outlook if inorganic phosphate suppliers accelerate cost reduction. Forecasts reflect assumptions about SFDA regulatory enforcement consistency and GCC import harmonization stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Lawn Care Chemicals Market