
 Berry Greenhouse Premium Micronutrient Package Market | 2026-2036
Berry Greenhouse Premium Micronutrient Package Market Size, Share, and Industry Trends Forecast 2026-2036
Berry Greenhouse Premium Micronutrient Package Market Insights
Specialized agronomy expertise is bifurcating the competitive landscape, as greenhouse operators struggle to source technicians fluent in both hydroponic chemistry and berry phenology. Haifa Group leverages its decades-long water-soluble fertilizer heritage to dominate premium liquid concentrate formulations. ICL Group sustains competitive positioning through captive phosphate and potassium supply chains that anchor cost structures.
Berry Greenhouse Premium Micronutrient Packages are precision-blended fertilizer systems containing iron, manganese, zinc, copper, boron, and molybdenum in plant-available chelated forms, engineered for closed irrigation systems where runoff recovery demands exact ppm dosing. Their primary purpose is to prevent deficiency-induced fruit abortion while optimizing brix accumulation in cultivars bred for extended shelf life. Chelated micronutrients command the deepest margin pools due to manufacturing complexity and patent-protected EDTA and EDDHA ligand chemistries, while hydroponic nutrient solution application is expanding fastest as substrate-based berry culture displaces field production across Mediterranean and Central American operations.
The EU Fertilizing Products Regulation and REACH constrain cadmium and heavy metal thresholds in micronutrient imports, forcing reformulation of legacy mineral sources. The USDA's National Organic Program shapes demand through allowed and prohibited substance lists that differentiate conventional from certified organic greenhouse berry channels. Stakeholders must monitor evolving carbon border adjustment mechanisms that threaten to reprice imported soluble fertilizers from carbon-intensive production nodes.
Market Dynamics
The EU Fertilizing Products Regulation is forcing reformulation of legacy mineral sources across European greenhouse operations, while substrate-based berry culture displaces field production in Mediterranean and Central American corridors.
Growth Catalysts
- REACH contaminant thresholds:The EU's tightened cadmium and heavy metal limits accelerate demand for chelated micronutrient alternatives in Dutch and Spanish greenhouse clusters.
- Hydroponic nutrient solution application:Closed irrigation systems with runoff recovery requirements expand rapidly across Almería's controlled-environment agriculture corridors.
- Precision fertigation programs:Commercial operators in the Netherlands deploy sensor-driven dosing systems that require plant-available chelated forms.
Market Restraints
- Patent-protected ligand chemistries:EDTA and EDDHA manufacturing complexity limits supplier entry and concentrates margin capture among established formulators.
- Phosphate and potassium supply concentration:Captive supply chains anchor cost structures for dominant players, squeezing mid-tier competitors without backward integration.
- Carbon-intensive production nodes:Evolving carbon border adjustment mechanisms threaten to reprice imported soluble fertilizers from key manufacturing regions.
Strategic Opportunities
- USDA National Organic Program certification:Differentiation between conventional and certified organic greenhouse berry channels creates parallel premium product lines.
- Central American substrate operations:Underpenetrated controlled-environment agriculture in Guatemala and Costa Rica offers expansion vectors for precision nutrient packages.
- Sensor-chemistry convergence:Integration of real-time ion-selective electrodes with automated dosing systems enables subscription-based nutrient management services.
Industry Challenges
- Hydroponic chemistry and berry phenology fluency:Greenhouse operators struggle to source technicians competent in both disciplines, creating bottlenecks in program deployment.
- Closed system integration complexity:Legacy irrigation infrastructure requires costly retrofitting to achieve exact ppm dosing and runoff recovery compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Berry Greenhouse Premium Micronutrient Package Market |
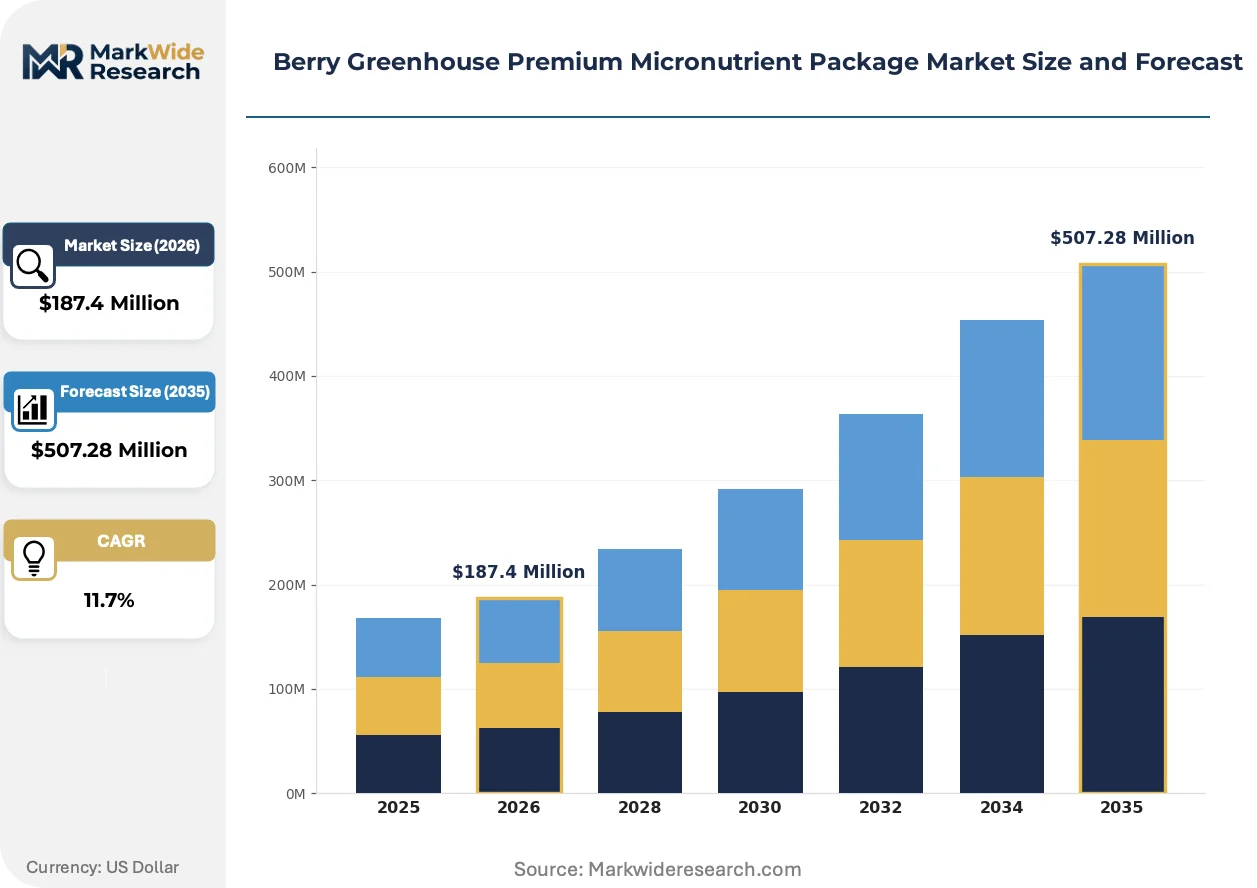
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chelated Micronutrients, Soluble Powder, Liquid Concentrate, Granules, Water-Soluble Fertilizer Application: Soil Treatment, Foliar Spray, Hydroponic Nutrient Solution, Seed Treatment, Root Zone Feeding Crop Type: Strawberries, Raspberries, Blueberries, Blackberries, Gooseberries Customer Type: Greenhouse Growers, Commercial Nurseries, Agricultural Cooperatives, Specialty Crop Producers, Research Institutions |
| Companies Covered | ICL Group, Haifa Group, Yara International, Nutrien, UPL, EuroChem Group, The Mosaic Company, The Andersons, Wilbur-Ellis Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Berry Greenhouse Premium Micronutrient Package Market Trends and Innovations
Formulation science and regulatory compliance are reshaping competitive advantage in berry greenhouse micronutrient supply, with chelation chemistry and digital dosing systems converging to redefine precision agriculture economics.
Next-generation EDDHA-Fe formulations with improved ortho-ortho isomer ratios are fragmenting the premium chelate segment by enabling lower application rates at equivalent efficacy. Dutch greenhouse cooperatives are adopting these concentrates fastest, compressing demand for standard-grade mineral salts in high-value berry operations. The technology is fragmenting legacy supplier relationships as formulators with patent access capture margin pools previously distributed across commodity channels.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of certain complexing agents used in legacy micronutrient products. Manufacturers serving EU markets must redesign synthesis pathways or exit specific product categories. Spanish and Italian greenhouse clusters face the steepest compliance timelines, with several operators accelerating supplier audits ahead of enforcement windows.
Buyer consolidation among Almería's berry marketing cooperatives is compressing supplier negotiation cycles and unbundling technical advisory services from product procurement. Large greenhouse consortia now demand standalone agronomy retainers separate from input purchases. This restructuring is most visible in strawberry and raspberry operations exceeding fifty hectares, where procurement teams centralize across multiple grower holdings.
Berry Greenhouse Premium Micronutrient Package Market Segmentation
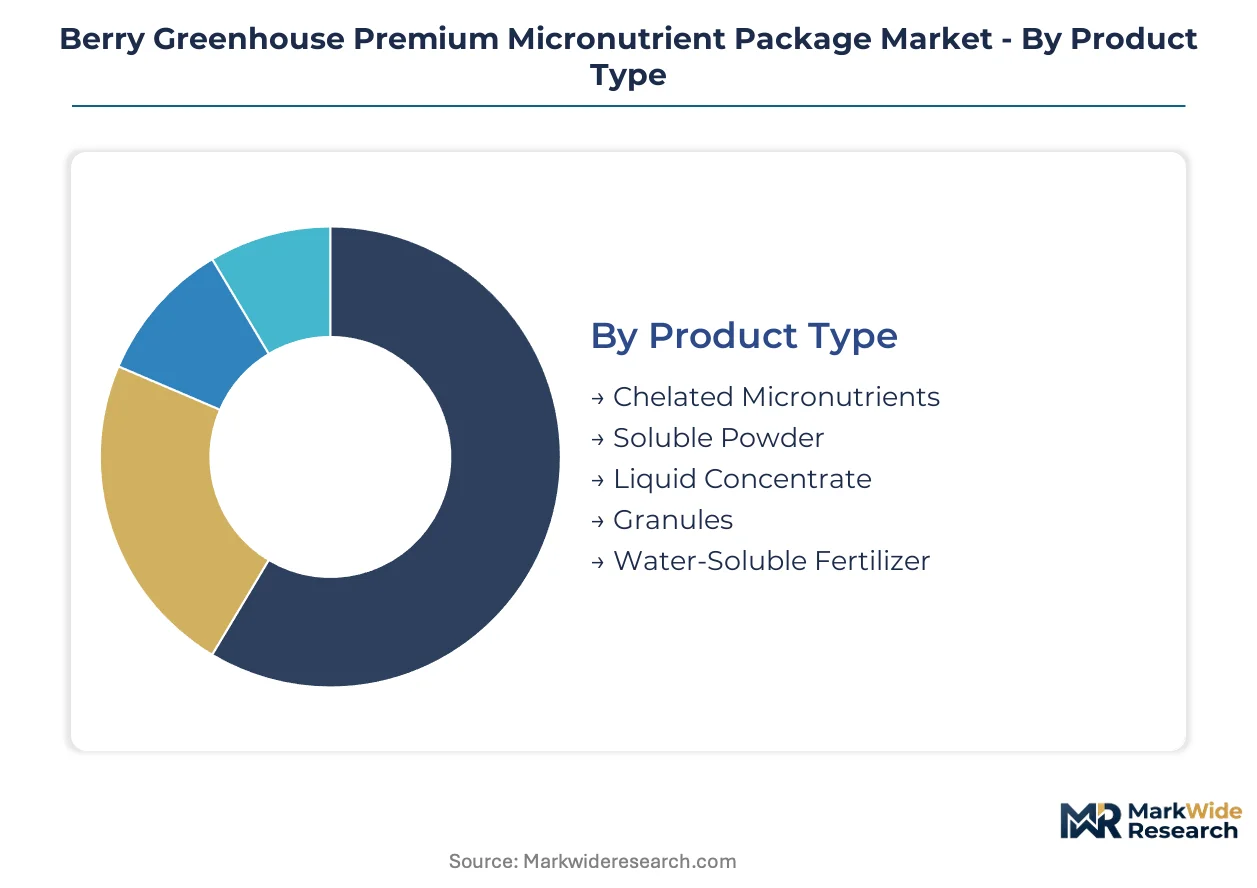
Precision dosing requirements in closed irrigation systems fragment demand across formulation chemistries and delivery mechanisms. Each segment carries distinct technical specifications, regulatory footprints, and margin structures that reshape supplier positioning.
Product Type:
Substitution pressure from next-generation chelation technologies is fragmenting legacy mineral salt demand, as greenhouse operators prioritize plant-available forms over commodity inputs.
- Chelated Micronutrients:Iron, manganese, zinc, copper, boron, and molybdenum bound to EDTA or EDDHA ligands prevent precipitation in alkaline irrigation water. Dutch greenhouse cooperatives prioritize ortho-ortho EDDHA-Fe formulations for strawberry operations requiring exact ppm control. REACH Annex XVII restrictions on persistent organic pollutants accelerate supplier reformulation timelines.
- Liquid Concentrate:Pre-dissolved solutions enable direct injection into fertigation systems without mixing infrastructure. Almería's berry marketing cooperatives centralize procurement of these concentrates across holdings exceeding fifty hectares. Sensor-driven dosing compatibility drives specification decisions.
- Soluble Powder:Dry crystalline formulations require on-site dissolution but offer lower transport costs and extended shelf stability.
- Granules:Slow-release mineral matrices suit substrate-based operations with less frequent irrigation cycles.
- Water-Soluble Fertilizer:Complete NPK-plus-micronutrient blends simplify program management for mid-scale greenhouse operators.
Chelated Micronutrients retains volume leadership; Liquid Concentrate holds the steepest expansion curve.
Application:
Cost tier stratification separates high-frequency hydroponic programs from periodic soil amendment cycles, with labor and equipment requirements driving channel selection.
- Hydroponic Nutrient Solution:Continuous recirculation systems demand chelated forms that resist oxidation and maintain bioavailability across multiple irrigation cycles. Substrate-based berry culture in Mediterranean and Central American corridors displaces field production fastest in this channel. Runoff recovery compliance mandates exact dosing precision.
- Foliar Spray:Direct leaf application bypasses root zone chemistry constraints during critical phenological windows. Raspberry operations in Spain's controlled-environment agriculture corridors deploy targeted sprays during fruit set to prevent deficiency-induced abortion. Application timing aligns with brix accumulation targets.
- Soil Treatment:Pre-plant incorporation of micronutrient packages addresses legacy substrate depletion.
- Root Zone Feeding:Localized placement near active root hairs improves uptake efficiency in established plantings.
- Seed Treatment:Prophylactic coating of propagation material reduces early-stage deficiency risk.
Hydroponic Nutrient Solution commands the premium tier; Foliar Spray is climbing the fastest among established greenhouse operators.
Crop Type:
Customer type concentration among berry marketing cooperatives concentrates procurement power toward cultivars with extended shelf-life breeding.
- Strawberries:High-value cultivars bred for export shelf life exhibit elevated micronutrient demand during fruit expansion phases. Almería's greenhouse consortia prioritize iron and boron management to prevent physiological disorders. Brix optimization protocols differentiate premium fruit grades.
- Raspberries:Continuous fruiting varieties require sustained micronutrient availability across extended harvest windows. Dutch precision fertigation programs deploy sensor-chemistry convergence for real-time adjustment. Deficiency-induced flower abortion carries severe economic penalty.
- Blueberries:Acid-loving species require specialized pH-buffered formulations uncommon in general greenhouse programs.
- Blackberries:Thornless greenhouse varieties gain traction in Mediterranean export corridors.
- Gooseberries:Niche demand concentrates in Northern European specialty operations.
Strawberries retains volume leadership; Raspberries holds the steepest expansion curve.
Customer Type:
Supply concentration among formulators with captive phosphate and potassium integration shapes access tiers for buyers without backward integration.
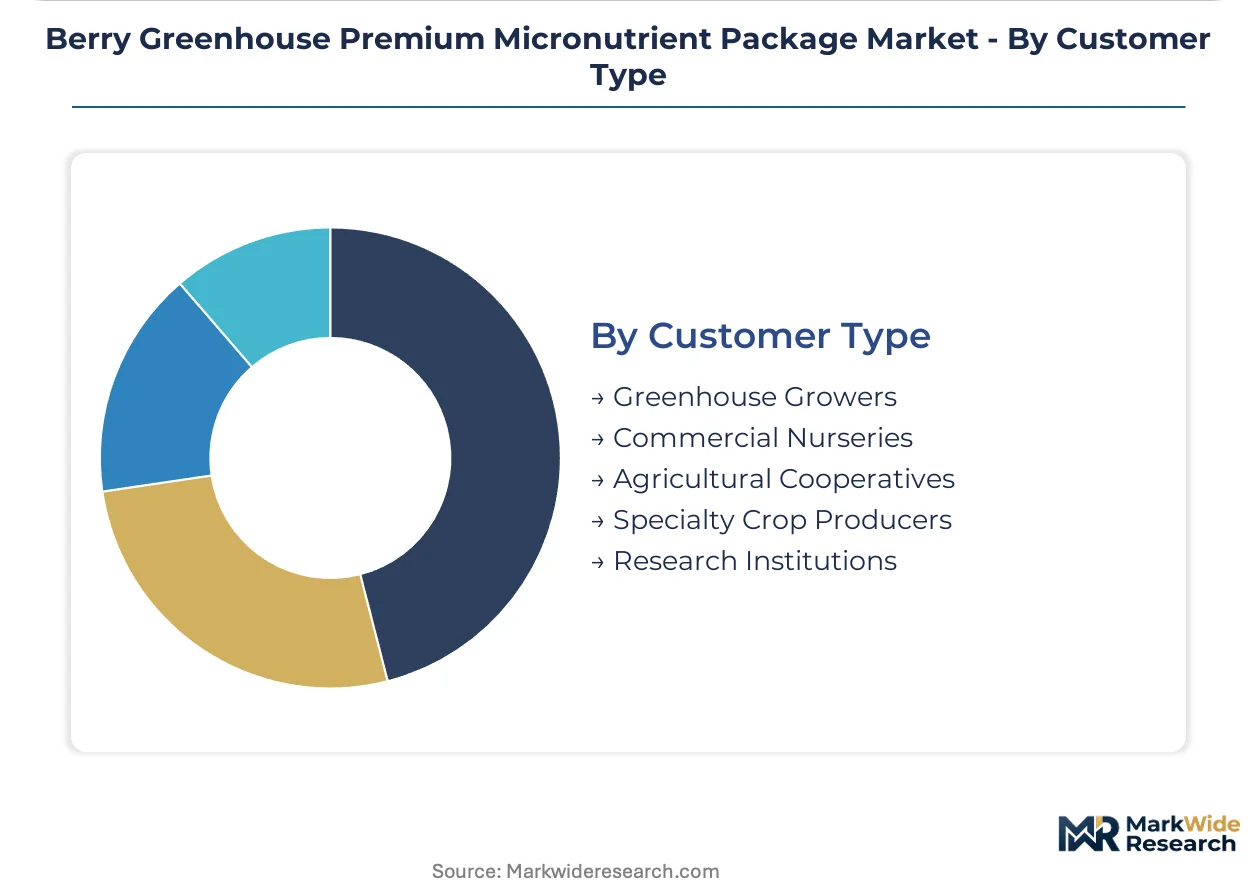
- Greenhouse Growers:Commercial operators with sensor-driven infrastructure demand technical advisory services bundled with precision formulations. Netherlands-based operations lead adoption of automated dosing systems. Procurement teams centralize across multiple grower holdings exceeding fifty hectares.
- Agricultural Cooperatives:Consolidated buying power enables standalone agronomy retainers separate from product procurement. Spanish berry marketing cooperatives compress supplier negotiation cycles through volume concentration. Technical service unbundling accelerates.
- Commercial Nurseries:Propagation specialists require consistent micronutrient protocols for young plant establishment.
- Specialty Crop Producers:Diversified operations balance greenhouse berry programs with other high-value crops.
- Research Institutions:Trial programs drive early adoption of next-generation EDDHA formulations with improved isomer ratios.
Greenhouse Growers retains volume leadership; Agricultural Cooperatives is gaining share fastest through procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Annex XVII restrictions on persistent organic pollutants anchor European regulatory stringency, forcing micronutrient formulators to redesign synthesis pathways ahead of enforcement windows. The report maps demand concentration across five greenhouse berry production clusters where precision fertigation infrastructure is scaling fastest.
Netherlands
Sensor-driven dosing systems now dominate commercial greenhouse operations exceeding fifty hectares, with Dutch cooperatives prioritizing ortho-ortho EDDHA-Fe formulations for strawberry cultivars. The EU Fertilizing Products Regulation tightens cadmium thresholds on imported mineral sources, accelerating domestic reformulation investments. Westland and Aalsmeer greenhouse clusters deploy automated nutrient management services as subscription offerings.
Spain
Almería's controlled-environment agriculture corridors displace field production fastest among Mediterranean berry operations, concentrating procurement power within marketing cooperatives. REACH compliance timelines pressure Spanish formulators to audit supplier contaminant profiles before enforcement activation. The Murcia and Huelva clusters expand substrate-based raspberry culture for export shelf-life optimization.
United States
The USDA National Organic Program differentiates conventional from certified organic greenhouse berry channels, creating parallel premium product specifications for micronutrient packages. California's Central Valley and Florida's Plant City districts lead hydroponic strawberry adoption among domestic fresh market suppliers. EPA water quality standards for agricultural runoff influence closed irrigation system design in these corridors.
Mexico
Central American substrate operations in Baja California and Sinaloa offer expansion vectors for precision nutrient packages targeting export-oriented berry production. Mexican greenhouse operators balance USMCA trade access against evolving carbon border adjustment mechanisms on imported soluble fertilizers. The Querétaro and Michoacán clusters attract Dutch technical advisory partnerships for fertigation deployment.
Canada
Health Canada's PMRA regulates micronutrient residue limits in greenhouse berry exports to US and Asian markets, shaping formulation specifications for cross-border suppliers. Ontario's Leamington greenhouse district and British Columbia's Fraser Valley concentrate domestic strawberry and raspberry production under precision irrigation. Provincial carbon pricing mechanisms increasingly factor into fertilizer import cost structures.
Berry Greenhouse Premium Micronutrient Package Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Berry Greenhouse Premium Micronutrient Package Market. Captive phosphate and potassium supply chains anchor cost structures for dominant players, squeezing mid-tier competitors lacking backward integration. Three archetypes define competitive positioning: chelation chemistry specialists with patent-protected ligand access, integrated fertilizer conglomerates with mineral supply control, and regional formulators serving local greenhouse clusters. Consolidation through strategic partnerships and technology licensing agreements is accelerating as REACH compliance costs rise.
Within the integrated chemistry tier, ICL Group and Haifa Group exemplify divergent strategic anchors. ICL Group represents the mineral supply-integrated archetype, with captive raw material positions supporting cost discipline across formulation portfolios. Haifa Group occupies the water-soluble heritage specialist position, leveraging decades of fertigation chemistry expertise in premium liquid concentrate development. Yara International sits within the global nitrogen and complete nutrient blend segment, serving greenhouse operators seeking simplified program management. These three entities collectively illustrate how chelation patent access and upstream supply control partition margin capture in European and Mediterranean markets.
| Leading Market Players |
|---|
| ICL Group |
| Haifa Group |
| Yara International |
| Nutrien |
| UPL |
| EuroChem Group |
| The Mosaic Company |
| The Andersons |
| Wilbur-Ellis Company |
| Others |
Pricing and Supply Chain Analysis
EU Fertilizing Products Regulation certification gates both supplier qualification and price differentiation simultaneously, as compliant chelated formulations command substantial premiums over legacy mineral salts while excluding non-reformulated competitors from Dutch and Spanish procurement channels. Greenhouse operators in Almería and Westland face parallel pressures: sourcing plant-available micronutrients that satisfy tightening cadmium thresholds while managing input cost structures across sensor-driven dosing infrastructure investments.
Pricing Analysis
Geographic price spreads of 40-60% separate premium ortho-ortho EDDHA-Fe concentrates in Dutch greenhouse cooperatives from standard-grade mineral salts in less regulated Mediterranean markets. Three-tier pricing structure across premium chelated, certified-compliant standard, and economy mineral tiers reflects REACH compliance investment and patent-protected ligand access. Cost compression in the standard tier is intensifying because buyer consolidation among Almería's berry marketing cooperatives concentrates negotiation leverage. Mid-scale greenhouse operators without backward integration exhibit highest price sensitivity, while Dutch precision fertigation adopters prioritize dosing precision over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate Dutch greenhouse corridors where sensor-driven systems enable weekly nutrient solution adjustments, while Spanish operators maintain strategic stockpiles of liquid concentrates to buffer against supplier audit delays under REACH enforcement timelines. Manufacturing concentration in Israel, Belgium, and Spain feeds European demand, with captive phosphate and potassium supply anchoring cost structures for integrated leaders. Raw material dependencies on phosphoric acid, potassium salts, and EDTA/EDDHA chelating agents create vulnerability to commodity price volatility in energy-intensive synthesis pathways. Distribution runs through agricultural cooperatives and direct technical partnerships rather than commodity chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent formulators face substitution pressure from next-generation biological micronutrient delivery systems and mineral salt recyclers targeting closed-loop irrigation compliance, requiring defensive repositioning around irreplaceable technical advisory capabilities.
For Market Incumbents: Compound technical service differentiation by unbundling precision agronomy retainers from product procurement, creating standalone subscription revenue streams that biological substitutes cannot replicate. Deepen backward integration into chelating agent synthesis to defend margin pools as REACH reformulation costs rise and patent-protected EDDHA isomer technologies fragment competitive positioning.
For New Entrants and Emerging Players: Technical advisory capacity gaps in Central American substrate operations offer white-space entry points where Dutch and Israeli incumbents lack localized agronomy infrastructure. Guatemala and Costa Rica present the most penetrable expansion corridors for precision nutrient packages, with sensor-chemistry convergence as the differentiated go-to-market angle against commodity fertilizer distributors.
For Investors and Strategic Acquirers: REACH Annex XVII enforcement reshapes the acquisition landscape toward formulators with proven synthesis pathway redesign capabilities and existing EU regulatory dossiers. Long-term viability across the projection horizon favors mid-tier specialists with captive chelation chemistry expertise over commodity blenders lacking technical differentiation. Watch for carbon border adjustment mechanism activation as the inflection signal repricing imported soluble fertilizers from carbon-intensive production nodes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chelating Agent Synthesis | Captive EDTA and EDDHA production secures margin pools as REACH compliance costs exclude non-integrated competitors from Dutch and Spanish procurement channels. |
| Sensor-Chemistry Convergence Partnership | Integration with Dutch ion-selective electrode manufacturers enables subscription-based nutrient management services beyond commodity fertilizer sales. |
| Central American Technical Advisory Expansion | Localized agronomy infrastructure in Guatemala and Costa Rica captures substrate-based berry culture displacement before incumbent formulators establish presence. |
| Organic Certification Product Line Diversification | USDA National Organic Program-compliant formulations create parallel premium channels with distinct specification barriers against conventional competitors. |
| Next-Generation EDDHA Isomer Patent Licensing | Improved ortho-ortho ratio technologies fragment legacy supplier relationships and concentrate margin capture among patent-accessible formulators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Dutch greenhouse cooperative agronomists, Spanish berry marketing cooperative procurement directors, Central American substrate operation managers, and chelated micronutrient formulator technical directors. Secondary validation drew from EU Fertilizing Products Regulation enforcement documentation, REACH Annex XVII restriction timelines, USDA National Organic Program substance lists, customs trade data on water-soluble fertilizer imports, and SEC filings of integrated fertilizer conglomerates. Bottom-up volume modeling across formulation chemistries and application channels triangulated against top-down market sizing from greenhouse area expansion projections and micronutrient intensity per hectare benchmarks.
Across the analysis window, forecasts employed a segmented growth framework modeling product type substitution dynamics, application channel expansion rates, crop-specific micronutrient intensity curves, and customer type procurement centralization patterns. CAGRs were derived from regression analysis of historical pricing and volume relationships, adjusted for regulatory inflection impacts. Industry-specific inputs included Almería controlled-environment agriculture area expansion, Dutch sensor-driven dosing adoption rates, and REACH compliance timeline enforcement probability weightings.
Underlying assumptions cover sustained substrate-based berry culture displacement, stable chelating agent patent enforcement, and gradual carbon border adjustment mechanism implementation, with deviation risk concentrated in regulatory enforcement acceleration or biological micronutrient technology breakthroughs. Revision becomes warranted when biological substitute efficacy crosses commercial viability thresholds or REACH enforcement windows accelerate beyond modeled timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Neonicotinoid Insecticides Market