
 North America Soil Treatment Market | 2026-2036
North America Soil Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soil Treatment Market Analytics
Specialty horticulture is consolidating as the fastest-expanding demand vertical across the North America Soil Treatment Market. Corteva Agriscience leverages its germplasm-linked input bundles to anchor grower loyalty across high-value vegetable regions. BASF SE sustains R&D intensity in microbial inoculant formulations, while Novozymes A/S specializes in enzyme-based soil amendment platforms that differentiate its portfolio from synthetic competitors.
Soil treatment encompasses the mechanical, chemical, and biological modification of soil properties to optimize plant growth, water retention, and contaminant remediation, typically involving pH adjustment through lime or sulfur application, organic matter incorporation, and targeted microbial inoculation at application rates of 10^8 to 10^9 colony-forming units per gram. Its primary commercial purpose centers on restoring degraded agricultural land and maintaining productivity in intensive cropping systems. Biopesticides represent the fastest-growing product category as resistance management protocols and residue limits tighten across export-oriented production. Nutrient management applications command the deepest margin pools where precision agriculture integration allows variable-rate pricing. Granular formulations dominate volume in row-crop applications, though liquid microbial products capture premium positioning in specialty fruit and vegetable systems.
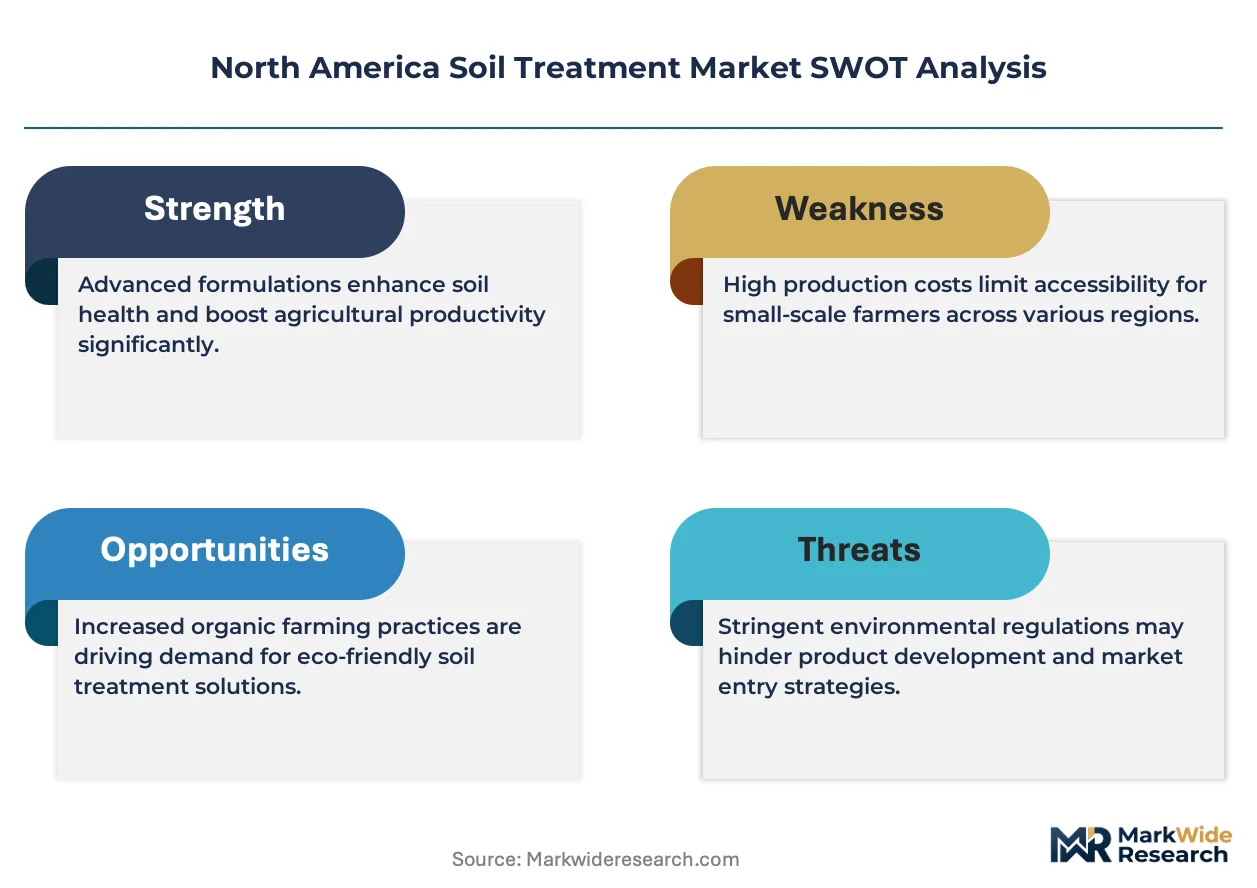
The EPA regulates soil treatment products through distinct pathways for chemical pesticides, biopesticides, and plant-incorporated protectants, with state departments of agriculture in Iowa, Illinois, and Nebraska enforcing supplemental certification requirements for nutrient management planners. The USDA's Natural Resources Conservation Service incentivizes cover crop adoption through Environmental Quality Incentives Program contracts that directly expand the soil amendments addressable market. Stakeholders must monitor how emerging per- and polyfluoroalkyl substance soil screening levels reshape remediation demand and product liability exposure across former industrial agricultural sites.
Market Dynamics
State-level fertilizer restriction laws in the Chesapeake Bay watershed are forcing product development pivots across the North America Soil Treatment Market. The EPA's streamlined biopesticide registration pathways simultaneously accelerate biological amendment commercialization.
Growth Catalysts
- USDA Environmental Quality Incentives Program:Cover crop adoption contracts expand the soil amendments addressable market through direct producer payments.
- Precision agriculture integration:Variable-rate nutrient management protocols in Iowa, Illinois, and Nebraska create demand for site-specific soil testing services.
- Specialty horticulture expansion:California and Florida vegetable producers are scaling biological amendment programs to meet export residue limits.
Market Restraints
- Phosphate rock price volatility:Concentrated Moroccan and Chinese supply exposes North American fertilizer blenders to input cost shocks.
- Per- and polyfluoroalkyl substance liability:Emerging soil screening levels at former industrial agricultural sites reshape remediation demand unpredictably.
- Microbial inoculant shelf-life constraints:Colony-forming unit degradation limits distribution radius for live biological products.
Strategic Opportunities
- Enzyme-based amendment platforms:Novozymes-style formulations differentiate from synthetic competitors in high-value fruit systems.
- Nebraska and Kansas wheat belts:Underpenetrated biological inoculant adoption offers first-mover positioning ahead of nutrient management mandates.
- Carbon credit stacking:USDA NRCS contract structures allow soil health practices to qualify for multiple payment mechanisms.
Industry Challenges
- Certified crop adviser pipeline:State nutrient management planner certification requirements in the Corn Belt outpace qualified professional supply.
- Legacy soil testing integration:Variable-rate application systems require retrofitting incompatible farm management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soil Treatment Market |
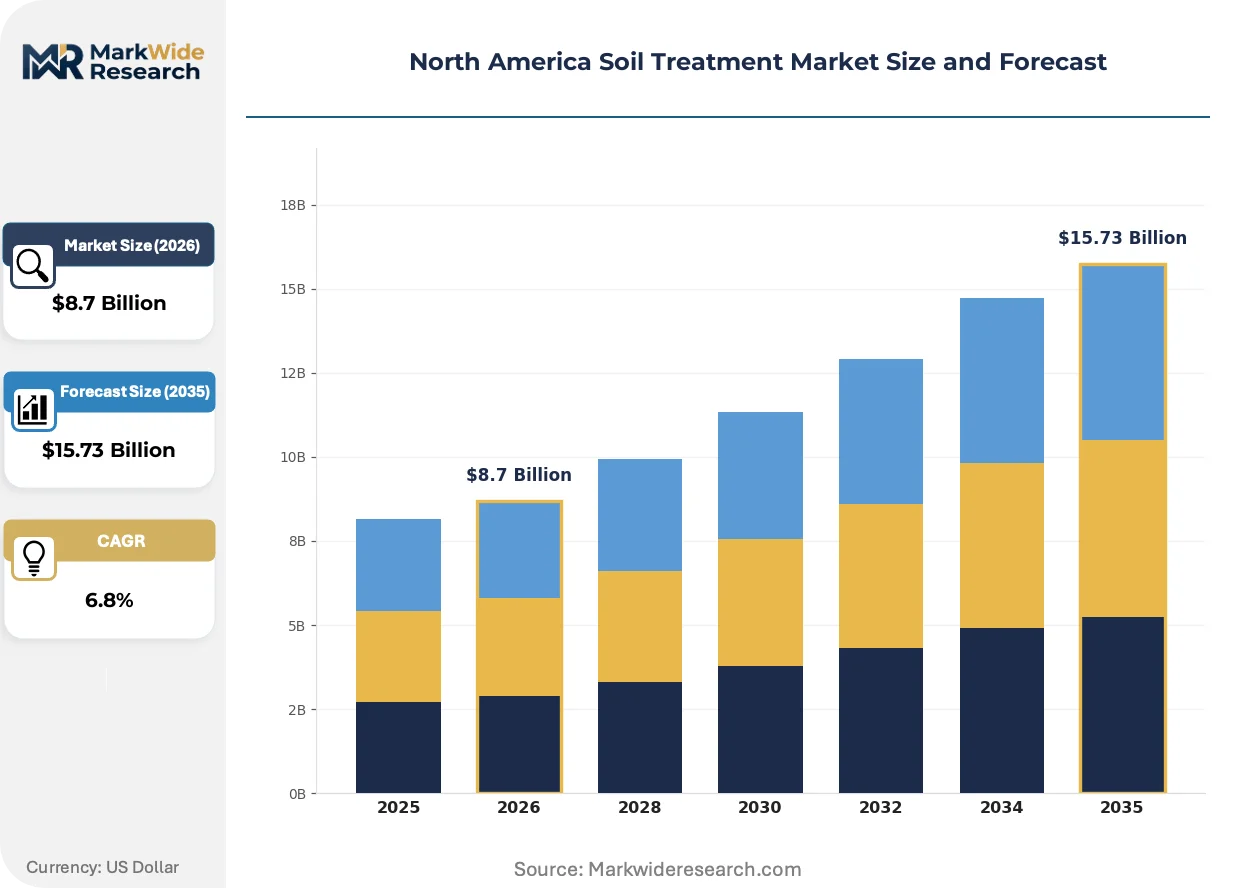
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Biopesticides, Soil Amendments, Cover Crops End Use Industry: Agriculture, Landscaping, Golf Courses, Horticulture Application: Soil Restoration, Nutrient Management, Erosion Control, Pest Management Form: Granular, Liquid, Powder, Aerosol |
| Companies Covered | Certis USA Llc, Agraquest Inc., BASF SE, Corteva Agriscience, American Vanguard Corporation, Syngenta AG, Amvac Chemical Corporation, UPL Limited, Novozymes A/S, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soil Treatment Market Evolving Landscape
Biological soil amendments are displacing synthetic chemistry across export-oriented production systems. Regulatory acceleration and precision application hardware are compressing traditional product development cycles.
RNA-interference biopesticides are rewriting resistance management protocols in specialty crop regions. California strawberry and Florida tomato growers are piloting these formulations at commercial scale. The technology is compressing synthetic fungicide application windows while demanding new soil microbiome monitoring capabilities.
The EPA's evolving biopesticide registration pathways are compressing time-to-market for microbial inoculants. Fast-track reviews for products with established safety profiles redirect R&D investment toward formulation science rather than toxicology studies. California Department of Pesticide Regulation conditional approvals are accelerating field trial expansion for Bacillus-based amendments.
Outcome-based service contracts are displacing product-centric sales in large row-crop operations. Iowa and Illinois grain producers now contract for yield-per-acre guarantees rather than purchasing inputs directly. Agronomic service providers absorb input price volatility while capturing margin through performance bonuses tied to soil health metrics.
North America Soil Treatment Market Segmentation
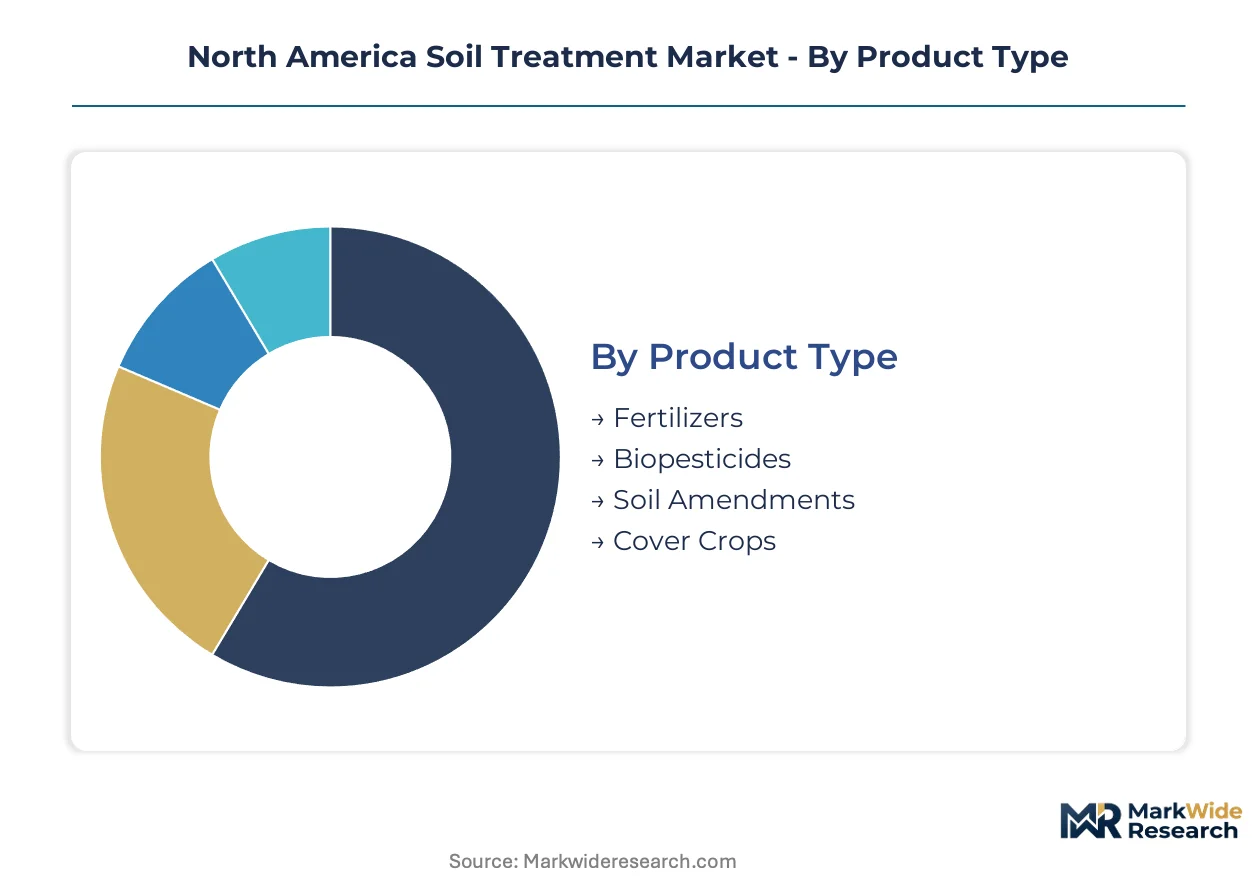
Soil treatment purchasing patterns diverge sharply between commodity row-crop operators and high-value specialty producers. Product selection hinges on regulatory compliance obligations, export market residue requirements, and precision agriculture infrastructure maturity.
Product Type:
Cost tier separates price-sensitive broadacre adopters from premium-paying specialty crop operators.
- Fertilizers:Nitrogen, phosphorus, and potassium formulations remain the volume foundation, with variable-rate application protocols in Iowa and Illinois Corn Belt states driving demand for customized N-P-K blends. Phosphate rock price volatility from concentrated Moroccan supply exposes blenders to margin compression.
- Biopesticides:Microbial inoculants and biochemical extracts command premium positioning as California strawberry and Florida tomato growers pilot RNA-interference formulations at commercial scale. EPA fast-track registration pathways accelerate Bacillus-based amendment commercialization.
- Soil Amendments:Lime, gypsum, and organic matter incorporation address pH adjustment and water retention in degraded agricultural land.
- Cover Crops:USDA Environmental Quality Incentives Program contracts expand the addressable market through direct producer payments for legume and grass mixtures.
Fertilizers lead volumes today; biopesticides are gaining share fastest.
End Use Industry:
Application intensity and residue limit exposure create divergent customer economics across verticals.
- Agriculture:Corn Belt grain operations and California specialty vegetable producers constitute the core demand base, with nutrient management plans in Iowa, Illinois, and Nebraska mandating soil testing protocols that expand amendment consumption.
- Horticulture:High-value fruit and vegetable systems in Florida and California drive biological amendment adoption as export residue limits tighten. Precision application hardware enables variable-rate pricing capture.
- Landscaping:Commercial turf and ornamental installations in metropolitan corridors generate steady seasonal demand for soil restoration products.
- Golf Courses:Intensive turf management protocols in resort destinations and private clubs sustain premium product positioning for erosion control and nutrient management formulations.
Agriculture dominates revenue today; horticulture is expanding most quickly.
Application:
Margin structure varies by technical complexity and outcome measurability.
- Nutrient Management:Precision agriculture integration enables variable-rate pricing and site-specific soil testing services, creating the deepest margin pools where agronomic service providers contract for yield-per-acre guarantees.
- Soil Restoration:Degraded land reclamation and former industrial agricultural site remediation face emerging per- and polyfluoroalkyl substance liability exposure that reshapes demand unpredictably.
- Pest Management:Resistance management protocols compress synthetic fungicide application windows while demanding new soil microbiome monitoring capabilities in specialty crop regions.
- Erosion Control:Cover crop adoption and structural amendment programs address water retention and topsoil preservation across sloped terrain.
Nutrient management leads margins today; soil restoration is climbing the fastest.
Form:
Distribution economics and shelf-life constraints segment the supply base.
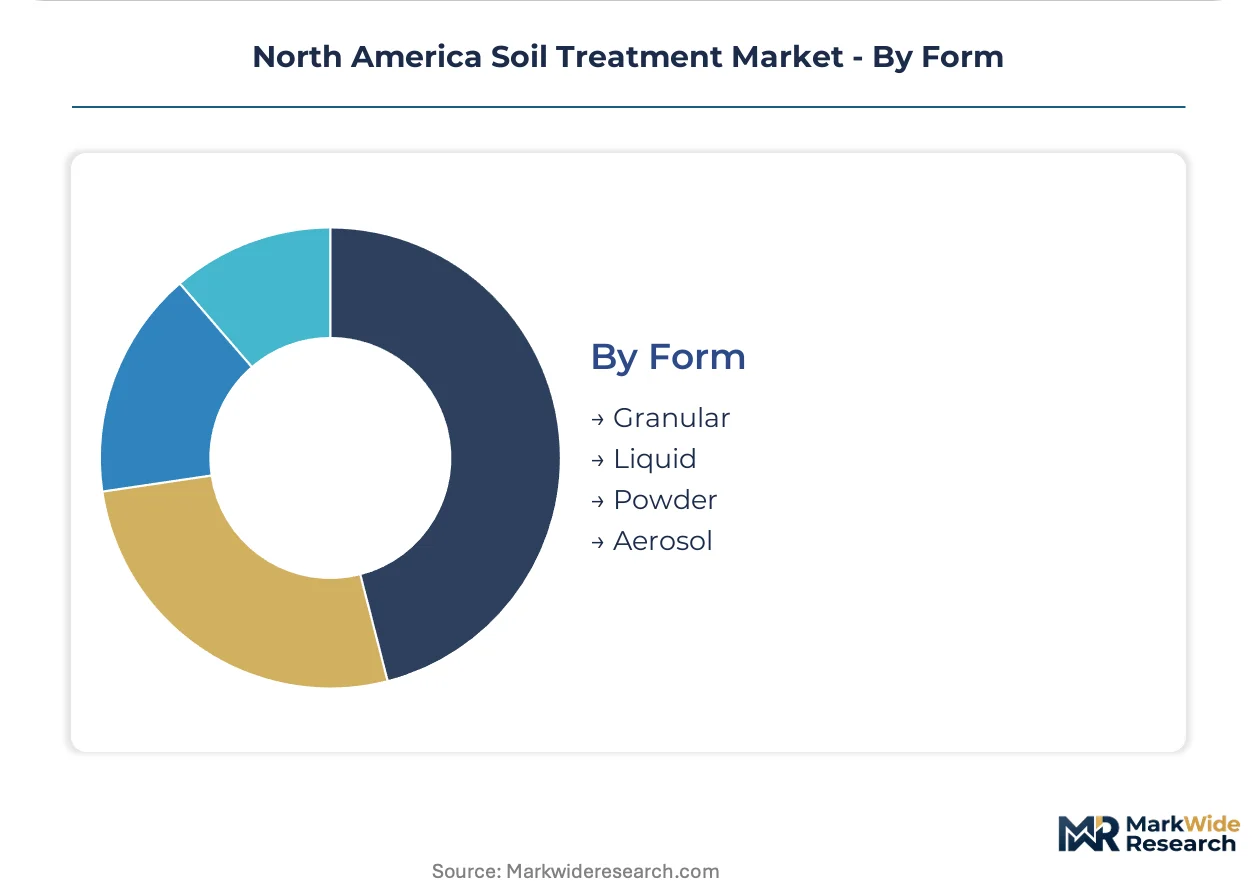
- Granular:Dry formulations dominate volume in row-crop applications, with mechanical spreading compatibility and extended storage stability supporting broadacre adoption across the Corn Belt.
- Liquid:Microbial suspensions and soluble concentrates capture premium positioning in specialty fruit and vegetable systems where fertigation infrastructure enables precise delivery.
- Powder:Fine-ground amendments address pH adjustment and targeted nutrient delivery in smaller-scale horticultural operations.
- Aerosol:Pressurized delivery systems serve niche pest management applications with limited soil treatment penetration.
Granular leads volumes today; liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate soil treatment product development in jurisdictions with streamlined biopesticide pathways. The EPA's fast-track registration protocols attract R&D investment away from states with restrictive fertilizer laws. This compliance-cost gradient redistributes manufacturing capacity toward research clusters with favorable permitting timelines.
United States
Corn Belt nutrient management mandates in Iowa, Illinois, and Nebraska drive precision soil testing adoption. The USDA's Environmental Quality Incentives Program channels direct payments into cover crop expansion. California's Central Valley specialty vegetable producers anchor biological amendment demand as export residue limits tighten.
Canada
Prairie province grain operations adopt variable-rate nutrient protocols to optimize fertilizer efficiency. Health Canada's PMRA regulates biopesticide registration with timelines that lag EPA pathways by 12-18 months. Ontario's greenhouse vegetable sector concentrates biological inoculant demand near Leamington processing clusters.
Mexico
Bajío region berry and avocado exporters drive biological amendment adoption to meet US and EU residue standards. Mexico's national agricultural regulator, SENASICA, coordinates with EPA on biopesticide data requirements. Sinaloa's winter vegetable production belt represents the fastest-expanding addressable market for microbial inoculants.
North America Soil Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational agrichemical conglomerates dominating volume in row-crop fertilizers while biological specialists capture premium positioning in specialty horticulture. The vendor base organizes into three tiers: integrated input bundlers with germplasm-linked offerings, microbial R&D specialists with formulation science capabilities, and regional blenders serving localized nutrient management needs. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing distribution access through agronomic service provider networks.
Among the integrated agrichemical tier, BASF SE and Corteva Agriscience occupy positions defined by germplasm-linked input bundles and microbial R&D intensity respectively. Novozymes A/S represents the enzyme-based formulation archetype, differentiating through biological platforms rather than synthetic chemistry. These three anchors exemplify how competitive positioning stratifies across the biological-synthetic divide.
| Leading Market Players |
|---|
| Certis USA Llc |
| Agraquest Inc. |
| BASF SE |
| Corteva Agriscience |
| American Vanguard Corporation |
| Syngenta AG |
| Amvac Chemical Corporation |
| UPL Limited |
| Novozymes A/S |
| Others |
Value Network & Pricing Analysis
Captive phosphate rock sourcing anchors North American fertilizer blenders against Moroccan supply concentration, insulating pricing power from spot-market volatility while locking margin structure to vertical integration depth. This upstream control separates integrated agrichemical conglomerates from regional blenders exposed to input cost shocks.
Pricing Analysis
Distributor margin layering separates synthetic fertilizer commoditization from biological amendment premium capture. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and microbial viability guarantees. Cost compression in standard-grade N-P-K blends is intensifying because phosphate rock price volatility feeds directly into blender margin pressure. Commodity row-crop operators exhibit highest price sensitivity, while California specialty vegetable producers absorb premium positioning for residue-compliant biological inputs.
Supply Chain Analysis
Regional distribution centers in Iowa, Illinois, and Nebraska form hub-and-spoke patterns radiating from Corn Belt nutrient management clusters. Manufacturing concentrates in the United States, Canada, and Mexico under USMCA tariff alignment. Raw material flows draw from Moroccan phosphate rock, Canadian potash, and domestic nitrogen production. Single-source vulnerability in Bacillus strain supply threatens microbial inoculant formulation continuity. Distribution runs through agronomic service provider networks that bundle soil testing with amendment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA biopesticide registration acceleration compounds demand velocity through streamlined commercialization pathways.
For Market Incumbents: Extend germplasm-linked input bundles into outcome-based service contracts that absorb grower price volatility. Defensive consolidation through microbial R&D facility expansion in California counters emerging enzyme-based specialists threatening premium positioning. Backward integration into phosphate rock alternatives reduces exposure to Moroccan supply concentration.
For New Entrants and Emerging Players: Begin with underpenetrated wheat belt geographies in Nebraska and Kansas where nutrient management mandates have yet to enforce biological adoption. Specialty horticulture microbial inoculants offer the most penetrable segment given residue limit pressure and limited incumbent formulation diversity. Direct agronomic service provider partnerships bypass distributor margin capture.
For Investors and Strategic Acquirers: Roll-up economics work for regional soil testing laboratories because certified crop adviser scarcity creates captive customer relationships with multi-year contract visibility. Five-to-ten year viability hinges on precision agriculture integration depth rather than commodity amendment volume. Watch EPA biopesticide fast-track approval velocity as the signal indicating biological product development cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbial R&D Facility Expansion | BASF and Novozymes-style formulation capabilities anchor premium positioning in California specialty crops. |
| Outcome-Based Service Contracts | Iowa grain producers now contract yield guarantees rather than purchasing inputs directly. |
| Backward Integration into Phosphate Alternatives | Reduces blender exposure to concentrated Moroccan supply and Chinese export policy. |
| Precision Agriculture Platform Integration | Variable-rate application hardware enables site-specific pricing capture in Corn Belt states. |
| Carbon Credit Stacking Certification | USDA NRCS contract structures qualify soil health practices for multiple payment mechanisms. |
Research Methodology
Bottom-up acreage modeling reconciled against top-down nutrient application rate tracking forms the analytical core of this study. Primary interviews with certified crop advisers, fertilizer blender procurement managers, EPA registration specialists, and specialty crop agronomists informed demand segmentation. Secondary validation drew from USDA NRCS contract databases, EPA biopesticide registration filings, state nutrient management plan submissions, and customs phosphate rock import records. Top-down and bottom-up estimates triangulated through cross-reference against agronomic service provider revenue disclosures.
Historical trendline analysis across treatment intensity metrics and product category mix shifts anchored projection methodology. Segmentation dimensions modeled include product type, end-use industry, application purpose, and formulation state across the projection horizon. CAGRs derived from regression against planted acreage forecasts and regulatory mandate implementation timelines. Industry-specific inputs incorporated EPA registration pipeline velocity and state-level fertilizer restriction law adoption curves.
Several conditions sit outside the modeled scope, including unscheduled regulatory reversals, extreme weather disruption to planting cycles, and breakthrough synthetic chemistry obsoleting biological alternatives. Forecasts reflect documented assumptions about mandate enforcement consistency and grower compliance cost tolerance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market