
 Asia Pacific Silage Inoculant Market | 2026-2036
Asia Pacific Silage Inoculant Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Silage Inoculant Market Outlook
Aftermarket technical support revenue is narrowing as manufacturers bundle on-farm application guidance with bulk direct sales. Lallemand Inc. leverages its tropical strain libraries to dominate wet-climate fermentation protocols across Southeast Asia. Kemin Industries sustains competitive positioning through in-house production of proprietary Pediococcus cultures. Cargill Inc. anchors regional supply security with licensed distributor networks spanning Indonesian dairy cooperatives.
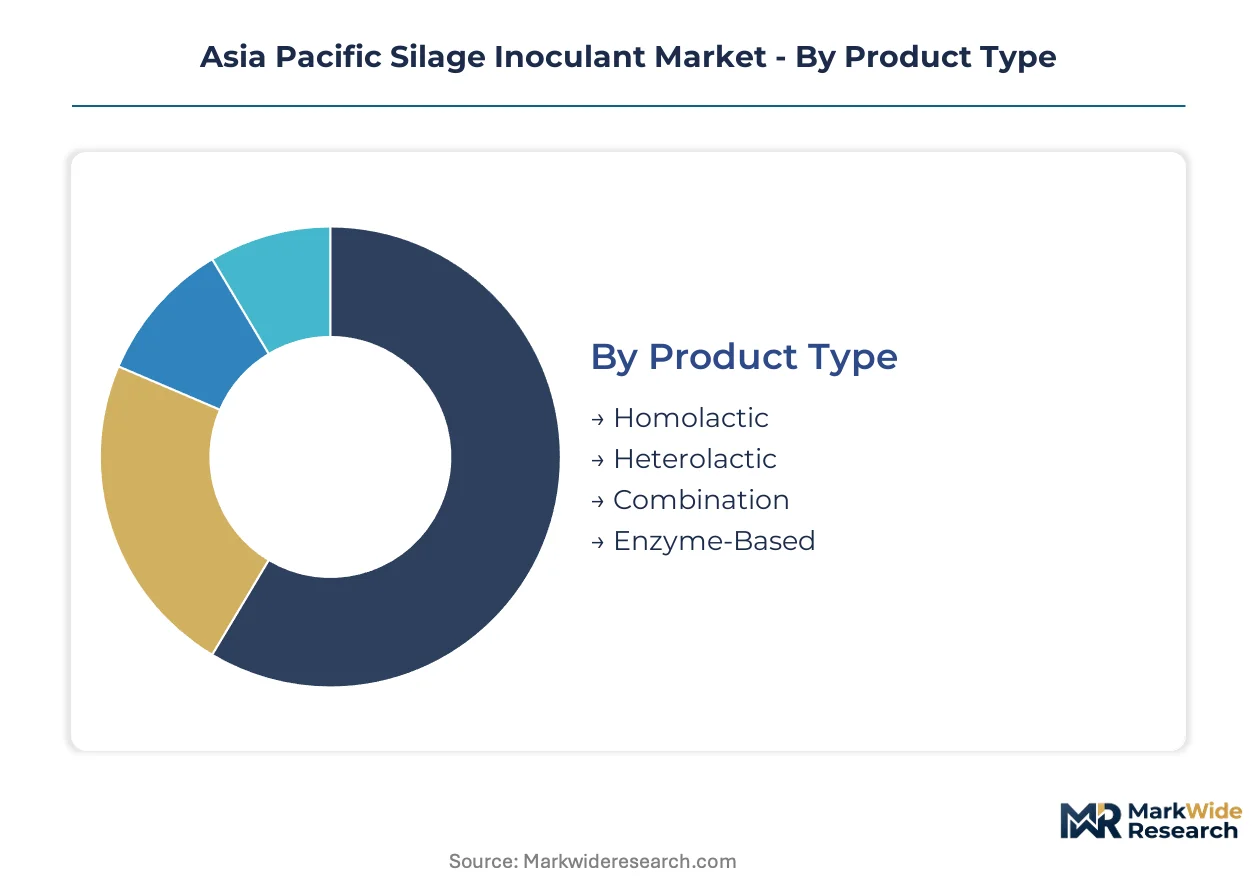
Silage inoculants are freeze-dried or liquid formulations of lactic acid bacteria, typically containing 100,000 to 1,000,000 colony-forming units per gram, applied to chopped forage to accelerate pH decline and suppress spoilage organisms during anaerobic storage. Their primary purpose is preserving nutritional value in fermented animal feed for dairy and beef operations. Homolactic strains currently occupy the largest volume share due to predictable acidification kinetics in corn and grass silages. Combination products represent the fastest-expanding category as producers seek dual-phase fermentation control across variable moisture conditions. Enzyme-based additives remain a niche margin pool, constrained by temperature sensitivity during tropical transport.
Australia's TGA and New Zealand's MPI both regulate microbial feed additives under veterinary medicine and biosecurity frameworks, requiring strain-specific safety dossiers that filter out uncertified suppliers. India's FSSAI and BIS jointly oversee feed-grade additive standards, with recent notifications tightening microbial count specifications for imported inoculants. China's SAMR enforces GB standards on fermentation product labeling, compelling reformulation disclosures that reshape competitive transparency. Stakeholders must monitor evolving strain registration timelines across these jurisdictions to avoid supply interruptions during peak harvest windows.
Market Dynamics
China's SAMR enforcement of GB standards on fermentation product labeling is compressing formulation opacity and forcing domestic manufacturers toward certified homolactic strain documentation. This regulatory pressure cascades across Southeast Asian supply chains as exporters adapt documentation protocols to maintain cross-border access.
Growth Catalysts
- Homolactic strain standardization:Predictable acidification kinetics in corn and grass silages reduce dry matter losses for dairy cooperatives in tropical storage conditions. China's feed safety regulations now mandate microbial additive documentation.
- Monsoon-season forage buffering:Cooperative dairy networks in Gujarat and Maharashtra deploy combination inoculants to manage moisture variability during harvest windows. India's FSSAI tightened microbial count specifications for imported formulations.
- Tropical fermentation protocols:Wet-climate strain libraries enable pH decline acceleration in high-humidity storage environments across Indonesia, Thailand, and Vietnam. Licensed distributor networks anchor supply security for Indonesian dairy cooperatives.
Market Restraints
- Temperature sensitivity during transport:Enzyme-based additives face viability degradation in tropical logistics corridors between manufacturing hubs and end-use farms. Cold chain gaps constrain margin expansion for specialty formulations.
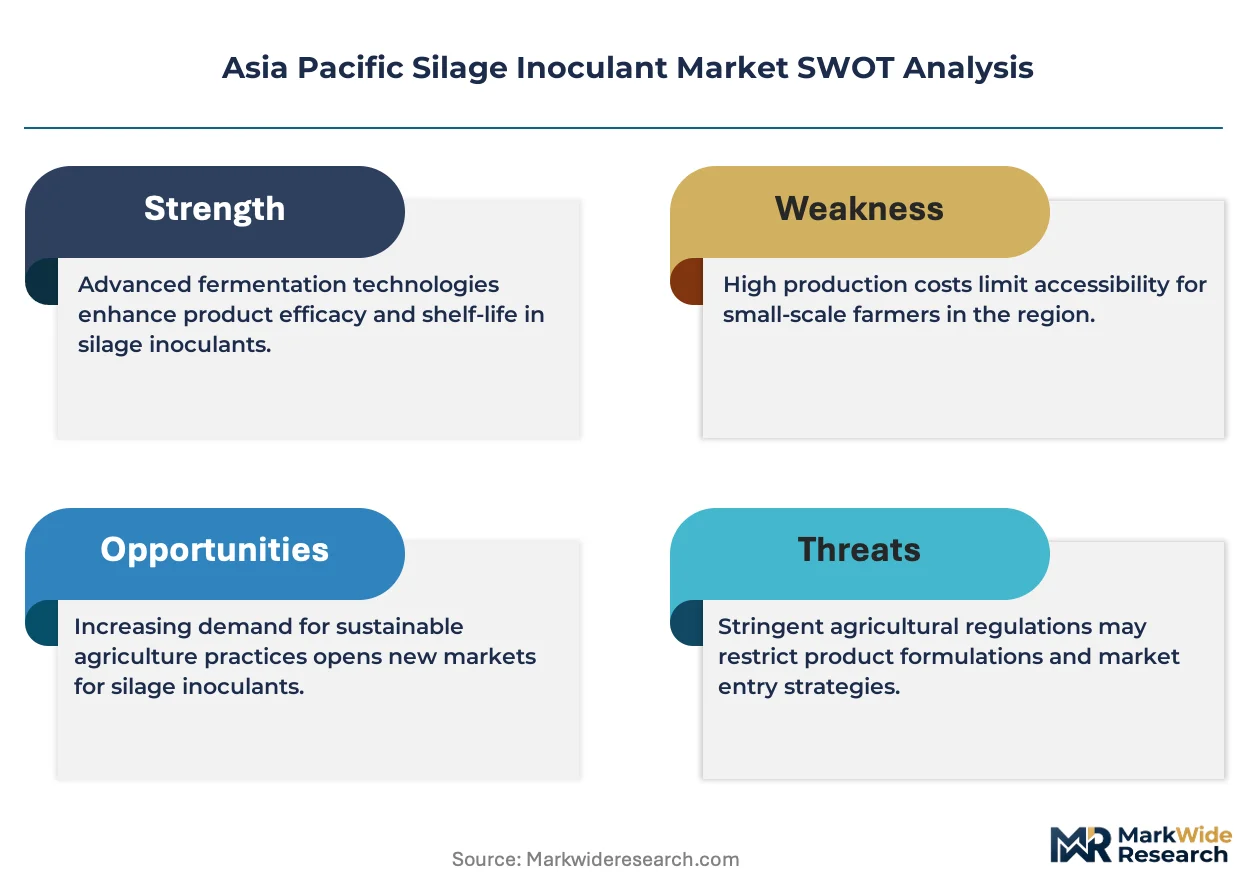
- Strain registration timeline fragmentation:Australia's TGA and New Zealand's MPI require strain-specific safety dossiers under veterinary medicine frameworks. Uncertified suppliers face automatic filtering from approved vendor lists.
- Homolactic commoditization pressure:Predictable acidification kinetics have become baseline expectations rather than differentiated value. Standard formulations face pricing compression as domestic manufacturers replicate certified protocols.
Strategic Opportunities
- Combination product penetration in Vietnam:Dual-phase fermentation control remains underdeployed in emerging dairy regions outside Ho Chi Minh City and Hanoi corridors. Local cooperatives lack technical guidance on variable moisture protocol selection.
- Direct-to-farm application bundling:Bulk sales with embedded on-farm technical support replace traditional aftermarket service contracts. Manufacturers capture margin previously allocated to distributor technical staff.
- Biosecurity framework alignment:New Zealand's MPI and Australia's TGA are harmonizing microbial feed additive safety dossier requirements. Early alignment creates preferred supplier status for cross-Tasman dairy operations.
Industry Challenges
- Strain viability verification skill gaps:Cooperative extension services in emerging dairy regions lack laboratory capacity to validate colony-forming unit counts at point of application. Farmers cannot distinguish degraded from active formulations.
- Multi-jurisdiction registration synchronization:Peak harvest windows in India, China, and Southeast Asia overlap with divergent regulatory review timelines. Supply interruptions occur when strain approvals lag seasonal demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Silage Inoculant Market |
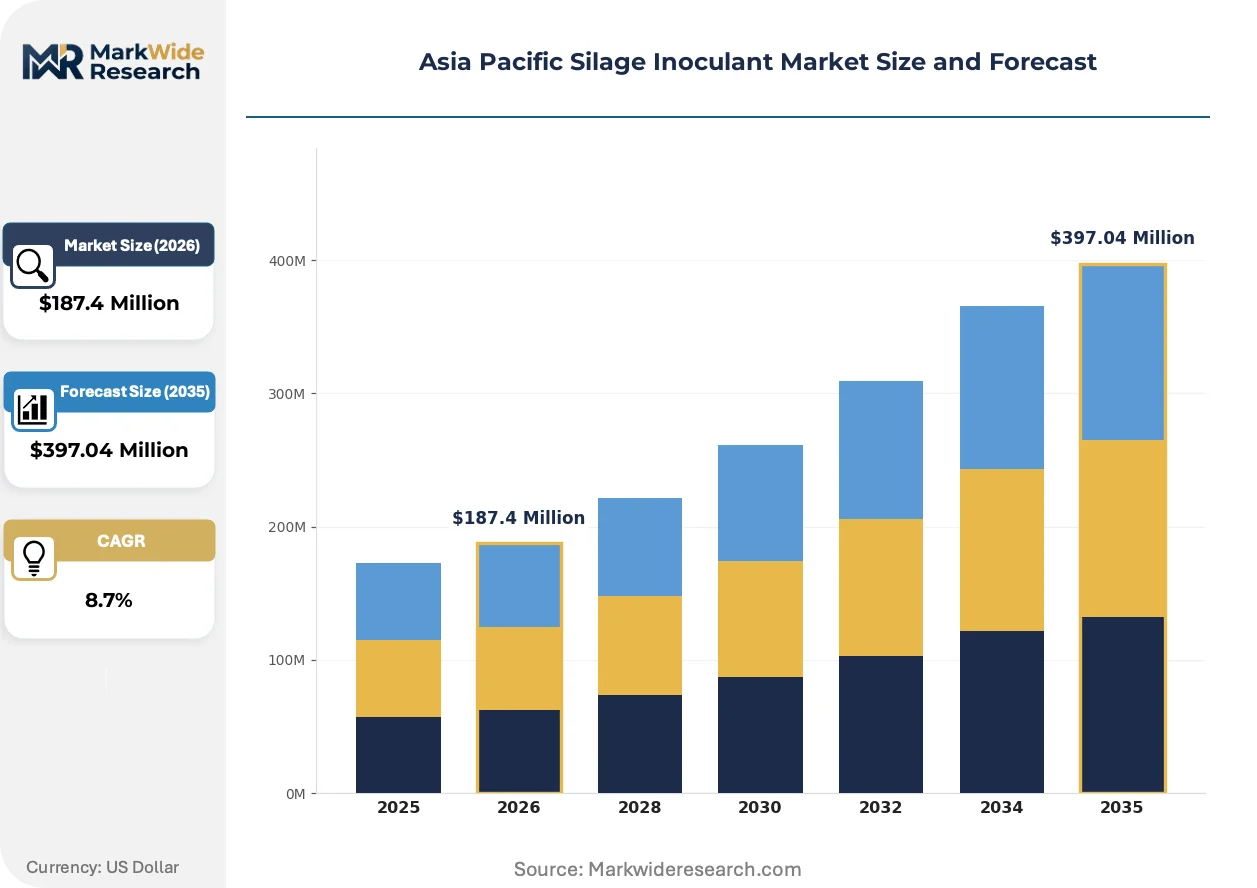
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homolactic, Heterolactic, Combination, Enzyme-Based Application: Dairy Feed, Beef Feed, Biogas Production, Other Uses Distribution Channel: Online Retail, Direct Sales, Authorized Distributors, Agricultural Supply Stores End User: Dairy Farms, Feedlots, Biogas Plants, Agronomists |
| Companies Covered | Lallemand Inc., Kemin Industries, Cargill Inc., ADM, Nutreco NV, ADDCON Group GmbH, BASF SE, Novozymes A/S, DSM N.V., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Silage Inoculant Market Strategic Shifts
Fermentation control technologies are converging with digital traceability systems across Asia Pacific dairy supply chains. This convergence is compressing opacity in formulation provenance and accelerating preference shifts toward documented strain heritage.
On-farm near-infrared spectroscopy paired with mobile application interfaces is digitizing real-time moisture and pH monitoring during ensiling. Dairy cooperatives in Maharashtra and Gujarat deploy these integrated systems during monsoon harvest windows. The technology is digitizing decision-making previously dependent on extension officer site visits, compressing response times from days to hours when fermentation deviations occur.
China's SAMR GB standards now compel disclosure of homolactic strain lineages and fermentation product labeling reformulations. Domestic manufacturers must submit certified documentation to maintain distribution licenses. Imported inoculant suppliers face the steepest compliance burden as they restructure packaging and disclosure protocols to match domestic competitor transparency levels.
Aftermarket technical support contracts are dissolving as manufacturers embed application guidance directly into bulk direct sales relationships. Indonesian dairy cooperatives now expect on-farm protocol training as a standard inclusion rather than a premium service tier. This unbundling is most visible in wet-climate regions where fermentation failure costs exceed inoculant price premiums by substantial margins.
Asia Pacific Silage Inoculant Market Segmentation
Segmentation in the Asia Pacific silage inoculant market reveals how fermentation control technologies align with distinct operational scales and climatic stressors. Product formulation choices directly map to moisture variability patterns, while distribution channel preferences reflect infrastructure maturity across emerging dairy corridors.
Product Type:
Formulation chemistry spans single-strain precision to multi-phase fermentation architectures suited to tropical harvest windows.
- Homolactic:Single-phase acidification using Lactobacillus plantarum and Pediococcus pentosaceus strains delivers rapid pH decline to 4.0-4.5 within 48 hours. Dairy cooperatives in Gujarat and Maharashtra specify these formulations for corn silage during stable pre-monsoon harvests where moisture predictability supports straightforward fermentation kinetics.
- Combination:Sequential inoculation protocols layer homolactic primary fermentation with heterolactic secondary stability control. Indonesian dairy cooperatives deploy these products across wet-season grass silages where dual-phase pH management prevents butyric acid proliferation in high-humidity storage.
- Heterolactic:Lactobacillus buchneri-based formulations prioritize aerobic stability during feed-out phases through acetic acid generation.
- Enzyme-Based:Cellulase and hemicellulase additives target fiber digestibility enhancement in low-quality forages.
The dominant share belongs to Homolactic formulations, while Combination products are closing the gap fastest.
Application:
End-use intensity correlates with herd scale and nutritional precision requirements across regional dairy development stages.
- Dairy Feed:High-value milk production operations demand consistent dry matter preservation to maintain energy-corrected milk yields. China's expanding commercial dairies in Hebei and Shandong provinces drive specification tightening for inoculant efficacy documentation under SAMR GB standards.
- Beef Feed:Feedlot operations prioritize intake maximization over fermentation precision, accepting wider pH variation in exchange for cost containment. Australian lot feeders in Queensland and New South Wales represent concentrated demand for bulk homolactic formulations in backgrounding programs.
- Biogas Production:Anaerobic digester operators apply inoculants to optimize volatile fatty acid profiles for methane yield enhancement.
- Other Uses:Specialty applications include equine nutrition and small ruminant systems with limited volume concentration.
Dairy Feed commands the largest application share, with Biogas Production expanding most quickly as renewable energy policy tightens across Southeast Asia.
Distribution Channel:
Channel selection reflects technical support requirements and procurement centralization in cooperative versus independent farm structures.
- Direct Sales:Manufacturer-to-farm relationships embed on-farm application training and fermentation monitoring protocols. Vietnamese dairy cooperatives outside Ho Chi Minh City and Hanoi corridors increasingly specify direct procurement to close technical guidance gaps in emerging production zones.
- Authorized Distributors:Licensed networks provide inventory proximity and localized regulatory compliance support. Cargill's Indonesian distributor infrastructure exemplifies this channel's role in maintaining supply security across archipelago logistics constraints.
- Agricultural Supply Stores:Retail counter sales serve smallholder segments with limited storage capacity and immediate-need purchasing patterns.
- Online Retail:E-commerce penetration remains constrained by cold-chain verification requirements and strain viability uncertainty in last-mile delivery.
Direct Sales holds the dominant channel position, though Authorized Distributors are gaining share fastest as technical bundling standardizes across regional markets.
End User:
User sophistication determines specification granularity and willingness to pay for documented strain heritage.
- Dairy Farms:Commercial operations with 500+ head capacity conduct in-house fermentation trials and demand colony-forming unit verification. India's cooperative networks in Anand and Kolhapur districts specify combination products with monsoon-season technical support packages.
- Feedlots:Large-scale beef finishing operations prioritize volume procurement and price predictability over formulation complexity. Australian feedlot accreditation schemes under MLA guidelines increasingly reference inoculant application records in environmental compliance documentation.
- Biogas Plants:Industrial digester operators seek fermentation additives that stabilize input variability from agricultural residues.
- Agronomists:Independent crop consultants specify inoculants as part of integrated forage management protocols for client farms.
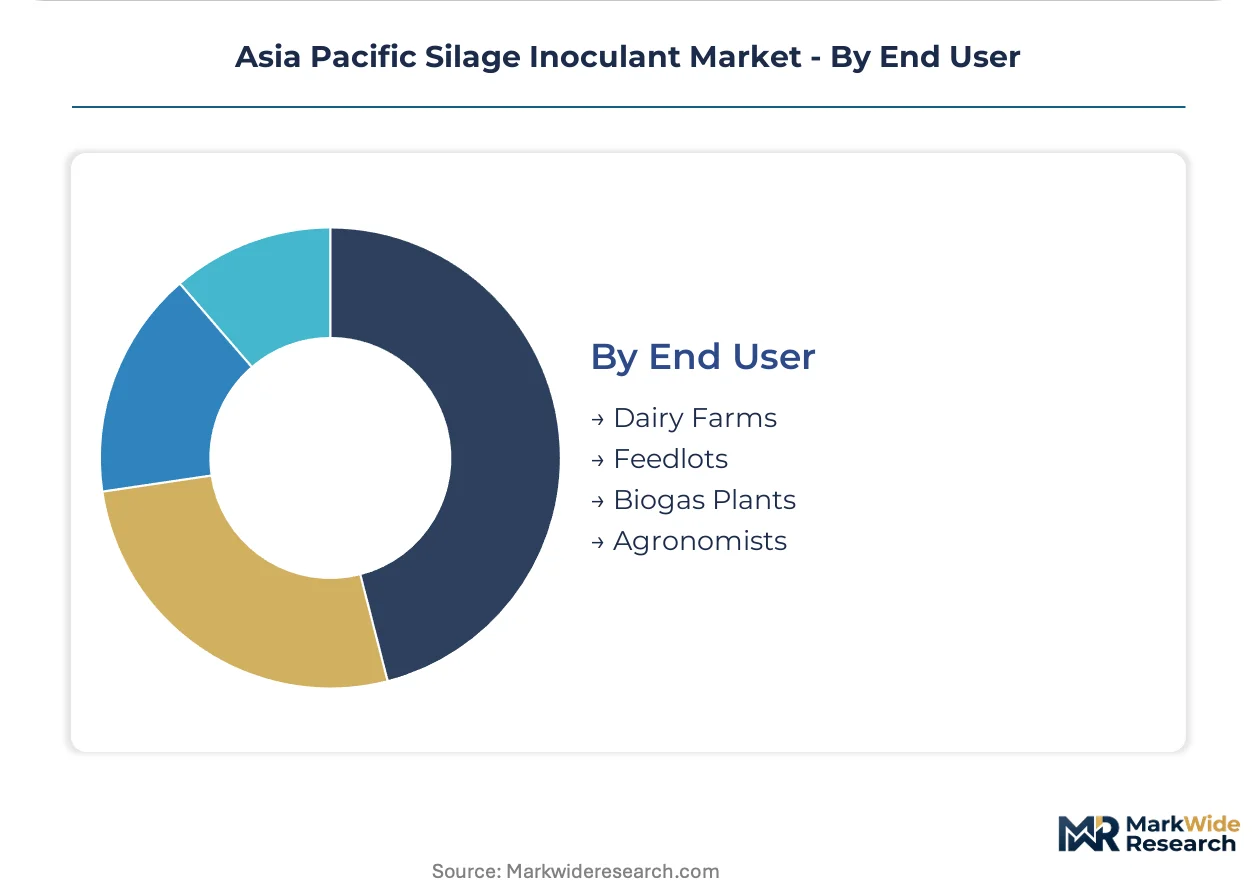
Dairy Farms represent the largest end-user segment, with Biogas Plants climbing the fastest as energy-transition policy accelerates digester construction across China and India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia Pacific silage inoculant market. Smallholder dairy cooperatives in Vietnam and Indonesia prioritize cost containment, while commercial operations in Australia and China's Hebei province absorb premiums for documented strain heritage and technical support bundling.
China
Commercial dairies in Hebei and Shandong provinces drive specification tightening for inoculant efficacy documentation. SAMR enforcement of GB standards on fermentation product labeling compels domestic manufacturers to submit certified homolactic strain documentation. Yangtze River Delta feed compounders are restructuring supply chains to maintain cross-border access into Southeast Asian markets.
India
Cooperative dairy networks in Gujarat and Maharashtra deploy combination inoculants to buffer monsoon-season forage variability. FSSAI and BIS jointly tightened microbial count specifications for imported formulations, filtering uncertified suppliers from approved vendor lists. Anand and Kolhapur districts specify technical support packages with documented colony-forming unit verification.
Indonesia
Dairy cooperatives across Java and Sumatra anchor demand for wet-climate fermentation protocols in high-humidity storage environments. Licensed distributor networks maintain supply security across archipelago logistics constraints. Surabaya and Medan procurement clusters increasingly expect on-farm application training as standard inclusions rather than premium service tiers.
Australia
Feedlot operations in Queensland and New South Wales concentrate demand for bulk homolactic formulations in backgrounding programs. TGA regulation of microbial feed additives under veterinary medicine frameworks requires strain-specific safety dossiers. MLA accreditation schemes increasingly reference inoculant application records in environmental compliance documentation.
Vietnam
Emerging dairy regions outside Ho Chi Minh City and Hanoi corridors represent underdeployed penetration for dual-phase fermentation control. Local cooperatives lack technical guidance on variable moisture protocol selection. Direct procurement relationships are displacing traditional distributor channels as manufacturers embed on-farm training into bulk sales contracts.
Asia Pacific Silage Inoculant Market Competitive Environment
Specialist microbial culture developers and diversified agricultural conglomerates split the Asia Pacific silage inoculant market. The competitive structure concentrates around three archetypes: tropical strain library specialists, in-house culture producers, and licensed distributor network operators. M&A activity targets regional fermentation technology assets, while capacity expansion focuses on tropical viability stabilization for wet-climate logistics corridors.
Among the specialist tier, Lallemand Inc. and Kemin Industries occupy positions defined by proprietary biological asset control. Lallemand leverages tropical strain libraries to anchor wet-climate fermentation protocol positioning. Kemin sustains competitive differentiation through captive supply of proprietary Pediococcus cultures. Cargill Inc. represents the diversified conglomerate archetype, with licensed distributor networks spanning Indonesian dairy cooperatives to secure regional supply security.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Kemin Industries |
| Cargill Inc. |
| ADM |
| Nutreco NV |
| ADDCON Group GmbH |
| BASF SE |
| Novozymes A/S |
| DSM N.V. |
| Others |
Value Chain & Pricing Dynamics
Freeze-dried culture production concentrates in France and the United States, anchoring margin pools at the formulation and technical service tiers rather than raw material supply. Downstream pricing power accrues to manufacturers with validated tropical strain libraries and direct-to-farm application bundling.
Pricing Analysis
Aftermarket technical support contracts historically drove lifetime value, though manufacturers now embed on-farm training into bulk direct sales to capture margin previously allocated to distributor staff. Three-tier pricing structure across premium, standard, and economy levels separates documented strain heritage with colony-forming unit verification from basic homolactic formulations. Pricing pressure stems from domestic manufacturers in China replicating certified protocols and compressing margins on commodity formulations. Smallholder cooperatives in Vietnam and Indonesia exhibit highest price sensitivity, while commercial dairies in Australia's Queensland absorb premiums for biosecurity-compliant documentation.
Supply Chain Analysis
Cold chain gaps between manufacturing hubs and end-use farms dominate supply chain risk for enzyme-based additives facing viability degradation in tropical logistics corridors. Raw material inputs draw from specialized fermentation substrate suppliers in China and India, alongside lyoprotectant chemical producers in Germany and Japan. Single-source vulnerability concentrates in tropical strain library access, where Lallemand's proprietary collections anchor wet-climate protocol differentiation. Distribution runs through licensed networks in Indonesia and direct procurement relationships in Vietnam, with authorized distributors gaining share as technical bundling standardizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory documentation cycles, with SAMR enforcement in China and FSSAI tightening in India creating compliance-driven replacement demand that lifts formulation premiums.
For Market Incumbents: Insulate proprietary strain assets through expanded tropical viability stabilization capacity in Southeast Asian logistics corridors. Invest in backward integration into captive Pediococcus culture production to defend against Kemin's in-house supply advantage. Deepen direct-to-farm technical embedding to preempt distributor disintermediation.
For New Entrants and Emerging Players: Pursue white-space penetration in Vietnam's emerging dairy regions outside Ho Chi Minh City and Hanoi corridors, where dual-phase fermentation control remains underdeployed. Target combination product positioning for monsoon-season forage variability in India's cooperative networks. Lead with mobile-integrated moisture monitoring bundles to differentiate from established technical service models.
For Investors and Strategic Acquirers: Capital is best deployed toward tropical strain library specialists with documented wet-climate fermentation protocols and existing SAMR or FSSAI registration dossiers. Long-term viability over a five-to-ten year window rests on regulatory compliance asset accumulation rather than volume scale alone. Monitor strain registration timeline synchronization across India, China, and Southeast Asia as the signal for supply interruption risk and pricing power inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Tropical Strain Library Expansion | Lallemand's wet-climate fermentation protocols anchor premium positioning across Indonesia and Vietnam. |
| Regulatory Dossier Harmonization | Early alignment with Australia's TGA and New Zealand's MPI creates preferred supplier status for cross-Tasman operations. |
| Direct-to-Farm Technical Embedding | Indonesian dairy cooperatives now expect on-farm training as standard inclusions rather than premium tiers. |
| Mobile-Integrated Moisture Monitoring | Maharashtra and Gujarat cooperatives deploy near-infrared spectroscopy to compress fermentation response times. |
| Captive Culture Production Investment | Kemin's proprietary Pediococcus supply sustains competitive differentiation against outsourced formulation competitors. |
Study Parameters
Initial hypotheses were tested against primary input from dairy cooperative procurement managers, feed compounder technical directors, regulatory affairs specialists at microbial culture manufacturers, and veterinary extension officers across Gujarat, Maharashtra, and Java. These perspectives were refined against secondary validation from SAMR GB standard filings, FSSAI notification records, Australian TGA veterinary medicine registers, customs trade data on fermentation product imports, and SEC disclosures from diversified agricultural conglomerates. Bottom-up strain registration timelines and top-down regional dairy production forecasts were triangulated to anchor volume projections.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeled by product type (homolactic, combination, heterolactic, enzyme-based), application intensity (dairy feed, beef feed, biogas production), distribution channel configuration, and end-user sophistication tier. CAGRs were derived from logistic curve fitting to documented adoption rates in cooperative networks, cross-referenced with regulatory enforcement timelines as demand accelerators. Industry-specific forecast inputs included monsoon seasonality patterns in India and cold chain infrastructure development indices in Southeast Asia.
Sensitivities concentrate around strain registration delays, tropical logistics disruption, and domestic manufacturer replication speed in China. Forecasts reflect documented adoption assumptions and regulatory enforcement intensity. Macroeconomic dairy commodity weakness, unanticipated biosecurity restrictions, or breakthroughs in synthetic fermentation alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
North America Agricultural Microbials Market