
 Amino Acid for Agriculture Market | 2026-2036
Amino Acid for Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Amino Acid for Agriculture Market Outlook
Biostimulant formulation revenue is reconfiguring margin pools away from commodity fertilizer blending toward value-added amino acid complexes. Ajinomoto Co., Inc. leverages its fermentation technology leadership to dominate L-glutamate and L-lysine precursors for agricultural derivatives. Haifa Group anchors premium positioning through precision-nutrition integration of amino acids with its specialty fertilizer portfolio. Futureco Bioscience SA differentiates via microbial-derived amino acid biostimulants tailored to Mediterranean and Latin American crop profiles.
Amino acid for agriculture encompasses biologically active nitrogenous compounds—typically L-α-amino acids produced via enzymatic hydrolysis, fermentation, or chemical synthesis at purities ranging from 40% to 80% active content—formulated to enhance nutrient uptake efficiency, abiotic stress tolerance, and root system development in crop and livestock systems. Liquid formulations capture the dominant share in foliar and fertigation applications due to rapid cuticular penetration and tank-mix compatibility with existing spray programs. Microbial source segments exhibit the fastest trajectory as fermentation-derived amino acids gain cost parity with plant hydrolysates while satisfying tightening sustainability criteria in European and North American procurement protocols.
The EU Fertilizing Products Regulation and REACH frameworks mandate full substance characterization and ecotoxicological profiling for amino acid biostimulants entering European markets, elevating compliance costs but creating barriers that favor established producers with dedicated regulatory affairs capabilities. India's FSSAI and BIS standards govern amino acid incorporation into animal feed matrices, with the PLI scheme indirectly supporting domestic fermentation capacity expansion for agricultural inputs. Stakeholders must monitor evolving divergence between EU and US EPA regulatory pathways for novel biostimulant claims, as asynchronous approval timelines will determine which formulation portfolios achieve first-mover advantage in high-value specialty crop territories.
Market Dynamics
Specialty crop producers in Brazil, India, and Spain are expanding amino acid fertilizer programs as micronutrient deficiency and abiotic stress tolerance become critical yield determinants. The EU Fertilizing Products Regulation is tightening purity standards for biostimulant inputs, forcing reformulation investments across the value chain.
Growth Catalysts
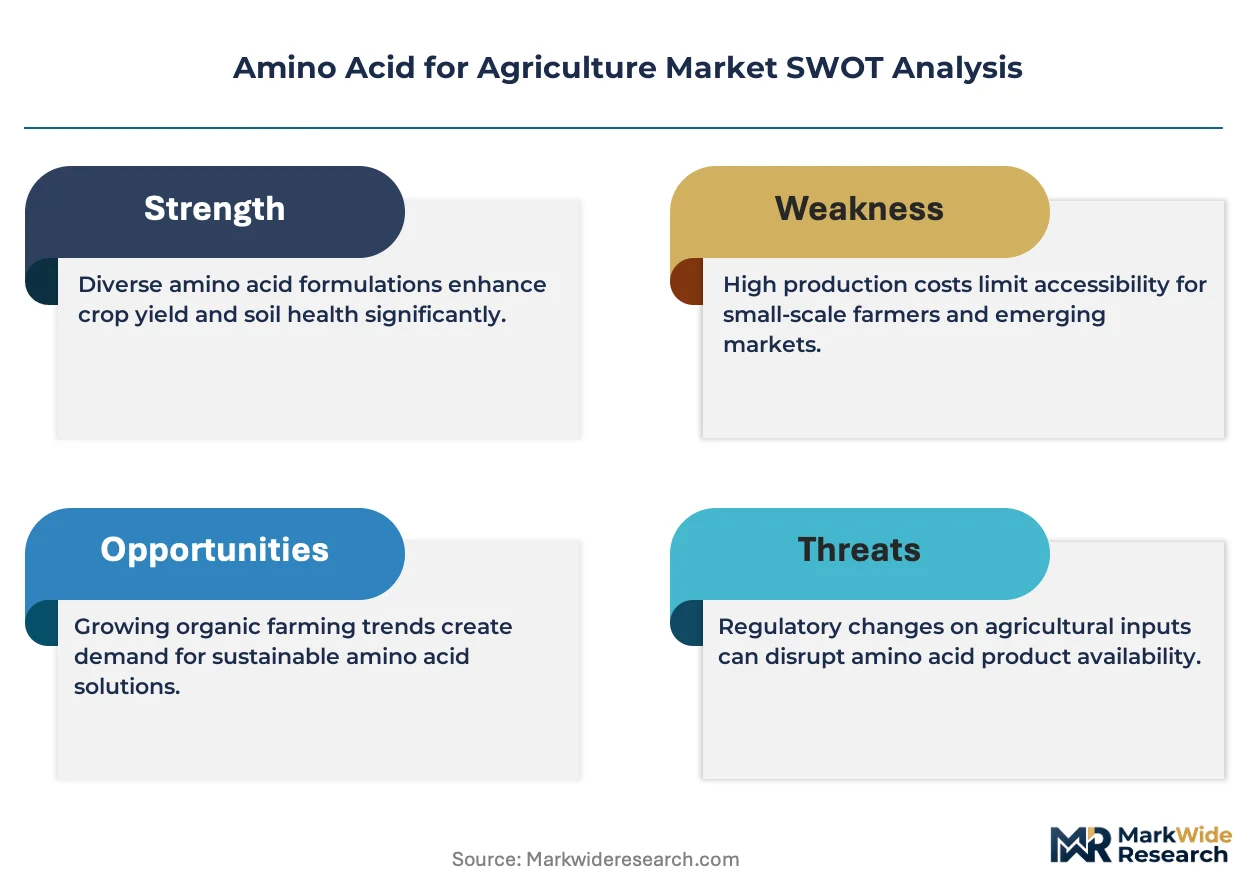
- REACH substance characterization mandates:European regulatory pressure for full ecotoxicological profiling creates compliance barriers that favor established producers with dedicated regulatory affairs capabilities, consolidating market share among fermentation technology leaders.
- India PLI scheme expansion:India's production-linked incentive scheme indirectly supports domestic fermentation capacity expansion for agricultural amino acid inputs, reducing import dependence in Punjab and Haryana states.
- Microbial-derived amino acids:Fermentation-derived amino acids achieve cost parity with plant hydrolysates while satisfying tightening sustainability criteria in European and North American procurement protocols, accelerating adoption in premium specialty crop segments.
Market Restraints
- Protein feedstock cost volatility:Soy and corn gluten meal prices fluctuate with commodity grain markets, compressing margins for enzymatic hydrolysis producers dependent on agricultural waste streams.
- East Asian fermentation supply concentration:L-glutamate and L-lysine precursor capacity clusters in China and Japan, creating geographic concentration risk for agricultural derivative formulators in Europe and Latin America.
- Substitution by seaweed extracts:Kelp-based biostimulants compete for shelf space in foliar application programs, particularly in Mediterranean markets where local extraction infrastructure exists.
Strategic Opportunities
- Underpenetrated Brazilian Cerrado:Large-scale soybean and corn operations in Brazil's interior lack amino acid soil amendment programs, presenting white space for precision-nutrition integration with existing fertigation infrastructure.
- CSRD sustainability disclosure requirements:Corporate Sustainability Reporting Directive mandates create procurement pull for microbial-derived amino acids with verified carbon footprints, opening premium pricing tiers.
- Drone-based foliar delivery convergence:Amino acid liquid formulations paired with unmanned aerial application systems enable variable-rate biostimulant deployment in orchards and vineyards, reducing labor costs.
Industry Challenges
- Fermentation process engineering talent scarcity:Industrial microbiology and downstream purification expertise concentrates in pharmaceutical and food-grade amino acid sectors, limiting agricultural-grade capacity expansion.
- EU Fertilizing Products Regulation certification timelines:Full substance characterization and ecotoxicological profiling requirements extend product registration cycles, delaying market entry for novel biostimulant formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amino Acid for Agriculture Market |
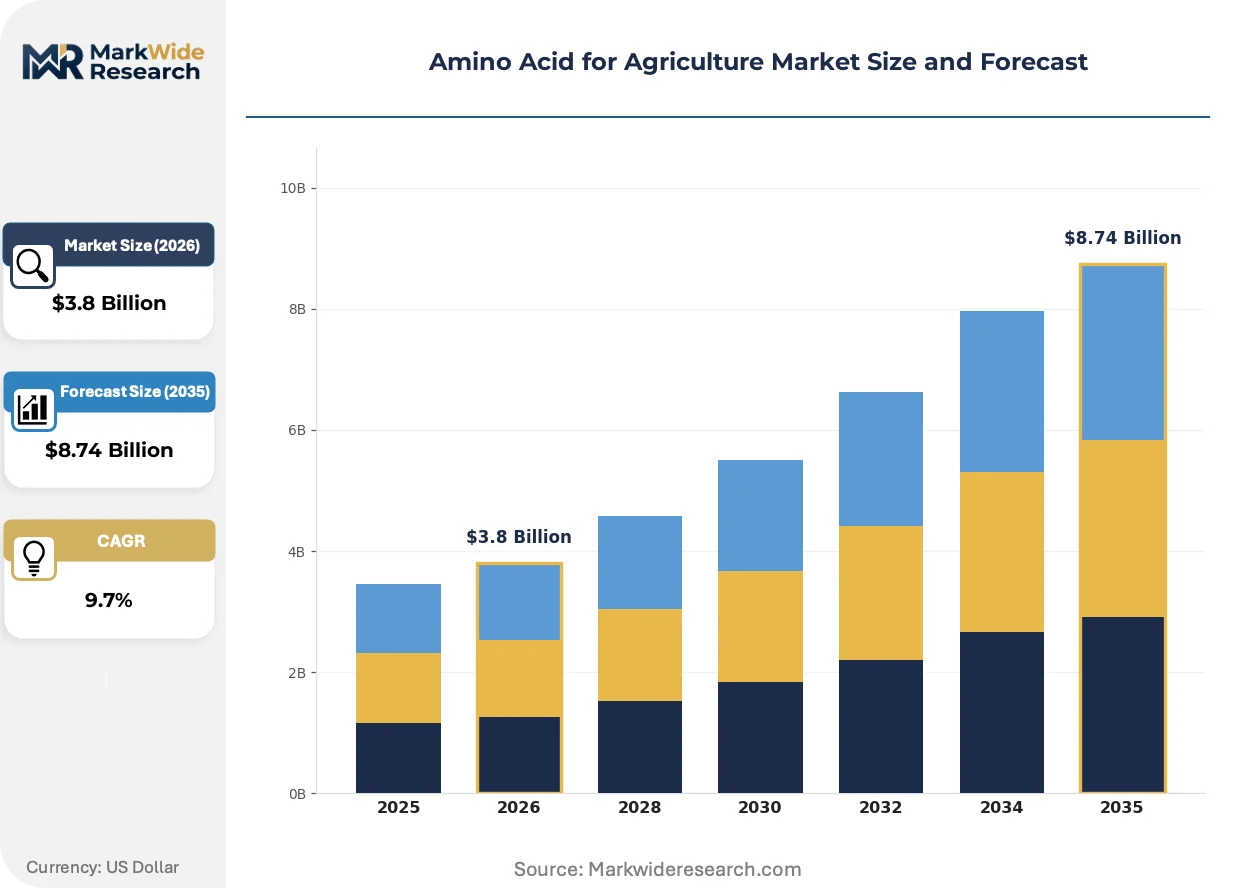
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fertilizer, Animal Feed, Crop Protection, Soil Amendment Formulation Type: Liquid, Powder, Granular, Tablet Source: Plant-Based, Animal-Based, Synthetic, Microbial Functionality: Growth Promoter, Stress Reducer, Nutrient Enhancer, Soil Conditioner |
| Companies Covered | Syngenta AG, Haifa Group, Futureco Bioscience SA, Gowan Co., Humintech GmbH, Isagro Spa, Ajinomoto Co., Inc., UPL Limited, SICIT Group S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amino Acid for Agriculture Market Strategic Shifts
Digital formulation platforms are compressing product development cycles for amino acid biostimulants, enabling rapid customization to regional crop profiles and soil conditions. Three interconnected developments are reconfiguring competitive positioning.
Enzymatic hydrolysis process control systems is virtualizing quality assurance for plant-derived amino acid production. Brazilian specialty crop cooperatives deploy real-time molecular weight distribution monitoring to standardize batch consistency. This technology is virtualizing the traditional reliance on fixed supplier relationships, enabling spot procurement of hydrolysate feedstocks based on instantaneous purity metrics.
REACH framework amendments for biostimulant substances are elevating documentation burdens for amino acid complex entrants. European formulators redirect R&D budgets toward full substance characterization and ecotoxicological profiling. Agricultural derivative producers with existing pharmaceutical-grade fermentation assets absorb compliance costs more readily than commodity blenders, widening capability gaps.
Certification-driven procurement preferences are fragmenting amino acid supplier bases across organic, regenerative, and conventional crop programs. German and Dutch distributors unbundle biostimulant portfolios by certification tier, requiring parallel inventory management. Spanish citrus and vegetable cooperatives demonstrate the most pronounced segmentation, mandating separate amino acid sourcing for export-bound versus domestic-market production.
Amino Acid for Agriculture Market Segmentation
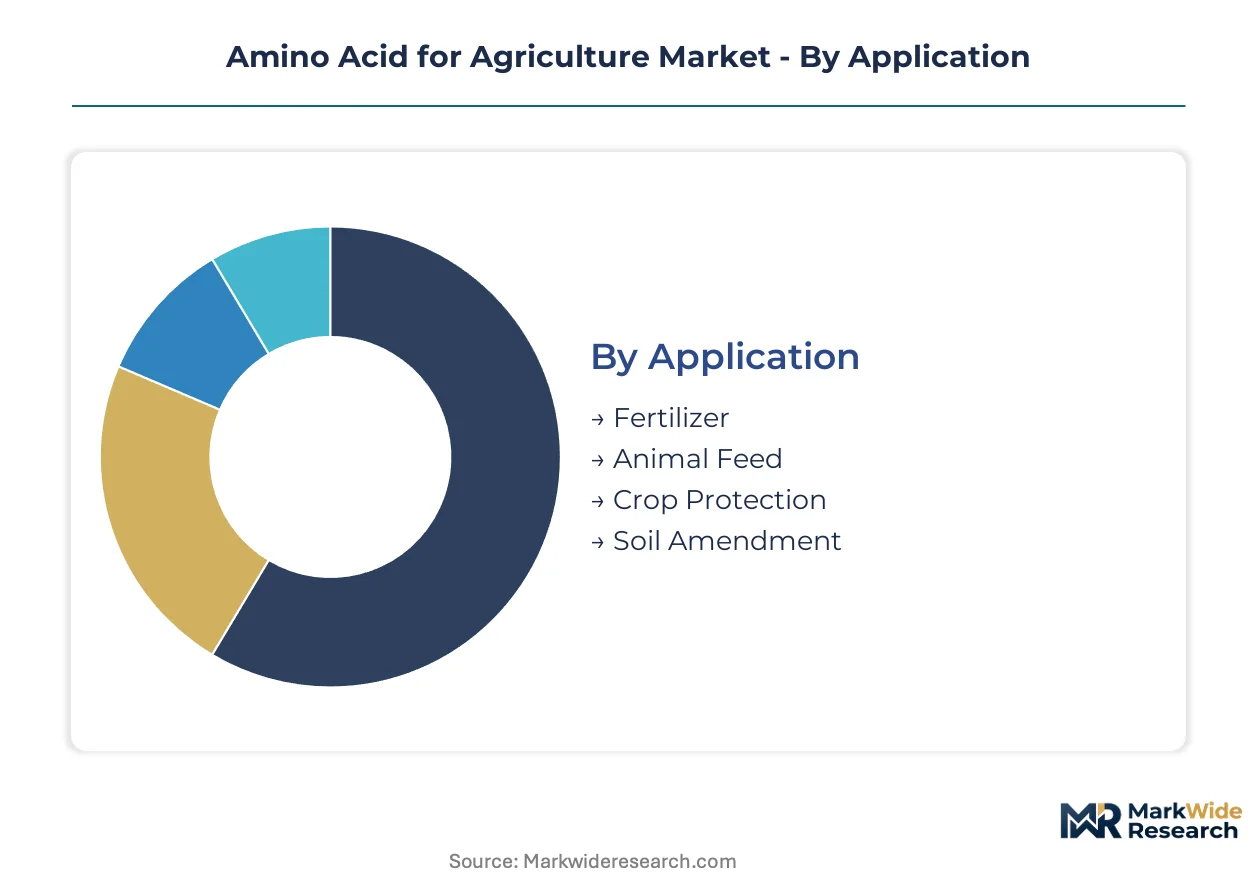
Amino acid agricultural inputs fragment across four functional dimensions that determine formulation chemistry, regulatory pathway, and procurement economics. Each segmentation axis carries distinct margin profiles and compliance burdens that reshape supplier competitive positioning.
Application:
Fertilizer programs dominate volume offtake, though animal feed and crop protection applications are expanding fastest as producers seek yield protection beyond baseline nutrition.
- Fertilizer:Formulations integrate with NPK blends or standalone fertigation systems to enhance nitrogen use efficiency and root system development. Demand concentrates in Brazil's Mato Grosso soybean belt and India's Punjab wheat districts, where micronutrient deficiency drives premium pricing for amino acid complexes.
- Animal Feed:Lysine, methionine, and threonine supplements optimize protein conversion ratios in poultry and swine operations. India's FSSAI and BIS standards govern incorporation rates, with the PLI scheme accelerating domestic fermentation capacity to reduce import dependence from East Asian suppliers.
- Crop Protection:Biostimulant formulations enhance abiotic stress tolerance during drought and heat events. Spanish citrus cooperatives and California almond growers represent concentrated adoption clusters.
- Soil Amendment:Long-term soil organic matter rebuilding programs utilize slower-release amino acid complexes. Mediterranean viticulture and Australian broadacre wheat operations demonstrate procurement pull.
The dominant share belongs to Fertilizer, while Animal Feed is closing the gap fastest as India's domestic capacity expansion reshapes regional supply economics.
Formulation Type:
Application method and equipment compatibility dictate formulation selection, with liquid formats commanding premium positioning in precision agriculture systems.
- Liquid:Rapid cuticular penetration and tank-mix compatibility with existing spray programs drive foliar and fertigation dominance. Drone-based variable-rate deployment in Brazilian Cerrado orchards and Spanish vineyards accelerates technology convergence.
- Powder:Dry blending compatibility with bulk fertilizer operations and extended shelf stability support commodity-scale adoption. Chinese and Indian compound fertilizer manufacturers represent primary demand nodes.
- Granular:Controlled-release characteristics suit soil amendment programs requiring extended nutrient availability. Australian broadacre and Argentine soybean operations demonstrate procurement concentration.
- Tablet:Precision dosing for greenhouse and hydroponic systems eliminates measurement variability. Dutch and Israeli protected agriculture facilities anchor niche demand.
Liquid formulations capture the dominant revenue position, though Powder formats retain volume leadership in emerging market bulk blending operations.
Source:
Feedstock origin determines sustainability credentials, regulatory classification, and margin structure across procurement tiers.
- Plant-Based:Enzymatic hydrolysis of soy, corn gluten, and legume meals yields complex amino acid profiles with organic certification eligibility. Brazilian cooperatives deploy real-time molecular weight monitoring to standardize batch consistency and enable spot procurement.
- Microbial:Fermentation-derived amino acids achieve cost parity with plant hydrolysates while satisfying EU CSRD sustainability disclosure requirements and North American procurement protocols. Steepest expansion trajectory as pharmaceutical-grade fermentation assets pivot to agricultural derivatives.
- Animal-Based:Collagen and keratin hydrolysates from slaughterhouse waste streams face tightening EU Fertilizing Products Regulation purity constraints. Mediterranean markets with local extraction infrastructure retain niche positioning.
- Synthetic:Chemical synthesis delivers single-amino-acid purity for specialized research and high-value crop applications. Limited agricultural penetration due to cost disadvantage versus biological production routes.
Plant-Based sources retain volume leadership, though Microbial production is expanding most quickly as fermentation technology achieves cost parity with hydrolysis methods.
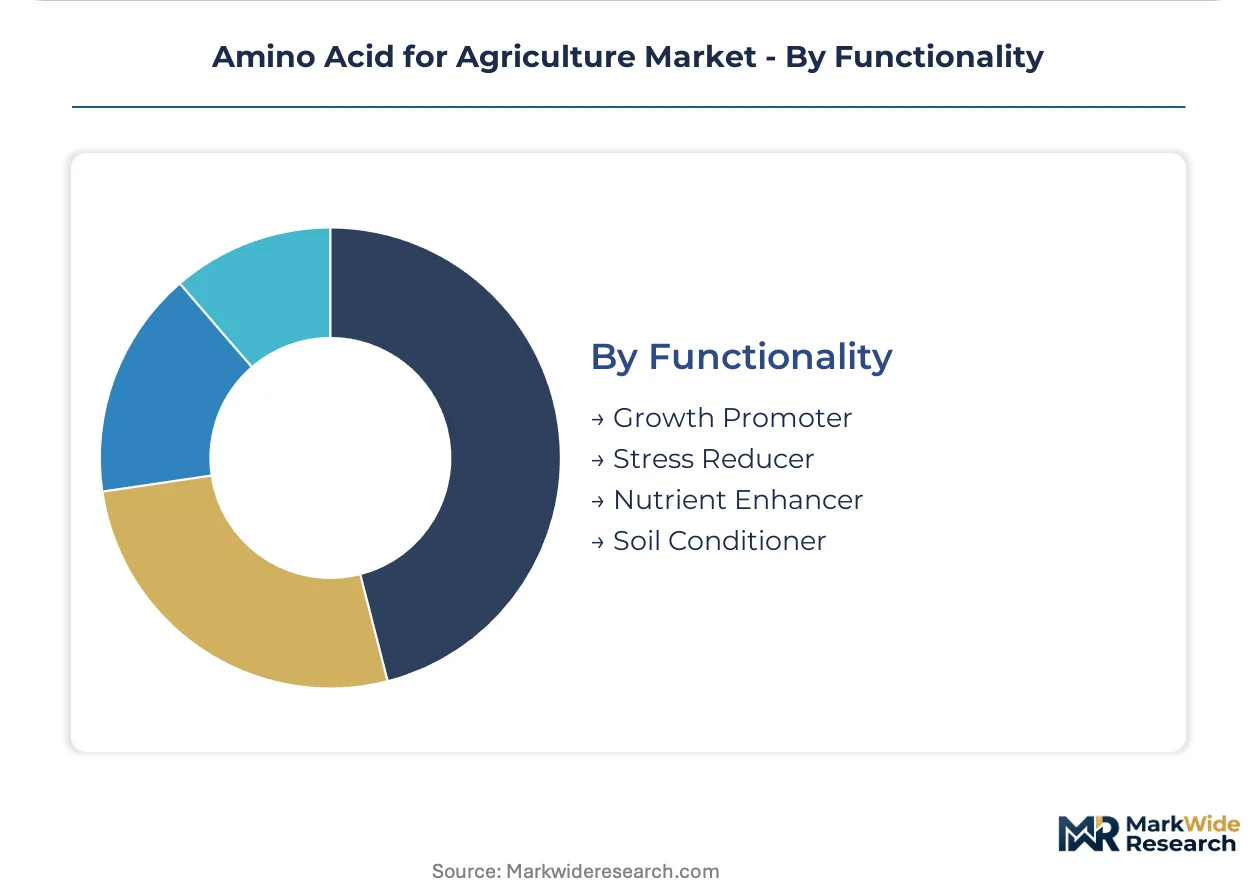
Functionality:
Claim substantiation requirements under REACH and national biostimulant regulations are forcing reformulation investments toward demonstrable physiological effects.
- Growth Promoter:Auxin and cytokinin pathway modulation accelerates vegetative development and fruit set. Greenhouse tomato and pepper operations in Spain and Mexico demonstrate concentrated adoption.
- Stress Reducer:Osmoprotectant and antioxidant mechanisms mitigate drought, salinity, and temperature extremes. Australian wheat belt and California Central Valley operations facing climate volatility drive procurement.
- Nutrient Enhancer:Chelation and translocation improvements boost micronutrient uptake efficiency. Indian Punjab and Haryana states with documented zinc and iron deficiency represent priority markets.
- Soil Conditioner:Microbial food source properties stimulate rhizosphere biology and aggregate stability. Regenerative agriculture programs in France and Germany mandate separate sourcing tiers.
Nutrient Enhancer claims dominate current formulation portfolios, while Stress Reducer functionality is gaining share fastest as climate adaptation becomes critical to yield stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers exhibit the highest price elasticity for amino acid fertilizers, while Brazilian specialty crop producers absorb premium formulations with minimal volume sensitivity. European procurement patterns split between cost-conscious bulk blenders and sustainability-certified premium tier buyers. Chinese fermentation capacity anchors global precursor supply, creating geographic concentration that amplifies regional price volatility.
Brazil
Mato Grosso soybean operators and São Paulo citrus cooperatives drive demand for foliar amino acid programs targeting micronutrient deficiency. ANVISA biostimulant registration pathways remain less burdensome than REACH equivalents, accelerating product launch timelines. The Cerrado interior presents white space for precision-nutrition integration with existing fertigation infrastructure.
India
Punjab and Haryana wheat districts concentrate demand for zinc-chelating amino acid complexes addressing documented soil deficiencies. The PLI scheme accelerates domestic fermentation capacity expansion, reducing import dependence from East Asian suppliers. FSSAI and BIS standards govern animal feed incorporation rates, tightening quality enforcement in Gujarat and Maharashtra processing clusters.
Spain
Valencia citrus cooperatives and Catalonia vegetable producers mandate separate amino acid sourcing tiers for export-bound versus domestic-market production. EU Fertilizing Products Regulation certification timelines extend product registration cycles, delaying novel formulation entry. Andalusian olive and vineyard operations demonstrate the most pronounced procurement segmentation by organic certification status.
United States
California Central Valley almond growers and Florida citrus operations drive adoption of stress-reducer biostimulant formulations amid climate volatility. EPA regulatory pathways for novel biostimulant claims diverge from EU REACH frameworks, creating asynchronous approval timelines. The Pacific Northwest specialty seed sector exhibits concentrated demand for microbial-derived amino acids with verified carbon footprints.
China
Shandong and Jiangsu provinces host fermentation capacity clusters supplying L-glutamate and L-lysine precursors for agricultural derivative formulators. GB standards and dual carbon goals tighten sustainability criteria for domestic biostimulant procurement. Yangtze River Delta compound fertilizer manufacturers represent primary demand nodes for powder-format amino acid integration.
Amino Acid for Agriculture Market Competitive Environment
Capability concentration sits with fermentation technology specialists possessing pharmaceutical-grade asset bases; scale advantage sits with diversified agrochemical conglomerates with existing distribution infrastructure. The market structures around three archetypes: Japanese and Chinese fermentation leaders with precursor dominance, Israeli and Spanish precision-nutrition integrators, and Indian and Brazilian regional formulators with local regulatory fluency. Dominant competitive moves include backward integration into fermentation capacity and technology licensing partnerships spanning multiple geographies.
Within the fermentation-leader archetype, Ajinomoto Co., Inc. and SICIT Group S.p.A. occupy positions defined by precursor supply control and downstream formulation reach. Among precision-nutrition integrators, Haifa Group anchors premium positioning through specialty fertilizer portfolio alignment. Regional formulators exemplified by UPL Limited sit within emerging market access tiers, leveraging local regulatory relationships and distribution density. These three patterns—precursor dominance, premium integration, and regional access—collectively determine competitive mobility across procurement segments.
| Leading Market Players |
|---|
| Syngenta AG |
| Haifa Group |
| Futureco Bioscience SA |
| Gowan Co. |
| Humintech GmbH |
| Isagro Spa |
| Ajinomoto Co., Inc. |
| UPL Limited |
| SICIT Group S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu fermentation clusters anchor global L-glutamate and L-lysine precursor capacity, translating geographic supply concentration into asymmetric pricing power for downstream agricultural derivative formulators. Cost compression in plant-based hydrolysate tiers intensifies as Brazilian cooperatives deploy real-time molecular weight monitoring to enable spot procurement, eroding fixed-contract premiums.
Pricing Analysis
Long-term offtake agreements dominate amino acid procurement for large-scale compound fertilizer manufacturers, while spot markets serve specialty crop cooperatives with fluctuating formulation needs. Three-tier pricing structure across fermentation-derived premium, plant-hydrolysate standard, and animal-based economy levels reflects certification grade and carbon footprint verification under EU CSRD mandates. Price differentiation hinges on REACH compliance documentation depth and sustainability credentialing, with Indian Punjab buyers exhibiting highest elasticity and Brazilian citrus producers absorbing premium microbial-derived formulations with minimal volume sensitivity. Margins are tightening in enzymatic hydrolysis tiers due to soy and corn gluten meal feedstock volatility.
Supply Chain Analysis
Export-control restrictions on pharmaceutical-grade fermentation technology limit capacity transfer to agricultural derivative producers outside East Asia, reinforcing supply concentration. L-glutamate and L-lysine precursor production draws from Shandong and Jiangsu provinces in China, with secondary fermentation hubs in Japan, creating single-source vulnerability for European and Latin American formulators. Raw material dependencies rest on soy meal, corn gluten, and sugar-based fermentation feedstocks. Distribution runs through regional agrochemical distributors with formulation blending capabilities, though direct procurement by Brazilian cooperatives and Indian state agricultural departments is fragmenting traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amino acid biostimulants represent a high-growth disruption as EU Fertilizing Products Regulation certification timelines and CSRD sustainability disclosure requirements simultaneously elevate compliance barriers and premium pricing tiers for verified microbial-derived inputs.
For Market Incumbents: Insulate formulation portfolios from plant-hydrolysate margin compression by securing captive fermentation capacity through backward integration into pharmaceutical-grade asset bases in East Asia. Prioritize REACH substance characterization investments to extend certification lead times that block emerging entrants, while redirecting R&D toward drone-compatible liquid formulations for Brazilian Cerrado and Spanish vineyard precision deployment.
For New Entrants and Emerging Players: Build out microbial-derived amino acid production targeting underpenetrated Brazilian Cerrado soybean operations lacking existing soil amendment programs. Target Indian Punjab and Haryana state agricultural departments with zinc-chelating complexes addressing documented micronutrient deficiency, leveraging PLI scheme capacity expansion to displace East Asian import dependence. Deploy digital formulation platforms enabling rapid regional customization as primary go-to-market differentiation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agrochemical conglomerates with stranded fermentation assets underutilized for agricultural derivatives. Five-to-ten year viability centers on pharmaceutical-grade capacity pivots with existing regulatory affairs infrastructure capable of absorbing EU ecotoxicological profiling burdens. Monitor divergence between EPA and REACH biostimulant approval timelines as inflection indicator for first-mover advantage in California almond and Florida citrus premium segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive L-glutamate supply secures margin control against East Asian precursor volatility. |
| REACH Substance Characterization Investment | Full ecotoxicological profiling creates compliance moats favoring established producers. |
| Drone-Compatible Liquid Formulation Development | Tank-mix compatibility with unmanned aerial systems unlocks Brazilian orchard variable-rate deployment. |
| CSRD Carbon Footprint Verification | Sustainability credentialing opens premium procurement tiers in German and Dutch distributor networks. |
| Regional Formulation Platform Licensing | Technology partnerships spanning Mediterranean and Latin American crop profiles accelerate geographic penetration. |
Study Parameters
Cross-validation between primary interviews with fermentation technology directors, regulatory affairs leads at biostimulant formulators, procurement managers at Brazilian agricultural cooperatives, and Indian state agricultural department officials anchors the qualitative findings. Secondary validation draws from EU Fertilizing Products Regulation certification databases, ANVISA registration filings, India PLI scheme capacity announcements, and SEC disclosures from listed agrochemical conglomerates. Bottom-up amino acid consumption estimates triangulate against top-down specialty fertilizer market sizing across the analysis window.
Calibration against historical capacity utilization rates and procurement contract structures informs the projection framework. Segmentation dimensions modeled include application type, formulation chemistry, source origin, and functionality claim across regional regulatory clusters. CAGRs derive from elasticity-adjusted adoption curves incorporating REACH compliance cost absorption and CSRD procurement preference shifts. Industry-specific inputs encompass fermentation yield improvements and enzymatic hydrolysis process control diffusion rates.
Stress conditions across feedstock price volatility bands, regulatory timeline extensions, and substitution elasticity by seaweed extract competitors were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme execution and EU biostimulant framework stability. Material shifts in East Asian fermentation capacity expansion trajectories or asynchronous EPA-REACH approval convergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
South America Feed Acidifiers Market