
 Neonicotinoid Insecticides Market | 2026-2036
Neonicotinoid Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Neonicotinoid Insecticides Market Outlook
Specialty vegetable producers is redrawing procurement patterns for neonicotinoid insecticides as broad-acre grain growers face pollinator-risk restrictions. Bayer AG leverages its seed-treatment integration to sustain channel control across major cotton and soybean markets. Syngenta AG anchors its position through R&D intensity in next-generation thiamethoxam formulations. BASF SE differentiates via geographic dominance in European greenhouse applications where residual use permits persist.
Neonicotinoid insecticides constitute a class of systemic neuro-active chemistries structurally derived from nicotine, engineered to bind selectively to insect nicotinic acetylcholine receptors with water-soluble profiles enabling root uptake and translocation through xylem tissues. Their primary commercial purpose centers on crop protection against sucking pests and soil-dwelling insect larvae across intensive agricultural systems. Imidacloprid retains the largest volume footprint among product types though regulatory pressure in multiple jurisdictions accelerates grower transitions toward acetamiprid for certain foliar applications. The agricultural application segment commands the dominant value share while residential channels face structural contraction from municipal pollinator-protection ordinances. Liquid formulations lead in revenue contribution due to compatibility with precision application equipment, though granule demand persists in row-crop seed treatment protocols.
The EPA's pollinator risk assessments and conditional registration reviews shape product availability timelines and label restrictions across the United States, while EFSA's ongoing neonicotinoid re-evaluations under EU regulation 1107/2009 determine market access parameters for European growers. India's Central Insecticides Board registration requirements and state-level resistance-management protocols govern product introduction and rotation mandates in that market. Stakeholders must monitor evolving residue tolerance harmonization between Codex Alimentarius standards and national food-safety authorities to anticipate trade-barrier implications for treated-commodity exports.
Market Dynamics
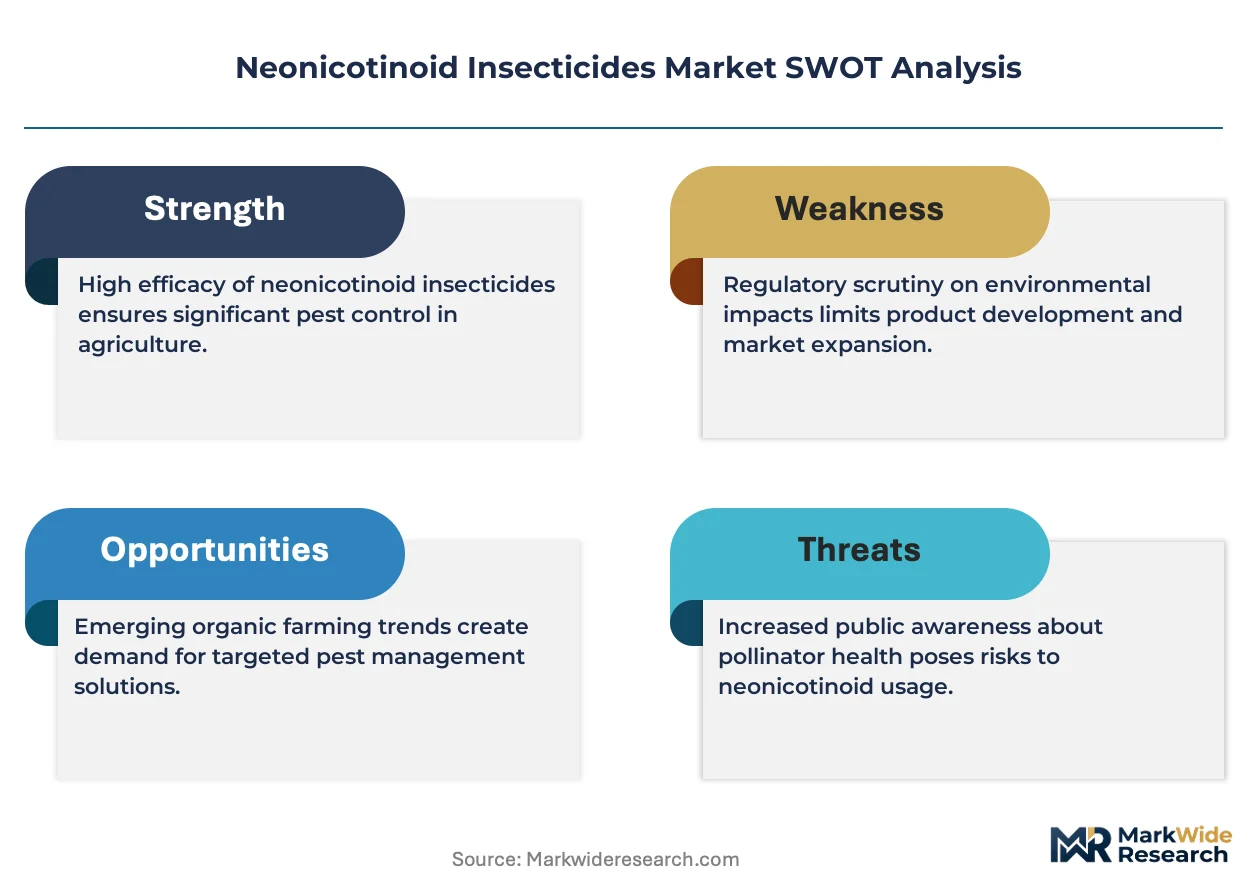
Regulatory fragmentation between pollinator-risk jurisdictions and residue-tolerant markets is forcing manufacturers to maintain parallel formulation portfolios while specialty crop growers absorb premium pricing for compliant chemistries.
Growth Catalysts
- Seed-treatment integration:Systemic uptake via coated seeds reduces foliar spray volumes and aligns with integrated pest management protocols in Brazilian soybean operations.
- EFSA outdoor-use restrictions:The partial ban redirected product inventories toward Asian agricultural markets where registration pathways remain navigable.
- Pink bollworm pressure:Sustained infestation intensity across India's cotton-belt states preserves grower reliance on neonicotinoid chemistries despite resistance-management mandates.
Market Restraints
- Active ingredient concentration:Three manufacturers control the majority of technical-grade thiamethoxam and imidacloprid supply, creating input cost volatility for downstream formulators.
- Biological substitute maturation:Bacillus thuringiensis and entomopathogenic nematode products are displacing soil-applied neonicotinoids in greenhouse vegetable systems.
- Residue tolerance divergence:Misalignment between Codex Alimentarius standards and national food-safety authorities generates trade-barrier risk for treated-commodity exporters.
Strategic Opportunities
- Greenhouse residual permits:EFSA guidelines preserve neonicotinoid access for protected-crop applications, creating a defendable European stronghold amid broader outdoor restrictions.
- Precision application convergence:Integration with variable-rate equipment and drone-based delivery systems enables dose optimization that satisfies resistance-management protocols.
- Indonesian horticulture expansion:Rising protected-crop acreage in West Java and North Sumatra offers underpenetrated demand for systemic chemistries compliant with local residue limits.
Industry Challenges
- Resistance-monitoring infrastructure:State-level mandates in India and Brazil require sustained investment in susceptibility baseline establishment and annual surveillance reporting.
- Label restriction compliance:Conditional EPA registrations impose application timing windows and buffer-zone requirements that complicate operational logistics for aerial applicators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonicotinoid Insecticides Market |
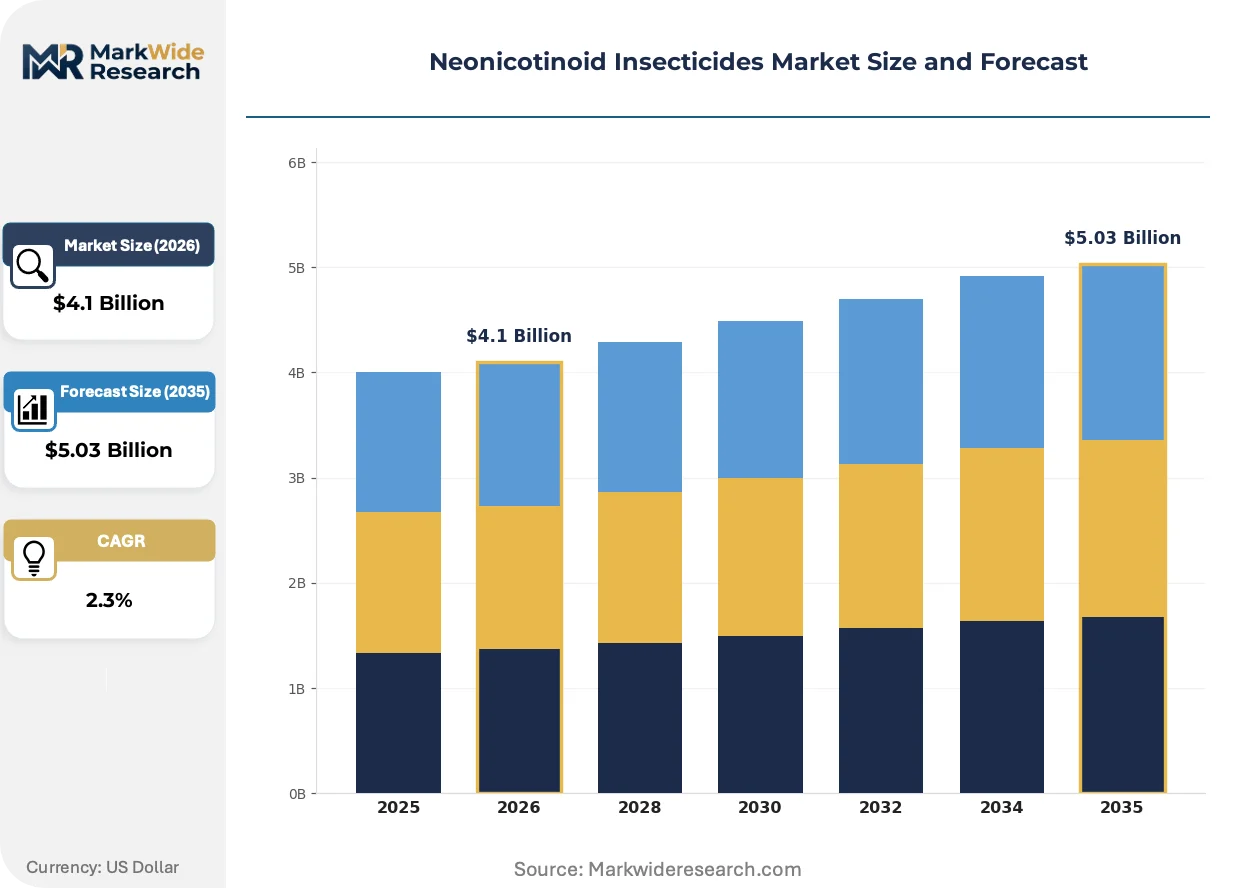
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.03 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imidacloprid, Thiamethoxam, Acetamiprid, Clothianidin Application: Agricultural, Residential, Commercial, Turf Formulation: Granules, Liquids, Sprays, Tablets Distribution Channel: Online, Retail, Agricultural Cooperatives, Distributors |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, FMC Corporation, Sumitomo Chemical Co., Ltd., UPL Limited, Adama Agricultural Solutions Ltd., Nufarm Limited, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonicotinoid Insecticides Market Strategic Shifts
Formulation chemistry is diverging between high-load concentrates for industrial-scale seed treatment and precision-delivery microencapsulates for specialty crop systems.
Microencapsulation technology is bifurcating the foliar application segment. These formulations extend residual activity through controlled release mechanisms. Vegetable producers in Spain and Italy are adopting them at accelerated rates to satisfy supermarket chain residue specifications. The technology is bifurcating competitive positioning between premium encapsulate suppliers and commodity emulsifiable concentrate manufacturers.
EPA's pollinator risk assessments are compressing product availability timelines across the United States. Conditional registration reviews impose interim use restrictions pending additional field-study submissions. Row-crop applicators in the Corn Belt are responding by accelerating transitions to acetamiprid for certain foliar programs.
Buyer concentration among specialty crop cooperatives is consolidating procurement leverage. Large vegetable marketing organizations in California's Central Valley are negotiating direct supply agreements that displace traditional distributor relationships. This pattern is most visible in strawberry and leafy green operations where residue compliance documentation requirements favor integrated supplier partnerships.
Neonicotinoid Insecticides Market Segmentation
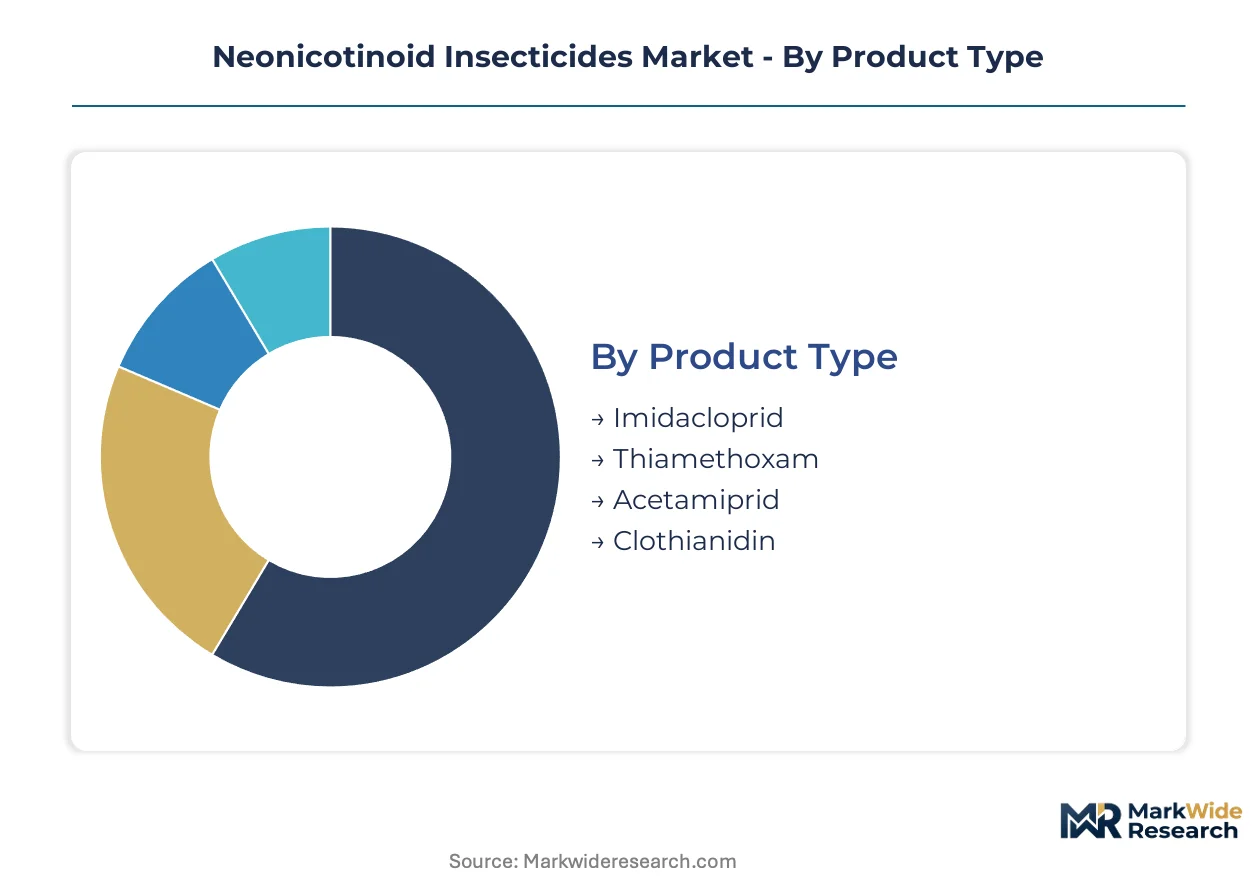
Neonicotinoid manufacturers configure product portfolios around regulatory tolerance gradients and application-specific residue thresholds. Segment boundaries shift as seed-treatment integration concentrates volume in agricultural channels while municipal ordinances compress residential access.
Product Type:
Margin pools concentrate in technical-grade active ingredient supply where three manufacturers control thiamethoxam and imidacloprid production.
- Imidacloprid:The first commercialized neonicotinoid retains the largest volume footprint across cotton and soybean seed-treatment protocols. India's cotton-belt states sustain demand despite EFSA's pollinator-risk restrictions in European markets.
- Thiamethoxam:Syngenta AG anchors R&D intensity in next-generation formulations with enhanced xylem translocation efficiency. Brazilian soybean operations drive uptake via coated-seed integration that reduces foliar spray volumes.
- Acetamiprid:Row-crop applicators in the US Corn Belt are accelerating transitions to this chemistry for certain foliar programs amid EPA conditional registration timelines.
- Clothianidin:Primarily deployed in soil-applied and seed-treatment matrices for root-feeding pest control in maize and canola systems.
Imidacloprid holds installed capacity. Acetamiprid is rotating up the share rankings.
Application:
Volume concentrates in agricultural channels where precision pest management justifies systemic chemistry investment.
- Agricultural:Specialty crop growers in California's Central Valley and India's cotton-belt states absorb premium pricing for compliant chemistries. Bayer AG leverages seed-treatment integration to sustain channel control across major cotton and soybean markets.
- Residential:Municipal pollinator-protection ordinances are compressing structural access in North American and European urban markets.
- Commercial:Greenhouse operators in Spain and Italy adopt microencapsulated formulations to satisfy supermarket chain residue specifications.
- Turf:Golf course and sports field maintenance faces tightening neonicotinoid prohibitions under state-level environmental regulations.
Agricultural commands value share. Commercial is climbing the fastest as protected-crop permits persist.
Formulation:
Technology investment bifurcates between industrial-scale seed-treatment concentrates and precision-delivery microencapsulates.
- Liquids:Compatibility with precision application equipment drives revenue contribution across broad-acre grain operations. Emulsifiable concentrates dominate commodity procurement while microencapsulates capture premium positioning.
- Granules:Row-crop seed treatment protocols in Brazil and the US Midwest sustain demand for soil-incorporated delivery systems.
- Sprays:Foliar application in specialty vegetables requires buffer-zone compliance under EPA conditional registrations.
- Tablets:Limited deployment in greenhouse and nursery systems where controlled-release matrices align with protected-crop residue limits.
Liquids hold formulation leadership. Microencapsulate variants are gaining share fastest in European horticulture.
Distribution Channel:
Procurement leverage is consolidating around large vegetable marketing organizations negotiating direct supply agreements.
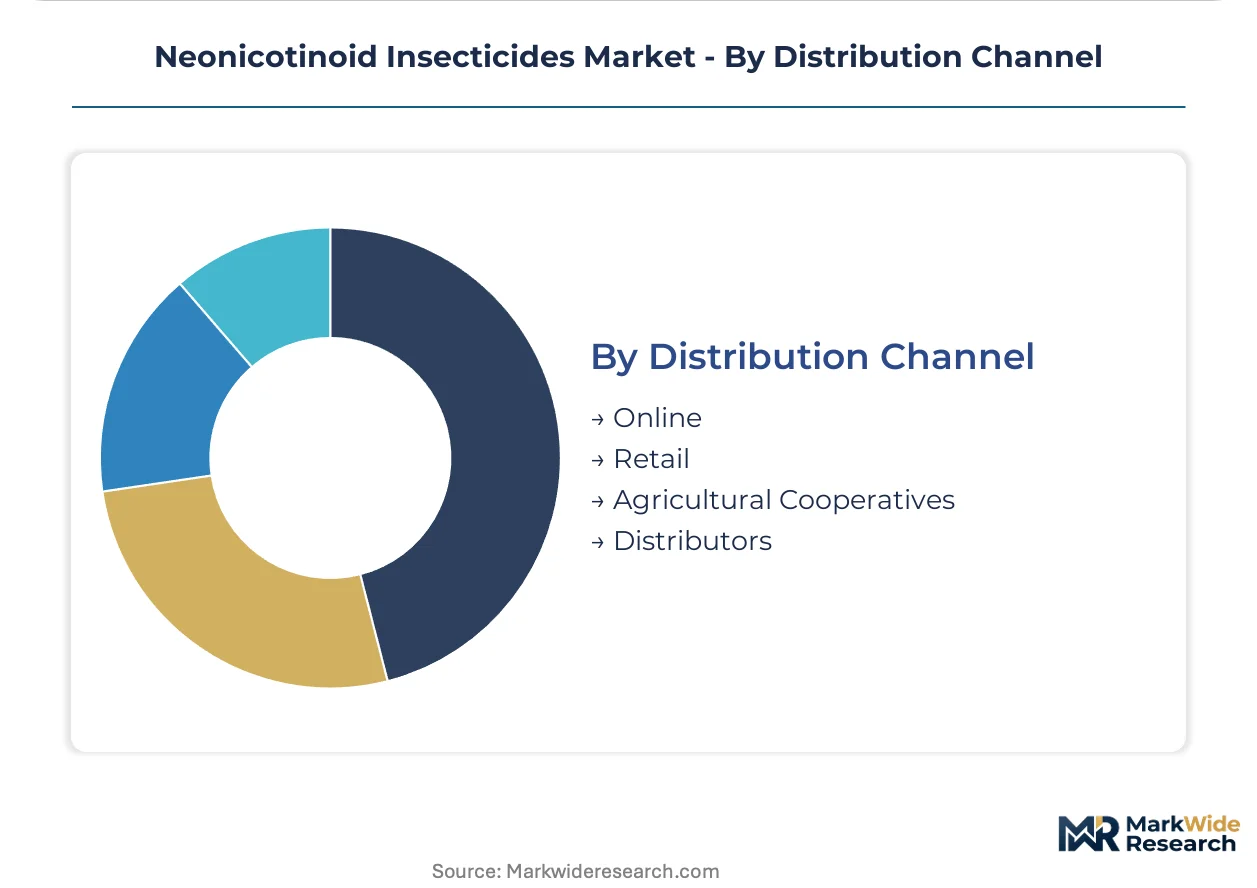
- Distributors:Traditional channel control persists in Brazilian and Indian markets where regulatory navigation requires localized expertise.
- Agricultural Cooperatives:Buyer concentration among California Central Valley cooperatives is displacing traditional distributor relationships in strawberry and leafy green operations.
- Retail:Farm supply stores face margin compression as cooperative procurement scales.
- Online:Digital platforms capture share in smaller-scale horticulture and residential segments where regulatory documentation requirements are less stringent.
Distributors retain infrastructure density. Agricultural cooperatives are rotating up the share rankings through consolidated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Product flows from European manufacturers have redirected toward Asian agricultural markets following EFSA's outdoor-use restrictions, with Indian cotton-belt states and Brazilian soybean regions absorbing redirected inventories.
United States
Corn Belt row-crop applicators drive acetamiprid uptake for foliar programs amid EPA conditional registration timelines. The agency's pollinator risk assessments impose buffer-zone requirements that complicate aerial application logistics. Illinois and Iowa field operations concentrate demand for liquid formulations compatible with precision equipment.
India
Pink bollworm pressure across Maharashtra and Gujarat sustains grower reliance on systemic chemistries despite Central Insecticides Board rotation mandates. State-level resistance-management protocols require annual susceptibility surveillance reporting. Cotton-belt procurement concentrates through agricultural cooperatives in Telangana and Andhra Pradesh.
Brazil
Soybean seed-treatment integration reduces foliar spray volumes across Mato Grosso and Paraná operations. ANVISA registration pathways govern product introduction timelines for soil-applied matrices. The Cerrado expansion corridor anchors coated-seed demand for root-feeding pest control.
Germany
BASF SE leverages geographic proximity to sustain greenhouse residual permit access under EFSA guidelines. Protected-crop applications in Lower Saxony and Bavaria preserve neonicotinoid channels amid broader outdoor prohibitions. The Rhine-Ruhr industrial cluster concentrates formulation chemistry R&D investment.
Indonesia
West Java and North Sumatra horticulture expansion generates underpenetrated demand for systemic chemistries compliant with local residue limits. Protected-crop acreage growth outpaces regulatory infrastructure development. Jakarta-based distributors navigate import licensing for technical-grade active ingredients.
Neonicotinoid Insecticides Market Competitive Environment
Player mix skews toward integrated agrochemical conglomerates with captive technical-grade manufacturing. Three manufacturers control the majority of thiamethoxam and imidacloprid supply, creating tiered competitive positioning around active ingredient access. Strategic archetypes include seed-treatment integrators, formulation specialists, and geographic stronghold operators. Dominant competitive moves center on backward integration into technical-grade production and direct supply agreements with large agricultural cooperatives.
Within the integrated conglomerate tier, Bayer AG, Syngenta AG, and BASF SE exemplify divergent geographic anchoring strategies. Bayer AG occupies a position emphasizing seed-treatment channel control across major cotton and soybean markets. Syngenta AG sits within the R&D-intensive archetype, with its corporate structure supporting next-generation formulation development. BASF SE represents the geographic stronghold model, leveraging European greenhouse permit persistence to defend regional positioning amid broader regulatory contraction.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| UPL Limited |
| Adama Agricultural Solutions Ltd. |
| Nufarm Limited |
| Corteva Agriscience |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day technical-grade inventory cycles concentrate pricing power among the three manufacturers controlling thiamethoxam and imidacloprid supply, forcing downstream formulators into long-term offtake commitments that lock in cost structures across regional markets.
Pricing Analysis
Next-generation microencapsulate formulations command 40-60% premiums over commodity emulsifiable concentrates, with price differentiation resting on residue-compliance documentation and precision-application compatibility. Three-tier pricing structure across premium encapsulates, standard liquids, and economy granules reflects certification grade and volume scale. Cost compression in the standard liquid tier is intensifying because Brazilian and Indian cooperatives are consolidating procurement leverage. Agricultural cooperatives in California's Central Valley exhibit the sharpest price sensitivity, while greenhouse operators in Spain and Italy absorb premiums for residue-compliant microencapsulates.
Supply Chain Analysis
Strategic stockpiling of technical-grade actives prevails over just-in-time approaches as manufacturers buffer against EFSA-driven supply redirections and Indian Central Insecticides Board registration delays. China, India, and Germany anchor technical-grade production, with formulation chemistry concentrated in the Rhine-Ruhr cluster and São Paulo state. Supply chains draw from 2-chloro-5-chloromethylpyridine and nitroguanidine chemical precursors, with single-source vulnerability concentrated in Chinese intermediate suppliers. Tariff exposure runs through EU-Asia trade corridors for redirected inventories. Distribution runs through agricultural cooperatives in consolidated markets and traditional distributors in fragmented regulatory environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large vegetable marketing organizations, with California Central Valley cooperatives displacing traditional distributor relationships through direct supply agreements that reshape procurement leverage across specialty crop channels.
For Market Incumbents: Secure captive technical-grade supply through backward integration into 2-chloro-5-chloromethylpyridine production, insulating against input cost volatility from Chinese intermediate suppliers. Lock in channel control via exclusive seed-treatment partnerships with Brazilian soybean operations and Indian cotton-belt cooperatives, defending against biological substitute encroachment from Bacillus thuringiensis formulations. For New Entrants and Emerging Players: Lead with precision-application compatibility as the go-to-market angle, targeting Indonesian protected-crop horticulture in West Java and North Sumatra where regulatory infrastructure lags acreage expansion. Penetrate the microencapsulate formulation tier for European greenhouse operators facing supermarket chain residue specifications, where incumbent concentration is lowest and premium pricing endures. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agrochemical conglomerates divesting non-core formulation assets amid regulatory contraction in outdoor-use markets. Five-to-ten-year viability hinges on greenhouse residual permit persistence and precision-application technology integration. Watch for EFSA re-evaluation timelines under regulation 1107/2009 as the signal for European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Actives | Captive supply of imidacloprid intermediates insulates Bayer and Syngenta from Chinese input volatility. |
| Microencapsulation R&D Partnership | Collaboration with Spanish greenhouse operators accelerates residue-compliant formulation adoption. |
| Direct Supply Agreement with Cooperatives | California Central Valley vegetable marketing organizations displace distributor margins through consolidated procurement. |
| Seed-Treatment Platform Expansion | Brazilian coated-seed integration in Mato Grosso reduces foliar spray volumes and locks in channel control. |
| Greenhouse Residual Permit Defense | BASF leverages Lower Saxony protected-crop access to sustain European positioning amid outdoor prohibitions. |
Study Parameters
The analysis maps neonicotinoid product types, application segments, and formulation technologies, each validated through technical-grade manufacturers, downstream formulators, and agricultural cooperative procurement directors. Primary interviews with plant managers at Rhine-Ruhr formulation facilities, distribution channel partners in São Paulo and Mumbai, and regulatory affairs leads navigating EPA conditional registrations combined with secondary validation. Secondary sources include EPA pollinator risk assessment dockets, EFSA re-evaluation submissions under regulation 1107/2009, Indian Central Insecticides Board registration databases, and customs trade data for technical-grade active ingredient flows. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions modeled include product type chemistry, agricultural versus commercial application channels, liquid versus microencapsulate formulation tiers, and distributor versus cooperative procurement pathways. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory event impacts. Industry-specific forecast inputs incorporate EFSA re-evaluation timelines, EPA registration review milestones, and state-level resistance-monitoring mandate compliance rates.
Underlying assumptions cover sustained pink bollworm pressure in Indian cotton-belt states, EFSA greenhouse residual permit persistence, and Brazilian soybean seed-treatment integration rates, with deviation risk concentrated in accelerated biological substitute adoption and Codex Alimentarius residue tolerance harmonization failures. Revision becomes warranted when pollinator-risk regulatory restrictions cross thresholds that trigger mass grower transitions to non-neonicotinoid chemistries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Europe Silage Additives Market