
 Neem Pesticides Market | 2026-2036
Neem Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Neem Pesticides Market Analytics
Premium cold-pressed azadirachtin formulations is decoupling from commodity neem cake powders in both pricing and distribution channels. E.I.D. Parry (India) Ltd anchors its position through captive neem seed collection networks across Tamil Nadu and Andhra Pradesh. Fortune Biotech Ltd differentiates via high-purity extraction protocols that meet European import thresholds for residual solvents. Ozone Biotech competes on volume scale in the African and Southeast Asian export markets.
Neem pesticides are botanical formulations derived from Azadirachta indica seed kernels, typically containing 0.03% to 5% azadirachtin by weight alongside salannin and nimbin triterpenoids, functioning as antifeedants and insect growth regulators against chewing and sucking pests. Liquid formulations lead commercial volumes due to ease of foliar application and tank-mix compatibility with conventional sprayers, while emulsifiable concentrates capture premium margins through extended field persistence and lower phytotoxicity risk. Agricultural applications dominate tonnage as row-crop growers integrate neem into resistance management programs, though home and garden segments exhibit faster growth rates driven by municipal pesticide restrictions in urban catchments.
India's Central Insecticides Board mandates registration under the Insecticides Act for all azadirachtin products above 0.15% concentration, creating compliance barriers for unformulated seed powder traders. The EU's F-Gas Regulation and Sustainable Use Directive are redirecting horticultural procurement toward biopesticide alternatives, tightening residue tolerance protocols for imported produce. Stakeholders must monitor evolving equivalence standards between national organic certification bodies to preserve cross-border market access.
Market Dynamics
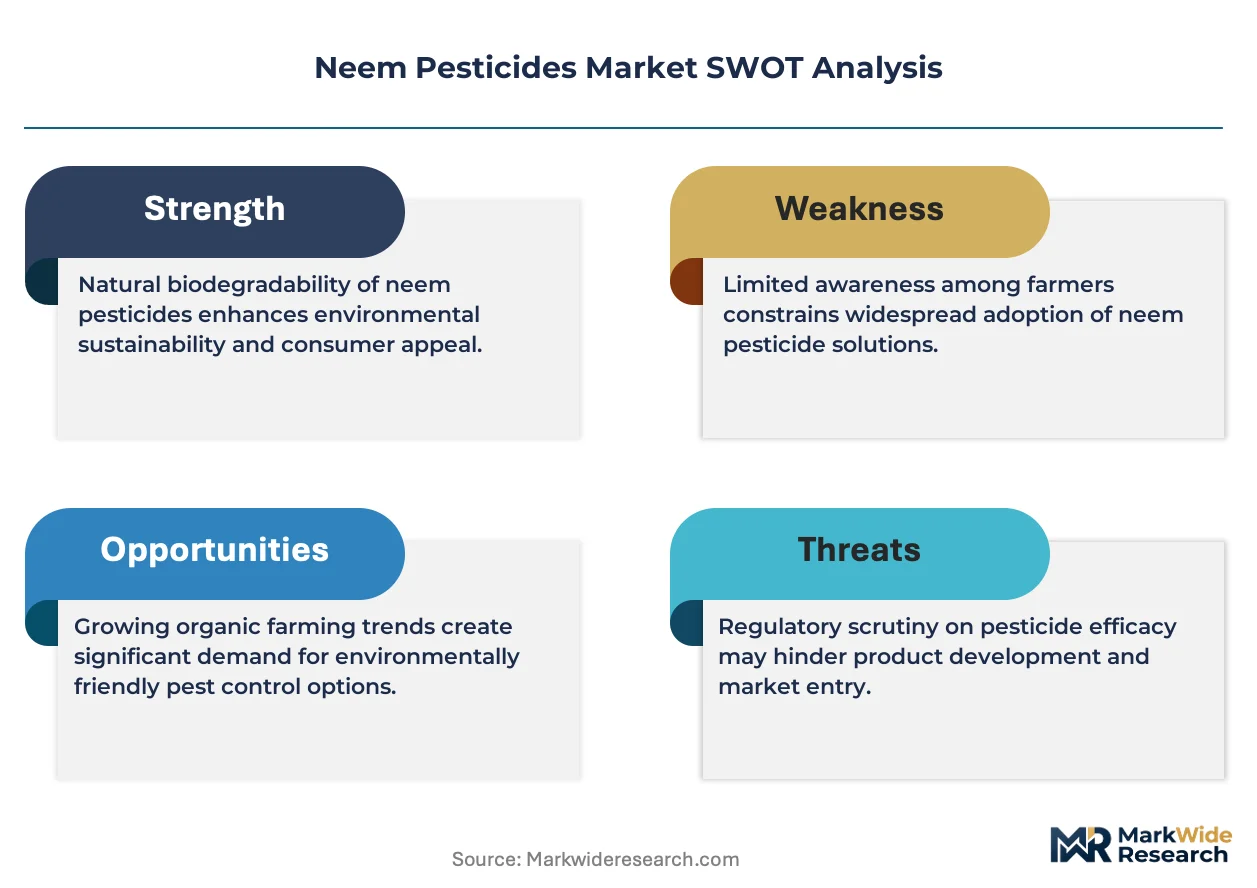
Azadirachtin extraction technology is polarizing the Neem Pesticides Market between high-purity pharmaceutical-grade producers and commodity solvent-extraction operators, compressing mid-tier margins while concentrating procurement power among certified organic exporters.
Growth Catalysts
- EU F-Gas Regulation phase-down:Horticultural buyers in Spain and Italy are substituting synthetic insecticides with azadirachtin-based alternatives to comply with residue thresholds on exported produce.
- Maharashtra grape cluster resistance cycles:Pomegranate and table grape growers in Nashik-Solapur belt are integrating neem into rotation programs against thrips and fruit borer populations.
- India's PLI scheme for agrochemicals:Domestic manufacturers are expanding cold-pressed extraction capacity to capture incentives for import-substituting active pharmaceutical ingredients.
Market Restraints
- Seed kernel supply volatility:Tamil Nadu and Andhra Pradesh collection networks face yield fluctuations from erratic monsoon patterns, concentrating input risk with regional aggregators.
- Residual solvent compliance:European EFSA thresholds for methanol and hexane residues in imported azadirachtin exceed capabilities of conventional solvent-extraction facilities.
- Synthetic pyrethroid price compression:Generic deltamethrin and lambda-cyhalothrin formulations from Chinese manufacturers undercut neem-based alternatives on cost-per-hectare metrics.
Strategic Opportunities
- Kenya and Tanzania export corridors:East African horticultural exporters to EU markets lack local biopesticide manufacturing, creating first-mover openings for formulation partnerships.
- Drone-based precision application:Ultralow-volume spraying systems are reducing azadirachtin dosage rates while improving coverage uniformity in orchard crops.
- India's organic certification harmonization:APEDA's alignment with EU 2018/848 standards is streamlining export documentation for Participatory Guarantee System farmers.
Industry Challenges
- Analytical chemistry skill scarcity:High-performance liquid chromatography operators capable of azadirachtin quantification are concentrated in Hyderabad and Bangalore, constraining quality control scaling.
- Registration timeline compression:India's Central Insecticides Board requires 24-36 month field efficacy trials for new formulations, delaying product launch cycles against faster-moving synthetic competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neem Pesticides Market |
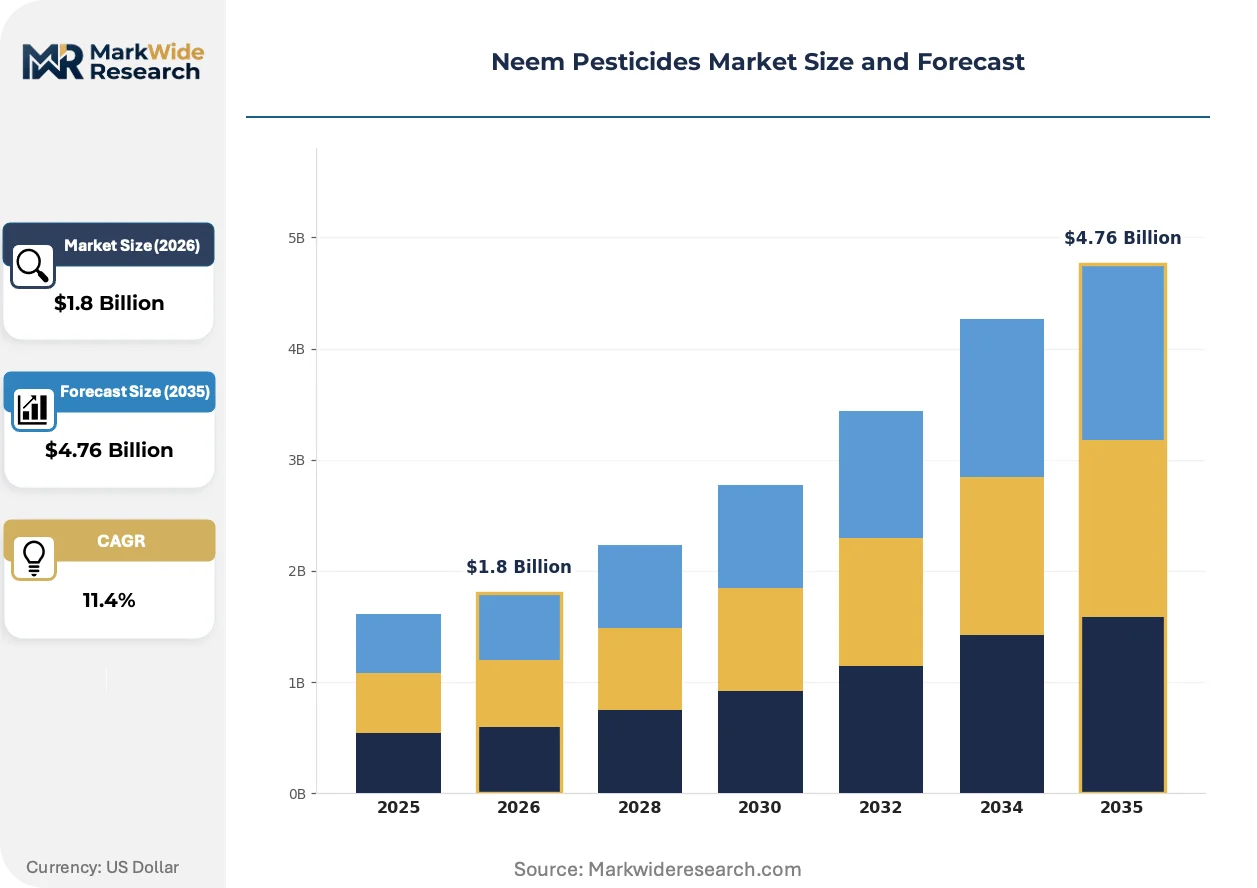
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Emulsifiable Concentrate Application: Agricultural, Horticultural, Home & Garden, Forestry Formulation: Organic, Synthetic, Natural, Biopesticide Target Pest: Insects, Fungi, Bacteria, Nematodes |
| Companies Covered | Gramin India Agri Business, E.I.D. Parry (India) Ltd, Ozone Biotech, Agro Extracts Limited, Prithvi Exports, Neem India Products Pvt Ltd, Fortune Biotech Ltd, Neeming Australia Pty Ltd, Parker Biotech Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neem Pesticides Market Evolving Landscape
Formulation chemistry and application hardware are converging to extend azadirachtin field persistence while reducing operator exposure, reshaping how botanical pesticides compete with synthetic alternatives on performance metrics rather than narrative alone.
Encapsulation technology using chitosan-alginate matrices is modularizing azadirachtin delivery systems. Grape and citrus growers in California's Central Valley are piloting microencapsulated formulations that extend residual activity from 48 hours to 7-10 days. This technology is compressing the performance gap with synthetic insect growth regulators while preserving beneficial insect populations.
India's Central Insecticides Board revised its biopesticide registration guidelines in 2023 to permit reduced field trial requirements for existing azadirachtin formulations with proven equivalence. Domestic manufacturers are accelerating dossier submissions for emulsifiable concentrate variants. Maharashtra-based exporters are prioritizing registrations to secure shelf space ahead of EU Sustainable Use Directive implementation deadlines.
Contract spraying services are displacing individual farmer procurement in Vietnam's Mekong Delta vegetable belts. Service providers bundle azadirachtin applications with pheromone monitoring and drone deployment, capturing margin that previously flowed through distributor networks. This consolidation is most advanced in Long An and Tien Giang provinces where land consolidation has reduced the number of decision-making units by 40 percent over five years.
Neem Pesticides Market Segmentation
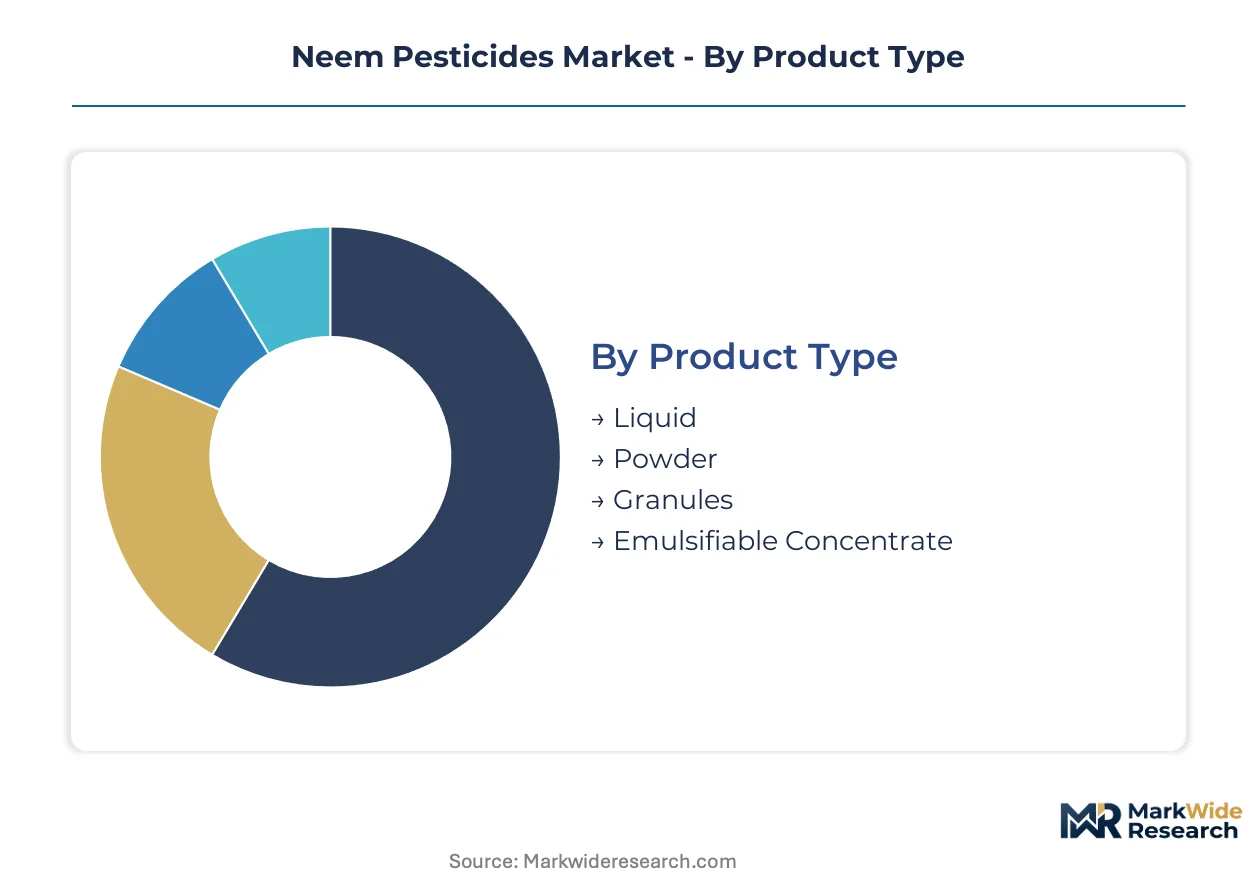
Neem pesticide segmentation reveals how formulation chemistry and application hardware are diverging across use cases. Procurement patterns in Maharashtra's grape belt and California's Central Valley demonstrate how technical specifications drive purchasing decisions more than price alone.
Product Type:
Liquid and emulsifiable concentrate formulations are polarizing extraction technology investments between cold-pressed pharmaceutical-grade producers and commodity solvent-extraction operators.
- Liquid:Aqueous or oil-based suspensions containing 0.03% to 5% azadirachtin enable foliar application through conventional backpack and tractor-mounted sprayers. Demand concentrates in Maharashtra's Nashik-Solapur belt where grape and pomegranate growers integrate neem into rotation programs against thrips and fruit borer populations facing synthetic insecticide resistance.
- Emulsifiable Concentrate:Oil-in-water formulations with surfactant packages extend field persistence from 48 hours to 7-10 days through improved cuticle penetration and rainfastness. California's Central Valley citrus and grape growers are piloting microencapsulated variants that compress the performance gap with synthetic insect growth regulators.
- Powder:Dry formulations derived from neem cake or seed kernel meal typically contain 0.15% to 0.6% azadirachtin alongside nitrogen-rich organic matter for soil amendment applications.
- Granules:Slow-release matrix formulations embedding azadirachtin in clay or organic carriers target soil-dwelling pest stages with reduced leaching risk.
Mature deployment sits with liquid formulations in established agricultural procurement channels. Newer deployment is concentrated in emulsifiable concentrate variants as EU F-Gas Regulation phase-down redirects horticultural buyers toward extended-residue biopesticide alternatives.
Application:
End-use concentration follows regulatory pressure gradients, with municipal pesticide restrictions in urban catchments accelerating non-agricultural adoption faster than tonnage growth.
- Agricultural:Row-crop integration of azadirachtin into resistance management programs dominates commercial volumes, particularly in soybean and cotton systems where chewing pest pressure overlaps with beneficial insect conservation priorities. India's PLI scheme for agrochemicals is accelerating domestic cold-pressed extraction capacity to serve this segment.
- Horticultural:High-value fruit and vegetable production in Spain, Italy, and Kenya commands premium pricing for residue-compliant formulations meeting EU import thresholds. East African exporters lack local biopesticide manufacturing, creating first-mover openings for formulation partnerships serving cut flower and fresh produce supply chains.
- Home & Garden:Municipal restrictions on synthetic pyrethroids in urban catchments across Germany, France, and the Netherlands are displacing retail shelf space toward botanical alternatives with consumer-friendly safety profiles.
- Forestry:Aerial and ground-based application in plantation timber systems targets defoliating Lepidoptera populations where broad-spectrum synthetic alternatives conflict with aquatic buffer zone regulations.
Volume leadership remains with agricultural procurement. Steepest expansion trajectory is concentrated in home and garden segments where regulatory compression of synthetic alternatives outpaces farmer education requirements.
Formulation:
Certification grade and residual solvent thresholds are fragmenting procurement between premium export channels and domestic commodity markets.
- Organic:Formulations meeting EU 2018/848 and USDA National Organic Program standards command 40-60% price premiums through certified supply chain segregation from conventional processing. APEDA's alignment with EU standards is streamlining export documentation for Indian Participatory Guarantee System farmers.
- Biopesticide:Regulatory-classified formulations requiring Central Insecticides Board registration above 0.15% azadirachtin concentration face 24-36 month field efficacy trial timelines that delay product launch cycles.
- Natural:Unformulated or minimally processed seed kernel powders and crude extracts falling below registration thresholds serve informal markets with minimal quality standardization.
- Synthetic:Azadirachtin-synthetic pyrethroid combination products targeting immediate knockdown plus residual antifeedant activity occupy niche positions in resistance management programs.
Price differentiation sits with organic certification grade. Volume scale is concentrating in biopesticide-classified formulations as registration timeline compression becomes a competitive capability.
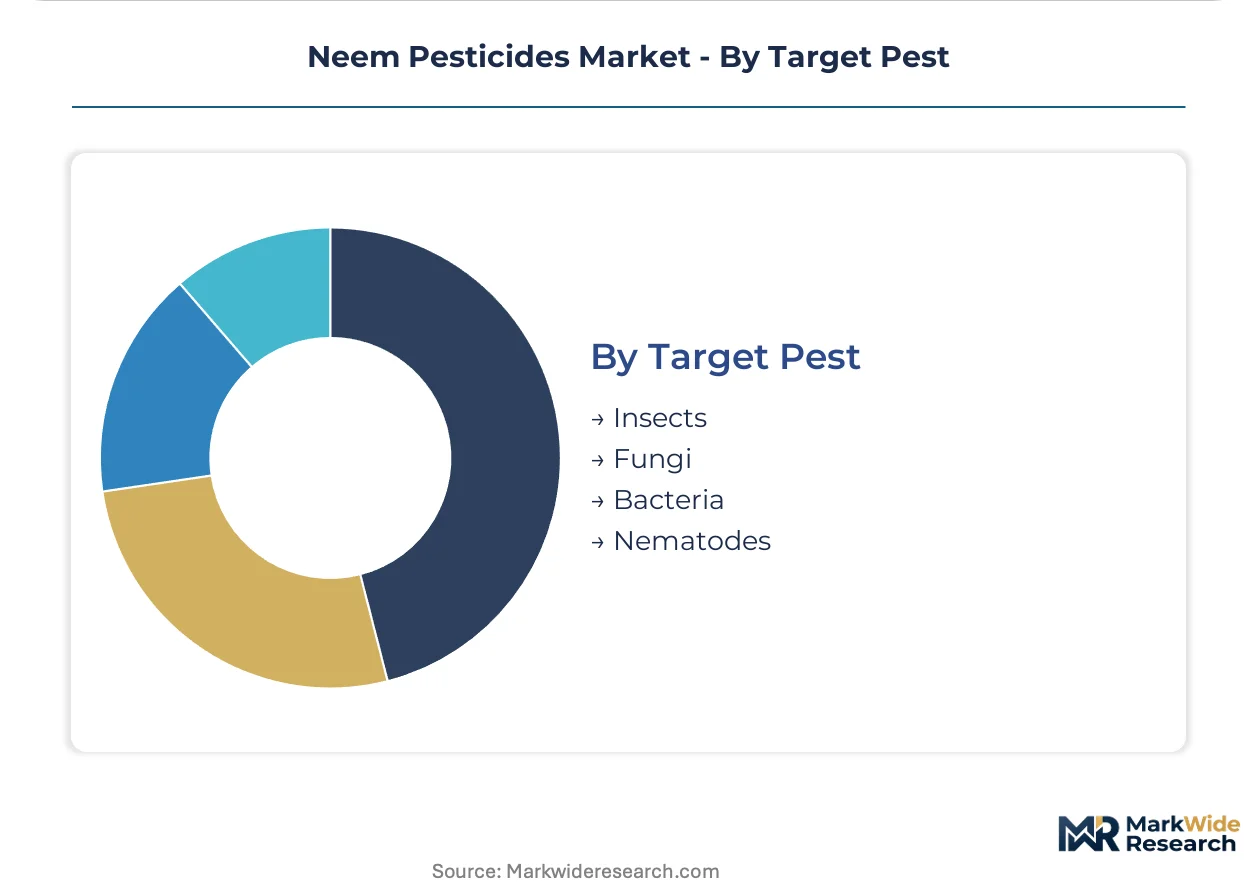
Target Pest:
Mode-of-action specificity determines formulation chemistry investments, with antifeedant and insect growth regulator properties dominating R&D allocation.
- Insects:Chewing and sucking pest targets including Lepidoptera larvae, aphids, whiteflies, and thrips represent the primary commercial application, with azadirachtin's ecdysteroid antagonism disrupting molting sequences. Drone-based precision application in Vietnam's Mekong Delta is reducing dosage rates while improving coverage uniformity against vegetable pest complexes.
- Fungi:Azadirachtin's terpenoid fractions exhibit antifungal properties against powdery mildew and rust pathogens in high-value horticultural systems, though efficacy consistency lags behind dedicated fungicide alternatives.
- Nematodes:Soil-dwelling plant-parasitic nematode suppression through neem cake incorporation targets egg hatch inhibition and juvenile mortality in protected cultivation systems.
- Bacteria:Antibacterial applications remain experimental, with limited field validation against fire blight and bacterial wilt in comparison to established copper-based alternatives.
Established efficacy validation sits with insect targets. Emerging deployment is concentrated in nematode suppression as soil health priorities redirect amendment procurement toward multifunctional organic inputs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Nashik-Solapur belt anchors procurement intensity for azadirachtin formulations, with grape and pomegranate growers driving resistance-management adoption across five country-level markets.
India
Tamil Nadu and Andhra Pradesh seed collection networks supply kernel inputs to domestic extractors, while the PLI scheme for agrochemical manufacturing accelerates cold-pressed capacity expansion. The Central Insecticides Board mandates registration under the Insecticides Act for formulations above 0.15% azadirachtin concentration. Maharashtra's organic farming cooperatives are expanding procurement of azadirachtin-based formulations to serve export-oriented horticulture.
United States
California's Central Valley citrus and grape growers pilot microencapsulated formulations extending residual activity to 7-10 days. The EPA regulates azadirachtin as a biochemical pesticide with reduced registration requirements compared to conventional synthetics. Fresno and Kern counties concentrate demand where beneficial insect conservation priorities overlap with chewing pest pressure.
Spain
Almería and Murcia greenhouse operators substitute synthetic insecticides to comply with EU F-Gas Regulation phase-down and residue thresholds on exported produce. The EU's Sustainable Use Directive tightens procurement standards for horticultural biopesticides. Valencia's citrus belt integrates azadirachtin into integrated pest management rotations against Mediterranean fruit fly.
Kenya
Naivasha and Thika flower exporters lack local biopesticide manufacturing, creating first-mover openings for formulation partnerships serving EU supermarket supply chains. The country's national agricultural regulator enforces residue monitoring for export certification. Rift Valley vegetable growers face compliance pressure from British and German retail procurement standards.
Vietnam
Long An and Tien Giang provinces in the Mekong Delta concentrate contract spraying services bundling azadirachtin with drone deployment. Land consolidation has reduced decision-making units by 40 percent over five years, displacing individual farmer procurement. The Ministry of Agriculture and Rural Development oversees biopesticide registration timelines affecting product launch cycles.
Neem Pesticides Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction technology and certification grade. Cold-pressed pharmaceutical-grade producers capture 40-60% price premiums through EU 2018/848 and USDA National Organic Program compliance, while solvent-extraction operators compete on volume scale in African and Southeast Asian export corridors. Three archetypes dominate: captive seed network aggregators, high-purity extraction specialists, and volume-scale export traders. Competitive moves concentrate on registration timeline compression and geographic expansion into East African horticultural supply chains.
Within the captive network tier, E.I.D. Parry (India) Ltd represents upstream integration into seed collection infrastructure across southern India. Fortune Biotech Ltd occupies a position exemplifying high-purity extraction protocols meeting European residual solvent thresholds. Ozone Biotech sits within the volume-export archetype competing on scale in African and Southeast Asian markets.
| Leading Market Players |
|---|
| Gramin India Agri Business |
| E.I.D. Parry (India) Ltd |
| Ozone Biotech |
| Agro Extracts Limited |
| Prithvi Exports |
| Neem India Products Pvt Ltd |
| Fortune Biotech Ltd |
| Neeming Australia Pty Ltd |
| Parker Biotech Private Limited |
| Others |
Value Network & Pricing Analysis
Captive seed collection networks across Tamil Nadu and Andhra Pradesh anchor supply positions while compressing input cost volatility for integrated extractors, translating upstream control into pricing power that commodity solvent-extraction operators cannot replicate. E.U. 2018/848 certification thresholds and residual solvent compliance requirements stratify procurement channels, concentrating premium margins with cold-pressed pharmaceutical-grade producers who capture organic export premiums.
Pricing Analysis
Yield-per-hectare performance anchors value-based pricing for azadirachtin formulations, with grape and pomegranate growers in Maharashtra's Nashik-Solapur belt paying 40-60% premiums for extended-residue emulsifiable concentrates that compress the efficacy gap with synthetic insect growth regulators. Three-tier pricing structure across organic-certified, biopesticide-registered, and unformulated natural grades reflects certification investment and analytical chemistry capabilities. Cost compression in commodity solvent-extraction tiers intensifies as generic pyrethroid imports from Chinese manufacturers undercut cost-per-hectare metrics. Smallholder vegetable producers in Vietnam's Mekong Delta exhibit highest price sensitivity, while E.U.-oriented horticultural exporters in Kenya and Spain demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from E.U. supermarket procurement standards mandate multi-supplier qualification for Kenyan and Tanzanian flower exporters, fragmenting order volumes across formulation partners to mitigate single-source disruption risk. Kernel supply concentrates in India, with secondary processing capacity in the United States and formulation partnerships emerging in Spain and Kenya. Raw material dependencies center on Azadirachta indica seed kernel availability, cold-pressed extraction equipment, and high-performance liquid chromatography analytical chemistry capacity. Single-source vulnerability in monsoon-dependent seed collection networks poses structural supply risk. Distribution runs through agrochemical distributor networks in established agricultural markets, with contract spraying services displacing individual farmer procurement in Vietnam's consolidating vegetable belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kernel supply volatility from erratic monsoon patterns props pricing power for integrated extractors with captive collection networks, constraining volume expansion for non-integrated competitors and preserving margin premiums across the analysis window.
For Market Incumbents: Anticipate synthetic pyrethroid price compression from Chinese generic manufacturers by accelerating cold-pressed capacity expansion under India's PLI scheme for agrochemicals, while securing Central Insecticides Board registration dossiers for emulsifiable concentrate variants ahead of E.U. Sustainable Use Directive implementation deadlines. Certification investment in E.U. 2018/848 equivalence standards represents the priority defensive lever against mid-tier margin erosion. For New Entrants and Emerging Players: E-commerce direct-to-grower platforms offer the most penetrable route into India's fragmented horticultural procurement, bypassing entrenched distributor networks that E.I.D. Parry and Fortune Biotech have locked through decades of relationship cultivation. White-space targets concentrate in East African formulation partnerships serving Naivasha and Thika flower exporters, and in drone-based precision application service bundling for Vietnam's consolidating Mekong Delta vegetable belts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by agrochemical majors seeking botanical pesticide portfolios to satisfy E.U. F-Gas Regulation compliance requirements and sustainability repositioning mandates. Long-term viability hinges on registration timeline compression capabilities and organic certification infrastructure that preserves cross-border market access. The signal to watch is E.U. residue tolerance protocol tightening on imported produce, which would accelerate substitution demand and revalue premium-compliant extraction assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Collection Networks | Captive kernel supply from Tamil Nadu and Andhra Pradesh aggregators mitigates monsoon-driven input volatility. |
| Cold-Pressed Extraction Capacity Expansion | India's PLI scheme incentives accelerate pharmaceutical-grade azadirachtin production for E.U. organic export channels. |
| Emulsifiable Concentrate Registration Acceleration | Central Insecticides Board dossier submissions compress 24-36 month field trial timelines against synthetic competitors. |
| East African Formulation Partnership | Kenya and Tanzania horticultural exporters lack local biopesticide manufacturing, creating first-mover positioning. |
| Drone-Based Precision Application Service | Ultralow-volume spraying in Vietnam's Mekong Delta reduces dosage rates while capturing margin from distributor displacement. |
Research Methodology
Multi-period observation of azadirachtin formulation registrations, seed kernel collection volumes, and E.U. import compliance rates anchored the trend analysis, supplemented by interviews with extraction plant managers, agrochemical procurement leads at Indian cooperatives, Central Insecticides Board regulatory officials, Kenyan flower exporter quality managers, and Vietnamese contract spraying service operators. Secondary validation drew from APEDA export documentation databases, E.U. F-Gas Regulation implementation guidance, India customs trade data, and SEC filings of listed agrochemical manufacturers. Bottom-up segmentation modeling and top-down macroeconomic triangulation converged on volume and value estimates.
Segment-weighting across product type, application, formulation certification grade, and target pest mode-of-action distributed baseline volumes before applying region-specific growth coefficients over the projection horizon. Agricultural procurement, horticultural export compliance, and home and garden regulatory substitution each carried distinct trajectory assumptions. CAGRs derived from regression analysis of historical registration timelines, adoption curve penetration in Maharashtra's grape belt, and E.U. directive implementation pacing. Industry-specific forecast inputs included monsoon variability indices affecting seed kernel yields and drone spraying penetration rates in Southeast Asian vegetable systems.
The model holds under stable E.U.-India organic certification equivalence and consistent PLI scheme incentive structures; deviation in E.U. residue tolerance protocol tightening or Indian monsoon pattern disruption would shift volume and value outlooks materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Turf and Ornamental Inputs Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market