
 Bird Repellent Market | 2026-2036
Bird Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
Bird Repellent Market Intelligence
North American chemical manufacturers is restructuring supply chains for bird repellent actives after methyl anthranilate reformulation deadlines. Rentokil Initial plc leverages its integrated pest management platform to bundle avian services with rodent and insect protocols across commercial contracts. Bird-X LLC anchors its position through proprietary sonic technology developed for agricultural and aviation end users. Bird Control Group competes with laser-based systems that reduce bird strikes at runways without disrupting flight operations.
Bird repellent formulations encompass chemical agents, physical barriers, electronic devices, and visual deterrents engineered to modify avian behavior without lethal outcomes. Methyl anthranilate and anthraquinone represent the most widely deployed active ingredients in chemical repellents, functioning through taste aversion at concentrations between 10 and 20 percent. Electronic scarecrows and ultrasonic devices command the fastest expansion as precision agriculture operators seek automated, labor-reducing solutions for large-scale field protection. Chemical repellents retain the largest revenue share due to established efficacy in vineyard and berry production, though margin compression from regulatory testing costs is accelerating.
EPA registration requirements under FIFRA govern chemical repellent commercialization in the United States, while REACH compliance shapes formulation chemistry for European suppliers. The EU Green Deal and national biodiversity strategies in Germany and France are restricting certain visual deterrent materials with microplastic components. Facility managers and municipal authorities must monitor evolving aviation safety mandates from FAA and EASA that increasingly specify non-lethal wildlife hazard management protocols at certified airports.
Market Dynamics
EPA registration deadlines for methyl anthranilate reformulation are forcing chemical manufacturers to restructure active ingredient supply chains while airport authorities accelerate procurement of non-lethal electronic systems.
Growth Catalysts
- FIFRA Compliance Windows:EPA-mandated reformulation timelines for avian repellent actives are pulling forward R&D investment in non-toxic chemistry pipelines.
- Aviation Safety Mandates:FAA protocols specifying non-lethal wildlife hazard management at certified airports are expanding procurement of laser and sonic deterrent systems.
- Precision Agriculture Automation:Large-scale vineyard and berry operators are deploying electronic scarecrows to reduce labor dependency during critical fruiting periods.
Market Restraints
- Regulatory Testing Cost Burden:EPA registration requirements under FIFRA impose multi-year evaluation timelines that compress margins for chemical repellent developers.
- Active Ingredient Concentration Limits:Methyl anthranilate and anthraquinone formulations face efficacy ceilings at 10-20 percent concentrations, constraining performance differentiation.
- Ultrasonic Frequency Adaptation:Target avian species demonstrate habituation to fixed-frequency electronic deterrents, degrading field efficacy over deployment cycles.
Strategic Opportunities
- EU Green Deal Alignment:REACH-compliant formulation chemistry positions suppliers to capture replacement demand as microplastic-containing visual deterrents face phase-out.
- Grain Storage Facility Modernization:Australian bulk handling operators are retrofitting silo complexes with integrated electronic and chemical deterrent systems.
- AI-Enabled Species Recognition:Machine vision paired with directional acoustic emitters enables targeted deterrence without blanket sonic pollution.
Industry Challenges
- Field Efficacy Validation:Demonstrating consistent avian aversion across variable weather conditions and species mixes requires extended multi-site trials.
- Legacy Infrastructure Integration:Retrofitting existing agricultural and aviation facilities with automated deterrent networks demands customized mounting and power solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bird Repellent Market |
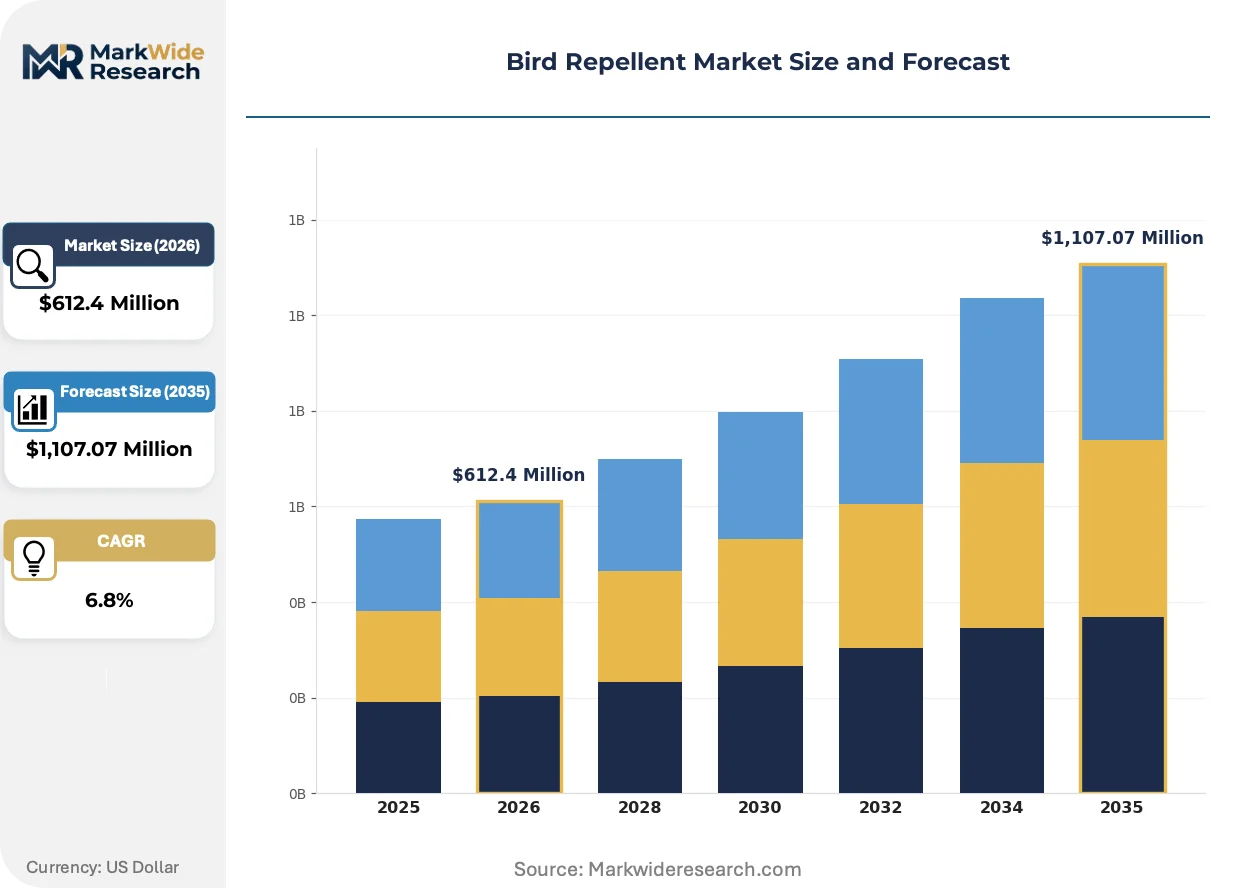
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Devices, Visual Deterrents, Chemical Repellents, Physical Barriers, Electronic Scarecrows Application: Agricultural Fields, Airports, Warehouses, Urban Areas, Residential Gardens End User: Farmers, Facility Managers, Property Developers, Municipal Authorities Distribution Channel: Direct Sales, Online Retailers, Distributors, Specialty Stores |
| Companies Covered | Rentokil Initial plc, Bird Barrier of America, Bird-B-Gone Inc., Anticimex AB, Bird Control Group, Bird-X LLC, Bird Gard Ltd, Migratec GmbH, Bird Control Denmark APS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bird Repellent Market Strategic Shifts & Innovations
Autonomous deterrent systems incorporating species-specific targeting are displacing broadcast chemical applications. Regulatory chemistry constraints and labor cost pressures are converging to reshape procurement criteria across agricultural and aviation end uses.
Laser-based avian dispersal technology is overtaking pyrotechnic and acoustic methods at commercial airports. These systems project non-visible beams that trigger escape responses without disrupting flight operations or generating noise complaints from surrounding communities. German airport authorities led adoption, with Australian and US facilities now following.
REACH authorization processes are restricting microplastic-containing visual deterrent materials across EU member states. ECHA substance evaluation timelines are extending reformulation lead times for chemical repellent suppliers serving European vineyard and berry markets. German and French national biodiversity strategies are accelerating substitution toward biodegradable visual elements.
Service bundling is consolidating procurement decisions across integrated pest management contracts. Facility managers now specify single-vendor accountability for avian, rodent, and insect protocols rather than maintaining separate supplier relationships. This pattern concentrates contract value with full-service providers in US commercial and municipal segments.
Bird Repellent Market Segmentation
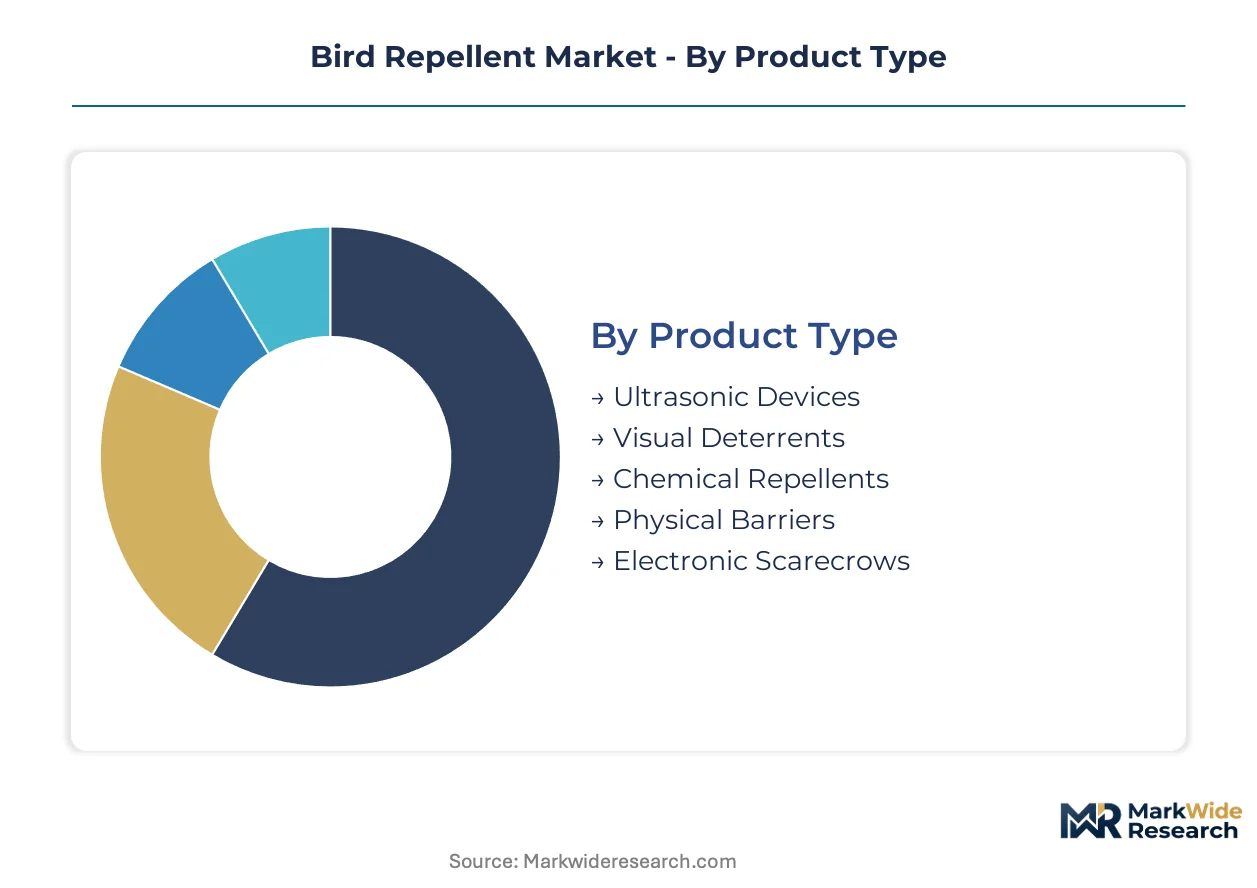
Bird repellent procurement splits sharply between standalone point solutions and integrated facility-wide systems. Understanding these deployment patterns reveals which segments command premium pricing versus commodity positioning across agricultural and aviation end uses.
Product Type:
Standalone ultrasonic and visual units dominate residential and small-farm procurement, while electronic scarecrows and chemical systems embed into larger automated networks.
- Ultrasonic Devices:Emit frequency-modulated acoustic waves between 15-45 kHz to trigger avian stress responses without human detection. German vineyard operators deploy these as perimeter arrays during ripening windows, though habituation effects limit single-frequency efficacy. Demand concentrates in precision agriculture clusters seeking labor reduction.
- Electronic Scarecrows:Combine motion sensors, species-recognition software, and multi-modal deterrent activation. Australian grain storage facilities and US airport authorities lead procurement of these programmable systems for 24/7 coverage with minimal staffing.
- Visual Deterrents:Reflective tapes, predator eye replicas, and laser projectors exploit optical reflex triggers in target species.
- Chemical Repellents:Methyl anthranilate and anthraquinone formulations create taste aversion at 10-20 percent concentrations.
- Physical Barriers:Netting, spikes, and exclusion fencing deliver permanent perimeter control.
Chemical repellents lead volumes today; electronic scarecrows are gaining share fastest.
Application:
Cost-tier stratification separates high-investment aviation infrastructure from price-sensitive agricultural and residential deployments.
- Agricultural Fields:Berry and vineyard operations in California, France, and Australia represent the largest addressable base for automated deterrent deployment. Seasonal labor shortages during critical fruiting periods accelerate electronic system adoption over manual alternatives.
- Airports:FAA and EASA mandates for non-lethal wildlife hazard management drive procurement of laser and integrated sonic systems. German hubs including Frankfurt and Munich pioneered laser dispersal technology now spreading to US facilities.
- Warehouses:Food storage and logistics facilities require continuous protection against contamination and structural damage.
- Urban Areas:Municipal authorities manage roosting pressure on public infrastructure and waste management sites.
- Residential Gardens:Small-scale ultrasonic and visual units serve homeowner protection needs.
Agricultural fields anchor current revenue; airports show the steepest expansion trajectory.
End User:
Customer-type segmentation distinguishes between owner-operated deployments and outsourced facility management contracts.
- Farmers:Owner-operators of vineyards, berry fields, and grain operations purchase direct or through agricultural supply cooperatives. California and Australian producers increasingly specify bundled chemical-electronic protocols.
- Facility Managers:Commercial property and logistics operators procure through integrated pest management contracts bundling avian, rodent, and insect services.
- Municipal Authorities:City and regional governments manage public space applications including airports, parks, and waste facilities.
- Property Developers:Construction-phase and completed commercial developments require pre-occupancy bird exclusion.
Farmers represent the largest installed base; facility managers are shifting procurement fastest toward bundled service contracts.
Distribution Channel:
Supply concentration varies by channel, with direct relationships capturing complex aviation contracts while retail serves fragmented residential demand.
- Direct Sales:Manufacturer field teams handle large aviation and agricultural enterprise accounts requiring site assessment and custom installation. Rentokil Initial and Bird-X maintain dedicated technical sales forces for this segment.
- Distributors:Agricultural supply and pest control wholesalers stock chemical repellents and portable electronic units for vineyard and warehouse operators.
- Online Retailers:E-commerce platforms serve residential and small commercial purchasers seeking ultrasonic and visual deterrents.
- Specialty Stores:Garden centers and farm supply outlets provide local access to physical barriers and entry-level electronic devices.
Direct sales capture the highest contract values; online retailers are expanding fastest into mid-tier agricultural segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reformulation cost disparities are redirecting chemical active production toward jurisdictions with streamlined environmental registration pathways. Manufacturers seeking FIFRA compliance efficiencies concentrate manufacturing in the United States, while REACH-aligned chemistry clusters consolidate in Germany.
United States
California vineyard operators and Texas grain storage facilities drive procurement of electronic scarecrows and methyl anthranilate formulations. EPA registration deadlines under FIFRA are compressing margins for domestic chemical manufacturers while accelerating airport authority adoption of laser deterrent systems. The Central Valley agricultural corridor anchors demand for automated perimeter protection during critical fruiting windows.
Germany
Frankfurt and Munich airport authorities pioneered laser-based avian dispersal technology now spreading to commercial aviation infrastructure nationwide. ECHA substance evaluation timelines under REACH extend reformulation lead times for anthraquinone suppliers serving European berry markets. The Rhine-Main logistics cluster generates sustained procurement for warehouse-integrated electronic deterrent networks.
Australia
Bulk grain handling operators in New South Wales and Victoria are retrofitting silo complexes with combined electronic and chemical deterrent systems. TGA-aligned biocide regulations shape import requirements for active ingredient formulations. The Murray-Darling irrigation basin concentrates vineyard demand for ultrasonic perimeter arrays during harvest periods.
France
Bordeaux and Champagne vineyard cooperatives represent the largest European addressable base for automated deterrent deployment. National biodiversity strategies restrict microplastic-containing visual deterrent materials, accelerating substitution toward biodegradable alternatives. The Île-de-France logistics corridor sustains warehouse facility procurement for continuous avian exclusion systems.
United Kingdom
Commercial property managers in Greater London bundle avian services with rodent and insect protocols through integrated pest management contracts. HSE guidance on non-lethal wildlife management influences municipal procurement criteria for public infrastructure applications. The Thames Valley logistics cluster generates demand for automated deterrent installation in food storage and distribution facilities.
Bird Repellent Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-enabled species recognition and autonomous targeting systems. The vendor base stratifies between full-service integrated pest management platforms and specialized technology developers. Three archetypes dominate: chemical formulation specialists, electronic deterrent technology developers, and bundled service providers. Competitive dynamics center on strategic partnerships for distribution reach and portfolio diversification into adjacent wildlife management categories.
Within the bundled service tier, Rentokil Initial plc exemplifies the integrated platform model spanning avian, rodent, and insect protocols. Bird-X LLC anchors the electronic technology specialist position through proprietary sonic system development. Bird Control Group occupies the laser-based dispersal niche serving aviation infrastructure requirements. These three entities represent distinct strategic postures without implying specific market share or operational scale claims.
| Leading Market Players |
|---|
| Rentokil Initial plc |
| Bird Barrier of America |
| Bird-B-Gone Inc. |
| Anticimex AB |
| Bird Control Group |
| Bird-X LLC |
| Bird Gard Ltd |
| Migratec GmbH |
| Bird Control Denmark APS |
| Others |
Cost & Logistics Intelligence
EPA registration deadlines under FIFRA are gating qualified supply for methyl anthranilate formulations and restricting premium-tier pricing access to manufacturers with completed reformulation dossiers. Buyers lacking verified EPA-compliant sources face extended lead times and elevated procurement costs for chemical repellent actives.
Pricing Analysis
Distributor margin layers compress as direct sales capture complex aviation and agricultural enterprise accounts requiring site assessment. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled species-recognition systems from fixed-frequency ultrasonic units and commodity chemical formulations. Cost compression in standard-tier chemical repellents is intensifying because FIFRA-mandated testing extends development timelines. Small-farm owner-operators exhibit highest price sensitivity; airport authorities demonstrate lowest sensitivity given safety mandate compliance requirements.
Supply Chain Analysis
REACH certification and EPA registration gating restricts active ingredient supply to qualified manufacturers with completed dossiers in the United States, Germany, and China. Methyl anthranilate and anthraquinone feedstock draws from agrochemical intermediate producers; electronic deterrent components rest on semiconductor and acoustic emitter supply chains. Single-source vulnerability concentrates in specialty acoustic transducer manufacturing. Distribution runs through agricultural supply cooperatives for vineyard operators and direct manufacturer field teams for aviation infrastructure contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement shifts toward premium specifications for AI-enabled species-recognition systems with documented field efficacy validation.
For Market Incumbents: Extend platform bundling advantages by integrating avian deterrent protocols with rodent and insect services across integrated pest management contracts. Invest in backward integration into methyl anthranilate active ingredient production to defend margin position against FIFRA compliance cost inflation. Prioritize certification investment for REACH-compliant formulation chemistry to capture EU Green Deal replacement demand. For New Entrants and Emerging Players: Agricultural supply cooperatives represent the most penetrable channel partner type for mid-tier electronic deterrent penetration. Target Australian grain storage facility modernization programs and French vineyard cooperative procurement cycles as white-space entry points. Pursue demonstration-led go-to-market approaches featuring multi-site field efficacy trials during critical fruiting windows. For Investors and Strategic Acquirers: Roll-up economics work for integrated pest management platforms because facility managers are consolidating procurement decisions toward single-vendor accountability across avian, rodent, and insect protocols. Long-term viability centers on technology-enabled service differentiation rather than commodity chemical positioning. Monitor FAA and EASA procurement specification shifts toward autonomous deterrent systems as inflection indicator for electronic technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredients | Captures margin compression from EPA FIFRA registration cost inflation for methyl anthranilate supply. |
| AI-Enabled Species Recognition Development | Enables targeted deterrence without blanket sonic pollution, commanding premium positioning in aviation contracts. |
| REACH-Compliant Formulation Chemistry | Positions suppliers for EU Green Deal-driven replacement demand as microplastic visual deterrents phase out. |
| Integrated Pest Management Platform Expansion | Consolidates procurement decisions with facility managers seeking single-vendor accountability across wildlife protocols. |
| Multi-Site Field Efficacy Validation Programs | Generates documented performance data required by California vineyard operators and German airport authorities. |
Research Approach
Coverage spans the United States, Germany, Australia, France, and the United Kingdom, with primary inputs from each market cluster. Field research combined structured interviews with airport wildlife management officers, vineyard operations managers, grain storage facility engineers, integrated pest management contract directors, and agricultural supply cooperative procurement leads. Secondary validation drew from EPA FIFRA registration databases, ECHA REACH authorization records, FAA wildlife hazard management guidelines, and EASA safety directives. Bottom-up demand modeling triangulated against top-down industry value chain estimates.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, separating volume growth from price-mix effects and technology substitution dynamics. Segmentation dimensions modeled include product type, application sector, end-user archetype, and distribution channel. CAGRs were derived from fitted growth curves applied to base-year estimates. Industry-specific forecast inputs incorporated FIFRA compliance timeline assumptions and precision agriculture automation adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA registration pathway delays and avian species habituation effects degrading electronic deterrent efficacy. Model outputs reflect assumptions regarding regulatory chemistry constraints and labor cost pressures in agricultural end uses. A model refresh is warranted upon material change in FAA or EASA non-lethal wildlife management procurement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
US Home and Garden Fungicides Market