
 Feed Pelletizing Agents Market | 2026-2036
Feed Pelletizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Pelletizing Agents Market Foresight
Pharmaceutical-grade binder specifications is rotating through the feed pelletizing agents market as livestock producers prioritize pellet durability and nutrient protection over basic cost minimization. Borregaard AS leverages its lignin-based biopolymer expertise to serve premium aquaculture and pet food segments. Cargill sustains broad geographic coverage through its integrated animal nutrition platform and captive distribution networks. BASF SE differentiates via synthetic binder chemistry optimized for high-temperature pelleting processes.
Feed pelletizing agents encompass binders, fillers, and functional additives that mechanically stabilize feed pellets during extrusion, cooling, and transport, typically comprising lignosulfonates, bentonite clays, or specialized starches that achieve pellet durability indices above 90 percent. Their primary commercial purpose is to reduce feed fines, improve handling characteristics, and protect heat-sensitive nutrients from degradation during thermal processing. Binders command the largest revenue share within product type segmentation due to irreplaceable functional performance in high-moisture aquaculture feeds. Livestock feed applications generate the deepest volume pools, though aquaculture feed exhibits faster growth trajectory driven by expanding shrimp and salmon farming operations. Dry formulations dominate manufacturing scale, while liquid variants capture premium positioning in specialized premix applications.
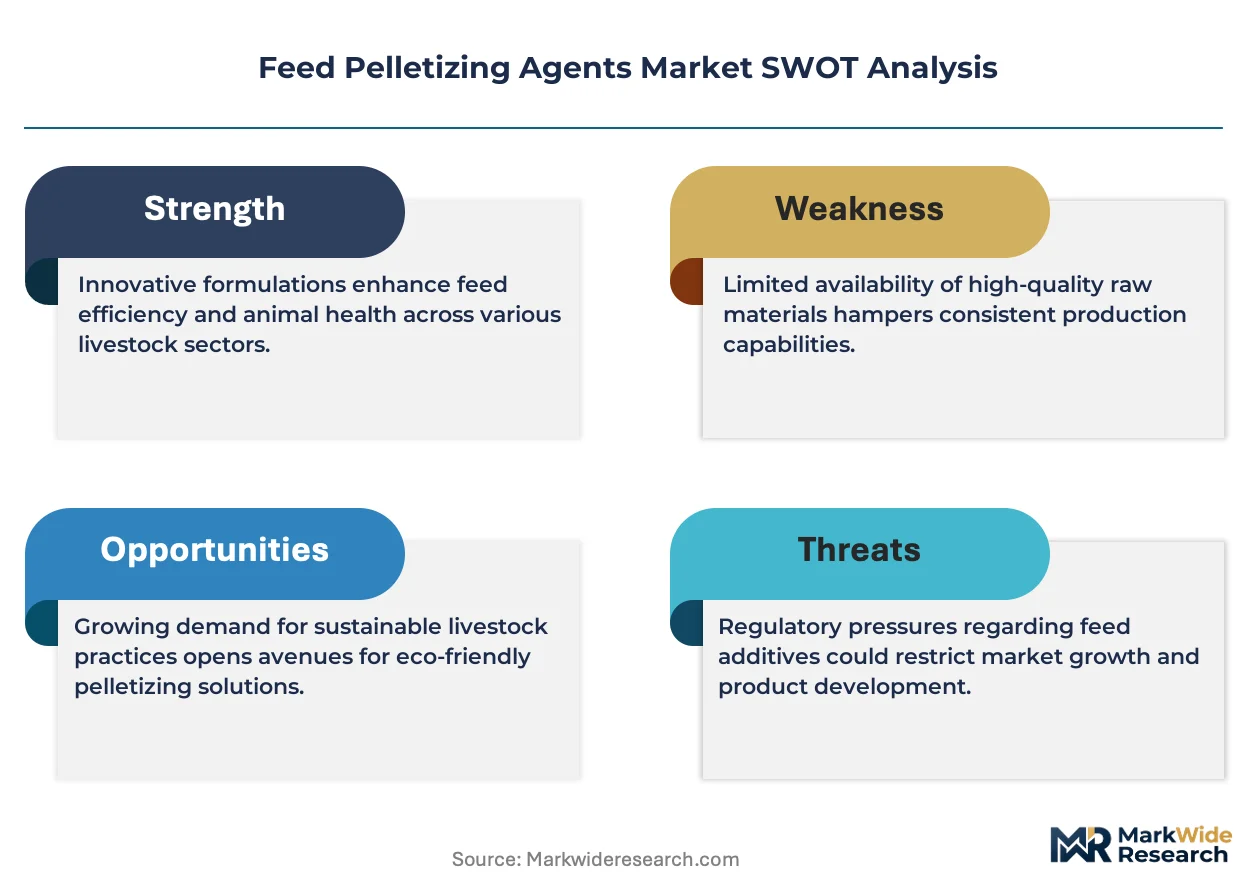
Regulatory frameworks including FDA feed safety rules, EU Feed Hygiene Regulation, and China's GB standards for feed additives collectively shape product registration pathways and residue limits across major producing regions. REACH compliance in Europe and evolving EPA guidelines on mining-derived bentonite processing impose additional testing burdens on suppliers seeking multi-regional market access. Stakeholders must monitor accelerating divergence between regional maximum contaminant thresholds and emerging sustainability certification schemes that increasingly influence procurement decisions by integrated protein companies.
Market Dynamics
The EU Green Deal's binding sustainability mandates are forcing feed manufacturers to abandon petroleum-derived binders in favor of lignin-based and bio-based alternatives, rewiring raw material procurement strategies across integrated protein supply chains.
Growth Catalysts
- REACH compliance deadlines:European compound feed producers face phased restrictions on synthetic additive residues, accelerating qualification of biodegradable binding agents in ruminant and monogastric formulations.
- Shrimp farming intensification:Southeast Asian aquaculture operations require water-stable pellets with durability indices above 90 percent, generating specialized demand for modified starches and lignosulfonate complexes.
- Brazilian integrated operations:JBS, BRF, and Minerva Foods are consolidating feed milling capacity, standardizing pelletized formulations across poultry and pork verticals to optimize feed conversion ratios.
Market Restraints
- Bentonite supply concentration:Wyoming sodium bentonite deposits supply over 70 percent of global feed-grade clay binders, exposing formulators to rail logistics bottlenecks and mining permit volatility.
- FDA feed safety rule complexity:New animal drug application pathways for novel binding polymers extend commercialization timelines by 18-24 months, freezing investment in experimental chemistries.
- Raw material substitution:Soybean meal price spikes drive partial replacement with dried distillers grains, which lack natural binding properties and require 15-20 percent higher binder loading rates.
Strategic Opportunities
- India's aquaculture belt:Andhra Pradesh and Gujarat shrimp producers remain 60 percent dependent on imported binders, creating first-mover advantage for localized lignosulfonate production.
- CSRD disclosure requirements:Scope 3 emissions tracking mandates from the EU Corporate Sustainability Reporting Directive reward feed mills sourcing certified low-carbon binding agents with preferential procurement contracts.
- Precision fermentation:Microbial cellulose production is converging with enzymatic modification to create programmable binding matrices with tunable solubility profiles for species-specific feeds.
Industry Challenges
- Formulation chemist scarcity:The intersection of polymer science and animal nutrition requires hybrid expertise that existing agricultural universities rarely cultivate, constraining R&D pipeline velocity.
- Multi-regional registration burden:Simultaneous FDA, EFSA, and China's SAMR approval processes for novel bio-based binders demand parallel toxicology studies, fragmenting capital deployment across incompatible regulatory frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Pelletizing Agents Market |
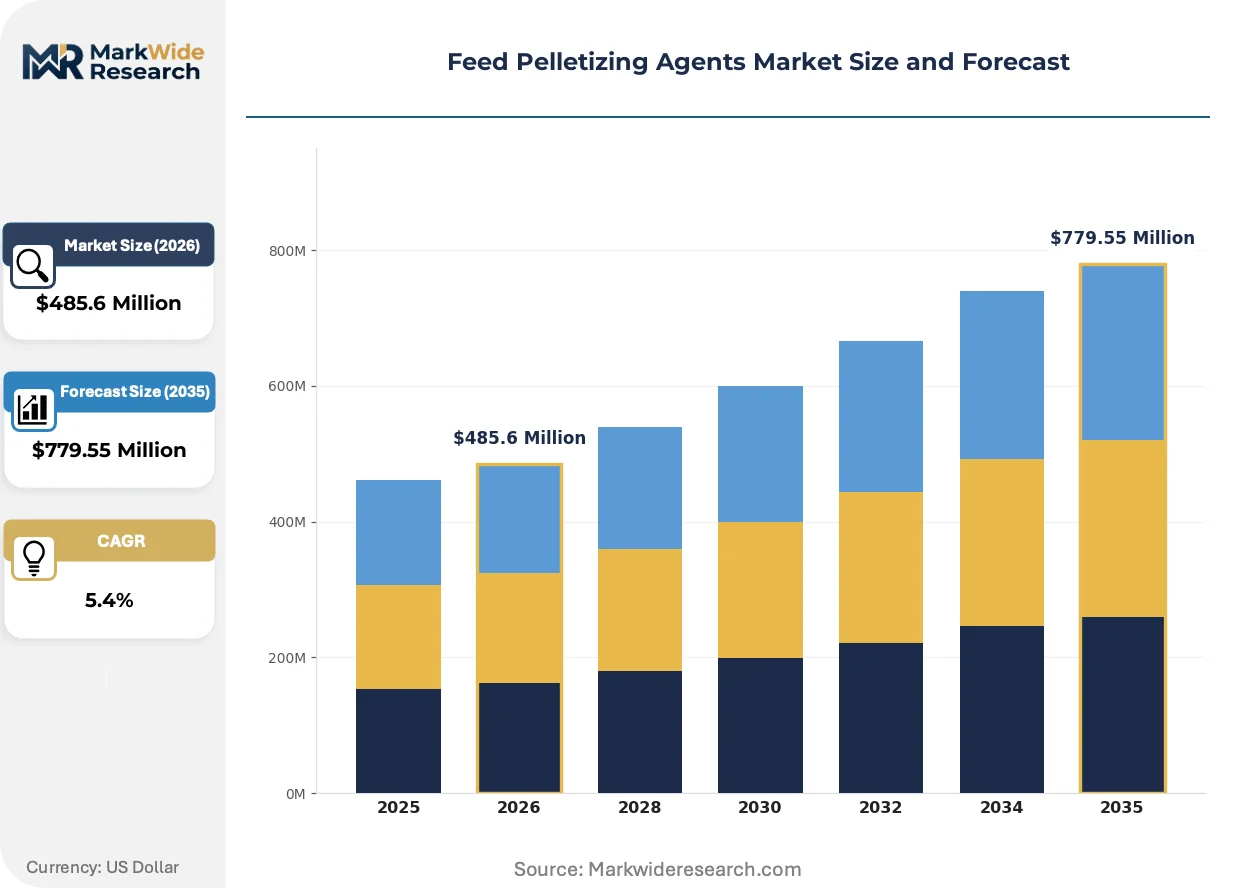
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $779.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Fillers, Nutritional Additives, Palatability Enhancers Application: Agricultural Feed, Aquaculture Feed, Poultry Feed, Livestock Feed Formulation: Dry, Liquid, Granular, Powdered End User: Feed Manufacturers, Livestock Farms, Aquaculture Producers, Pet Food Companies |
| Companies Covered | Uniscope, Bentoli, BONAVENTURE CHEMICALS, INC., Borregaard AS, Bentonite Performance Minerals LLC, Adisseo, BASF SE, Archer Daniels Midland Company, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Pelletizing Agents Market Shifts & Advancements
Active substitution of incumbent chemistries is compressing traditional supplier margins while opening proprietary formulation partnerships between biopolymer developers and integrated livestock operators.
Enzymatically modified lignosulfonates with enhanced cross-linking density are supplanting synthetic urea-formaldehyde resins in high-temperature pelleting applications above 85 degrees Celsius. Scandinavian salmon feed producers are adopting these biopolymers at pilot scale this season. The shift is compressing synthetic binder margins while locking in multi-year offtake agreements with pulp mill derivative suppliers.
China's GB 13078 feed hygiene standard revisions are tightening maximum allowable limits on heavy metal contaminants in mineral binders, forcing domestic bentonite processors to invest in acid-activation purification capacity. The industrial consequence is a 30 percent capacity rationalization among small-scale clay processors in Hebei province. Aquaculture feed manufacturers are responding by dual-sourcing from certified Wyoming deposits and domestic upgraded material.
Integrated protein companies are consolidating supplier relationships from transactional spot purchasing to multi-year binding agent contracts with embedded durability performance guarantees. The traditional distributor channel serving independent feed mills is losing volume to direct manufacturer relationships. This consolidation is most visible in Brazil's Center-West region, where JBS and Marfrig have eliminated third-party chemical distributors from their feed additive procurement.
Feed Pelletizing Agents Market Segmentation
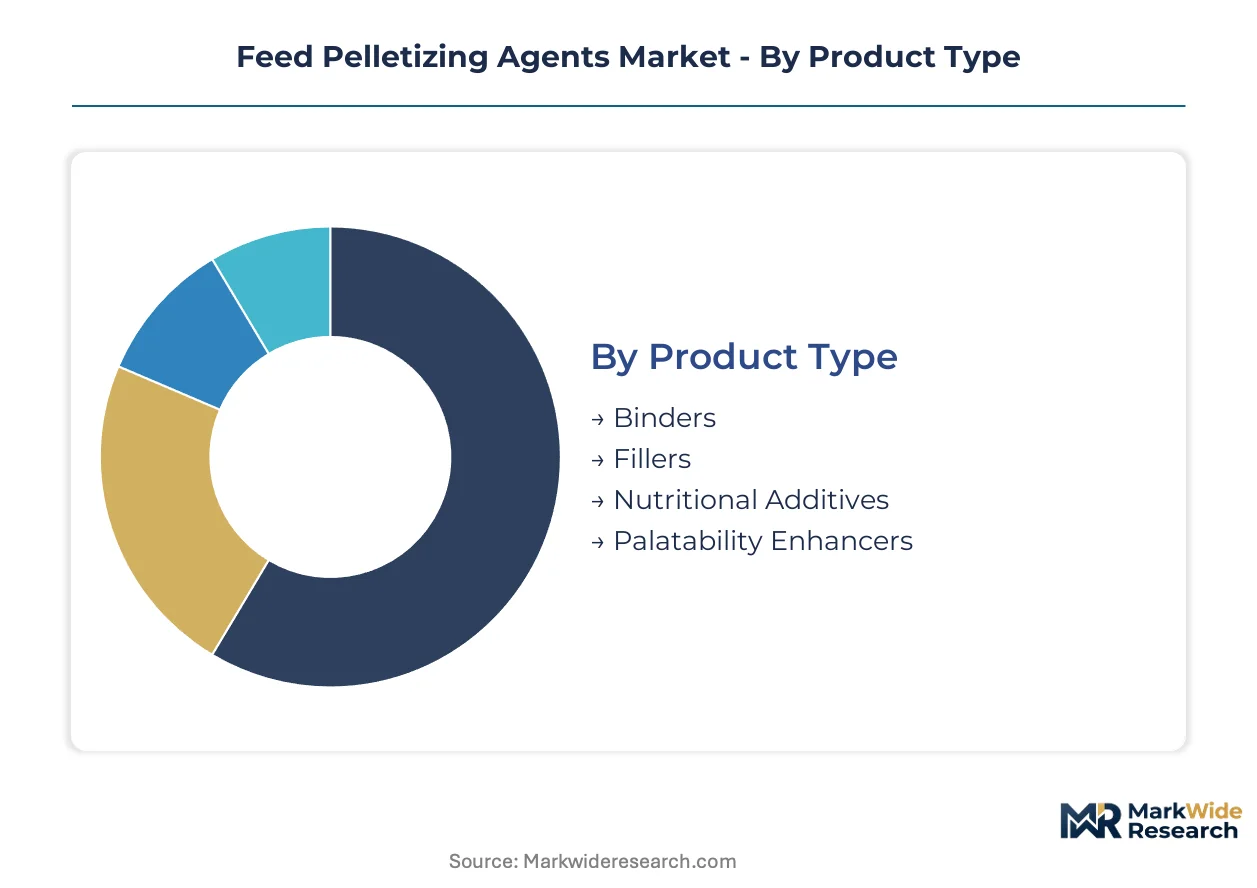
Feed pelletizing agents segment across functional chemistry, target species, physical state, and customer procurement patterns. Channel dynamics vary sharply: commodity binders flow through distributor networks to independent mills, while specialized formulations move through direct technical sales to integrated protein operators.
Product Type:
Distributor networks concentrate commodity binders and fillers toward independent feed mills, whereas direct manufacturer relationships channel nutritional additives and palatability enhancers toward integrated livestock operations seeking formulation partnerships.
- Binders:Lignosulfonates, bentonite clays, and modified starches mechanically stabilize pellets during extrusion and transport, achieving durability indices above 90 percent. Demand concentrates in Brazilian integrated poultry operations where JBS and BRF standardize pelletized formulations to optimize feed conversion ratios and reduce handling losses.
- Fillers:Inert mineral and fiber-based extenders adjust pellet density and reduce formulation costs without compromising structural integrity. Procurement is shifting toward certified low-carbon sources as EU Corporate Sustainability Reporting Directive mandates Scope 3 emissions tracking across integrated protein supply chains.
- Nutritional Additives:Vitamin and mineral premixes incorporated during pelleting to protect heat-sensitive nutrients from thermal degradation.
- Palatability Enhancers:Flavor and aroma compounds masking off-notes from high-inclusion alternative proteins like dried distillers grains.
Binders dominate installed base. Nutritional additives are where expansion concentrates.
Application:
Volume distribution tracks species-specific farming intensity: livestock and poultry generate deepest demand pools, while aquaculture commands premium pricing for water-stable formulations.
- Agricultural Feed:Broad-category formulations serving mixed farming operations with multi-species nutritional requirements. Demand aggregates in India's northern plains where smallholder dairy cooperatives rely on distributed feed mill networks.
- Aquaculture Feed:High-moisture extruded pellets requiring specialized binders with tunable solubility profiles for shrimp and salmon farming. Southeast Asian operations in Vietnam and Indonesia drive specification intensity as farming intensifies and durability standards tighten.
- Poultry Feed:High-throughput pelleting for broiler and layer operations with standardized nutrient density requirements.
- Livestock Feed:Ruminant and monogastric formulations optimized for fiber content and rumen bypass protection.
Livestock feed anchors volume scale. Aquaculture feed is climbing the fastest.
Formulation:
Physical state determines manufacturing integration: dry forms suit high-volume mill operations, while liquid and granular variants serve specialized premix and on-farm applications.
- Dry:Powdered and granulated binders integrated into bulk mixing systems for high-throughput feed mills. Scale concentration in Brazil's Center-West region where JBS and Marfrig have eliminated third-party distributors from additive procurement.
- Liquid:Suspensions and solutions applied via spray systems for uniform coating and moisture-activated binding. Aquaculture producers in Norway and Chile adopt liquid lignosulfonate complexes for precision dosing in high-value salmon feeds.
- Granular:Free-flowing particles with controlled particle size distribution for automated handling systems.
- Powdered:Fine-milled additives for homogeneous dispersion in mash feeds prior to pelleting.
Dry formulations dominate manufacturing scale. Liquid variants are gaining share fastest.
End User:
Customer type stratifies by procurement sophistication: integrated operators demand performance guarantees and technical service, while independent farms prioritize cost minimization.
- Feed Manufacturers:Compound feed mills purchasing binders and additives as formulation inputs. Margin pressure from raw material volatility drives consolidation toward multi-year supply contracts with embedded durability specifications.
- Livestock Farms:Large-scale operations with captive feed milling capacity, particularly Brazilian integrated protein companies standardizing pelletized formulations across poultry and pork verticals.
- Aquaculture Producers:Shrimp and salmon farming operations requiring water-stable pellets with species-specific solubility profiles.
- Pet Food Companies:Premium segment buyers prioritizing pellet aesthetics and palatability for differentiated consumer products.
Feed manufacturers dominate procurement volume. Aquaculture producers are where specification intensity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in feed pelletizing agents tilt toward net-import dependence in emerging aquaculture zones while established livestock economies maintain additive self-sufficiency through integrated chemical processing. Export capacity concentrates in lignin-rich Nordic regions and Wyoming bentonite districts.
Brazil
JBS, BRF, and Minerva Foods are consolidating feed milling across Center-West poultry and pork operations, standardizing pelletized formulations to optimize feed conversion ratios. ANVISA registration pathways for novel binding polymers remain less burdensome than FDA equivalents, accelerating qualification timelines. São Paulo state anchors formulation chemistry R&D clusters serving integrated protein supply chains.
United States
Wyoming sodium bentonite deposits supply over 70 percent of global feed-grade clay binders, exposing formulators to rail logistics bottlenecks and mining permit volatility. EPA guidelines on mining-derived bentonite processing impose additional testing burdens for multi-regional market access. The Powder River Basin concentration creates supply vulnerability during extreme weather disruptions.
China
GB 13078 feed hygiene standard revisions are tightening maximum allowable limits on heavy metal contaminants in mineral binders, forcing domestic bentonite processors to invest in acid-activation purification capacity. Hebei province is experiencing 30 percent capacity rationalization among small-scale clay processors. Yangtze River Delta aquaculture feed manufacturers are dual-sourcing from certified Wyoming deposits and domestic upgraded material.
Norway
Scandinavian salmon feed producers are adopting enzymatically modified lignosulfonates at pilot scale, supplanting synthetic urea-formaldehyde resins in high-temperature pelleting above 85 degrees Celsius. REACH compliance deadlines are accelerating qualification of biodegradable binding agents in ruminant and monogastric formulations. Bergen and Trondheim host pulp mill derivative suppliers locking in multi-year offtake agreements.
India
Andhra Pradesh and Gujarat shrimp producers remain 60 percent dependent on imported binders, creating first-mover advantage for localized lignosulfonate production. FSSAI feed additive regulations are converging with international residue limit standards, streamlining import substitution pathways. Visakhapatnam port infrastructure is expanding cold chain capacity for water-stable aquaculture feed distribution.
Feed Pelletizing Agents Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized biopolymer developers rather than regional commodity traders. The vendor base stratifies across three tiers: integrated nutrition platforms with captive distribution, lignin derivative specialists leveraging pulp mill integration, and synthetic binder chemists serving high-temperature industrial applications. Strategic moves center on multi-year supply contracts with embedded durability guarantees and backward integration into raw material security.
Within the biopolymer specialization tier, Borregaard AS exemplifies lignosulfonate expertise derived from Scandinavian pulp processing integration. BASF SE anchors synthetic binder chemistry optimized for industrial-scale thermal processing. Cargill occupies a position bridging agricultural commodity flows with formulated additive distribution. These three represent distinct competitive archetypes: renewable feedstock dependence, petrochemical process mastery, and supply chain verticality.
| Leading Market Players |
|---|
| Uniscope |
| Bentoli |
| BONAVENTURE CHEMICALS, INC. |
| Borregaard AS |
| Bentonite Performance Minerals LLC |
| Adisseo |
| BASF SE |
| Archer Daniels Midland Company |
| Cargill |
| Others |
Supply & Pricing Matrix
Synthetic urea-formaldehyde displacement by enzymatically modified lignosulfonates is redrawing procurement geography toward Nordic pulp mill corridors while compressing margins on petroleum-derived alternatives. Brazilian integrated protein operators exploit this shift through multi-year offtake contracts that lock in price stability against volatile clay binder markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that embed durability performance guarantees. Pricing stratifies across pharmaceutical-grade, feed-grade, and industrial-grade certification tiers, with EU Green Deal compliance premiums widening spreads. Cost compression in synthetic binder categories is intensifying because REACH deadlines accelerate bio-based substitution. Independent feed mills exhibit highest price sensitivity due to spot-market exposure, while integrated aquaculture producers accept premium positioning for water-stable formulations.
Supply Chain Analysis
Inventory cycles stretch 60-90 days for Wyoming bentonite rail shipments, creating working capital intensity that favors large compound feed mills with storage infrastructure. Supply concentrates in the United States, Norway, and Brazil, with lignosulfonate production drawing from Scandinavian pulp processing and bentonite extraction anchored in Wyoming deposits. Raw material flows hinge on sodium bentonite ore, spruce/pine lignin feedstock, and modified starch derivatives. Single-source vulnerability concentrates in Powder River Basin mining permits. Distribution runs through direct manufacturer relationships for integrated protein operators and distributor networks for independent mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Brazilian poultry and pork vertical integration, with JBS and BRF eliminating third-party chemical distributors and forcing binders suppliers into direct technical partnerships.
For Market Incumbents: Secure captive lignin supply through pulp mill offtake agreements before Nordic capacity locks into competitor contracts. Defend against synthetic binder margin erosion by accelerating REACH-compliant bio-based qualification timelines. Prioritize backward integration into Wyoming bentonite processing to neutralize rail logistics bottlenecks. For New Entrants and Emerging Players: Lead with localized lignosulfonate production targeting India's Andhra Pradesh shrimp belt, where 60 percent import dependence creates procurement vulnerability. Exploit FSSAI regulatory convergence to position domestic manufacturing as import substitution. Pursue technical sales direct to aquaculture feed manufacturers rather than distributor channel buildout. For Investors and Strategic Acquirers: The market sits at a substitution-phase inflection that favors biopolymer developers with pulp mill integration over synthetic chemistry incumbents. Long-term viability over the next decade rests on EU Green Deal compliance positioning and Scope 3 emissions certification. Monitor CSRD disclosure adoption rates among European protein companies as the signal for contract reallocation toward low-carbon binder suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignin Supply | Pulp mill offtake agreements with Borregaard AS lock in raw material security against Nordic capacity constraints. |
| REACH Compliance Certification | Biodegradable binder qualification opens EU compound feed procurement previously closed to synthetic alternatives. |
| Direct Technical Sales Buildout | Eliminating distributor margins allows price competitiveness against commodity bentonite suppliers in Brazil. |
| Acid-Activation Purification Investment | Domestic Chinese bentonite upgrading captures market share from Wyoming imports under tightening GB 13078 standards. |
| Multi-Year Durability Guarantee Contracts | Performance-based pricing aligns supplier incentives with JBS and BRF feed conversion optimization targets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA feed additive registrations, EU EFSA safety assessments, Brazilian ANVISA filings, and trade flow databases. Primary inputs drew from feed formulation chemists at integrated protein companies, procurement directors at compound feed mills, technical sales leads at biopolymer suppliers, and regulatory affairs specialists navigating REACH and GB 13078 pathways. Secondary validation incorporated customs records, pulp industry capacity reports, and mining permit disclosures. Bottom-up demand modeling triangulated against top-down chemical consumption estimates.
Segmentation dimensions modeled span binder chemistry type, target species application, physical formulation state, and customer procurement archetype across the projection horizon. CAGRs derived from elasticity-adjusted volume projections tied to livestock and aquaculture production forecasts. Industry-specific inputs included shrimp farming intensification rates in Southeast Asia, Brazilian poultry vertical integration timelines, and EU sustainability mandate implementation phasing.
The analysis sits within stated boundaries; outcomes outside current regulatory trajectories or raw material substitution velocities would require recalibration. Forecasts reflect documented assumptions regarding REACH deadline adherence, Wyoming mining permit stability, and lignosulfonate production scale-up. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market