
 Asia Pacific Fungicide Market | 2026-2036
Asia Pacific Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fungicide Market Insights
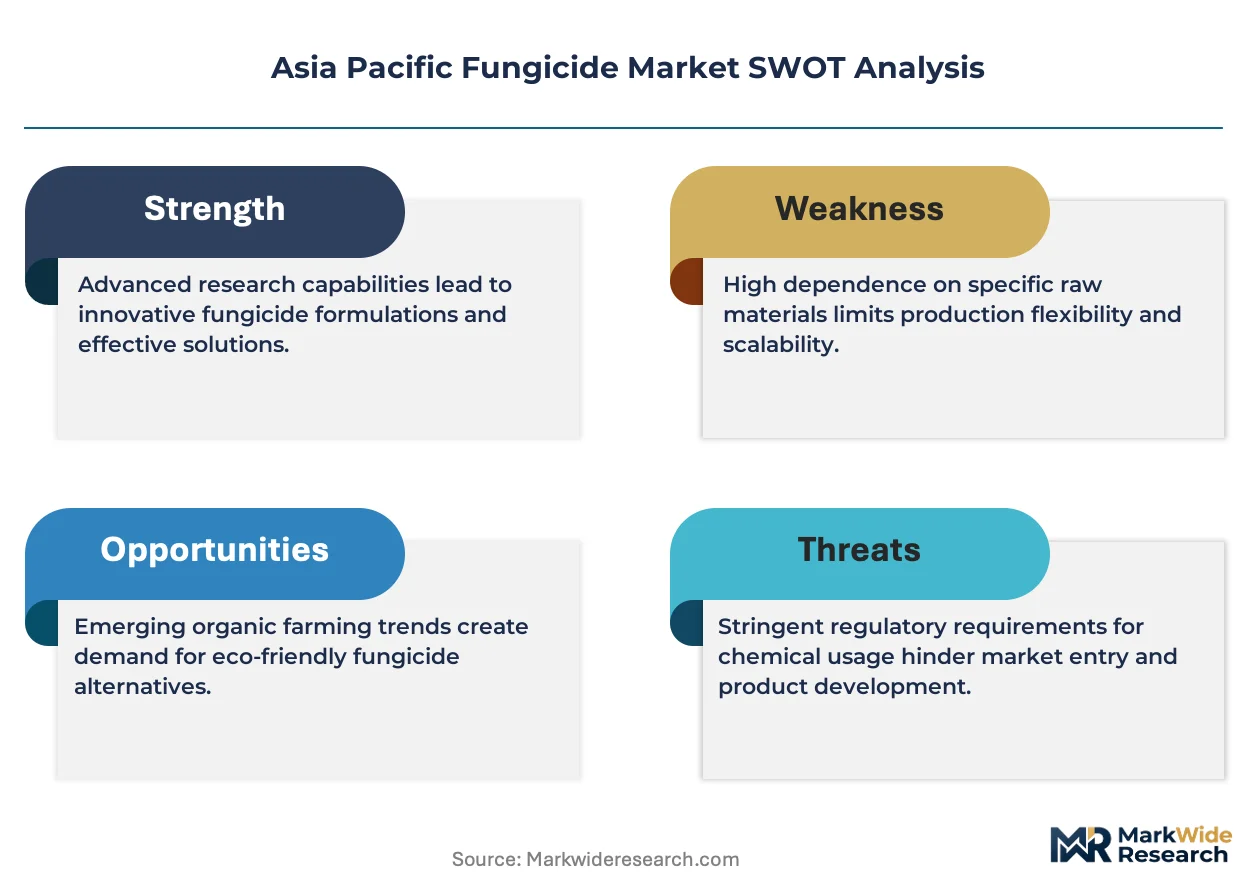
ISO 17025 accreditation for analytical laboratories is collapsing the supplier base eligible to certify active ingredient purity for import into major Asia Pacific jurisdictions. BASF SE leverages its Ludwigshafen technical center to sustain dual-registration dossiers across Australia and Japan. Bayer AG anchors its position through captive production of prothioconazole intermediates in China. Sumitomo Chemical Co., Ltd differentiates via biological fermentation platforms that navigate Japan's PMDA data requirements.
Asia Pacific fungicides comprise synthetic or biological agents formulated to inhibit fungal spore germination, mycelial growth, or sporulation through modes including ergosterol biosynthesis disruption or mitochondrial respiration inhibition. Their primary commercial purpose is protecting yield and shelf stability in high-humidity cropping environments where fungal pressure intensifies with monsoon patterns. Strobilurins occupy the premium tier among product types due to broad-spectrum activity and translaminar movement, while biological formulations represent the fastest-expanding category as residue-conscious fruit exporters in Vietnam and Thailand seek MRL-compliant alternatives. Liquid formulations dominate volume because of compatibility with aerial application infrastructure across Indonesian palm oil estates and Australian broadacre farms.
China's MEE enforces environmental impact assessments for glyphosate and fungicide manufacturing facilities along the Yangtze River basin. India's CEA regulates power-intensive fermentation processes for biological fungicide production under national energy conservation codes. Australia's TGA-equivalent APVMA maintains parallel data requirements with Codex Alimentarius that shape export-oriented formulation standards. Stakeholders must monitor regulatory divergence between ASEAN harmonization initiatives and country-specific re-registration timelines to anticipate formulation obsolescence risks.
Market Dynamics
China's MEE is tightening environmental impact assessments for fungicide manufacturing facilities along the Yangtze River basin, forcing formulation restructuring and supplier consolidation across the region's agrochemical value chain.
Growth Catalysts
- Monsoon-intensified fungal pressure:Rice cultivation across Vietnam, Thailand, and Indonesia drives expanding preventive fungicide applications as humidity patterns shift.
- ISO 17025 accreditation requirements:Collapsing analytical laboratory eligibility for certifying active ingredient purity concentrates import demand on accredited suppliers.
- Biological fermentation platforms:Japan's PMDA data requirements favor domestically developed microbial formulations that navigate residue testing protocols.
Market Restraints
- Active ingredient supply concentration:Captive production of prothioconazole intermediates in China creates dependency on single-source chemistry for strobilurin formulations.
- Power cost volatility:India's CEA energy conservation codes raise operating expenses for fermentation-based biological fungicide manufacturing.
- Dual-registration dossier burden:Divergent data requirements between Australia's APVMA and Japan's PMDA extend product commercialization timelines.
Strategic Opportunities
- MRL-compliant biological alternatives:Vietnam and Thailand fruit exporters seek residue-conscious formulations that satisfy EU import standards.
- Aerial application infrastructure:Indonesian palm oil estates and Australian broadacre farms favor liquid formulations compatible with drone and fixed-wing spraying systems.
- ASEAN harmonization gaps:Country-specific re-registration timelines create windows for first-movers to secure provisional approvals ahead of regional standardization.
Industry Challenges
- Analytical chemist scarcity:ISO 17025-accredited laboratories face talent shortages for metabolite identification and residue method validation.
- Legacy formulation obsolescence:China's tightening GB standards for pesticide residue limits force rapid reformulation of established products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fungicide Market |
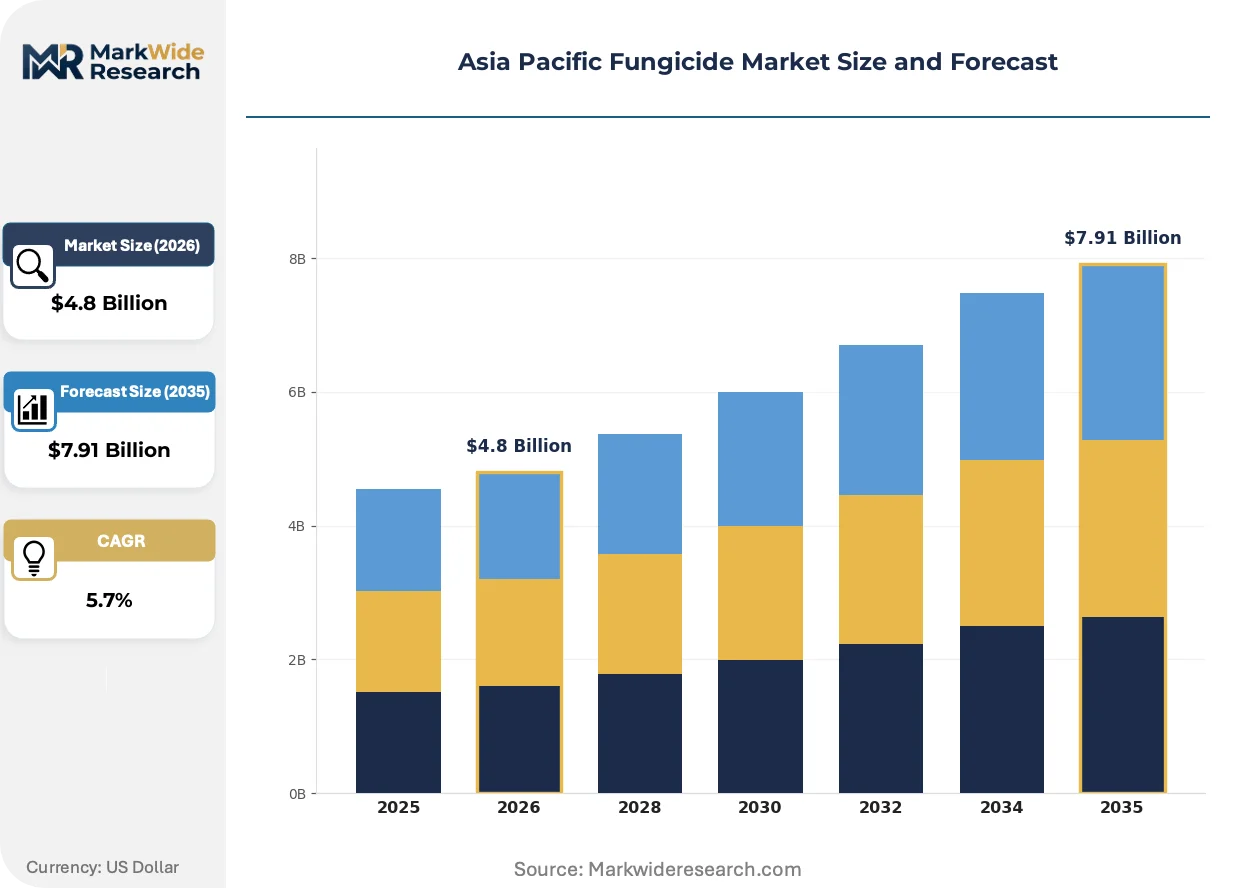
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Strobilurins, Dicarboximides, Biological Application: Cereals, Fruits, Vegetables, Oilseeds Formulation: Liquid, Granular, Powder, Pellets Distribution Channel: Direct Sales, Retail, E-commerce, Others |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, UPL Limited, Sumitomo Chemical Co., Ltd, ADAMA Agricultural Solutions Ltd, Nufarm Limited, FMC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fungicide Market Trends and Innovations
Formulation chemistry is splitting between high-performance synthetic strobilurins and rapidly advancing biological alternatives, with regulatory pressure and export market access requirements determining adoption velocity across cropping systems.
Biological fungicide platforms leveraging fermentation-derived metabolites are bifurcating the product tier structure. Vietnamese dragonfruit and Thai durian exporters facing EU MRL scrutiny are adopting microbial formulations at twice the pace of domestic-oriented growers. This technology compression is creating parallel supply chains—one serving residue-sensitive export markets, another optimized for cost in local consumption crops.
Japan's PMDA has tightened data requirements for novel active ingredients, extending evaluation periods for synthetic chemistry while creating expedited pathways for domestically sourced biologicals. The industrial consequence is a pivot among Japanese formulators toward microbial screening programs. Australian broadacre operators are most affected, as APVMA parallel requirements with Codex Alimentarius delay access to new synthetic modes of action.
Residue testing certification is becoming the primary purchase criterion for procurement officers at Vietnamese and Thai export cooperatives. Traditional distributor networks emphasizing price and volume are losing share to specialized agronomic service providers bundling MRL compliance guarantees with product supply. This channel restructuring is most visible in Mekong Delta rice and Central Highlands coffee value chains.
Asia Pacific Fungicide Market Segmentation
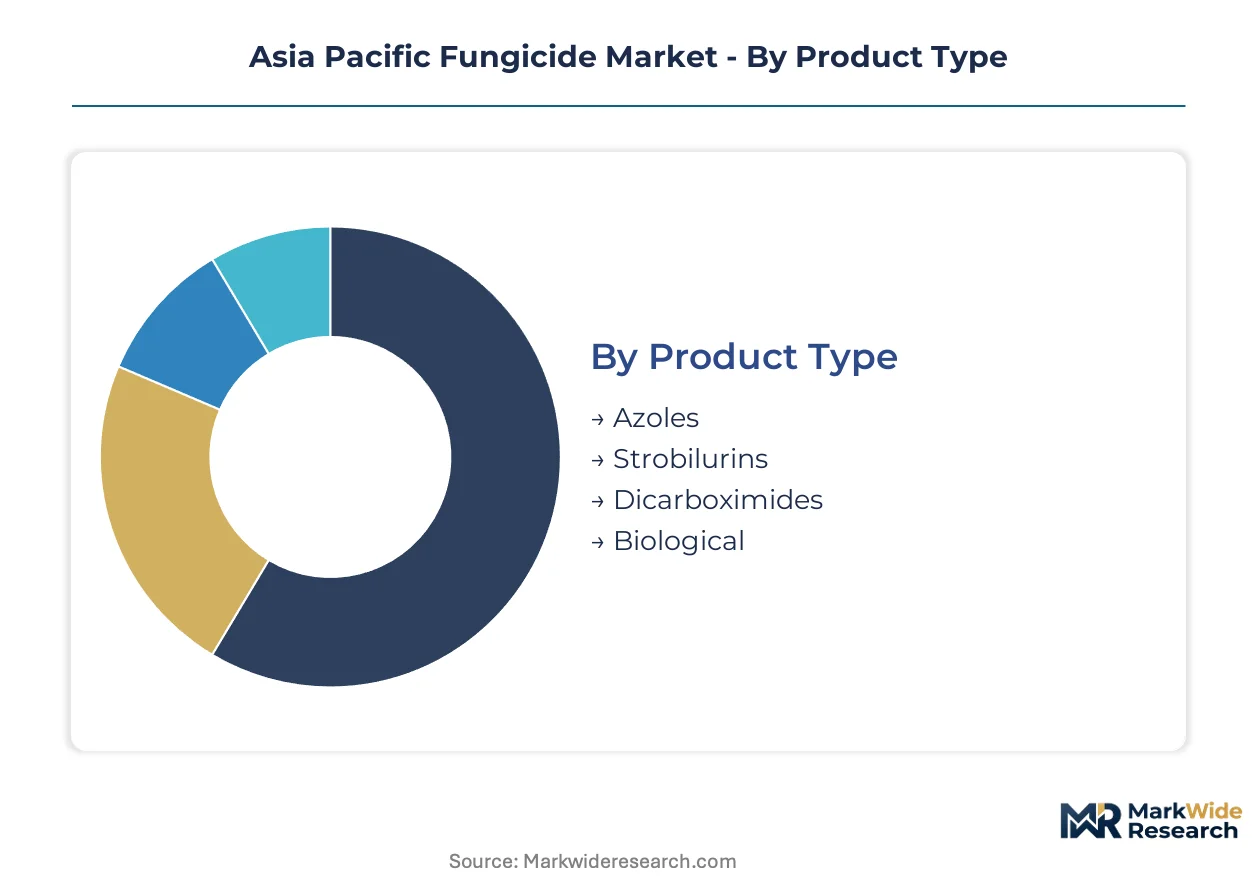
Fungicide segmentation across Asia Pacific reflects divergent pressure points between domestic food security crops and export-oriented horticulture. Each dimension carries distinct regulatory, application, and supply chain implications for formulation strategy.
Product Type:
Domestic rice and wheat belts favor established chemistries with proven resistance management, while export fruit corridors drive biological adoption under EU MRL scrutiny.
- Azoles:Ergosterol biosynthesis inhibitors with systemic movement protect rice blast and wheat rust across Vietnam's Mekong Delta and India's Indo-Gangetic Plain. China's tightening GB residue limits force reformulation of legacy triazole products ahead of re-registration deadlines.
- Strobilurins:Broad-spectrum translaminar compounds command premium positioning in Indonesian palm oil and Australian broadacre cereals. Captive production of prothioconazole intermediates concentrates supply leverage among integrated manufacturers.
- Dicarboximides:Contact-acting protectants retain niche utility in Japanese greenhouse vegetable systems where resistance rotation protocols are strictly enforced.
- Biological:Fermentation-derived microbial formulations from Japanese and Vietnamese platforms navigate PMDA and EU residue protocols for dragonfruit and durian export chains.
Strobilurins hold the largest share; momentum sits with biological platforms.
Application:
Cost tier stratification separates commodity grain protection from high-value horticulture where residue certification commands price premiums.
- Cereals:Rice across Southeast Asia and wheat in Maharashtra and Madhya Pradesh drive volume demand for preventive strobilurin and azole applications timed to monsoon fungal pressure peaks.
- Fruits:Vietnamese dragonfruit and Thai durian exporters adopt biological formulations at accelerated pace to satisfy EU MRL compliance requirements for supermarket retail access.
- Vegetables:Japanese greenhouse tomato and cucumber operations prioritize resistance rotation with dicarboximides and microbial alternatives under PMDA evaluation pathways.
- Oilseeds:Australian canola and Indonesian palm oil estates favor liquid strobilurin formulations compatible with aerial drone and fixed-wing spraying infrastructure.
Cereals dominate volume; fruits are climbing the fastest on export compliance premiums.
Formulation:
Application infrastructure and labor availability determine format preference across estate scale and smallholder fragmentation.
- Liquid:Emulsifiable concentrates and suspension concentrates suit mechanized application across Indonesian palm oil plantations and Australian broadacre farms with drone compatibility.
- Granular:Slow-release formulations serve Japanese paddy rice systems where single-application convenience offsets higher unit cost in labor-constrained planting windows.
- Powder:Wettable powders retain cost-sensitive adoption among Indian smallholder wheat and soybean growers in Maharashtra distribution networks.
- Pellets:Controlled-release matrices target high-value greenhouse vegetables in Japan with precision placement and reduced handler exposure.
Liquid formulations hold the largest share; granular formats gain traction in labor-scarce rice systems.
Distribution Channel:
Customer type fragmentation between estate procurement offices and smallholder cooperative networks reshapes channel economics.
- Direct Sales:Bulk supply contracts dominate Indonesian palm oil estates and Australian broadacre cooperatives seeking volume pricing and technical service bundling.
- Retail:Traditional agro-dealer networks serve Indian smallholder wheat and soybean belts across Maharashtra and Madhya Pradesh with credit-linked seasonal purchasing.
- E-commerce:Digital platforms penetrate Vietnamese and Thai export-oriented fruit cooperatives seeking MRL-compliant product verification and documentation trails.
- Others:Government subsidy programs and development project procurement operate in parallel across Philippine rice extension systems.
Direct sales hold the largest share; e-commerce channels show steepest expansion trajectory on compliance documentation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes fragment between estate procurement offices in Indonesian palm oil and Australian broadacre, and smallholder cooperatives across Vietnamese fruit export chains. This bifurcation drives divergent channel economics and formulation requirements. Regulatory fragmentation between Japan's PMDA, China's MEE, and Australia's APVMA compounds supply chain complexity for multinational formulators.
China
Rice blast and wheat rust pressure across the Yangtze River Delta and North China Plain sustains azole and strobilurin consumption. The MEE enforces environmental impact assessments for manufacturing facilities along the Yangtze basin, forcing reformulation of legacy products. Shandong Province hosts concentrated technical-grade production where GB standard tightening is accelerating supplier consolidation.
India
Wheat and soybean cultivation across Maharashtra and Madhya Pradesh drives preventive fungicide applications timed to monsoon fungal peaks. The CEA regulates power-intensive fermentation processes under national energy conservation codes, raising biological manufacturing costs. Pune-based formulation facilities serve the Deccan plateau with credit-linked distribution through Maharashtra's agro-dealer networks.
Japan
Greenhouse tomato and cucumber operations in Chubu and Kanto regions prioritize resistance rotation protocols. The PMDA maintains expedited evaluation pathways for domestically sourced biologicals while extending synthetic chemistry review periods. Osaka-based microbial screening programs supply fermentation-derived formulations to precision agriculture clusters in Aichi Prefecture.
Vietnam
Dragonfruit and Mekong Delta rice exporters adopt biological formulations at accelerated pace to satisfy EU MRL compliance. Digital platforms penetrate export cooperatives seeking residue certification documentation. Ho Chi Minh City distribution hubs connect Central Highlands coffee and fruit estates with MRL-compliant supply chains.
Australia
Broadacre canola and cereal operations across New South Wales and Victoria favor liquid strobilurin formulations compatible with aerial drone infrastructure. The APVMA maintains parallel data requirements with Codex Alimentarius that delay access to novel synthetic modes. Adelaide-based cooperatives negotiate bulk supply contracts bundling volume pricing with technical service.
Asia Pacific Fungicide Market Competitive Landscape
Player mix skews toward integrated multinationals with captive technical-grade supply and specialized biological fermentation platforms. Market structure concentrates around three to five global formulators controlling strobilurin and azole active ingredient streams, with mid-tier regional specialists competing on distribution reach. Strategic archetypes split between integrated chemistry majors, biological platform developers, and generic formulation houses. Competitive moves center on backward integration into intermediate production and strategic partnerships with ISO 17025-accredited analytical laboratories.
Within the integrated chemistry tier, BASF SE and Bayer AG exemplify multinationals leveraging technical center infrastructure to sustain multi-jurisdiction registration dossiers. Sumitomo Chemical Co., Ltd occupies a distinct position among biological platform developers, representing the fermentation-derived alternative pathway that navigates Japan's PMDA data requirements. These three companies illustrate the strategic bifurcation between synthetic chemistry scale and biological specialization reshaping competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| UPL Limited |
| Sumitomo Chemical Co., Ltd |
| ADAMA Agricultural Solutions Ltd |
| Nufarm Limited |
| FMC Corporation |
| Others |
Pricing and Supply Chain Analysis
ISO 17025 accreditation requirements gate both supplier qualification and price differentiation simultaneously, collapsing the analytical laboratory base eligible to certify active ingredient purity while concentrating import demand on accredited suppliers commanding certification premiums across Vietnam and Thailand export corridors.
Pricing Analysis
Cost-plus contracts with indexation to technical-grade active ingredient spot markets dominate procurement between Indonesian palm oil estates and integrated manufacturers. Pricing stratifies across MRL-certified biologicals, strobilurin formulations with translaminar performance claims, and generic azole replacements in Indian smallholder channels. Price compression runs through legacy triazole products as China's GB standard tightening forces reformulation investments. Indian wheat and soybean growers in Maharashtra exhibit highest price sensitivity, while Vietnamese dragonfruit export cooperatives absorb premiums for residue documentation.
Supply Chain Analysis
Inventory lead times for prothioconazole intermediates stretch across captive production facilities in Shandong Province and formulation plants in Pune, creating working capital intensity for strobilurin manufacturers. Technical-grade supply concentrates in China and India, with fermentation-derived biological inputs sourcing from Osaka-based microbial platforms. Single-source dependency on Yangtze River basin chemical manufacturing exposes the chain to MEE environmental enforcement actions. Distribution runs through direct bulk contracts for Australian broadacre cooperatives and credit-linked agro-dealer networks serving Maharashtra smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological fermentation platforms are disrupting synthetic chemistry dominance as Japan's PMDA expedites domestic microbial pathways while extending synthetic review periods, creating a regulatory arbitrage window for residue-compliant alternatives.
For Market Incumbents: Consolidate backward integration into prothioconazole intermediate production to defend against supply concentration risks from Shandong Province manufacturing. Lock ISO 17025-accredited laboratory partnerships to secure certification capacity as analytical chemist scarcity intensifies qualification bottlenecks for import dossiers. For New Entrants and Emerging Players: Anchor in Vietnamese dragonfruit and Thai durian export cooperatives where MRL compliance documentation commands price premiums and incumbent biological portfolios remain thin. Deploy digital platform distribution with bundled residue testing certification to bypass traditional agro-dealer networks. For Investors and Strategic Acquirers: Japan's PMDA evaluation pathway divergence reshapes the acquisition landscape toward Osaka-based microbial screening platforms with expedited biological registration timelines. Target fermentation-derived formulation specialists with existing PMDA dossiers rather than synthetic chemistry assets facing extended review periods. Monitor ASEAN harmonization initiative progress as the signal for regional standardization windows closing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | Captive prothioconazole production in Shandong Province insulates against supply concentration leverage. |
| ISO 17025 Laboratory Partnership | Accredited analytical capacity secures import qualification gates across APVMA and PMDA jurisdictions. |
| Biological Platform Acquisition | Osaka-based microbial screening assets navigate PMDA expedited pathways versus synthetic chemistry delays. |
| Digital Distribution Buildout | E-commerce penetration captures Vietnamese export cooperative procurement shifting from traditional dealers. |
| ASEAN Harmonization Positioning | First-mover provisional approvals ahead of regional standardization secure transitional market share. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, APVMA registration databases, MEE environmental filings, and ASEAN agricultural ministry submissions. Conversations with formulation plant managers in Shandong and Pune, procurement leads at Indonesian palm oil estates, regulatory affairs directors navigating PMDA pathways, and Vietnamese export cooperative agronomists informed demand segmentation. Bottom-up volume estimates from crop hectarage and application rates triangulate against top-down manufacturer shipment data.
Segmentation dimensions modeled span product type, application crop, formulation format, and distribution channel across the projection horizon. CAGRs derive from regression against historical fungicide intensity trends, crop area expansion, and regulatory-driven substitution elasticities. Industry-specific forecast inputs include monsoon pattern variability indices and EU MRL revision schedules affecting Vietnamese and Thai export compliance costs.
Material uncertainties — regulatory divergence between ASEAN harmonization timelines and country-specific re-registration deadlines, MEE enforcement intensity along the Yangtze River basin, and biological formulation efficacy validation — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
Global Agricultural Fumigants Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
Neonicotinoid Insecticides Market