
 North America Fungicide Market | 2026-2036
North America Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fungicide Market Insights
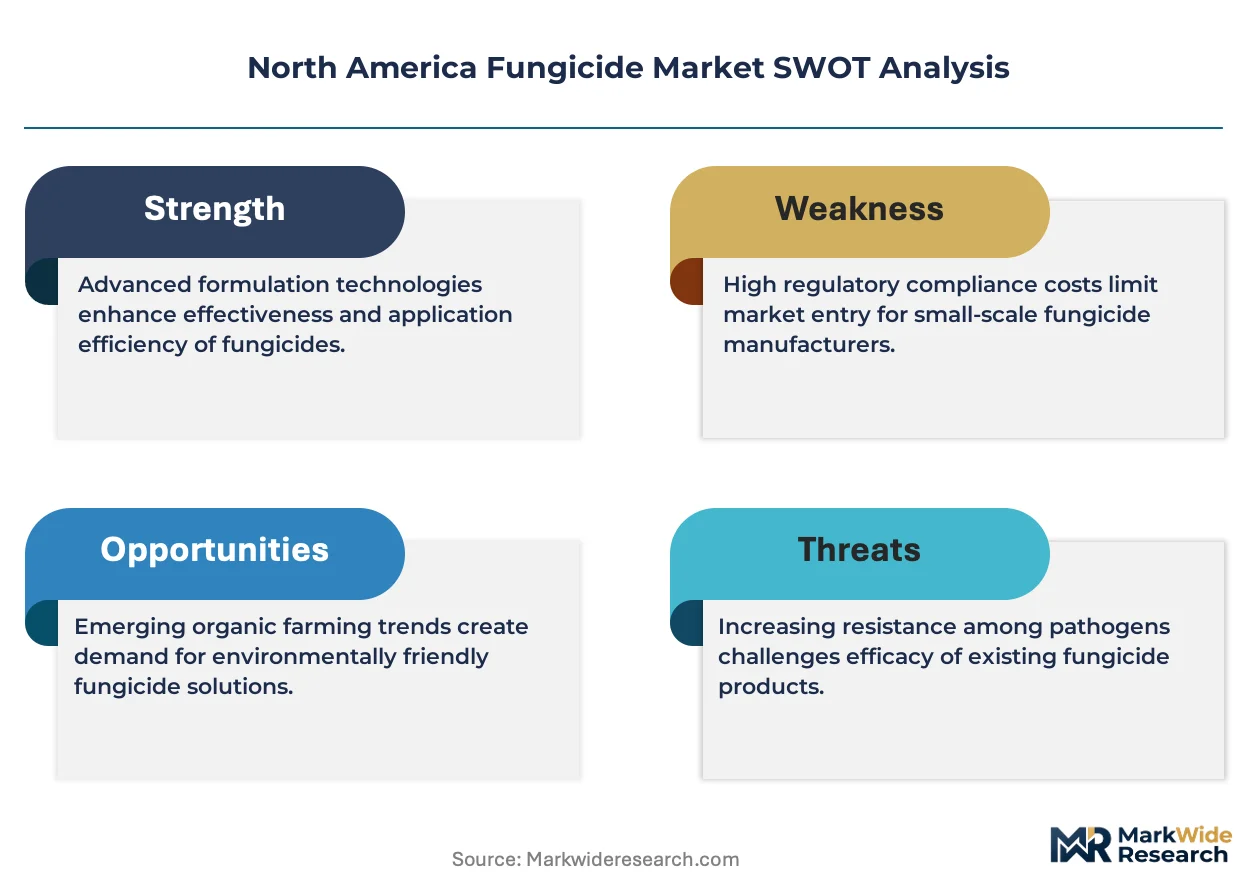
EPA Section 3 registration under FIFRA is reorganizing competitive access across the North America fungicide landscape. BASF SE leverages its integrated pyraclostrobin supply chain to sustain cost advantages in strobilurin production. Bayer AG anchors its position through in-house triazole chemistry and broad corn-soybean distribution networks. Corteva Agriscience differentiates via biologicals R&D partnerships and channel control through agricultural cooperatives.
North America fungicides comprise synthetic and biological formulations designed to inhibit fungal pathogen development in crop and non-crop systems, with active ingredients typically applied at 0.1 to 2.0 pounds per acre depending on pathogen pressure and crop stage. Triazoles dominate the synthetic segment due to established efficacy against ascomycete and basidiomycete diseases in row crops. Biologicals represent the fastest-expanding product category as farmers seek residue-compliant solutions for export-oriented fruit and vegetable production. Among end users, commercial growers command premium pricing power through volume commitments and direct technical service relationships.
EPA, PMRA in Canada, and state-level Departments of Agriculture collectively govern active ingredient approval, maximum residue limits, and buffer zone requirements that determine which chemistries gain market access. FIFRA re-registration reviews and Endangered Species Act consultations are extending product development cycles and raising compliance costs for synthetic fungicide manufacturers. Stakeholders must monitor biologicals pipeline progress and state-level 24(c) special local need registrations as these pathways increasingly determine competitive positioning.
Market Dynamics
EPA FIFRA re-registration timelines are compressing product life cycles for synthetic chemistries while biological registration pathways accelerate, forcing manufacturers to rebalance R&D portfolios toward residue-compliant alternatives.
Growth Catalysts
- Specialty crop expansion:California and Florida fruit and vegetable growers are intensifying fungicide applications to meet export market residue standards for European and Asian buyers.
- Biologicals pipeline acceleration:EPA's biopesticide registration pathway under FIFRA is shortening time-to-market for microbial and plant-extract formulations versus conventional synthetics.
- Climate-driven disease pressure:Elevated humidity patterns across the U.S. Corn Belt are extending fungal pathogen seasons, expanding treatment windows for preventive applications.
Market Restraints
- Active ingredient concentration:Three multinational suppliers control over 70% of global strobilurin technical production, creating input cost volatility for formulators.
- Regulatory friction:EPA Endangered Species Act consultations for new active ingredients now add 18-36 months to registration timelines.
- Resistance management mandates:FRAC code rotation requirements limit single-chemistry dominance and compress effective product life spans.
Strategic Opportunities
- Underpenetrated prairie provinces:Canadian canola and pulse growers in Saskatchewan and Alberta show adoption gaps for biological seed treatments versus U.S. benchmarks.
- 24(c) special local need registrations:State-level emergency exemptions for minor crops create first-mover advantages for nimble registrants.
- Precision application convergence:Integration of drone spraying platforms with variable-rate prescription maps is opening subscription-based service models.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in nano-emulsion and micro-encapsulation technologies is concentrated among retiring cohorts at legacy manufacturers.
- Residue testing infrastructure:Third-party laboratory capacity for maximum residue limit verification is bottlenecking export certification for specialty crop cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fungicide Market |
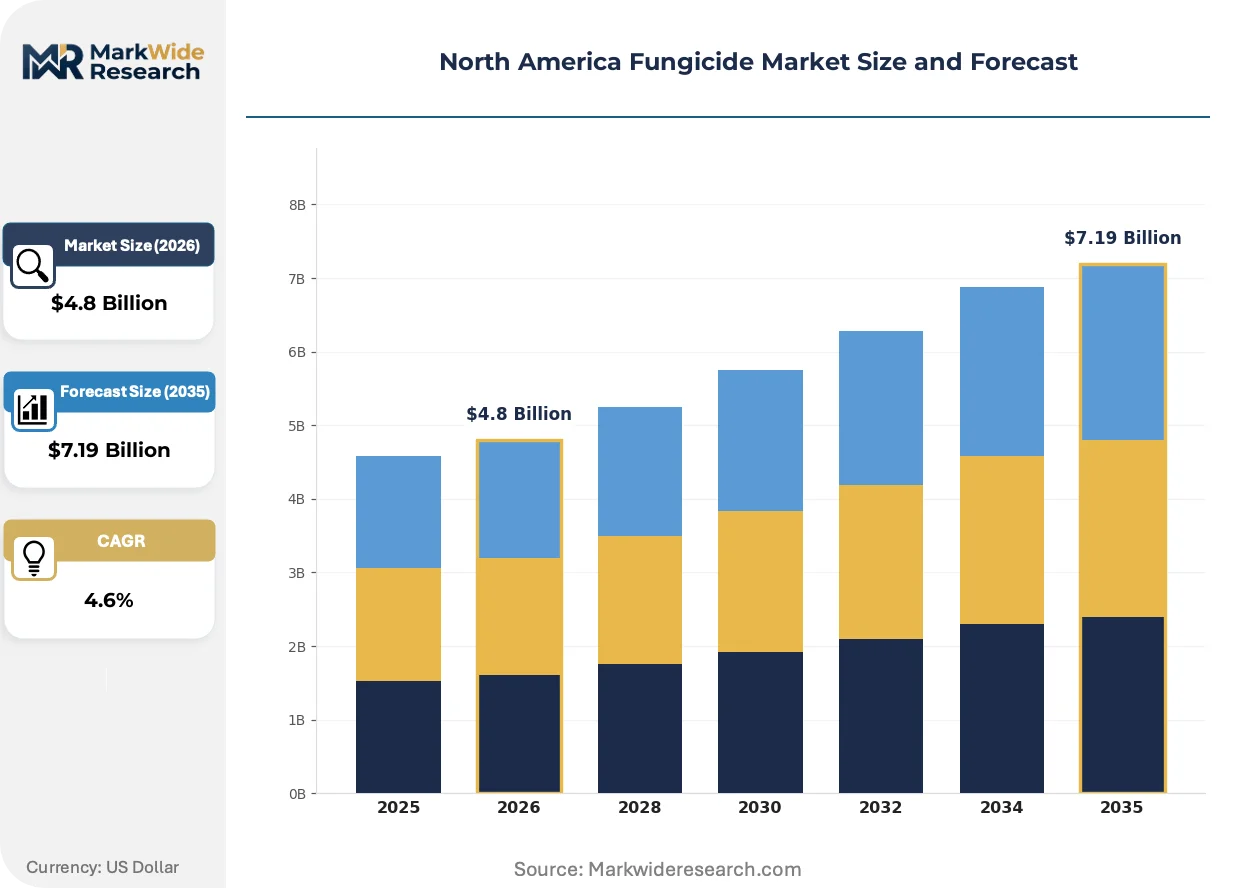
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triazoles, Azoles, Strobilurins, Biologicals Application: Agriculture, Horticulture, Turf, Ornamentals End User: Farmers, Landscapers, Gardeners, Commercial Growers Distribution Channel: Online Retail, Direct Sales, Distributors, Agricultural Cooperatives |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta Group, FMC Corporation, UPL Limited, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical Co Ltd, Nufarm Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fungicide Market Trends and Innovations
RNA interference fungicides are advancing from greenhouse trials toward field registration, threatening to disrupt conventional mode-of-action categories across the row crop and specialty sectors.
RNAi-based fungicide platforms are decomposing the traditional protectant-curative dichotomy by enabling sequence-specific pathogen suppression without broad-spectrum ecological impact. Large-scale corn and soybean operators in Iowa and Illinois are piloting these formulations through grower-funded research cooperatives. The technology is decomposing established FRAC classification systems and forcing registrants to develop entirely new resistance monitoring protocols.
EPA's revised endangered species biological opinions under FIFRA are mandating expanded buffer zones and aquatic toxicity testing for new synthetic fungicide registrations. These requirements are elevating development costs and pushing manufacturers toward biological alternatives with streamlined ecological risk profiles. Specialty crop exporters in California's Central Valley are accelerating adoption of microbial formulations to preempt future use restrictions.
Direct-to-grower digital platforms are consolidating procurement decisions for fungicide programs away from traditional agricultural retail cooperatives. Midwestern corn belt farmers are increasingly subscribing to season-long crop protection bundles through manufacturer portals, bypassing independent agronomists. This channel shift is most pronounced among operations exceeding 5,000 acres in Illinois and Indiana, where price transparency and rebate aggregation drive platform selection.
North America Fungicide Market Segmentation
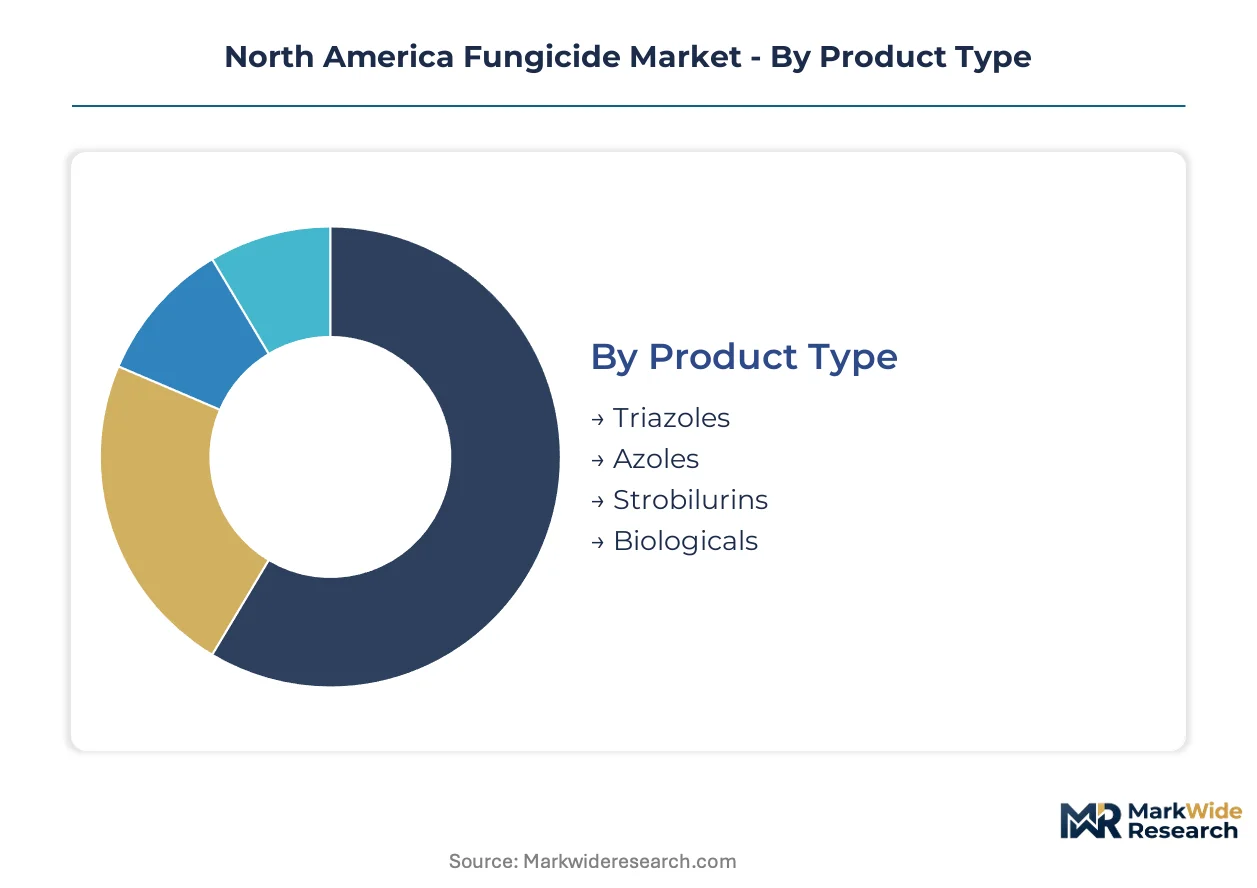
Segmentation in the North America fungicide market reveals distinct procurement patterns between export-oriented specialty crop regions and domestic row crop belts. Understanding these divides helps manufacturers align formulation portfolios with regulatory tolerance windows and residue compliance tiers.
Product Type:
Domestic consumption concentrates on broad-spectrum synthetics for corn-soy rotations, while export-facing growers in California and Florida drive biological adoption to meet EU and Asian maximum residue limits.
- Triazoles:Systemic ergosterol biosynthesis inhibitors with curative and protective activity against ascomycete and basidiomycete pathogens. Demand clusters in the U.S. Corn Belt and Canadian prairie provinces where fusarium head blight and rust diseases drive preventive spray programs; EPA re-registration reviews are compressing effective product lifespans and forcing rotation mandates.
- Biologicals:Microbial and plant-extract formulations including Bacillus subtilis and Trichoderma species with multiple modes of action and zero pre-harvest intervals. California Central Valley fruit exporters and Florida vegetable growers are expanding acreage coverage to secure EU MRL compliance and preempt future synthetic restrictions.
- Azoles:Demethylation inhibitors with established efficacy in turf and ornamental applications where aesthetic thresholds demand rapid knockdown.
- Strobilurins:Quinone outside inhibitors applied preventively in high-value potato and sugar beet production across the Red River Valley and Michigan.
Triazoles hold the largest share; momentum sits with biologicals.
Application:
Cost tiers separate commodity grain operations from high-input specialty systems where treatment frequency and product selection correlate directly with export certification requirements.
- Agriculture:Row crop and specialty vegetable production encompassing corn, soybeans, wheat, potatoes, and high-value fruits. Iowa and Illinois corn operators apply preventive programs at V5-V8 growth stages; California strawberry and lettuce growers intensify rotations to manage botrytis and downy mildew pressure under coastal humidity.
- Horticulture:Tree fruit, vine crops, and protected greenhouse vegetables requiring residue-compliant chemistries for premium export channels. Washington apple and Oregon pear producers are transitioning biological shares to maintain Japan and Taiwan market access.
- Turf:Golf course and sports field maintenance with aesthetic-driven application timing and concentrated seasonal demand in the Southeast and Mid-Atlantic.
- Ornamentals:Nursery stock and greenhouse floral production where phytotoxicity tolerance limits product selection and buffer zone restrictions constrain application windows.
Agriculture commands the volume base; horticulture carries the steepest expansion trajectory.
End User:
Customer type determines technical service intensity, with commercial operations demanding direct manufacturer relationships and small-scale users remaining tethered to retail intermediaries.
- Commercial Growers:Operations exceeding 1,000 acres or 100 greenhouse acres with dedicated agronomy staff and volume-based procurement leverage. California Central Valley almond and pistachio cooperatives negotiate direct technical service agreements; Florida tomato and pepper operations coordinate county-wide resistance monitoring programs.
- Farmers:Mid-scale grain and oilseed producers in the Corn Belt and Northern Plains relying on agricultural cooperative recommendations and rebate-aggregated purchasing. Saskatchewan canola growers show adoption gaps for biological seed treatments versus U.S. benchmarks.
- Landscapers:Commercial maintenance contractors serving municipal and corporate accounts with seasonal crew-based application schedules.
- Gardeners:Residential consumers purchasing through home improvement retail with price sensitivity and pre-mixed formulation preferences.
Commercial growers anchor premium pricing; biological uptake among farmers is climbing fastest.
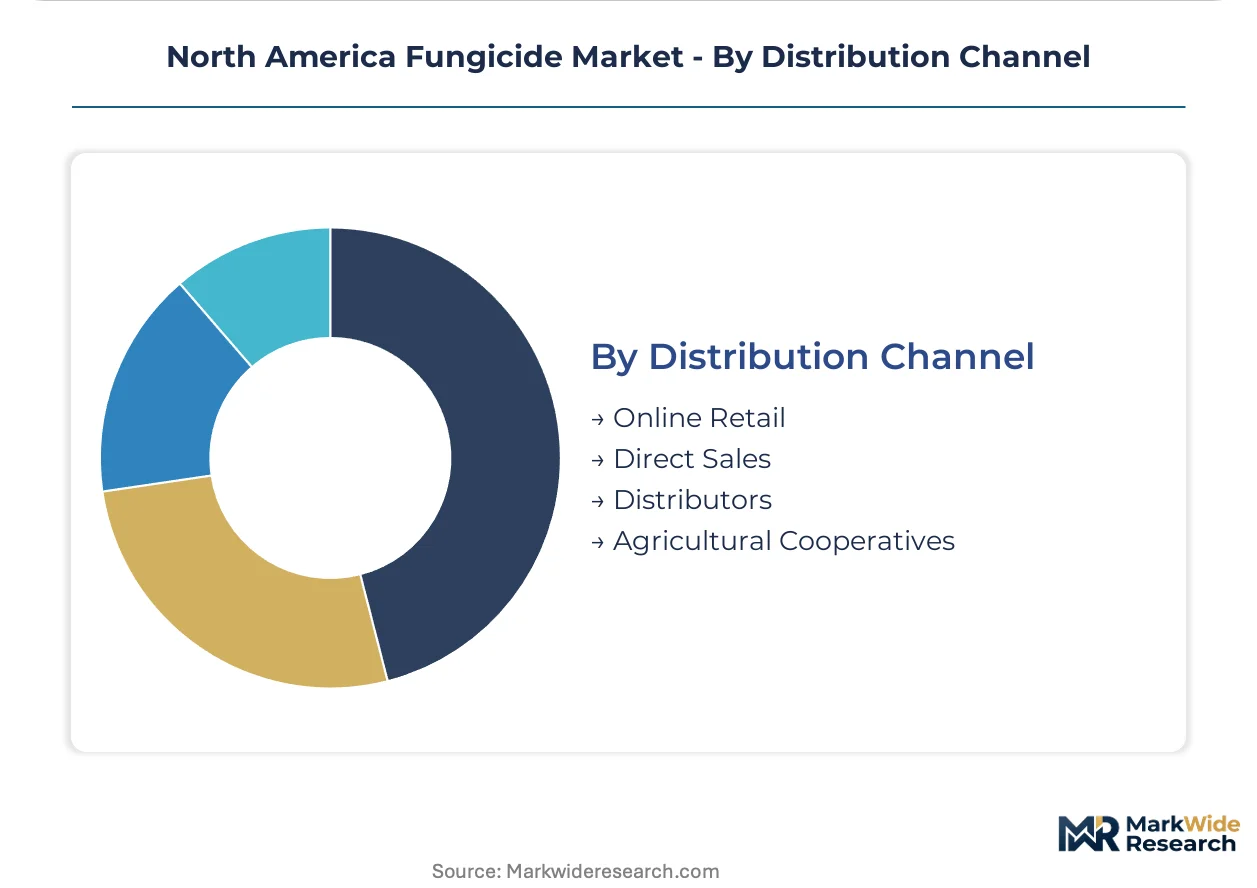
Distribution Channel:
Channel control is fragmenting as direct manufacturer platforms erode traditional cooperative dominance among large-acreage operators.
- Agricultural Cooperatives:Member-owned purchasing networks with embedded agronomists and seasonal credit programs. Corteva Agriscience and Bayer AG maintain exclusive technical service partnerships with regional cooperatives across Illinois, Indiana, and Iowa.
- Distributors:Independent wholesalers warehousing inventory for rural retail locations and custom applicators with localized disease pressure expertise.
- Direct Sales:Manufacturer portals and subscription bundles targeting operations exceeding 5,000 acres with price transparency and rebate aggregation. BASF SE and Syngenta Group are piloting season-long crop protection subscriptions in the Corn Belt.
- Online Retail:E-commerce platforms serving residential gardeners and small-scale landscapers with next-day delivery and product comparison tools.
Agricultural cooperatives retain the largest share; direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers in California's Central Valley and Iowa's Corn Belt command distinct procurement patterns. Specialty crop exporters prioritize residue-compliant biologicals for EU and Asian market access. Row crop operators emphasize cost-per-acre efficiency in preventive spray programs.
United States
California strawberry and lettuce growers intensify fungicide rotations to manage botrytis under coastal humidity. EPA FIFRA re-registration reviews compress effective product lifespans for triazole chemistries. The Central Valley almond and pistachio belt anchors biological adoption rates for export certification.
Canada
Saskatchewan canola and Alberta pulse growers show adoption gaps for biological seed treatments versus U.S. benchmarks. PMRA registration pathways maintain alignment with EPA data requirements while preserving independent ecological risk assessments. Prairie province cooperatives coordinate county-wide resistance monitoring programs.
Mexico
Sinaloa tomato and berry exporters face tightening EU maximum residue limits on synthetic fungicides. COFEPRIS harmonizes registration timelines with EPA and PMRA through trilateral data-sharing agreements. The Bajío region's greenhouse vegetable cluster accelerates microbial formulation trials for Netherlands and UK market access.
North America Fungicide Market Competitive Landscape
Player mix skews toward integrated multinational agrochemical conglomerates with captive technical production. Three suppliers control the majority of global strobilurin active ingredient output. Strategic archetypes separate backward-integrated pyraclostrobin producers, in-house triazole specialists, and biologicals-focused R&D partnerships. Dominant competitive moves include exclusive technical service agreements with agricultural cooperatives and direct-to-grower digital platform launches.
Among European-based integrated suppliers, BASF SE and Bayer AG exemplify contrasting strategic positions. BASF SE anchors the strobilurin cost-leadership archetype through captive pyraclostrobin supply chains. Bayer AG occupies the systemic chemistry dominance position with established corn-soybean distribution networks. Corteva Agriscience represents the biologicals-channel control hybrid model, embedding technical partnerships within cooperative purchasing structures.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Syngenta Group |
| FMC Corporation |
| UPL Limited |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical Co Ltd |
| Nufarm Ltd |
| Others |
Pricing and Supply Chain Analysis
EPA Section 3 registration under FIFRA gates both supplier qualification and price differentiation simultaneously, as only registrants with approved active ingredients can access premium pricing tiers while residue-compliant biologicals command export-market premiums.
Pricing Analysis
Cost-plus contracts with indexation to active ingredient feedstock costs dominate procurement between multinational formulators and agricultural cooperatives. Pricing stratifies across premium biological formulations, standard triazole blends, and economy generic strobilurins based on certification grade and volume scale. Cost compression in economy synthetics is intensifying because of concentrated strobilurin technical production among three global suppliers. Small-scale gardeners show highest price sensitivity through retail channels, while commercial growers above 5,000 acres leverage direct manufacturer subscriptions for lowest net costs.
Supply Chain Analysis
Strategic stockpiling of strobilurin technical concentrates among German, Chinese, and Indian active ingredient manufacturers, while North American formulators maintain just-in-time finished goods inventory ahead of planting seasons. Formulation draws from pyraclostrobin, triazole intermediates, and microbial culture stocks as primary inputs. Single-source vulnerability in strobilurin technical creates supply chain risk for formulators lacking backward integration. Distribution runs through agricultural cooperatives in the Corn Belt, direct manufacturer portals for large operations, and independent wholesalers serving specialty crop regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery driven by climate-driven extension of fungal pathogen seasons across the U.S. Corn Belt, expanding treatment windows and replenishing channel inventory.
For Market Incumbents: Consolidate backward integration into pyraclostrobin technical production to offset input cost volatility from concentrated global suppliers. Deepen exclusive technical service agreements with agricultural cooperatives in Illinois and Iowa to defend against direct-to-grower digital platforms eroding channel control. For New Entrants and Emerging Players: Biological seed treatment services for Canadian prairie canola and pulse growers represent an under-served white space where adoption gaps versus U.S. benchmarks create penetration opportunity. Target state-level 24(c) special local need registrations as a regulatory-first go-to-market angle to establish foothold before national EPA registration. For Investors and Strategic Acquirers: Carve-out targets emerge from agrochemical conglomerates spinning off biologicals R&D units lacking scale to compete with integrated players. Long-term viability hinges on residue-compliant formulation portfolios aligned with EU and Asian import standards. Watch EPA Endangered Species Act consultation timelines as the inflection signal—accelerated biological opinions that restrict synthetic chemistries would re-rate biologicals-focused assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Production | Captive pyraclostrobin supply secures cost advantage against input volatility. |
| Biologicals R&D Partnership Expansion | Microbial formulation pipelines accelerate EPA biopesticide registration timelines. |
| Direct-to-Grower Digital Platform Launch | Subscription bundles bypass agricultural cooperatives for operations exceeding 5,000 acres. |
| State-Level 24(c) Registration Pursuit | Emergency exemptions for minor crops create first-mover positioning ahead of national approval. |
| Precision Application Technology Integration | Drone spraying platforms with variable-rate maps enable service-based revenue models. |
Research Methodology
A standing panel of EPA regulatory affairs specialists, agricultural cooperative procurement managers, and specialty crop export compliance officers provided ongoing calibration throughout the study period. Primary interviews with formulation chemists at legacy manufacturers, biologicals R&D directors, and state Department of Agriculture registration staff combined with secondary validation against EPA registration databases, PMRA submission records, and FIFRA re-registration dockets. Bottom-up acreage and application rate estimates triangulated against top-down manufacturer shipment data.
Consistency checks validated volume and value outputs against USDA NASS crop acreage reports, state-level pesticide use surveys, and agricultural cooperative purchasing data across the analysis window. Segmentation modeling covered product type, application sector, end-user scale, and distribution channel dimensions. CAGRs derived from regression analysis of historical shipment trends and projected acreage expansion under climate-driven disease pressure scenarios, with explicit modeling of EPA registration timeline impacts on product launch cadence.
Underlying assumptions cover stable FIFRA registration pathways, cooperative channel retention above 50% share, and biologicals adoption rates in specialty crops, with deviation risk concentrated in EPA Endangered Species Act consultation delays and EU maximum residue limit tightening. Revision becomes warranted when regulatory timeline extensions exceed 36 months or when biologicals penetration in row crops crosses 15% threshold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market