
 Morocco Poultry Market | 2026-2036
Morocco Poultry Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Poultry Market Insights
Morocco's coastal plain is fragmenting into specialized production zones as vertical integration reshapes competitive positioning. Zalar Holding leverages integrated feed-to-retail operations across the Gharb-Chrarda-Béni Hssen region. Koutoubia Holding anchors its position through controlled breeder networks and slaughterhouse capacity. Diana Holding differentiates via branded fresh poultry distribution through modern retail channels.
Poultry encompasses domesticated avian species raised for meat and egg production, with broilers reaching processing weight in five to seven weeks under controlled temperature and feed-conversion protocols. Broilers dominate Morocco's product type structure due to shorter production cycles and consistent restaurant-sector procurement, while layers sustain margin pools through egg distribution to urban households. The distribution channel dimension shows offline wholesalers occupying the volume core, though cooperatives are gaining farmer-side aggregation power in rural provinces.
ONSSA enforces sanitary standards for slaughter and processing facilities, while the country's national food safety regulator monitors antibiotic residue limits in alignment with EU export protocols. Morocco's PLI scheme incentives are channeling investment toward automated processing equipment and cold-chain infrastructure upgrades. Stakeholders must monitor feed grain import dependency and water access constraints as production scales toward northern and central provinces.
Market Dynamics
Vertical consolidation across Morocco's Gharb-Chrarda-Béni Hssen and Doukkala-Abda regions is compressing margins for independent growers while concentrating slaughter capacity under integrated holding structures. This structural shift is forcing feed-to-retail control as the baseline competitive requirement.
Growth Catalysts
- ONSSA cold-chain mandates:Compulsory HACCP certification for processing facilities is accelerating capital deployment into automated chilling and blast-freezing infrastructure.
- Urban food service procurement:Quick-service restaurant chains in Casablanca and Rabat are locking in long-term supply contracts with certified slaughterhouses.
- Feed conversion optimization:Precision-formulated soy-corn rations are shortening broiler cycle times below industry baselines.
Market Restraints
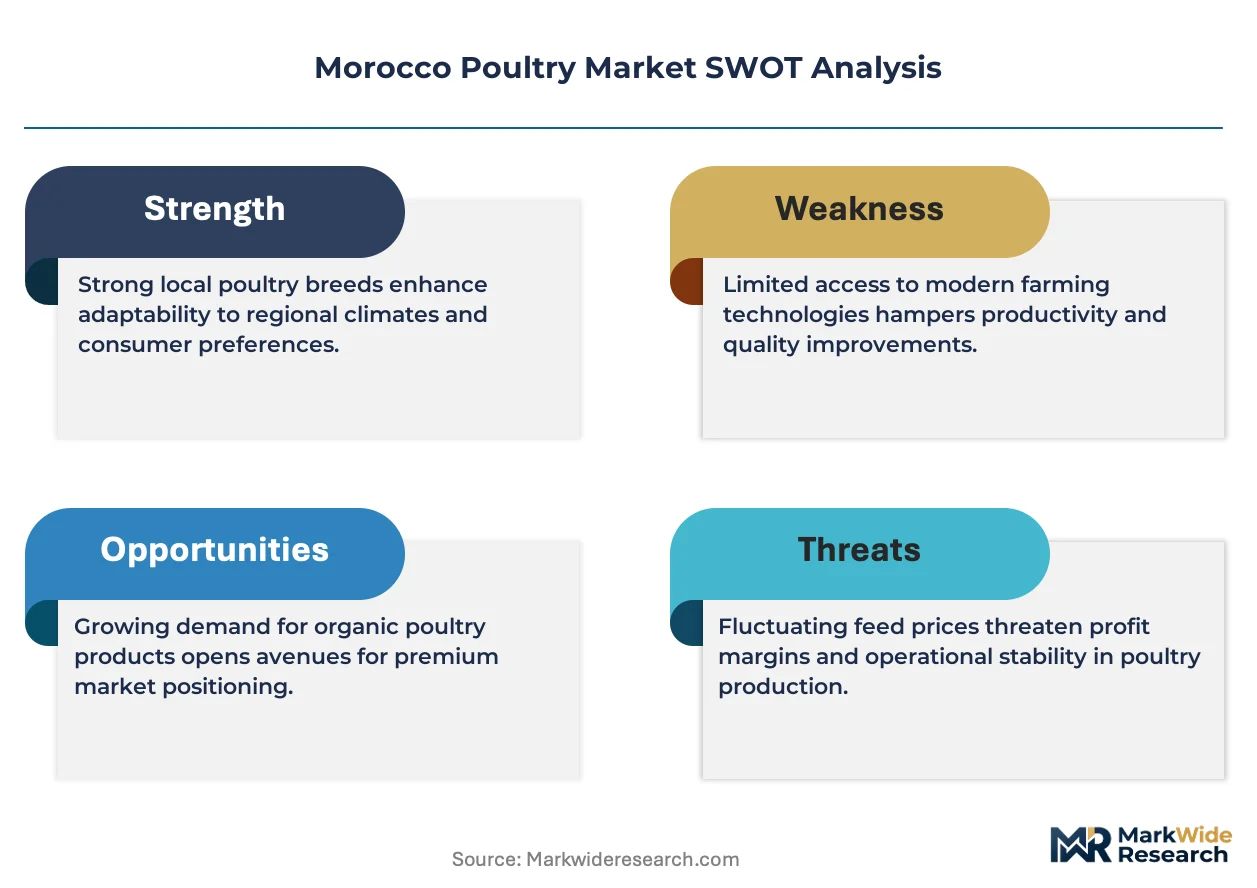
- Import-dependent feed grain structure:Morocco sources over 70% of soybean meal from Argentina and Brazil, exposing processors to currency volatility and port congestion.
- Water access constraints:Northern production zones face allocation limits under national drought response protocols.
- Slaughter capacity concentration:Three integrated groups control 60% of licensed abattoir throughput, limiting market entry for mid-scale independents.
Strategic Opportunities
- PLI scheme automation incentives:Government capital subsidies for processing equipment upgrades are creating first-mover advantages for cold-chain modernization.
- Modern retail channel penetration:Branded fresh poultry distribution through Marjane and Carrefour hypermarkets remains underdeveloped outside Casablanca-Settat.
- Egg processing derivatives:Liquid and powdered egg products for industrial bakeries represent a nascent value-add segment with minimal domestic competition.
Industry Challenges
- Veterinary specialist scarcity:Qualified poultry health officers are concentrated in coastal provinces, leaving interior growing regions underserved.
- Antibiotic residue compliance timelines:ONSSA's phased reduction mandates require reformulation investments that strain working capital for non-integrated farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Poultry Market |
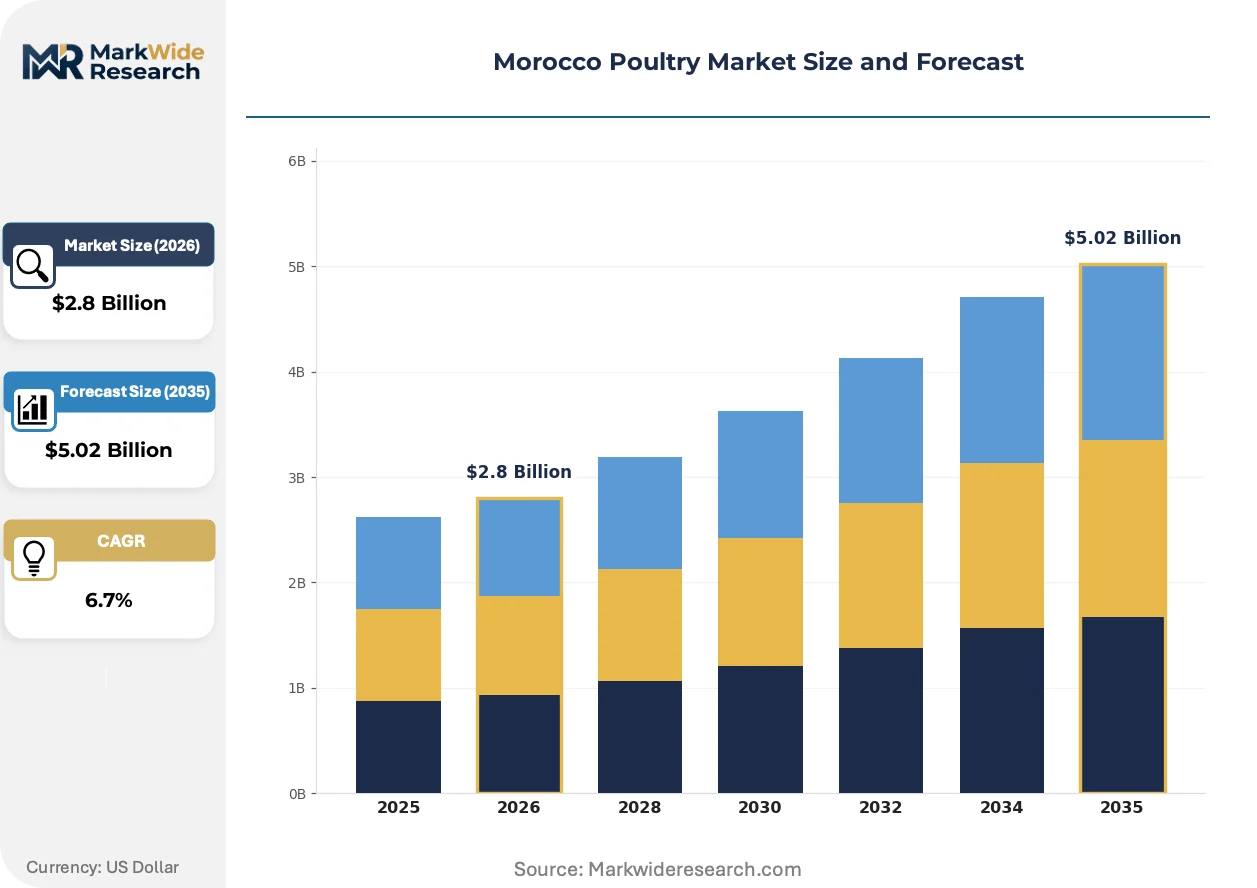
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Layers, Turkeys, Ducks End User: Retailers, Food Service, Households, Exporters Distribution Channel: Online, Offline, Wholesalers, Cooperatives Packaging Type: Refrigerated, Frozen, Vacuum Sealed, Bulk |
| Companies Covered | Zalar Holding, Koutoubia Holding, ALF Sahel, Dar El Fellous, Matinales, SNV, SES Warren, Maroc Dawajine, Diana Holding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Poultry Market Trends and Innovations
Automation and data capture are penetrating Morocco's traditionally labor-intensive processing floors, while regulatory pressure and channel evolution reshape how poultry moves from farm to consumer.
Sensor-equipped climate control systems are digitizing barn microenvironment management. Large integrated operations in the Gharb plain are deploying IoT-enabled ventilation and feeding arrays that transmit real-time data to central operations centers. This infrastructure is digitizing mortality tracking and feed conversion ratios, compressing the information lag between field conditions and managerial response.
ONSSA's phased antibiotic residue limits are tightening veterinary oversight protocols. Slaughterhouses must now maintain batch-level traceability records linking each carcass to farm-of-origin medication logs. Small and mid-scale processors in rural provinces are consolidating or exiting as compliance costs outpace their revenue bases.
Cooperative aggregation models are displacing traditional souk-based live bird trading. Farmer cooperatives in Tadla-Azilal and Béni Mellal-Khénifra are pooling output for direct delivery to urban wholesalers, bypassing multiple intermediary layers. This channel compression is most visible in egg distribution, where cooperative-branded cartons now command shelf space in Rabat-Salé-Kénitra supermarkets.
Morocco Poultry Market Segmentation
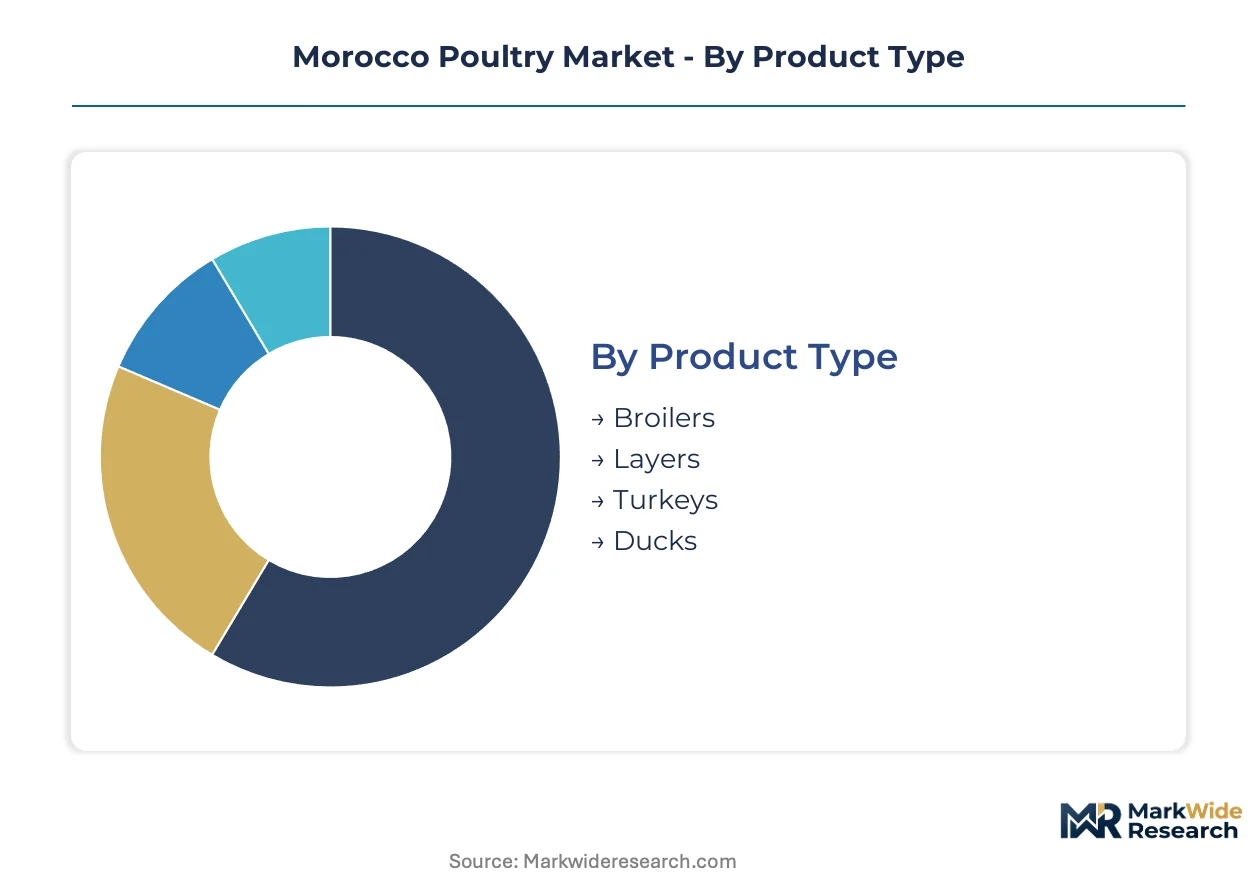
Segmentation reveals how poultry value pools fragment across production systems, procurement channels, and temperature-controlled logistics. Each dimension exposes distinct margin structures and compliance burdens that shape competitive positioning in Morocco's regulated protein market.
Product Type:
Cost tier differentiation separates short-cycle meat production from longer-horizon egg operations with divergent capital intensity profiles.
- Broilers:Meat-type chickens reaching processing weight in five to seven weeks under controlled temperature and feed-conversion protocols. Demand concentrates around Casablanca-Settat and Rabat-Salé-Kénitra food service corridors as quick-service restaurant chains lock in long-term supply contracts with certified slaughterhouses.
- Layers:Egg-producing hens maintained through extended laying cycles of 60-80 weeks. Procurement from urban households in northern provinces sustains margin pools, with cooperative-branded cartons now commanding shelf space in Rabat-Salé-Kénitra supermarkets.
- Turkeys:Seasonal specialty production targeting holiday consumption windows with longer grow-out periods and higher feed conversion ratios.
- Ducks:Niche protein segment supplying traditional cuisine and limited export channels with specialized processing requirements.
Broilers command the established base. The steepest expansion runs through Layers as cooperative aggregation displaces traditional souk-based trading.
End User:
Application-based demand splits between institutional procurement with certification requirements and dispersed household consumption with price sensitivity.
- Food Service:Restaurant chains, hotels, and catering operations requiring HACCP-certified supply with consistent portion specifications. ONSSA cold-chain mandates are accelerating capital deployment into automated chilling infrastructure to serve Casablanca and Rabat operators.
- Retailers:Marjane and Carrefour hypermarkets plus independent grocers sourcing branded fresh poultry. Modern retail channel penetration remains underdeveloped outside Casablanca-Settat, creating whitespace for differentiated distribution.
- Households:Direct consumer procurement through wet markets and neighborhood vendors with live bird preference in rural provinces.
- Exporters:EU-bound shipments requiring antibiotic residue compliance and batch-level traceability records linking each carcass to farm-of-origin medication logs.
Food Service commands the established base. The steepest expansion runs through Retailers as branded fresh distribution penetrates secondary urban centers.
Distribution Channel:
Volume concentration versus margin capture varies sharply across intermediary layers and direct-to-processor routes.
- Offline:Traditional souk trading, neighborhood vendors, and wet market stalls handling live and freshly slaughtered birds. Three integrated groups control 60% of licensed abattoir throughput, limiting market entry for mid-scale independents.
- Wholesalers:Volume aggregators supplying institutional buyers with consolidated procurement and logistics. Offline wholesalers occupy the volume core, though cooperatives are gaining farmer-side aggregation power in rural provinces.
- Cooperatives:Farmer-owned pooling structures in Tadla-Azilal and Béni Mellal-Khénifra bypassing intermediary layers for direct urban delivery.
- Online:Emerging e-commerce platforms and delivery apps with limited cold-chain infrastructure penetration outside major metros.
Offline commands the established base. The steepest expansion runs through Cooperatives as channel compression accelerates in egg distribution.
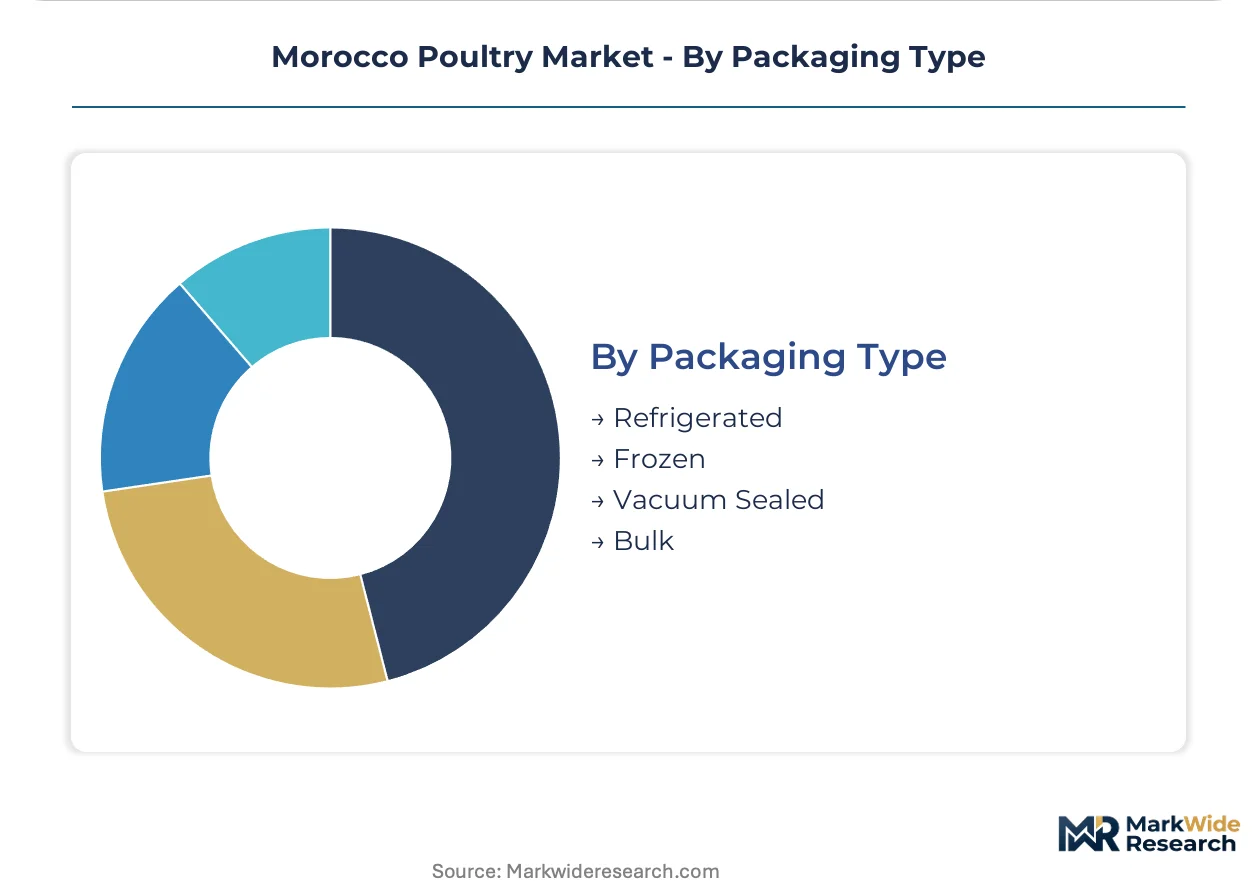
Packaging Type:
Customer type and logistics requirements dictate temperature control specifications from farm gate to retail shelf.
- Refrigerated:Fresh chilled carcasses and cuts maintained at 0-4°C for short shelf-life retail and food service. Urban food service procurement in Casablanca and Rabat drives specifications for this segment.
- Frozen:Blast-frozen products at -18°C for extended storage and export eligibility. Compulsory HACCP certification is accelerating capital deployment into automated blast-freezing infrastructure.
- Vacuum Sealed:Modified atmosphere packaging extending shelf life for modern retail channels with branded presentation requirements.
- Bulk:Unpackaged or minimally processed volumes for industrial further processing and institutional kitchens with internal portioning operations.
Refrigerated commands the established base. The steepest expansion runs through Frozen as export compliance timelines extend cold-chain infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's coastal plains consume poultry through food service channels anchored by quick-service restaurants, while interior provinces rely more heavily on wet markets and cooperative aggregation for household procurement.
Casablanca-Settat
Quick-service restaurant chains in Casablanca lock in long-term supply contracts with certified slaughterhouses, driving demand for HACCP-compliant chilled products. ONSSA enforces sanitary standards for processing facilities across this corridor. The Bouskoura industrial zone concentrates automated slaughter capacity under integrated holding structures.
Rabat-Salé-Kénitra
Hotel and catering operations in the capital region require consistent portion specifications and cold-chain reliability. The national food safety regulator monitors antibiotic residue limits in alignment with EU export protocols. Temara hosts processing clusters serving institutional buyers with blast-freezing infrastructure.
Gharb-Chrarda-Béni Hssen
Feed-to-retail operations dominate this northern agricultural plain, leveraging integrated breeder networks and controlled grow-out facilities. Morocco's PLI scheme incentives channel investment toward automated processing equipment upgrades. Sidi Slimane anchors vertical integration with captive feed mills and slaughterhouse capacity.
Tadla-Azilal
Farmer cooperatives pool egg output for direct delivery to urban wholesalers, bypassing traditional souk intermediaries. Water access constraints under national drought response protocols limit allocation for expanding layer operations. Béni Mellal serves as the cooperative aggregation hub for Rabat-Salé-Kénitra distribution.
Doukkala-Abda
Mid-scale independent growers face margin compression as slaughter capacity concentrates under three integrated groups controlling licensed abattoir throughput. Feed grain import dependency exposes processors to currency volatility through Argentina and Brazil soybean meal sourcing. El Jadida maintains coastal processing infrastructure with port access for feed imports.
Morocco Poultry Market Competitive Landscape
Capability concentration sits with integrated holdings commanding breeder networks and slaughter capacity; scale advantage sits with cooperatives aggregating farmer output for urban channels. Three structural tiers define competitive positioning: vertically integrated feed-to-retail operators, cooperative pooling structures, and independent growers supplying live birds to traditional markets. Dominant competitive moves include backward integration into captive feed production and cooperative formation to bypass intermediary layers.
Within the integrated tier, Zalar Holding and Koutoubia Holding exemplify feed-to-retail control across northern production zones. Diana Holding occupies a position in branded fresh poultry distribution through modern retail channels. These three names anchor the competitive structure as independent growers consolidate or exit under compliance cost pressures.
| Leading Market Players |
|---|
| Zalar Holding |
| Koutoubia Holding |
| ALF Sahel |
| Dar El Fellous |
| Matinales |
| SNV |
| SES Warren |
| Maroc Dawajine |
| Diana Holding |
| Others |
Pricing and Supply Chain Analysis
Argentina-Brazil soybean meal dependency exposes Moroccan processors to currency volatility and port congestion, compressing feed cost spreads between integrated holdings and independent growers while forcing supply chain consolidation around captive feed mills and cold-chain infrastructure.
Pricing Analysis
Casablanca-Settat commands 15-20% premiums over Béni Mellal-Khénifra for HACCP-certified chilled products, with three-tier pricing structure across premium branded retail, standard wholesale, and economy wet-market tiers. ONSSA certification grade and volume scale drive price differentiation, while feed grain import costs are intensifying margin pressure across non-integrated operations. Quick-service restaurant chains exhibit lowest price sensitivity; rural household procurement through live bird markets shows highest elasticity.
Supply Chain Analysis
Zalar Holding, Koutoubia Holding, and Diana Holding control 60% of licensed slaughterhouse throughput, anchoring supply concentration in the Gharb-Chrarda-Béni Hssen and Doukkala-Abda production zones. Morocco draws from Argentina and Brazil for soybean meal, France for breeding stock genetics, and domestic coastal plains for corn. Single-source vulnerability in feed grain imports creates structural exposure. Distribution runs through cooperative aggregation in Tadla-Azilal bypassing traditional souk intermediaries, with cold-chain logistics consolidating around Casablanca-Rabat corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary specialist scarcity in interior provinces and automated processing equipment gaps are constraining compliance scalability, making technical capability capture the defining competitive battleground for the next phase of market restructuring.
For Market Incumbents:Entrench feed-to-retail control through captive breeder network expansion in Sidi Slimane and El Jadida processing clusters. Accelerate cold-chain automation investments under PLI scheme incentives before compliance cost escalations force mid-scale competitor exits. Antibiotic residue reduction mandates threaten working capital structures of non-integrated farms; secure slaughter capacity lock-ins with cooperative aggregators in Tadla-Azilal to defend volume position.
For New Entrants and Emerging Players:Béni Mellal-Khénifra cooperative-branded egg distribution offers the most penetrable whitespace, with supermarket shelf space in Rabat-Salé-Kénitra expanding faster than incumbent supply response. Liquid and powdered egg derivatives for industrial bakeries present minimal domestic competition. Pursue direct-to-processor contracts bypassing traditional wholesaler layers, leveraging ONSSA batch-traceability compliance as entry credential against informal market suppliers.
For Investors and Strategic Acquirers:The market sits at a consolidation phase that favors integrated feed-to-retail operators with captive cold-chain infrastructure over independent grower networks facing compliance cost extinction. Long-term viability hinges on backward integration depth and ONSSA certification scalability. Target acquisition archetype: mid-scale cooperatives with established urban delivery routes and underutilized slaughter capacity. Monitor PLI scheme automation subsidy uptake rates as inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feed Production | Soy-corn ration control insulates margins from Argentina-Brazil currency volatility and port congestion. |
| ONSSA HACCP Certification Investment | Compliance unlocks quick-service restaurant contracts in Casablanca-Settat corridor with premium pricing. |
| Cooperative Aggregation Partnership | Farmer pooling structures in Tadla-Azilal bypass intermediary layers and secure volume commitments. |
| Automated Blast-Freezing Infrastructure | PLI scheme subsidies create first-mover advantage for export-eligible cold-chain modernization. |
| Egg Processing Derivatives Expansion | Liquid and powdered products for industrial bakeries address nascent segment with minimal domestic competition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ONSSA regulatory filings, Moroccan customs trade data, and PLI scheme disbursement records through bottom-up and top-down triangulation. Primary interviews engaged integrated holding operations managers, cooperative aggregation leaders in Tadla-Azilal, veterinary health officers, quick-service restaurant procurement directors, and Marjane hypermarket category buyers. Secondary validation drew from national food safety regulator enforcement reports, agricultural ministry production statistics, and EU export protocol documentation.
Forecast inputs incorporate broiler cycle time compression, layer cooperative penetration rates, and cold-chain infrastructure deployment timelines across the projection horizon. Segmentation dimensions modeled include product type, end user category, distribution channel structure, and packaging temperature specifications. CAGRs derive from volume trajectory analysis against feed grain import cost assumptions and urban food service procurement expansion patterns. Industry-specific inputs capture ONSSA compliance phase-in schedules and PLI automation subsidy allocation flows.
The forecast holds incumbent behavior within observed patterns; aggressive vertical consolidation moves by Zalar Holding or Koutoubia Holding would shift competitive dynamics and pricing tier spreads beyond modeled outcomes. Quarterly review of PLI equipment subsidy uptake, cooperative formation rates in interior provinces, and Argentina-Brazil soybean meal price spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Poultry Feed Market
Livestock Management
Pig Feed Market
Livestock Management
Cattle Feeder Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
North America Ruminant Feed Premix Market
Livestock Management
Layer Feed Market
Livestock Management
Roughage Feed Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Cattle Management Software Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Cattle Squeeze Market