
 Global Medicated Feed Additives Market | 2026-2036
Global Medicated Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medicated Feed Additives Market Outlook
The EU Green Deal is rebalancing formulation priorities across European livestock operations. Elanco Animal Health Incorporated leverages its antimicrobial-alternative pipeline to sustain veterinary-grade probiotic supply. Cargill, Incorporated anchors North American distribution through vertically integrated feed mill networks. Zoetis Inc. competes on species-specific immunomodulator development for intensive poultry systems.
Medicated feed additives are therapeutic or prophylactic substances incorporated into compound feeds at precise inclusion rates, typically containing active pharmaceutical ingredients, nutritional cofactors, or microbial cultures formulated for homogeneous distribution in pelleted or mash rations. Their primary purpose is to prevent, control, or treat disease in food-producing animals while simultaneously supporting growth performance and feed conversion efficiency. Amino acids dominate value capture in mature poultry and swine diets where crystalline L-lysine and L-threonine replace protein meals. Probiotics represent the fastest-expanding component category as direct-fed microbials displace sub-therapeutic antibiotics under tightening residue regulations. The medicinal ingredients segment concentrates margin pools where patent-protected ionophores and synthetic coccidiostats command formulation premiums.
The FDA's Veterinary Feed Directive governs antimicrobial use in US livestock, requiring veterinary oversight for medically important drugs in feed. EMA and EFSA jointly evaluate maximum residue limits and withdrawal periods for medicated feed additives marketed across EU member states. China's NMPA and Ministry of Agriculture enforce GB standard compliance for imported and domestically manufactured veterinary drug premixes. Stakeholders must monitor divergence between US and EU antimicrobial stewardship timelines to anticipate which formulation categories face accelerated phase-out versus extended compliance windows.
Market Dynamics
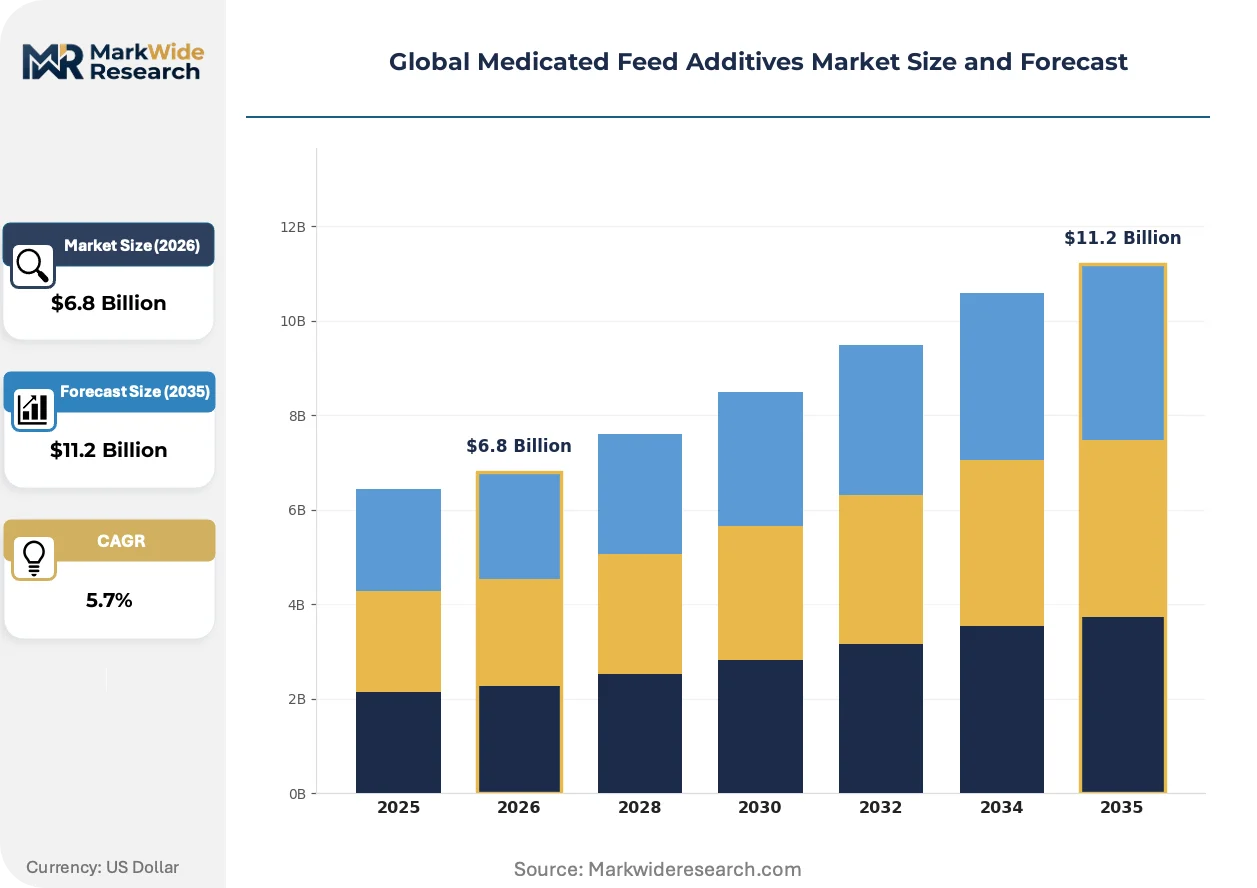
Antimicrobial stewardship programs are compressing formulation portfolios worldwide as regulators enforce withdrawal timelines for growth-promoting antibiotics. Livestock integrators must rebuild premix strategies around microbial alternatives while maintaining feed conversion benchmarks.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:Member states face binding antimicrobial reduction targets that accelerate probiotic formulation demand across swine and poultry operations.
- China's industrial swine restocking:Disease cycle recovery in concentrated animal feeding operations pulls therapeutic premix volumes through veterinary distribution channels.
- Precision fermentation for amino acids:Biosynthesis platforms cut production costs for L-lysine and L-threonine, expanding inclusion rates in cost-sensitive rations.
Market Restraints
- API supply concentration:Ionophore active ingredients depend on Chinese fermentation capacity, exposing formulators to export license volatility.
- Regulatory divergence friction:FDA Veterinary Feed Directive timelines misalign with EMA withdrawal schedules, complicating multinational premix portfolios.
- Substitution pressure from phytogenics:Essential oil blends displace synthetic coccidiostats in antibiotic-free certification programs.
Strategic Opportunities
- Brazil's antibiotic-free poultry expansion:Export-oriented integrators seek validated probiotic alternatives to maintain EU market access.
- Direct-fed microbial-digestive enzyme convergence:Combined formulations address both gut health and nutrient absorption in single inclusion products.
- India's dairy intensification:Cooperative sector modernization creates first-time demand for medicated calf starters and transition cow premixes.
Industry Challenges
- Microbiome assay standardization:Probiotic efficacy claims lack harmonized CFU enumeration protocols across national reference laboratories.
- Feed mill equipment reconfiguration:Heat-sensitive microbial additives require pelleting temperature retrofits that strain capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medicated Feed Additives Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Antioxidants, Vitamins, Probiotics End User: Poultry Farms, Swine Producers, Ruminant Feeders, Aquaculture Component: Medicinal Ingredients, Nutritional Substances, Flavoring Agents, Fillers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Outlets |
| Companies Covered | Elanco Animal Health Incorporated, CHS Inc., Cargill, Incorporated, Evonik Industries AG, Kemin Industries, Phibro Animal Health Corporation, Zoetis Inc., Nutreco, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medicated Feed Additives Market Strategic Shifts
Livestock nutrition is pivoting from pharmaceutical dependence toward functional ingredients that modulate immune response through non-antibiotic pathways. This reorientation demands new formulation science and manufacturing capabilities.
Encapsulated butyrate salts are overtaking traditional acidifiers as the preferred gut health intervention in weaned piglet diets. European swine integrators have accelerated adoption since 2023. The technology is overtaking commodity organic acid blends by delivering targeted release in the distal intestine.
REACH-registered feed additive authorizations now require extended environmental fate studies for ionophore residues in manure. EFSA guidance tightens maximum inclusion thresholds for monensin and salinomycin across member states. Poultry layer operations in the Netherlands and Denmark face accelerated reformulation deadlines.
Integrated poultry processors now specify premix contracts tied to live-weight performance guarantees rather than ingredient inclusion rates. This transfers biological risk from grower to supplier. The model is most visible in Thailand's vertically integrated export sector.
Global Medicated Feed Additives Market Segmentation
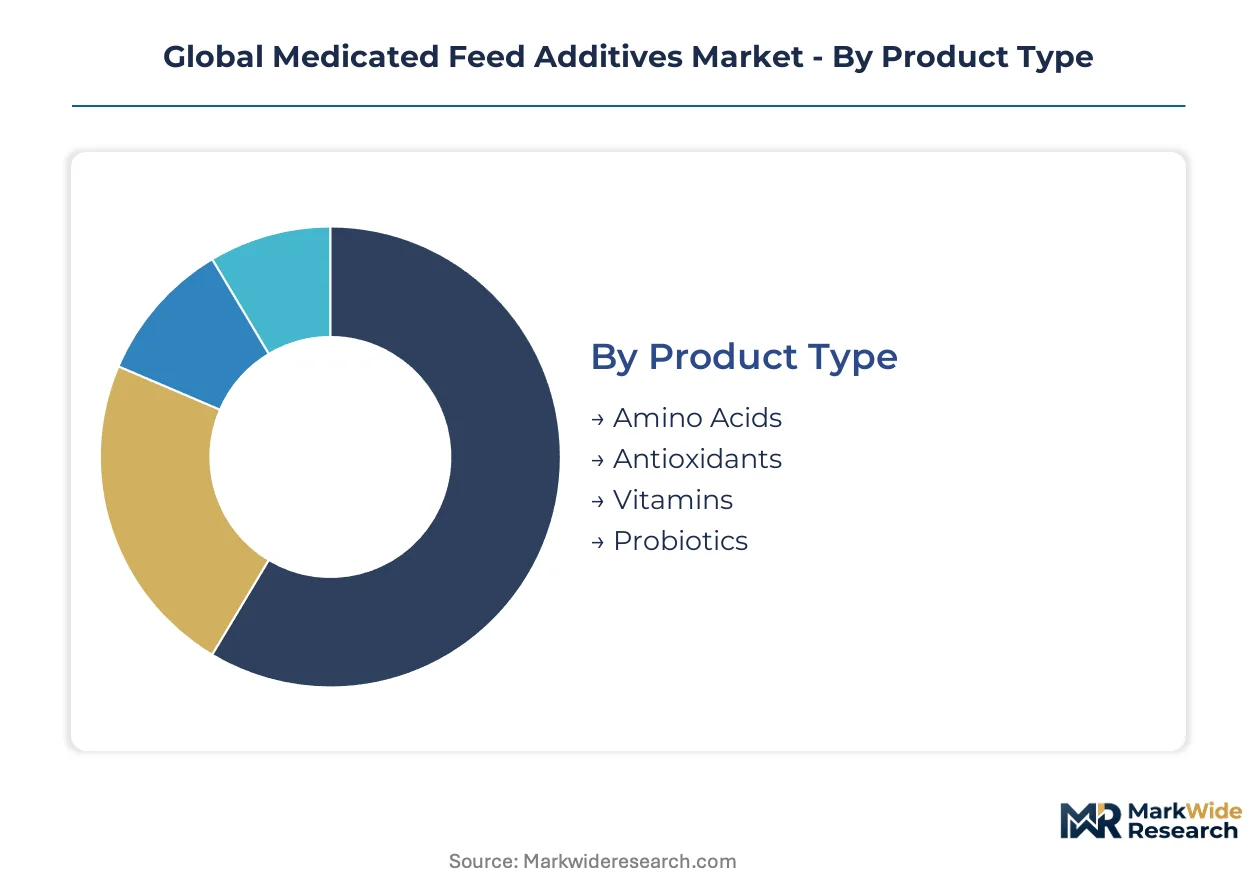
Medicated feed additive portfolios fragment across functional chemistry, species-specific formulation requirements, and channel access economics. Buyers prioritize different performance guarantees depending on their integration level and export market exposure.
Product Type:
Cost tier differentiation separates commodity amino acid buyers from premium probiotic adopters seeking antibiotic-free certification.
- Amino Acids:Crystalline L-lysine, L-threonine, and DL-methionine constitute the highest-volume inclusion category, with industrial swine and poultry operations in China and Brazil driving crystalline replacement of protein meals. Precision fermentation capacity expansions are compressing unit economics for standard-grade formulations.
- Probiotics:Direct-fed microbials including Bacillus subtilis, Lactobacillus, and Saccharomyces cerevisiae strains are expanding most quickly as EU Green Deal mandates and FDA Veterinary Feed Directive compliance reshape premix priorities across export-oriented integrators.
- Antioxidants:Ethoxyquin, BHT, and BHA formulations protect lipid stability in high-energy rations for intensive poultry systems.
- Vitamins:Fat-soluble and water-soluble premixes address deficiency correction in ruminant transition diets and aquaculture starter feeds.
Volume sits with amino acids; growth tilts toward probiotics.
End User:
Application intensity varies by species physiology and regulatory scrutiny of residue thresholds in destination markets.
- Poultry Farms:Broiler and layer operations consume the largest additive volumes per unit biomass, with coccidiostat and ionophore inclusion rates shaped by EFSA maximum residue limits and withdrawal period enforcement.
- Swine Producers:Post-weaning diarrhea management drives therapeutic premix demand, particularly in China's industrial restocking phase and Vietnam's expanding commercial sector.
- Ruminant Feeders:Dairy intensification in India and beef feedlot expansion in Argentina pull ionophore and buffer inclusion for acidosis prevention.
- Aquaculture:Shrimp and salmon producers in Vietnam, Indonesia, and Norway require species-specific immunomodulator formulations with stricter environmental fate profiles.
Revenue concentrates in poultry; margin expansion favors aquaculture.
Component:
Margin structure separates patent-protected medicinal actives from commodity nutritional substrates and formulation excipients.
- Medicinal Ingredients:Ionophores, synthetic coccidiostats, and anthelmintics command formulation premiums through veterinary prescription requirements and restricted distribution channels.
- Nutritional Substances:Trace minerals, macro-minerals, and vitamin premixes compete on homogeneous dispersion technology and stability under pelleting heat stress.
- Flavoring Agents:Palatability enhancers including sweeteners and umami compounds address feed refusal in medicated rations with bitter active pharmaceutical ingredients.
- Fillers:Carriers and diluents ensure precise micro-dosing distribution, with silica and calcium carbonate grades selected for flowability and electrostatic control.
Margin pools concentrate in medicinal ingredients; volume throughput dominates nutritional substances.
Distribution Channel:
Customer scale and technical service requirements determine channel selection, with large integrators bypassing intermediaries.
- Direct Sales:Vertically integrated poultry and swine operations in Thailand and Brazil negotiate premix contracts tied to live-weight performance guarantees rather than ingredient inclusion specifications.
- Distributors:Regional veterinary and feed supply networks dominate channel economics across fragmented livestock sectors in Mexico, Poland, and Indonesia.
- Online Platforms:E-procurement penetration remains limited to standard nutritional additives, with prescription medicinal ingredients excluded from digital commerce under FDA and EMA veterinary oversight frameworks.
- Retail Outlets:Farm supply cooperatives and independent merchants serve smallholder dairy and backyard poultry operations with pre-formulated mineral packs and vitamin premixes.
Contract value concentrates in direct sales; reach expansion favors distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors the densest concentration of industrial swine operations, with feed mills clustering around Foshan and Jiangmen to serve restocking demand following disease cycles. Veterinary-grade probiotic facilities are expanding capacity in this corridor to meet NMPA compliance requirements.
United States
Midwestern feedlots in Iowa and Nebraska drive ionophore premix consumption for beef cattle acidosis management. FDA Veterinary Feed Directive enforcement tightens veterinary oversight for medically important antimicrobials. Kansas City processors negotiate performance-based premix contracts tied to live-weight outcomes rather than ingredient specifications.
Brazil
São Paulo state integrators scale antibiotic-free broiler production to maintain EU export certification. ANVISA aligns with EFSA residue standards for maximum inclusion thresholds. Paraná feed mills retrofit pelleting lines to accommodate heat-sensitive microbial additives for probiotic formulations.
Germany
Lower Saxony's intensive piglet operations accelerate encapsulated butyrate adoption for post-weaning gut health. EU Green Deal farm-to-fork mandates enforce binding antimicrobial reduction targets. Bavarian compounders reformulate coccidiostat portfolios ahead of EFSA's tightened monensin withdrawal deadlines.
India
Gujarat and Punjab dairy cooperatives modernize calf starter programs with first-time medicated premix demand. FSSAI and state veterinary departments enforce GB-standard alignment for imported veterinary drug premixes. Karnal's feed manufacturing corridor attracts regional distributors for transition cow mineral formulations.
Netherlands
North Brabant poultry layer operations face accelerated ionophore phase-out under REACH-registered feed additive environmental fate requirements. ECHA and EFSA jointly evaluate manure residue thresholds for monensin and salinomycin. Venlo's feed technology cluster develops precision delivery systems for alternative gut health interventions.
Global Medicated Feed Additives Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory compliance capabilities. The vendor base stratifies between multinational pharmaceutical-animal health hybrids and regional feed compounders with limited species-specific expertise. Three archetypes dominate: patent-protected ionophore developers, precision fermentation amino acid specialists, and vertically integrated feed mill operators with captive premix capacity. Competitive moves concentrate on antimicrobial-alternative pipeline acquisitions and heat-stable microbial formulation technology licensing.
Within the pharmaceutical-animal health tier, Elanco Animal Health Incorporated and Zoetis Inc. occupy positions defined by species-specific immunomodulator development and veterinary distribution channel control. Evonik Industries AG anchors the precision fermentation segment for crystalline amino acid supply. Cargill, Incorporated exemplifies the integrated agribusiness archetype with backward control over feed mill networks and direct sales to large-scale poultry and swine integrators.
| Leading Market Players |
|---|
| Elanco Animal Health Incorporated |
| CHS Inc. |
| Cargill, Incorporated |
| Evonik Industries AG |
| Kemin Industries |
| Phibro Animal Health Corporation |
| Zoetis Inc. |
| Nutreco |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between antibiotic-free and conventional premix tiers shapes both margin capture and sourcing complexity across livestock integrator procurement. EU Green Deal compliance premiums and FDA Veterinary Feed Directive veterinary oversight requirements force distinct supply chain configurations for export-oriented versus domestic-only operations.
Pricing Analysis
Live-weight performance guarantees anchor value-based pricing for vertically integrated poultry and swine operations in Thailand and Brazil. Three-tier pricing structure across premium probiotic, standard amino acid, and economy mineral premix levels reflects certification status and heat-stability technology. Pricing pressure stems from precision fermentation cost compression in crystalline lysine supply. Smallholder dairy cooperatives in India exhibit highest price sensitivity; export-certified Brazilian integrators show lowest.
Supply Chain Analysis
Freight cost volatility from Chinese fermentation hubs to European compounders strains ionophore active ingredient economics. API manufacturing concentrates in China; precision fermentation capacity clusters in Germany and the US; feed mill integration dominates Brazil and Thailand. Raw material dependencies include corn-derived dextrose carriers, pharmaceutical-grade excipients, and heat-stable microbial strains. Single-source vulnerability runs through Chinese ionophore export license protocols. Distribution runs through veterinary prescription channels for medicinal ingredients and direct mill delivery for nutritional substrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Livestock nutrition is transitioning from pharmaceutical dependence toward functional gut health modulation, with encapsulated butyrate and direct-fed microbials displacing sub-therapeutic antibiotics under tightening residue regulations.
For Market Incumbents: Cement antimicrobial-alternative pipeline leadership through precision fermentation scale-up in amino acids and heat-stable probiotic formulation licensing. Elanco and Zoetis face substitution pressure from phytogenic essential oil blends; defensive investment in encapsulated delivery technology and veterinary distribution channel control protects margin pools in ionophore-dependent poultry operations. For New Entrants and Emerging Players: India's cooperative dairy sector offers first-time medicated calf starter demand with limited incumbent penetration. White-space targets include transition cow mineral formulations for Punjab's intensifying operations and probiotic premixes for Vietnam's expanding commercial swine sector. Go-to-market through regional veterinary distributor partnerships bypasses capital-intensive feed mill integration. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation specialists given biosynthesis platform leverage across amino acid and probiotic categories. Long-term viability favors companies with backward integration into heat-stable microbial strain libraries. Watch EFSA monensin withdrawal timeline acceleration as inflection signal for ionophore-dependent revenue exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Biosynthesis platforms cut L-lysine production costs, expanding inclusion rates in cost-sensitive Brazilian and Chinese rations. |
| Heat-Stable Probiotic Formulation Licensing | Pelleting temperature retrofits enable microbial additive adoption across EU antibiotic-free certification programs. |
| Veterinary Distribution Channel Control | Prescription-required ionophore premixes lock in margin pools through restricted access networks in Germany and the US. |
| Encapsulated Delivery Technology Investment | Targeted-release butyrate salts displace commodity acidifiers in post-weaning piglet diets across Lower Saxony operations. |
| Performance-Based Contract Structuring | Live-weight guarantees transfer biological risk from Thai poultry growers to premix suppliers, deepening integrator lock-in. |
Study Parameters
Multi-period observation of antimicrobial stewardship program implementation, probiotic adoption curves, and feed mill integration patterns anchored the trend analysis, supplemented by interviews with veterinary pharmaceutical executives, feed compounder procurement leads, livestock integrator nutritionists, and regulatory affairs specialists at EMA and FDA. Secondary validation drew from FDA Veterinary Feed Directive enforcement records, EFSA maximum residue limit guidance, Chinese NMPA GB standard filings, and customs trade data for ionophore active ingredient flows. Bottom-up premix volume estimates triangulated against top-down livestock production forecasts.
Segment-weighting approaches modeled product type, species application, component chemistry, and distribution channel access economics across the projection horizon. CAGRs derived from regression analysis of historical inclusion rate shifts and regulatory phase-out timelines. Industry-specific forecast inputs included EU Green Deal farm-to-fork mandate compliance deadlines and China's industrial swine restocking velocity post-disease cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA ionophore withdrawal acceleration, Chinese API export license volatility, and precision fermentation cost curve steepness. Forecasts reflect documented assumptions about regulatory timeline adherence and livestock production recovery trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Strobilurin Fungicide Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Agricultural Antibacterials Market