
 Soil Sterilizers Market | 2026-2036
Soil Sterilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Sterilizers Market Intelligence
Agricultural equipment technician shortages across major farming regions is reorganizing how soil sterilizer manufacturers structure service networks and aftermarket support. Meyer Industries leverages its established dealer infrastructure to sustain field-level technical coverage in North American row-crop zones. Egedal Maskinfabrik anchors Scandinavian greenhouse markets through specialized steam sterilizer fabrication. KlasmannDeilmann differentiates by controlling substrate formulation and sterilization as integrated horticultural supply operations.
Soil sterilizers are engineered systems and chemical formulations designed to eliminate pathogens, nematodes, weed seeds, and pest organisms from soil media through thermal, chemical, or biological action, typically operating at temperatures between 60°C and 100°C for steam-based units or utilizing fumigant concentrations measured in parts per million. These systems serve commercial agriculture, protected horticulture, and research institutions requiring biosecure growing media. Thermal sterilizers occupy the largest installed base due to proven efficacy against soil-borne diseases, while vapor heat sterilizers represent the fastest-growing category as greenhouse operators seek alternatives to restricted chemical fumigants. Chemical sterilizer margins concentrate in proprietary formulation patents, whereas biological sterilizer growth depends on microbial strain registration speed with national agricultural regulators.
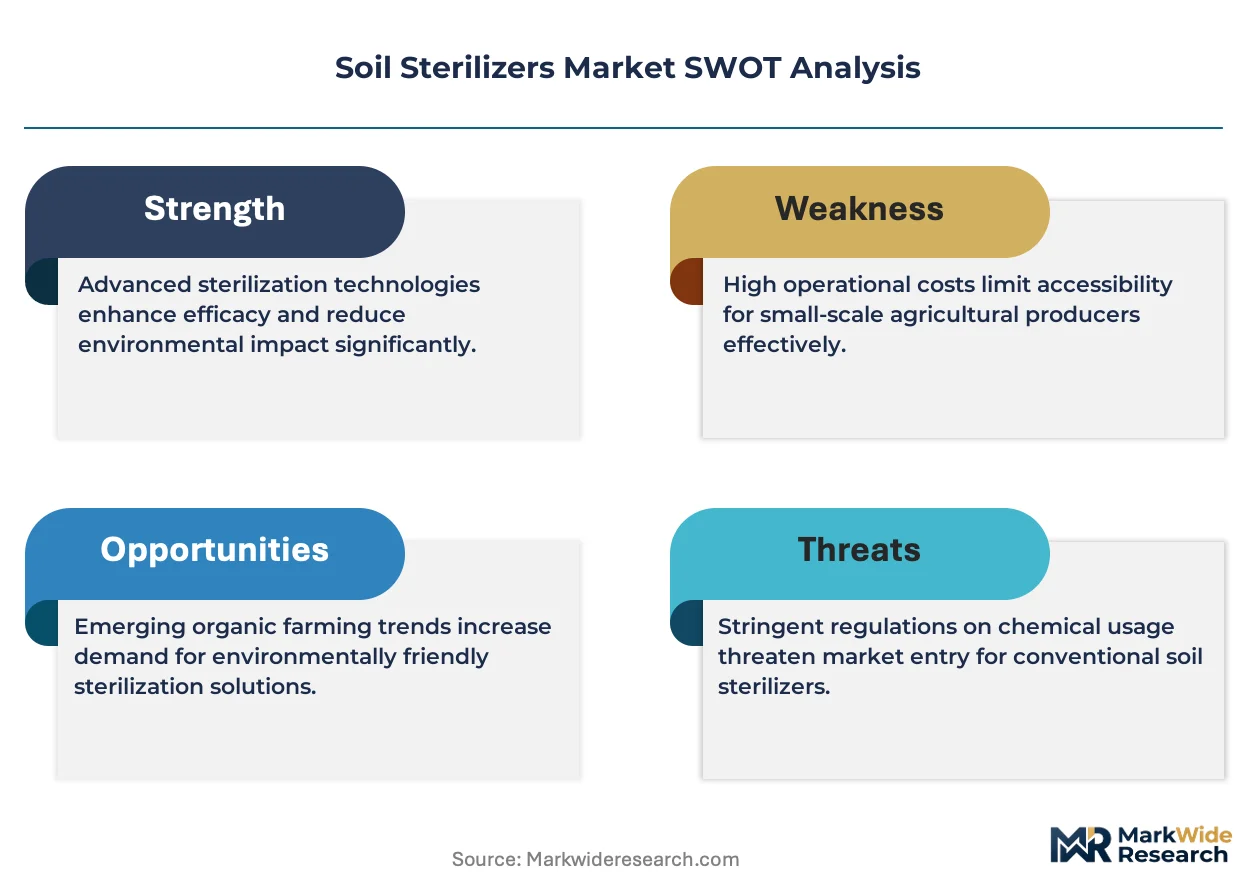
The US EPA regulates soil fumigant registration and buffer zone requirements under FIFRA, directly constraining chemical sterilizer application windows and pushing adoption toward steam and biological alternatives. EU REACH compliance and the F-Gas Regulation phase-down schedule are reshaping product portfolios for manufacturers serving European horticultural markets. California's Department of Pesticide Regulation maintains additional state-level restrictions on methyl iodide and chloropicrin that exceed federal stringency. Stakeholders must monitor evolving national buffer zone calculations and emerging microbial strain approval pathways to align R&D portfolios with regulatory trajectory.
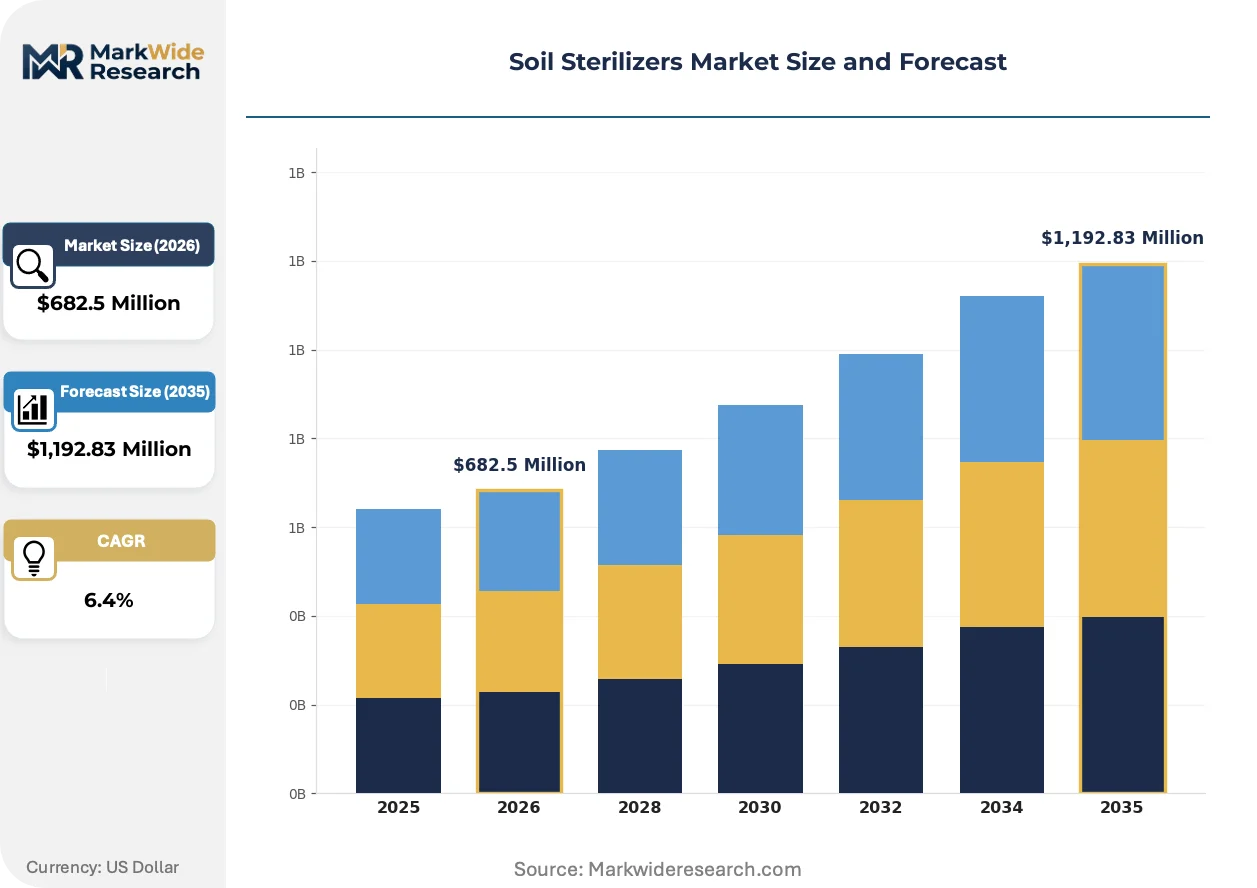
Market Dynamics
The methyl bromide phase-out under the Montreal Protocol is compressing chemical fumigant availability and redirecting capital toward steam infrastructure and microbial biopesticide development across protected horticulture sectors.
Growth Catalysts
- Montreal Protocol Compliance Deadlines:California's Department of Pesticide Regulation enforces accelerated methyl bromide phase-out timelines, forcing Central Valley specialty crop growers to convert existing fumigation infrastructure to steam-based thermal systems.
- EU F-Gas Regulation Phase-Down:Netherlands greenhouse operators face tightening synthetic fumigant quotas, accelerating biological sterilizer adoption through microbial strain portfolios registered with national agricultural regulators.
- Soil-Borne Pathogen Pressure:Protected vegetable cultivation expansion in Mediterranean climates intensifies demand for reliable nematode and fungal elimination without harvest interval restrictions.
Market Restraints
- Natural Gas Price Volatility:Steam sterilizer operating costs fluctuate with regional energy markets, compressing margins for continuous-operation greenhouse facilities in Northern Europe.
- Specialized Equipment Fabrication Concentration:Scandinavian steam sterilizer manufacturing capacity limits rapid fleet expansion for North American row-crop conversion programs.
- Microbial Strain Registration Timelines:Biological sterilizer commercialization faces multi-year approval pathways with EPA and EFSA, delaying product pipeline conversion from R&D to revenue.
Strategic Opportunities
- Sub-Saharan Protected Horticulture Expansion:Kenya and Ethiopia flower export sectors present underpenetrated demand for mobile steam sterilization units serving contract farming networks.
- Precision Steam Injection Convergence:Integration of soil moisture sensing with variable-rate steam application enables dosage optimization previously unavailable in blanket fumigation approaches.
- USDA Organic Certification Pathways:Biological sterilizer formulations meeting National Organic Program standards capture premium positioning in domestic fresh produce supply chains.
Industry Challenges
- Agricultural Equipment Technician Scarcity:Field-level steam sterilizer maintenance and calibration expertise concentrates in legacy dealer networks, constraining aftermarket service coverage expansion.
- Legacy Fumigation Infrastructure Stranded Assets:Row-crop operations face capital write-downs on chemical application equipment with limited secondary market liquidity during technology transition.
- Cross-Jurisdictional Strain Approval Complexity:Biological sterilizer manufacturers navigate divergent microbial registration requirements between EPA, EFSA, and OECD-member national regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Sterilizers Market |
| Market Size in 2026 | $682.5 Million |
| Market Size in 2035 | $1,192.83 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Sterilizers, Thermal Sterilizers, Biological Sterilizers, Vapor Heat Sterilizers Application: Agricultural Soil, Horticultural Soil, Organic Farming, Research Facilities Delivery Mode: Liquid Formulation, Granular Formulation, Gas Formulation, Powder Formulation Technology: Solarization, Steam Treatment, Chemical Fumigation, Microwave Treatment |
| Companies Covered | Meyer Industries, Steamericas, CM Regero Industries, Egedal Maskinfabrik, Ferrari Costruzioni Meccaniche, Potveer Sierteeltmachines, Alvan Blanch, VaporTech International, KlasmannDeilmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Sterilizers Market Strategic Shifts & Innovations
Steam-based thermal sterilization is decomposing the historical dominance of chemical fumigation through precision application technologies that reduce energy intensity while maintaining pathogen elimination efficacy.
Electromagnetic soil heating systems are decomposing conventional boiler-steam architectures by enabling targeted pathogen zone treatment without bulk soil temperature elevation. Dutch greenhouse operators pilot radio-frequency and microwave units for substrate-specific nematode elimination. The technology is decomposing capital barriers to sterilization adoption for mid-scale protected horticulture facilities previously priced out of steam infrastructure.
EPA buffer zone recalculations under FIFRA are compressing chemical fumigant application windows in densely populated agricultural counties. California's Department of Pesticide Regulation maintains state-specific chloropicrin restrictions exceeding federal baselines. Greenhouse operators in Ventura and Monterey counties accelerate steam sterilizer procurement to eliminate seasonal application uncertainty.
After-sales service unbundling is fragmenting traditional equipment procurement models as buyers separate sterilizer acquisition from technical support contracts. Independent agricultural equipment service providers in Florida and Arizona capture maintenance revenue previously retained by manufacturer-dealer networks. Specialty crop growers in desert production regions prioritize flexible service arrangements over bundled OEM support packages.
Soil Sterilizers Market Segmentation
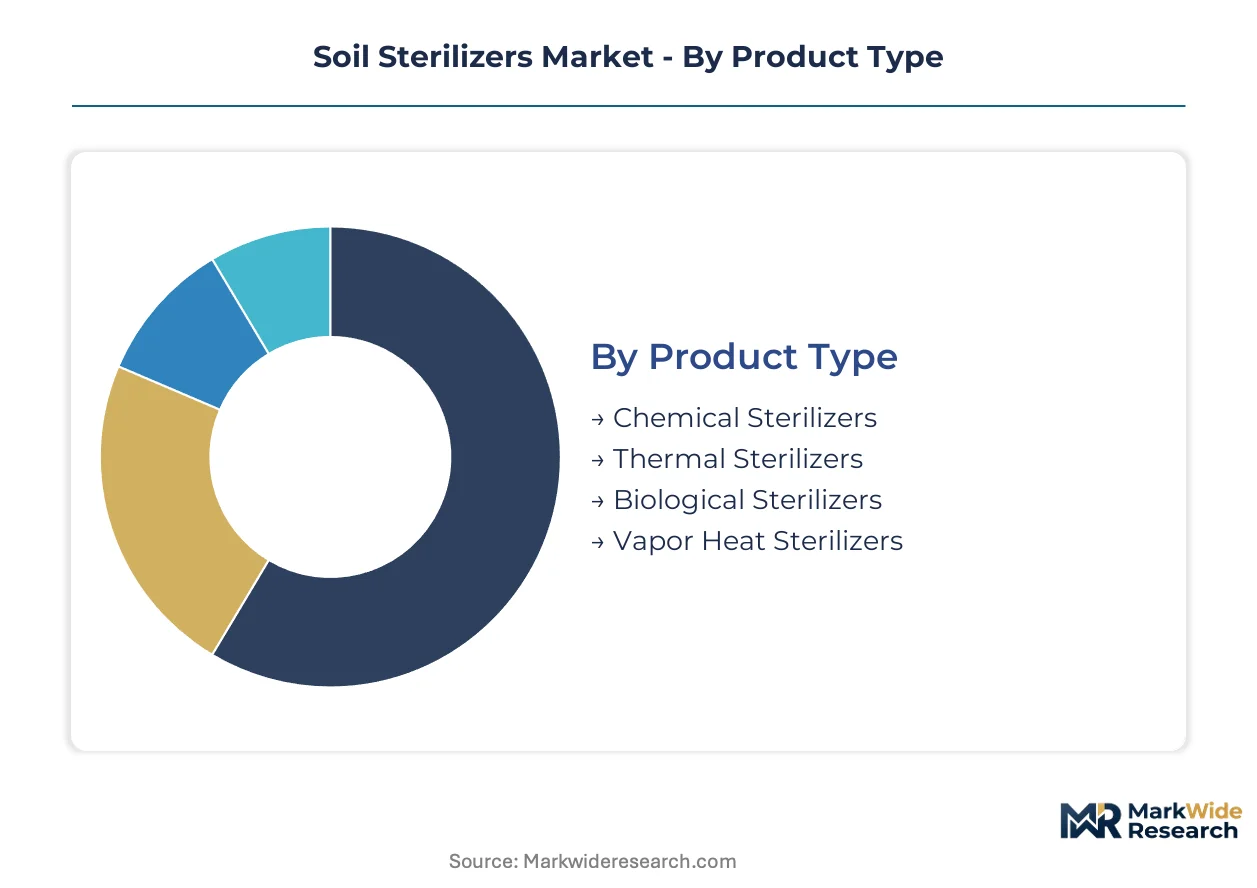
Soil sterilizer procurement patterns diverge sharply across product architectures, end-use environments, and regulatory exposure profiles. Buyers segment investments based on energy infrastructure access, pathogen pressure intensity, and compliance deadlines governing legacy fumigant phase-outs.
Product Type:
Margin pools concentrate in proprietary chemical formulations with extended patent protection, while thermal systems generate recurring revenue through service contracts and consumable replacement cycles.
- Thermal Sterilizers:Boiler-fed steam systems operating between 60°C and 100°C eliminate soil-borne pathogens through sustained heat exposure. California Central Valley specialty crop growers dominate procurement as methyl bromide phase-out deadlines under the Montreal Protocol force infrastructure conversion.
- Chemical Sterilizers:Synthetic fumigant formulations including chloropicrin and metam sodium deliver nematode control through vapor-phase distribution. EPA buffer zone recalculations under FIFRA compress application windows in densely populated agricultural counties, constraining revenue stability.
- Biological Sterilizers:Microbial biopesticide preparations containing registered bacterial and fungal antagonists colonize soil to outcompete pathogens. Netherlands greenhouse operators drive uptake as EU F-Gas Regulation quotas tighten synthetic fumigant availability.
- Vapor Heat Sterilizers:Closed-system steam injection units recover and recirculate thermal energy for substrate-specific treatment. Mid-scale protected horticulture facilities in Mediterranean climates adopt these systems to bypass capital barriers of conventional boiler infrastructure.
The dominant share belongs to Thermal Sterilizers, while Biological Sterilizers are expanding most quickly as regulatory pressure on synthetic chemistry intensifies.
Application:
Volume concentration tracks protected cultivation expansion, with horticultural environments commanding premium pricing due to zero-tolerance pathogen standards for export-grade production.
- Horticultural Soil:Greenhouse and nursery operations require biosecure substrate for ornamental and vegetable propagation. Kenya and Ethiopia flower export sectors generate underpenetrated demand for mobile sterilization units serving contract farming networks.
- Agricultural Soil:Open-field row-crop production relies on pre-plant fumigation for nematode suppression in high-value specialty crops. Florida and Arizona desert production regions prioritize flexible service arrangements over bundled OEM support packages.
- Organic Farming:USDA National Organic Program certification restricts allowable inputs to non-synthetic biological and thermal methods. Premium positioning in domestic fresh produce supply chains rewards compliant sterilizer formulations.
- Research Facilities:University and institutional laboratories require standardized pathogen elimination for controlled experimentation. Stringent biosecurity protocols drive specification of validated thermal treatment cycles with documented temperature logs.
Horticultural Soil captures the largest revenue pool, though Agricultural Soil conversion programs are gaining share fastest as chemical fumigant restrictions spread.
Delivery Mode:
Formulation selection hinges on application equipment compatibility and soil moisture conditions at treatment time, with liquid systems dominating where injection infrastructure exists.
- Liquid Formulation:Aqueous solutions of fumigant or biological active ingredients distribute through drip irrigation or shank injection equipment. California's Department of Pesticide Regulation enforces state-specific chloropicrin restrictions exceeding federal baselines, redirecting formulation preferences.
- Gas Formulation:Volatilized methyl bromide alternatives including 1,3-dichloropropene permeate soil through tarp-sealed application. Montreal Protocol compliance deadlines compress availability, stranding legacy application equipment with limited secondary market liquidity.
- Granular Formulation:Slow-release pellets of biological inoculants or chemical actives incorporate during tillage operations. Organic farming certification pathways favor these preparations for mechanical compatibility with prohibited-equipment restrictions.
- Powder Formulation:Dry concentrates of microbial spores or chemical precursors require reconstitution prior to field application. Research facilities specify powder formats for precise dosage control in small-scale experimental plots.
Liquid Formulation retains the dominant position, while Gas Formulation is losing share most rapidly as regulatory phase-outs advance.
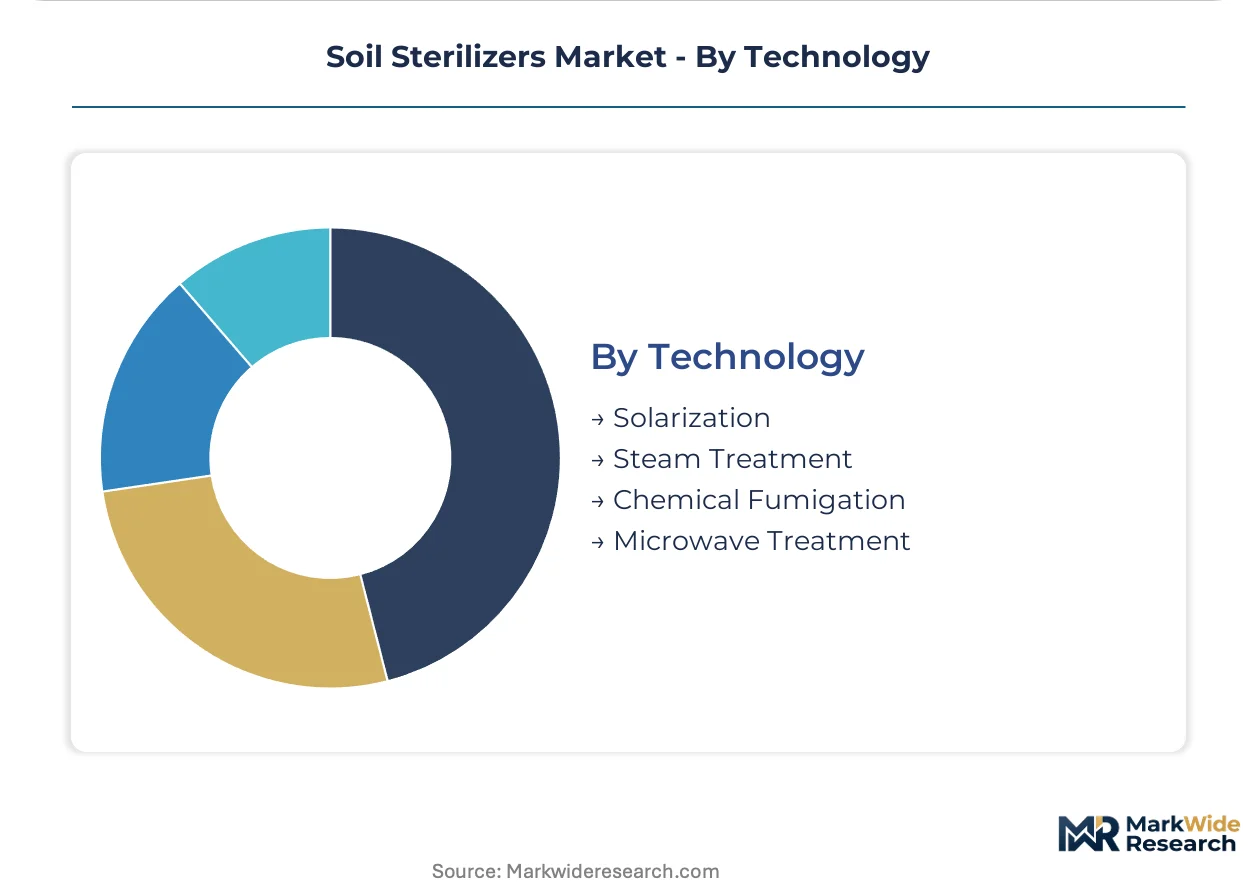
Technology:
Capital intensity and energy source availability determine technology selection, with electromagnetic methods decomposing traditional steam infrastructure requirements for mid-scale adopters.
- Steam Treatment:Conventional boiler-generated thermal energy raises bulk soil temperature to pathogen-lethal thresholds. Natural gas price volatility in Northern Europe compresses operating margins for continuous-operation greenhouse facilities.
- Chemical Fumigation:Synthetic biocide vapor distribution through soil profiles achieves broad-spectrum pest elimination. EPA and EFSA registration timelines for replacement chemistry extend multi-year approval pathways, delaying pipeline conversion.
- Solarization:Passive solar heating under transparent polyethylene tarps elevates soil temperature for extended periods. Mediterranean and desert production regions leverage abundant solar resources for zero-energy-cost pathogen suppression.
- Microwave Treatment:Radio-frequency and electromagnetic energy systems enable targeted pathogen zone treatment without bulk soil temperature elevation. Dutch greenhouse operators pilot these units for substrate-specific nematode elimination, decomposing capital barriers for mid-scale facilities.
Steam Treatment commands the largest installed base, though Microwave Treatment is climbing the fastest as precision application technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Netherlands exceeds that in California by a substantial margin, reflecting divergent regulatory enforcement timelines and energy infrastructure density across these horticultural centers.
United States
California Central Valley specialty crop growers dominate procurement as methyl bromide phase-out deadlines under the Montreal Protocol force infrastructure conversion. EPA buffer zone recalculations under FIFRA compress chemical fumigant application windows in densely populated agricultural counties. Ventura and Monterey counties accelerate steam sterilizer procurement to eliminate seasonal application uncertainty.
Netherlands
Greenhouse operators face tightening EU F-Gas Regulation quotas on synthetic fumigants, accelerating biological sterilizer adoption through microbial strain portfolios. National agricultural regulators register biological alternatives faster than EPA counterparts, shortening commercialization timelines. Westland municipality clusters drive precision steam injection convergence with soil moisture sensing integration.
Germany
Industrial boiler fabrication expertise supports steam sterilizer component supply chains serving Northern European greenhouse markets. REACH compliance requirements reshape product portfolios for manufacturers serving domestic horticultural operations. Bavaria's protected vegetable cultivation expansion intensifies demand for reliable nematode elimination without harvest interval restrictions.
Kenya
Flower export sectors present underpenetrated demand for mobile steam sterilization units serving contract farming networks. National agricultural regulators streamline microbial biopesticide registration to align with EU import phytosanitary standards. Naivasha and Thika growing clusters pilot solarization alternatives where grid electricity remains unreliable.
Italy
Mediterranean protected cultivation expansion drives vapor heat sterilizer adoption for mid-scale greenhouse facilities. National implementation of EU F-Gas Regulation phase-down schedules redirects capital from chemical fumigation toward thermal infrastructure. Sicily and Apulia horticultural zones concentrate procurement of closed-system steam injection units.
Soil Sterilizers Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with precision application innovators commanding premium positioning while scale fabricators capture volume share in conversion markets. The vendor base organizes around three strategic tiers: integrated horticultural supply operators controlling substrate formulation and sterilization as unified operations, specialized steam equipment fabricators anchored in regional greenhouse clusters, and diversified agricultural equipment manufacturers leveraging established dealer infrastructure for aftermarket coverage. Dominant competitive moves include backward integration into substrate production and geographic expansion through mobile sterilization service models.
Within the integrated supply tier, KlasmannDeilmann occupies a position exemplifying unified horticultural operations, while Egedal Maskinfabrik represents Scandinavian specialized fabrication. Among diversified equipment manufacturers, Meyer Industries exemplifies the dealer-network leverage archetype for field-level technical coverage.
| Leading Market Players |
|---|
| Meyer Industries |
| Steamericas |
| CM Regero Industries |
| Egedal Maskinfabrik |
| Ferrari Costruzioni Meccaniche |
| Potveer Sierteeltmachines |
| Alvan Blanch |
| VaporTech International |
| KlasmannDeilmann |
| Others |
Cost & Logistics Intelligence
Steam boiler systems displacing methyl bromide fumigation infrastructure simultaneously relocate supply geography toward Scandinavian fabrication centers and compress pricing power for legacy chemical formulation patents. California Central Valley growers facing Montreal Protocol deadlines absorb premium capital costs for thermal equipment while Netherlands greenhouse operators capture faster payback through EU F-Gas Regulation-driven biological sterilizer subsidies.
Pricing Analysis
Pricing spreads between Netherlands and California exceed substantial margins, reflecting divergent energy infrastructure density and regulatory enforcement timelines. Three-tier pricing structure across premium precision-steam, standard boiler-fed thermal, and economy solarization tiers differentiates by automation level and after-sales bundling. Cost compression in standard thermal tiers is intensifying because natural gas volatility erodes operating margins for continuous-operation facilities. Contract farming networks in Sub-Saharan Africa exhibit highest price sensitivity, while research institutions demonstrate lowest sensitivity due to biosecurity compliance mandates.
Supply Chain Analysis
Strategic stockpiling of boiler components dominates over just-in-time preferences due to Scandinavian fabrication capacity constraints and extended lead times for specialized pressure vessels. Manufacturing concentrates in Denmark, Germany, and the Netherlands, drawing from stainless steel sheet, industrial burner assemblies, and precision control sensors. Single-source vulnerability concentrates in high-pressure boiler fabrication where Egedal Maskinfabrik anchors regional capacity. Distribution runs through agricultural equipment dealer networks with aftermarket service unbundling fragmenting traditional procurement models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil sterilizer procurement is shifting toward platform economics as precision steam injection converges with soil moisture sensing and variable-rate application algorithms, creating interoperability standards that favor ecosystem orchestrators over standalone equipment vendors.
For Market Incumbents: Compound dealer network density in North American row-crop zones to defend against independent service provider fragmentation. Backward integration into substrate formulation captures margin pools from unified horticultural supply operations. Priority investment in EPA microbial strain registration fast-tracks accelerates biological sterilizer pipeline conversion against multi-year approval delays.
For New Entrants and Emerging Players: USDA National Organic Program certification fast-track unlocks premium positioning in domestic fresh produce supply chains with minimal incumbent saturation. Kenya and Ethiopia flower export sectors present most penetrable demand for mobile sterilization units serving contract farming networks. Go-to-market execution through equipment-as-a-service models bypasses capital barriers for mid-scale protected horticulture facilities.
For Investors and Strategic Acquirers: Capital is best deployed toward precision application technology specialists with validated electromagnetic heating prototypes and established pilot deployments with Dutch greenhouse operators. Long-term viability centers on regulatory arbitrage capabilities navigating divergent EPA, EFSA, and OECD microbial registration pathways. Signal to monitor is EPA buffer zone recalculation velocity under FIFRA compressing chemical fumigant application windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Steam Injection Convergence | Integration with soil moisture sensing enables dosage optimization previously unavailable in blanket fumigation. |
| Microbial Strain Registration Fast-Track | Accelerated EPA and EFSA approval pathways compress multi-year biological sterilizer commercialization timelines. |
| Mobile Sterilization Service Model | Equipment-as-a-service penetration in Sub-Saharan contract farming networks bypasses capital barriers. |
| Backward Integration into Substrate | Unified control over formulation and sterilization captures margin pools from fragmented supply chains. |
| Electromagnetic Heating Pilot Expansion | Radio-frequency and microwave substrate treatment decomposes boiler infrastructure requirements for mid-scale adopters. |
Research Approach
A spread of perspectives from greenhouse operations managers, agricultural equipment procurement leads, EPA regulatory affairs specialists, and aftermarket service technicians converged on the working assumptions governing steam sterilizer adoption trajectories. Primary fieldwork combined structured interviews with secondary validation through USDA organic certification databases, EPA pesticide registration filings, EU F-Gas Regulation implementation reports, and customs trade data on boiler component imports. Bottom-up equipment procurement modeling and top-down horticultural sector expenditure analysis triangulated volume and value estimates.
Segmentation dimensions modeled span product architecture, application environment, delivery mode formulation, and treatment technology across the projection horizon. CAGRs derive from regression analysis against methyl bromide phase-out compliance deadlines and EU F-Gas Regulation quota schedules. Industry-specific forecast inputs include natural gas price volatility indices for Northern European greenhouse operations and microbial strain registration velocity differentials between EPA and EFSA jurisdictions.
Underlying assumptions cover regulatory phase-out adherence timelines and energy infrastructure availability, with deviation risk concentrated in multi-year biological sterilizer approval delays and Scandinavian fabrication capacity constraints. Revision becomes warranted when EPA buffer zone recalculation velocity or EU F-Gas Regulation enforcement intensity crosses thresholds that materially alter chemical fumigant application economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
US Herbicide Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
South America Molluscicides Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
South America Nematicides Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
US Pest Control Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Grain and Cereal Crop Protection Market