
 South America Molluscicides Market | 2026-2036
South America Molluscicides Market Size, Share, and Industry Trends Forecast 2026-2036
South America Molluscicides Market Analytics
Biological formulation technology is tilting molluscicide development away from synthetic metaldehyde bases toward microencapsulated and bait-matrix innovations that improve rainfastness and target specificity. Bayer Crop Science leverages its crop protection R&D infrastructure to sustain integrated pest management portfolios spanning the Southern Cone. Syngenta Group anchors its regional position through distribution partnerships with Brazilian agricultural cooperatives. BASF SE differentiates via ferric phosphate formulations positioned for ANVISA-compliant replacement cycles.
Molluscicides are chemical or biological agents formulated to kill or repel gastropod pests, typically delivered as pelletized baits containing active concentrations of metaldehyde, ferric phosphate, or sodium niclosamide designed to disrupt mucus production or induce desiccation upon ingestion, primarily protecting yield-bearing crops and aquaculture infrastructure from feeding damage. Metaldehyde retains volume leadership across South America despite regulatory headwinds, while natural molluscicides represent the fastest-expanding category as organic-certified farming acreage climbs in Argentina's Pampas and Brazil's Minas Gerais coffee zones. Agricultural applications dominate value capture, though aquaculture operators in Chile and Ecuador generate concentrated margin pools through specialized pond-management contracts.
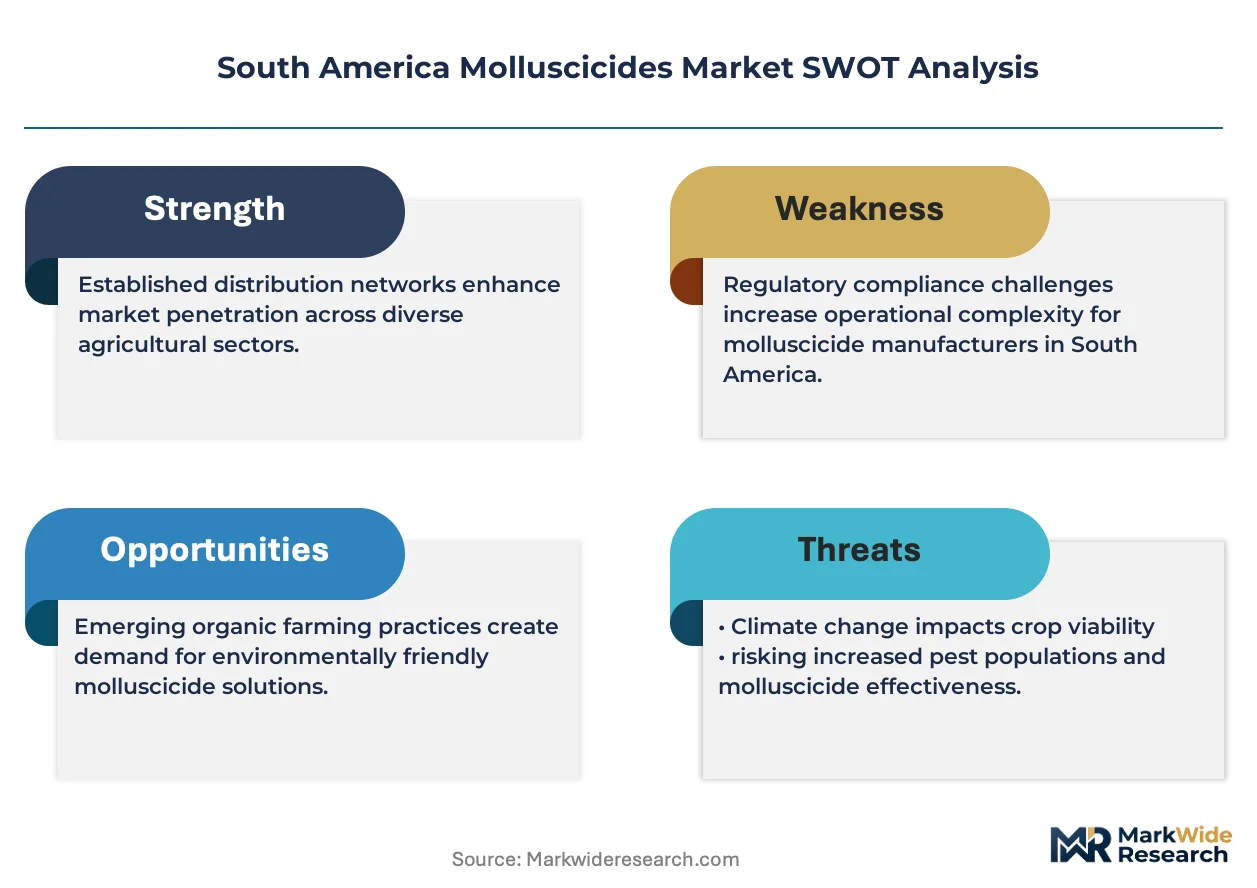
Brazil's ANVISA governs active ingredient re-registration and residue limits under Law 7.802, while Argentina's SENASA administers equivalent agrochemical import and formulation standards through Resolution 369. These frameworks restrict metaldehyde availability and elevate compliance costs for imported formulated products, directly reshaping manufacturer portfolio priorities and local registration strategies. Stakeholders must monitor pending regulatory determinations on ferric phosphate maximum residue levels and emerging state-level restrictions in Rio Grande do Sul and Santa Catarina to anticipate product substitution timelines and reformulation investment requirements.
Market Dynamics
Brazil's ANVISA re-registration protocols for metaldehyde-based formulations are compressing product lifecycles and forcing rapid portfolio transitions toward ferric phosphate alternatives across the Southern Cone.
Growth Catalysts
- No-till farming expansion:Soybean and corn producers in Brazil's southern states are adopting zero-tillage systems that preserve soil moisture and create ideal gastropod habitats, necessitating systematic molluscicide application protocols.
- Organic certification mandates:Argentina's SENASA has accelerated approval pathways for biological molluscicides, enabling copper-based and iron phosphate formulations to penetrate certified organic operations in Buenos Aires and Córdoba provinces.
- Aquaculture infrastructure investment:Chilean salmon and trout producers are deploying pond-specific molluscicide treatments to control snail vectors of parasitic flukes, generating specialized demand for sodium niclosamide formulations.
Market Restraints
- Active ingredient concentration risk:Brazil's ANVISA residue limit revisions under Law 7.802 threaten metaldehyde availability and elevate reformulation costs for legacy product portfolios.
- Import dependency for formulated baits:Argentina and Chile lack domestic production of microencapsulated pellet technologies, creating supply vulnerability concentrated in European and Asian contract manufacturers.
- Rainfastness limitations:Conventional metaldehyde formulations degrade rapidly under subtropical precipitation patterns in Rio Grande do Sul and Santa Catarina, reducing field efficacy and requiring reapplication.
Strategic Opportunities
- Underpenetrated coffee zones:Minas Gerais and São Paulo state coffee cooperatives represent untapped demand for ferric phosphate applications targeting slug damage in shaded plantation systems.
- Distribution partnership models:Direct contracting with Brazilian agricultural cooperatives in Paraná and Rio Grande do Sul bypasses traditional agrochemical distributor margins and secures volume commitments.
- Biological formulation convergence:Integration of entomopathogenic nematodes with iron phosphate matrices creates dual-action products eligible for premium organic certification premiums.
Industry Challenges
- Registration timeline compression:ANVISA's accelerated re-evaluation schedule demands toxicology dossier resubmission within 18-month windows, straining regulatory affairs capacity at smaller formulators.
- Field efficacy validation protocols:Rainfastness testing under controlled subtropical conditions requires specialized trial infrastructure that few regional research stations can replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Molluscicides Market |
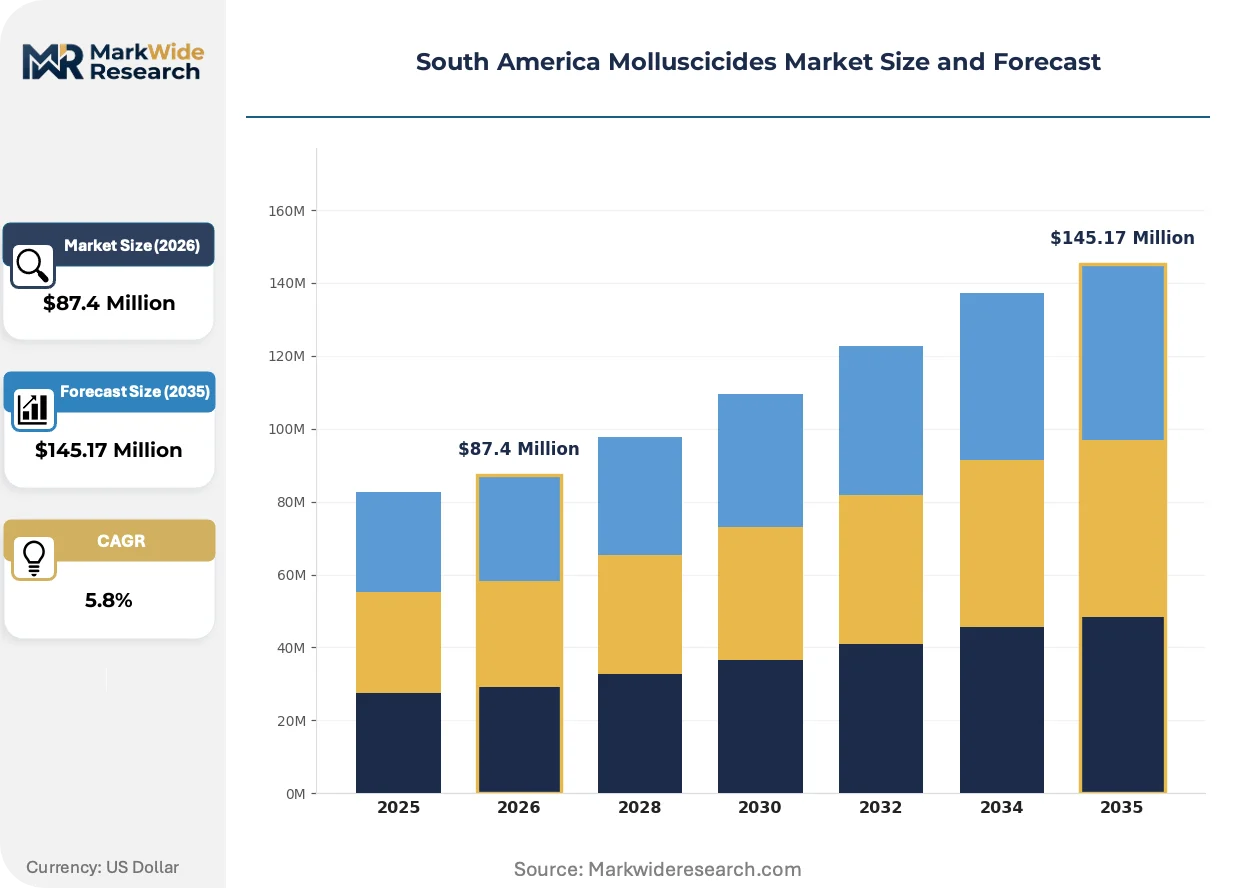
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $145.17 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metaldehyde, Ferric Phosphate, Sodium Niclosamide, Natural Molluscicides Application: Agriculture, Aquaculture, Public Health, Landscaping End User: Farmers, Aquaculture Operators, Municipalities, Landscaping Companies Distribution Channel: Online Retail, Specialty Stores, Agricultural Supply Stores, Distributors |
| Companies Covered | DE SANGOSSE, Rizobacter S.A., Bayer Crop Science AG, Huagro, Bequisa, Lonza Cologne GmbH, Acay, BASF SE, Syngenta Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Molluscicides Market Evolving Landscape
Formulation chemistry and application methodology are converging to address the tension between regulatory compliance and field performance under high-rainfall subtropical conditions.
Microencapsulated ferric phosphate matrices are collapsing the performance gap with synthetic alternatives. Brazilian soybean cooperatives in Paraná and Santa Catarina are adopting these formulations at scale for no-till corn-soy rotations. The technology is collapsing reapplication frequency requirements and enabling compliance with ANVISA's tightening residue protocols without yield sacrifice.
ANVISA's phased metaldehyde restriction schedule under Resolution RDC 293 is systematically removing neurotoxic actives from the Brazilian market. Formulators must complete ferric phosphate substitution by 2027 or surrender registration certificates. Southern soybean belt distributors are front-loading inventory transitions to avoid supply discontinuities during peak planting windows.
Cooperative procurement consolidation is compressing supplier negotiation cycles. Large Brazilian agricultural cooperatives in Rio Grande do Sul now contract molluscicide supply through multi-season framework agreements that displace spot purchasing through traditional agrochemical retailers. This pattern is most visible in the southern soybean belt where cooperative membership density exceeds 70 percent of farmed acreage.
South America Molluscicides Market Segmentation
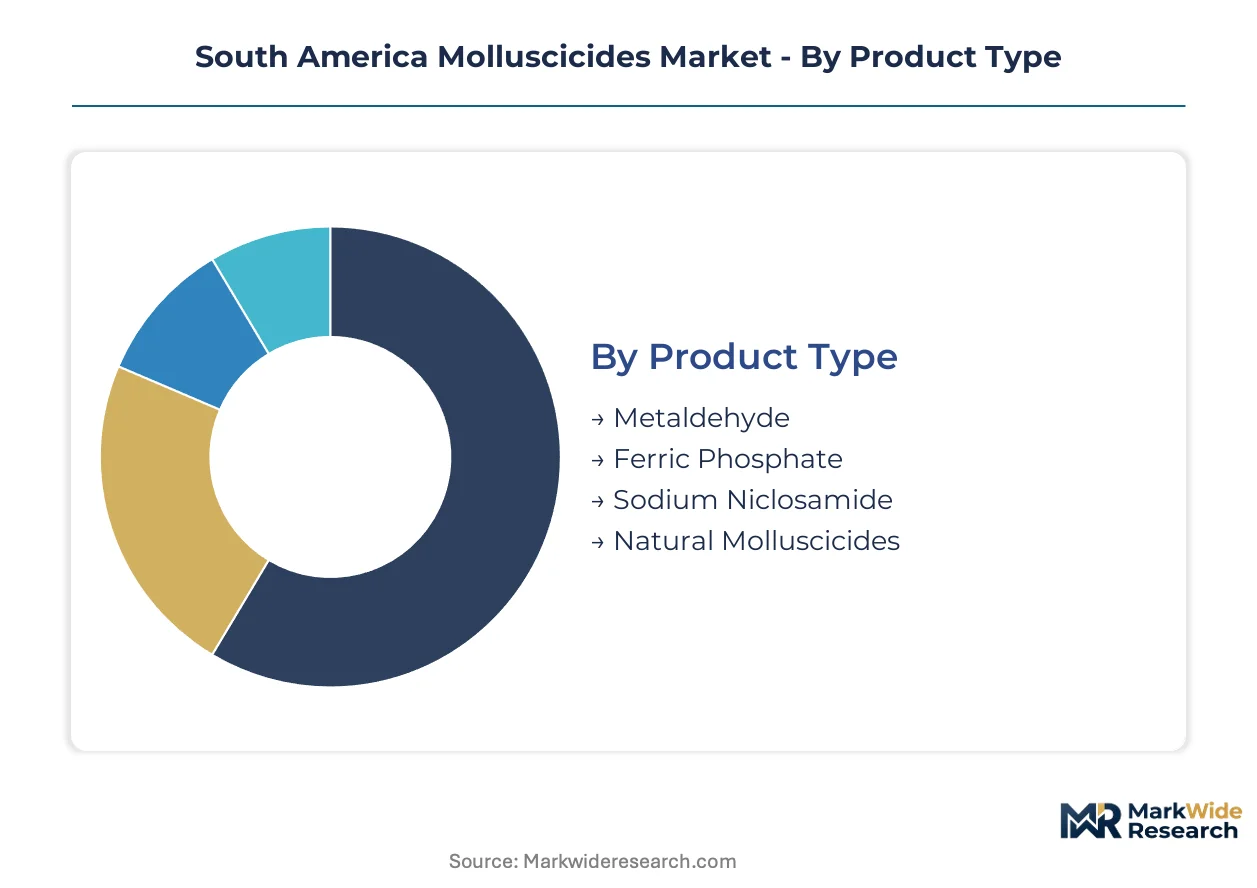
Molluscicide purchasing patterns across South America diverge sharply by user sophistication and application scale, with after-sales technical support intensity varying from intensive field advisory for cooperative farmers to minimal service for municipal procurement. Segmentation clarity enables suppliers to align formulation portfolios with distinct compliance requirements and reapplication protocols.
Product Type:
Technical consultation intensity peaks with metaldehyde transitions, where distributors must guide farmers through ANVISA-compliant substitution timelines and residue management protocols.
- Metaldehyde:Neurotoxic active ingredient formulated in pelletized baits that disrupt gastropod mucus production upon ingestion. Demand concentrates in Brazil's southern soybean belt where legacy product stocks sustain volume through transition periods, though ANVISA's phased restriction schedule compresses remaining commercial lifespan.
- Ferric Phosphate:Iron-based compound inducing desiccation through mucus disruption, formulated in rainfast microencapsulated matrices. Brazilian no-till corn and soybean operations in Paraná and Rio Grande do Sul are adopting these formulations fastest as cooperative procurement consolidates around ANVISA-compliant alternatives.
- Sodium Niclosamide:Molluscicidal compound deployed in aquaculture pond management for parasitic fluke vector control.
- Natural Molluscicides:Biological and plant-derived formulations including copper-based and entomopathogenic nematode combinations.
By volume, metaldehyde retains leadership. By growth pace, ferric phosphate formulations are expanding most quickly.
Application:
Margin profiles vary substantially across application domains, with aquaculture commanding premium pricing for specialized pond-management contracts while agricultural volumes drive overall revenue scale.
- Agriculture:Crop protection applications spanning soybean, corn, coffee, and horticultural production systems. Brazil's southern states dominate demand intensity where humid subtropical conditions and no-till farming sustain elevated gastropod pressure through extended growing seasons.
- Aquaculture:Pond and tank treatments targeting snail vectors of fish parasites in salmon, trout, and shrimp operations. Chilean salmon producers generate concentrated margin pools through technical service contracts requiring specialized sodium niclosamide application protocols.
- Public Health:Vector control programs targeting disease-transmitting snail species in water management infrastructure.
- Landscaping:Residential and commercial ornamental plant protection with lower volume concentration but higher per-unit pricing.
Agriculture captures the largest revenue share. Aquaculture demonstrates the steepest margin expansion trajectory.
End User:
Procurement sophistication divides sharply between organized cooperative buyers and fragmented individual purchasers, with contract structure complexity escalating alongside operational scale.
- Farmers:Individual producers and cooperative members managing crop protection programs across soybean, corn, and specialty crop systems. Southern Brazilian agricultural cooperatives in Rio Grande do Sul and Paraná now contract through multi-season framework agreements that displace spot purchasing.
- Aquaculture Operators:Salmon, trout, and shrimp producers requiring pond-specific molluscicide treatments with integrated technical support. Chilean operators concentrate demand for sodium niclosamide formulations through specialized distribution channels.
- Municipalities:Public health agencies managing vector control programs with standardized procurement protocols.
- Landscaping Companies:Commercial maintenance contractors serving residential and corporate clients with lower volume requirements.
Farmers constitute the largest addressable base. Aquaculture operators are climbing fastest in per-customer value terms.
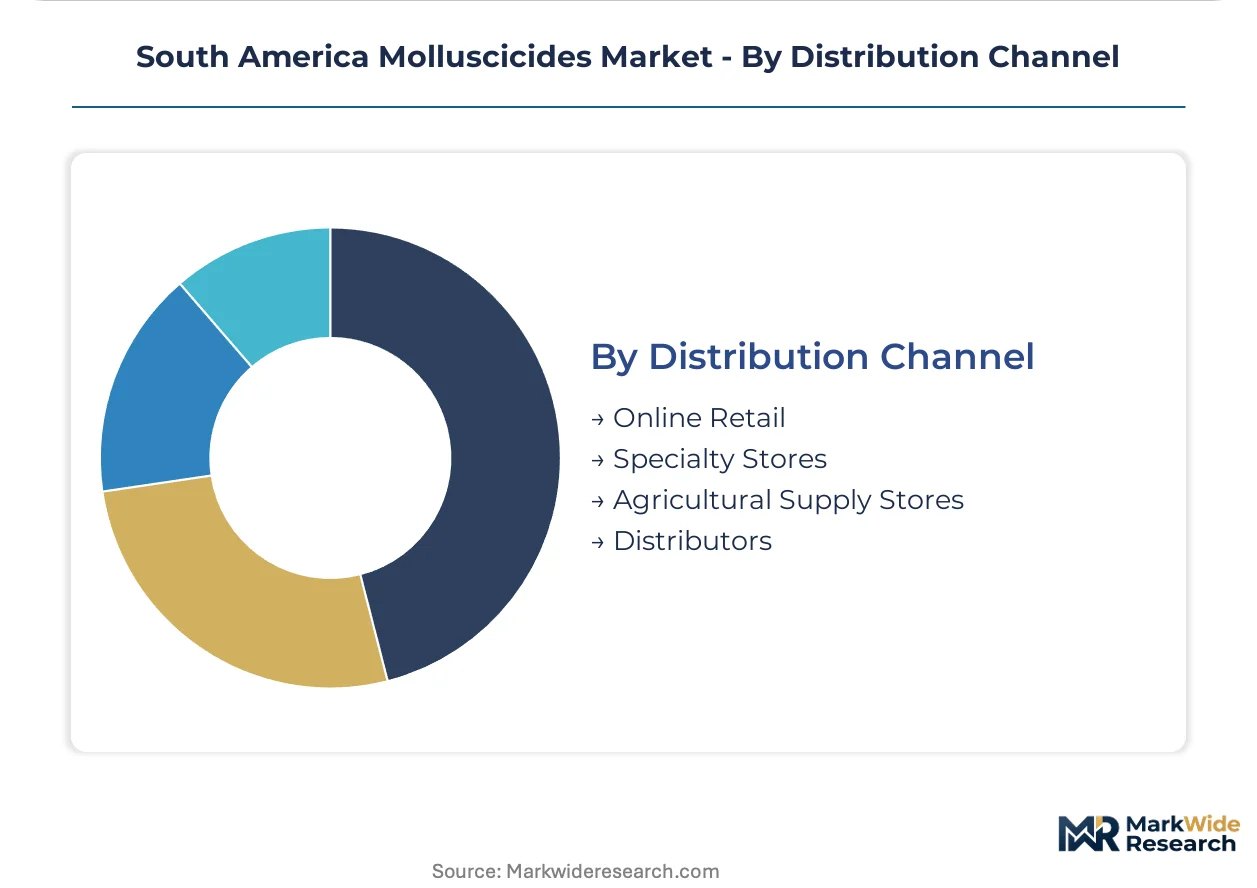
Distribution Channel:
Channel power is concentrating around cooperative procurement offices and specialized agricultural supply networks, with traditional distributor margins compressing under direct contracting pressure.
- Agricultural Supply Stores:Cooperative-affiliated retail points serving member farmers with technical advisory and inventory management. These outlets anchor distribution in Brazil's southern soybean belt where cooperative membership density exceeds seventy percent of farmed acreage.
- Distributors:Traditional agrochemical wholesalers facing margin pressure as large cooperatives bypass intermediary layers. Argentina's SENASA import standards elevate compliance costs for distributor-held inventory.
- Online Retail:E-commerce platforms gaining traction among smaller farmers and landscaping contractors.
- Specialty Stores:Niche outlets serving organic-certified producers and aquaculture specialists.
Agricultural supply stores lead by transaction volume. Online retail channels are gaining share fastest among non-cooperative buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for formulated molluscicide baits concentrates supply risk in European and Asian contract manufacturers, while Brazil and Argentina offset this through expanding domestic formulation partnerships. Export flows of active ingredients from China and Germany feed regional blending operations in São Paulo and Buenos Aires provinces.
Brazil
No-till soybean and corn systems across Paraná and Rio Grande do Sul sustain year-round gastropod pressure requiring systematic molluscicide protocols. ANVISA's Resolution RDC 293 mandates complete metaldehyde substitution by 2027, forcing cooperative procurement offices to front-load ferric phosphate inventory transitions. São Paulo state's formulation clusters now supply microencapsulated alternatives to southern agricultural cooperatives.
Argentina
Organic-certified wheat and horticultural operations in Buenos Aires and Córdoba provinces drive biological molluscicide uptake through SENASA's accelerated approval pathways. Resolution 369 elevates compliance costs for imported formulated products, redirecting demand toward locally registered ferric phosphate and copper-based alternatives. Rosario's agrochemical distribution hub coordinates supply to Pampas grain cooperatives.
Chile
Salmon and trout aquaculture in Los Lagos and Aysén regions generates concentrated demand for sodium niclosamide pond treatments targeting parasitic fluke vectors. The country's national pharmaceutical regulator enforces residue protocols that restrict metaldehyde use near watersheds. Puerto Montt anchors specialized technical service contracts linking European suppliers to marine farm operators.
Colombia
Coffee and banana plantations in Antioquia and Valle del Cauca deploy molluscicides against slug damage in high-humidity cultivation zones. The national agricultural health authority administers import permits for ferric phosphate formulations under tightening environmental review standards. Medellín-based distributors channel products to Andean slope cooperatives.
Peru
Asparagus and avocado export operations in Ica and La Libertad apply molluscicides to protect high-value perishables destined for North American markets. The country's national agricultural health service regulates active ingredient residues under phytosanitary protocols tied to destination-country import requirements. Lima's agrochemical importers coordinate supply from Brazilian and Argentine formulation sources.
South America Molluscicides Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational agrochemical conglomerates with integrated crop protection portfolios, regional formulators specializing in ANVISA-compliant alternatives, and aquaculture-focused technical service providers. Multinational players leverage R&D infrastructure to sustain integrated pest management offerings, while regional specialists exploit registration agility and cooperative distribution relationships. Competitive dynamics center on portfolio diversification toward ferric phosphate formulations and strategic partnerships with Brazilian agricultural cooperatives.
Among European-headquartered agrochemical conglomerates, Bayer Crop Science AG and BASF SE exemplify the multinational tier through their crop protection R&D infrastructure and integrated pest management portfolios. Syngenta Group anchors the cooperative distribution vector through partnerships with Brazilian agricultural supply networks. DE SANGOSSE, a French S.A., occupies a position within the specialized formulation tier, while Lonza Cologne GmbH represents the German chemical manufacturing segment serving regional blending operations.
| Leading Market Players |
|---|
| DE SANGOSSE |
| Rizobacter S.A. |
| Bayer Crop Science AG |
| Huagro |
| Bequisa |
| Lonza Cologne GmbH |
| Acay |
| BASF SE |
| Syngenta Group |
| Others |
Value Network & Pricing Analysis
Underutilized formulation capacity in São Paulo's agrochemical blending clusters is compressing supplier margins and accelerating price competition for ANVISA-compliant ferric phosphate alternatives. This slack capacity forces formulators to absorb regulatory compliance costs rather than pass them downstream, reshaping procurement leverage for Brazilian agricultural cooperatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Southern Cone. Price differentiation rests on certification grade—ANVISA-registered versus SENASA-pending—and volume scale in multi-season framework agreements. Cost compression in standard-grade metaldehyde formulations is intensifying because inventory liquidation precedes the 2027 phase-out deadline. Smallholder farmers outside cooperative networks demonstrate highest price sensitivity, while Chilean aquaculture operators accept premium positioning for specialized sodium niclosamide protocols.
Supply Chain Analysis
Tariff exposure between China and Brazil elevates landed costs for microencapsulated pellet technologies and active ingredient precursors. Geographic supply concentration centers on Chinese chemical manufacturers for metaldehyde intermediates, German specialty chemical houses for ferric phosphate matrices, and domestic Brazilian blenders for finished bait formulation. Raw material dependencies draw from iron ore derivatives, phosphoric acid feedstocks, and polymer encapsulation resins. Single-source vulnerability persists in European contract manufacturing of rainfast coating systems. Distribution runs through cooperative-affiliated agricultural supply stores in Rio Grande do Sul and Paraná, displacing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for aquaculture pond management are expanding faster than commodity bait sales, creating attach-rate opportunities for formulation suppliers willing to embed application protocols and residue monitoring into recurring service layers.
For Market Incumbents: Pre-empt cooperative procurement consolidation by securing exclusive multi-season framework agreements with Rio Grande do Sul and Paraná agricultural supply networks before 2027 inventory transitions complete. Invest in backward integration into microencapsulation resin production to offset European contract manufacturing dependency and defend margin structure against Chinese import price competition.
For New Entrants and Emerging Players: Pursue underpenetrated coffee cooperative channels in Minas Gerais and São Paulo state, where shaded plantation systems generate concentrated slug pressure but lack dedicated molluscicide technical advisory. Establish direct contracting relationships with organic-certified operations in Argentina's Pampas, leveraging SENASA's accelerated biological approval pathways as a regulatory differentiation wedge against legacy metaldehyde distributors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microencapsulated ferric phosphate manufacturing as São Paulo formulation clusters achieve scale economies. Long-term viability favors acquirers of regional formulators with ANVISA registration dossiers already filed and cooperative distribution relationships locked. Monitor ANVISA residue limit determinations on ferric phosphate as the signal indicating substitution timeline acceleration and inventory revaluation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Dossier Completion | Secures market access before metaldehyde phase-out deadlines force portfolio transitions. |
| Cooperative Supply Agreement | Locks volume commitments with Rio Grande do Sul agricultural supply networks bypassing distributor margins. |
| Microencapsulation Technology Licensing | Transfers rainfast formulation capability from European specialty chemical suppliers to Brazilian blenders. |
| Aquaculture Technical Service Contract | Attaches recurring revenue streams to Chilean salmon producers through pond-management protocols. |
| Biological Formulation Joint Venture | Combines entomopathogenic nematode expertise with iron phosphate matrices for organic certification eligibility. |
Research Methodology
Initial hypotheses were tested against primary input from agrochemical procurement managers at Brazilian agricultural cooperatives, regulatory affairs directors navigating ANVISA re-registration protocols, and technical service leads at Chilean aquaculture operations, then refined through secondary validation against ANVISA regulatory filings, SENASA import permit databases, and Brazilian customs trade records. Bottom-up volume estimates from cooperative purchasing data were triangulated against top-down market sizing derived from active ingredient import flows.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, application domain, and end-user procurement sophistication, with CAGRs derived from regression analysis of historical cooperative purchasing patterns and forward projection of ANVISA regulatory transition timelines. Industry-specific forecast inputs incorporated no-till farming adoption rates in Brazil's southern states and organic certification growth trajectories in Argentina's Pampas grain belt.
Sensitivities concentrate around ANVISA regulatory determinations on ferric phosphate maximum residue levels and potential state-level restrictions in Rio Grande do Sul and Santa Catarina. Forecasts reflect underlying assumptions about cooperative procurement consolidation velocity and import dependency persistence for microencapsulated technologies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Nematicides Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
US Pest Control Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Inorganic Fungicide Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Propiconazole Market