
 Asia Pacific Herbicide Market | 2026-2036
Asia Pacific Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Herbicide Market Insights
Subscription-based precision agriculture platforms bundled with herbicide prescriptions is recalibrating how crop protection inputs reach Asian growers. Bayer AG leverages its digital farming infrastructure to lock in recurring revenue streams across Australian and Indian operations. Syngenta Group anchors its position through biologicals-integrated portfolios that reduce chemical load per hectare. UPL Limited differentiates via open-source farmer networks that bypass traditional distributor markups in price-sensitive South Asian markets.
Herbicides constitute chemical agents engineered to inhibit photosystem II, disrupt amino acid synthesis, or interfere with cell division in target weed species, with formulations typically specifying active ingredient concentrations between 100–500 g/L for commercial application. These compounds serve industrial agriculture by reducing manual labor costs and protecting yield potential in monoculture systems where weed competition reduces output. Selective herbicides dominate volume sales across rice and wheat belts, while non-selective formulations capture premium positioning in orchard and plantation reset scenarios. Liquid concentrates lead formulation preference due to ease of tank-mixing and compatibility with drone-based application systems spreading across Chinese and Vietnamese operations.
India's CEA enforces BIS certification on imported technical-grade materials, raising compliance costs for non-domestic manufacturers while accelerating local production incentives. China's MEE implements discharge permits and environmental credit trading that constrain glyphosate synthesis capacity in legacy chemical parks. Australia's APVMA maintains residue tolerance schedules that directly shape export-oriented spraying calendars for grain consignments bound for Middle Eastern and East Asian buyers. Stakeholders must track regulatory divergence between hazard-based precautionary regimes and risk-assessment frameworks, as this split determines which chemistries retain market access versus face phased withdrawal.
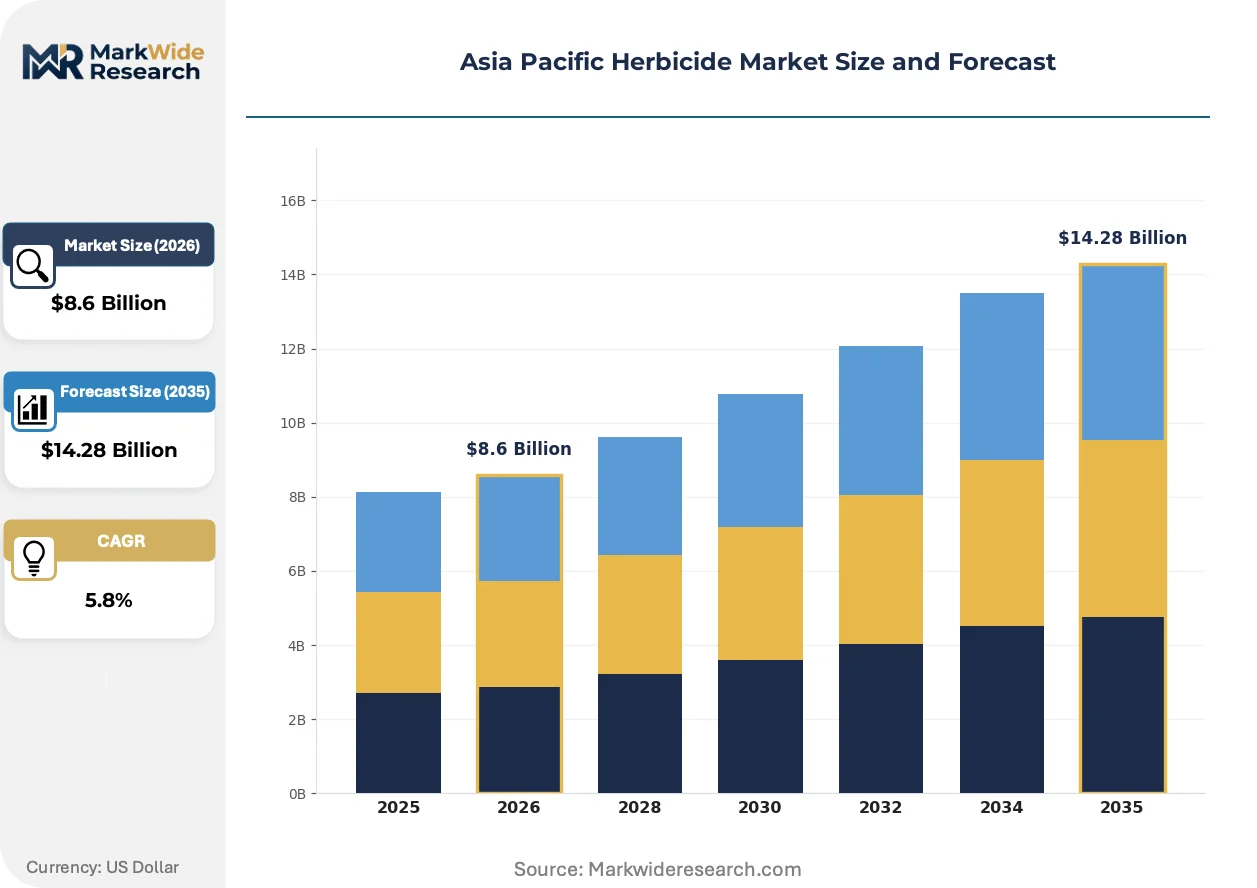
Market Dynamics
Mechanized rice cultivation across Southeast Asia is accelerating herbicide uptake as hand-weeding labor becomes scarcer and more expensive, compressing traditional weed management timelines and forcing input distributors to reconfigure their last-mile logistics networks around spray service bundling rather than standalone chemical sales.
Growth Catalysts
- India's PLI scheme for agrochemical manufacturing:Production-linked incentives are attracting technical-grade synthesis investments to Gujarat and Maharashtra, reducing import dependence for key intermediates.
- Drone-based application systems:Chinese and Vietnamese operators are adopting unmanned aerial spraying platforms that require liquid concentrate formulations optimized for low-volume precision delivery.
- Biologicals-integrated portfolios:Syngenta Group and regional formulators are blending microbial herbicide safeners with synthetic chemistries to meet residue tolerance thresholds in export-oriented Australian grain.
Market Restraints
- Glyphosate synthesis capacity constraints:China's MEE discharge permits and environmental credit trading schemes are capping output from legacy chemical parks in Jiangsu province.
- Paraquat substitution pressures:Thailand and Vietnam have implemented phased bans on this bipyridilium herbicide, forcing rapid reformulation investments without guaranteed replacement efficacy.
- Technical-grade import certification costs:India's BIS certification requirements for imported active ingredients impose compliance burdens that favor domestic manufacturers with established testing infrastructure.
Strategic Opportunities
- Subscription-based precision agriculture platforms:Bundled herbicide prescriptions tied to satellite imagery and soil sensors are penetrating Australian broadacre and Indian contract farming operations.
- Open-source farmer networks:Direct-to-farmer digital channels in Bangladesh and Pakistan are bypassing traditional distributor markups in price-sensitive South Asian markets.
- Biostimulant-herbicide combinations:Formulators are exploiting regulatory gaps in biological-pesticide hybrid classifications to access faster approval pathways than conventional chemistries.
Industry Challenges
- Residue testing laboratory capacity:Australia's APVMA tolerance schedules require analytical infrastructure that grain exporters in Queensland and Western Australia struggle to access at required throughput.
- Tank-mix compatibility verification:Drone operators in Vietnam and China face crop damage liability when combining multiple actives without established aerial application protocols.
- Technical registration data requirements:Generating ecotoxicology dossiers for novel herbicide safeners demands 24-36 month timelines that outpace product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Herbicide Market |
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $14.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Herbicides, Non-Selective Herbicides, Pre-Emergent Herbicides, Post-Emergent Herbicides Application: Agricultural Land, Horticulture, Turf & Ornamentals, Aquatic Weeds Formulation: Granules, Liquid Concentrates, Soluble Powders, Emulsifiable Concentrates End User: Farmers, Agricultural Cooperatives, Landscape Professionals, Garden Centers |
| Companies Covered | Bayer AG, Syngenta Group, UPL Limited, BASF SE, Corteva Agriscience, ADAMA Agricultural Solutions Ltd, FMC Corporation, Nufarm Ltd, Sumitomo Chemical Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Herbicide Market Trends and Innovations
Digital farming infrastructure is unifying previously separate decision layers—weed identification, prescription generation, and application execution—into continuous feedback loops that reshape how crop protection inputs reach Asian growers.
RNA interference herbicides targeting specific weed genetics are unifying precision agriculture's spatial resolution with molecular selectivity. Australian cotton and vineyard operators are piloting these formulations to manage glyphosate-resistant populations. The technology is unifying biological research pipelines with chemical registration frameworks, compressing development timelines for niche applications.
China's MEE environmental credit trading system is tightening discharge limits on legacy organophosphate synthesis facilities. Industrial consequence includes forced consolidation of technical-grade production into newer chemical parks with integrated waste treatment. Glyphosate and glufosinate manufacturers in Shandong province are most affected, responding by relocating capacity or investing in closed-loop water recycling systems.
Farmer procurement behavior is fragmenting across generational lines in India and Indonesia. Younger operators with smartphone access favor app-based input ordering with embedded credit, displacing commission-based village-level dealers. This shift concentrates purchase data with platform operators who leverage it for private-label herbicide development, most visible in Karnataka's sugarcane belt and East Java's corn districts.
Asia Pacific Herbicide Market Segmentation
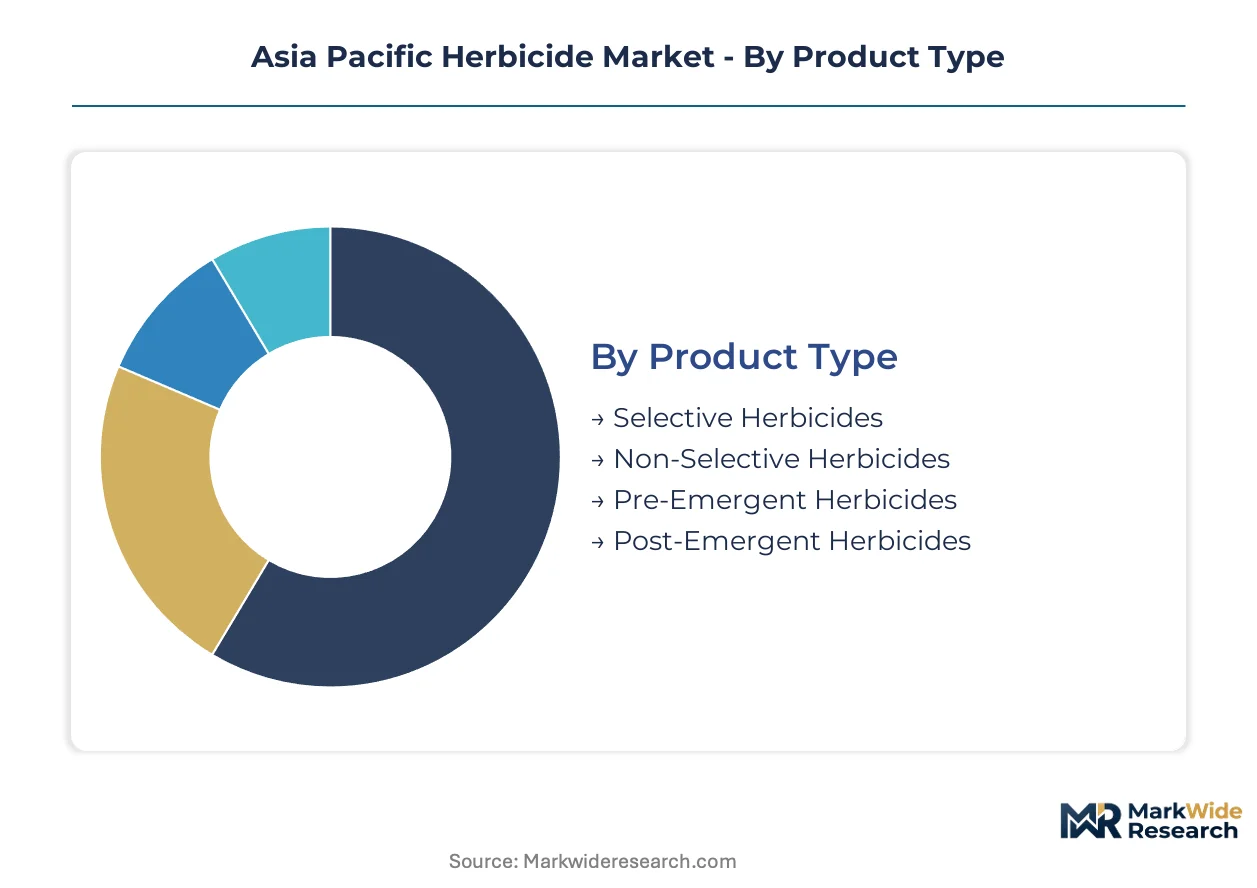
Herbicide segmentation across Asia Pacific reflects divergent agronomic requirements and distribution channel economics. Technical specifications governing selectivity, application timing, and formulation chemistry determine pricing power and margin capture for manufacturers serving rice belts versus plantation agriculture.
Product Type:
Supply concentration in glyphosate technical synthesis shapes competitive dynamics across all product categories, with Jiangsu and Shandong province clusters serving as the primary feedstock source for regional formulators.
- Selective Herbicides:These formulations target specific weed species while preserving crop physiology through differential enzyme inhibition pathways, typically featuring active concentrations between 150-400 g/L. Demand concentrates in India's wheat-rice rotation belts and Vietnam's Mekong Delta, where labor scarcity accelerates mechanized weed management adoption.
- Non-Selective Herbicides:Broad-spectrum agents indiscriminately disrupt photosynthetic or metabolic functions across plant taxa, requiring precise application to avoid crop damage. Australian broadacre operators and Indonesian palm oil plantations absorb the majority of regional volume, driven by pre-planting site preparation and plantation reset cycles.
- Pre-Emergent Herbicides:Soil-applied compounds forming chemical barriers that inhibit seedling emergence, valued in crops with slow initial growth.
- Post-Emergent Herbicides:Foliar-active formulations targeting established weeds, dominant in Southeast Asian rice systems where water management complicates early-season application timing.
Selective herbicides absorb the bulk of installed capacity; non-selective herbicides are expanding most quickly.
Application:
Cost tier differentiation separates commodity grain protection from premium horticultural inputs, with residue tolerance thresholds and export market access requirements driving formulation sophistication.
- Agricultural Land:Monoculture cereal and oilseed operations across eastern China's plains and India's Indo-Gangetic belt generate volume demand for cost-optimized selective chemistries, with BIS certification requirements and APVMA tolerance schedules shaping product registration priorities.
- Horticulture:High-value fruit and vegetable production in Australia's Murray-Darling basin and Thailand's northern valleys requires residue-compliant formulations with shortened pre-harvest intervals, commanding premium pricing and specialized distributor relationships.
- Turf & Ornamentals:Golf course and landscape maintenance applications in Japan and South Korea, characterized by aesthetic performance standards and public exposure concerns.
- Aquatic Weeds:Irrigation channel and reservoir management across water-stressed regions of Pakistan and northern India, where glyphosate and diquat formulations face discharge permit constraints under MEE-style environmental frameworks.
Agricultural land absorbs the bulk of installed capacity; horticulture is climbing the fastest.
Formulation:
Drone application compatibility is displacing traditional granular delivery in volume terms, compressing demand for labor-intensive spreading operations across Chinese and Vietnamese operations.
- Liquid Concentrates:Low-viscosity solutions optimized for tank-mixing and precision spraying equipment, dominating aerial application adoption curves. Vietnamese rice operators and Australian cotton growers prioritize these formulations for unmanned aerial system compatibility and reduced water volumes per hectare.
- Granules:Slow-release carrier matrices suited to pre-emergent soil incorporation and aquatic weed management, retaining relevance in labor-abundant Bangladesh and Myanmar where mechanized spraying infrastructure remains underdeveloped.
- Soluble Powders:Dry formulations requiring reconstitution, favored where cold chain logistics constrain liquid distribution.
- Emulsifiable Concentrates:Oil-in-water systems delivering lipophilic actives, common in plantation agriculture across Malaysia and Indonesia with established ground spraying contractor networks.
Liquid concentrates absorb the bulk of installed capacity; granules are gaining share fastest in frontier markets.
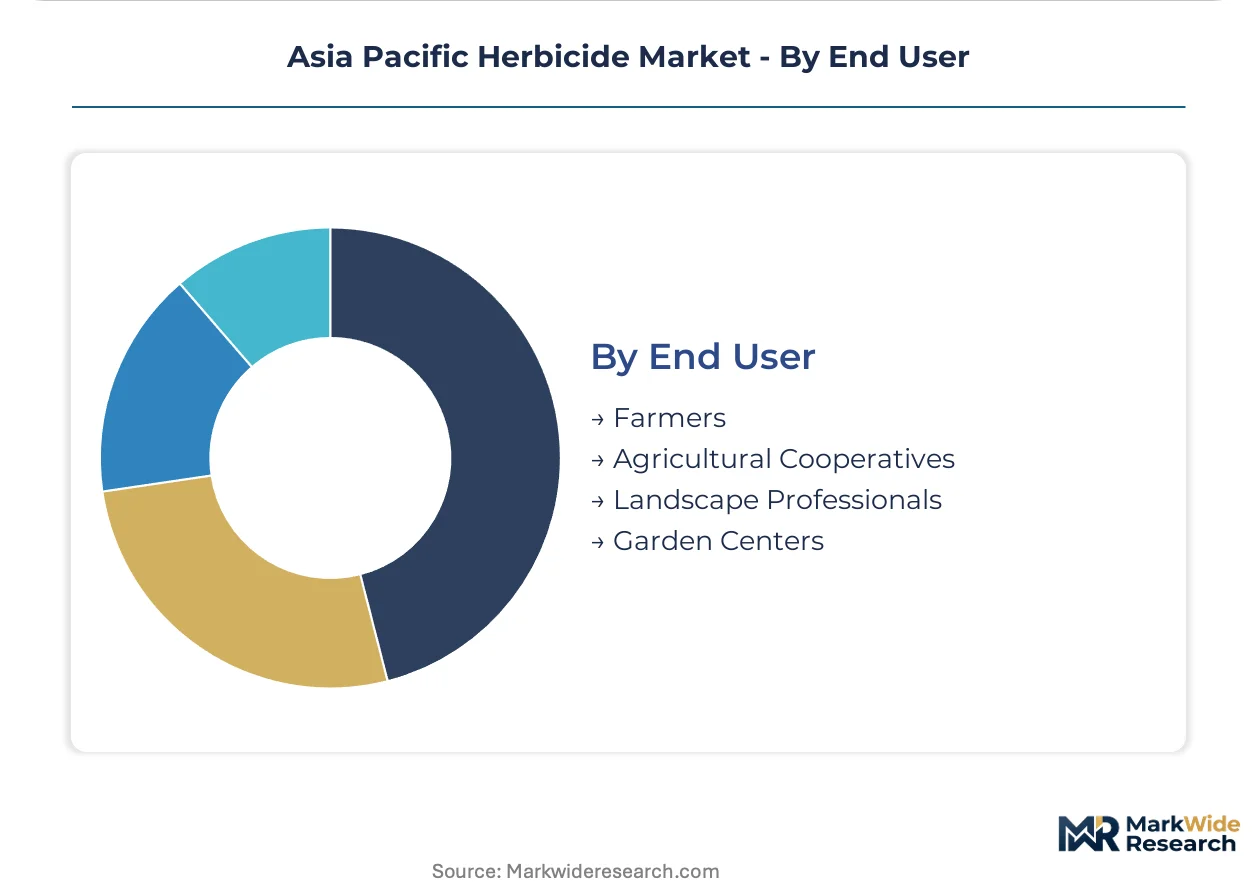
End User:
Procurement patterns fragment across generational and digital access divides, with platform-based purchasing concentrating transaction data among emerging agricultural input aggregators.
- Farmers:Individual operators across India's Karnataka sugarcane belt and Indonesia's East Java corn districts, increasingly accessing inputs through smartphone-enabled platforms that embed credit and bypass traditional village-level dealer markups.
- Agricultural Cooperatives:Consolidated purchasing entities in China's Shandong and Jiangsu provinces, leveraging contract manufacturing relationships and export market knowledge to source technical-grade materials.
- Landscape Professionals:Turf management contractors and municipal maintenance operators in Australian urban corridors and Japanese prefectural governments.
- Garden Centers:Retail channels serving hobbyist and smallholder segments, concentrated in suburban markets surrounding Bangkok, Jakarta, and Manila with limited technical advisory capacity.
Farmers absorb the bulk of installed capacity; agricultural cooperatives are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates technical-grade synthesis capacity while India and Southeast Asian nations absorb the bulk of formulated herbicide consumption. This production-consumption divide concentrates upstream chemical manufacturing in eastern coastal provinces and downstream demand across rice belts and plantation zones.
China
Jiangsu and Shandong provinces host glyphosate and glufosinate synthesis clusters serving export formulators. MEE discharge permits and environmental credit trading constrain legacy chemical park output, forcing relocation to integrated waste treatment facilities. Nantong and Lianyungang chemical parks absorb relocated capacity with closed-loop water recycling systems.
India
Wheat-rice rotation belts across Punjab, Haryana, and Uttar Pradesh drive selective herbicide volume demand. CEA-mandated BIS certification on imported technical-grade materials raises compliance costs for foreign suppliers while PLI scheme incentives accelerate Gujarat and Maharashtra synthesis investments. Bharuch and Ankleshwar industrial corridors attract technical-grade manufacturing capacity.
Australia
APVMA residue tolerance schedules shape export-oriented spraying calendars for grain consignments bound for Middle Eastern and East Asian buyers. Queensland and Western Australia grain exporters struggle with analytical laboratory capacity for required throughput testing. Brisbane and Perth testing facilities face backlogs during peak harvest windows.
Vietnam
Mekong Delta rice operators accelerate drone-based herbicide adoption as hand-weeding labor scarcity compresses traditional weed management timelines. Phased paraquat bans force rapid reformulation investments without guaranteed replacement efficacy. Can Tho and An Giang provinces concentrate unmanned aerial spraying contractor networks.
Indonesia
Palm oil plantation reset cycles and corn districts in East Java absorb non-selective herbicide volume. Younger operators with smartphone access favor app-based input ordering with embedded credit, displacing commission-based village-level dealers. Surabaya and Malang agricultural input aggregators concentrate purchase data for private-label development.
Asia Pacific Herbicide Market Competitive Landscape
Top-tier vendors anchor technical-grade synthesis and integrated formulation, while mid-tier regional formulators compete on price and distribution reach. The vendor base stratifies across multinational agrochemical conglomerates with biologicals-integrated portfolios, domestic Chinese and Indian manufacturers with PLI scheme backing, and specialist drone-application service providers bundling chemical prescriptions. Dominant competitive moves include backward integration into active ingredient production and strategic partnerships with precision agriculture platform operators.
Within the multinational tier, Bayer AG, Syngenta Group, and UPL Limited exemplify divergent strategic archetypes. Bayer AG leverages digital farming infrastructure to lock in recurring revenue streams across Australian and Indian operations. Syngenta Group anchors its position through biologicals-integrated portfolios that reduce chemical load per hectare. UPL Limited differentiates via open-source farmer networks that bypass traditional distributor markups in price-sensitive South Asian markets.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| UPL Limited |
| BASF SE |
| Corteva Agriscience |
| ADAMA Agricultural Solutions Ltd |
| FMC Corporation |
| Nufarm Ltd |
| Sumitomo Chemical Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Drone-based application systems spreading across Chinese and Vietnamese rice operations simultaneously compress formulation costs per hectare and concentrate procurement power among platform operators who bundle chemical prescriptions with aerial spraying services.
Pricing Analysis
Margin tightening in liquid concentrate tiers reflects glyphosate synthesis capacity caps under China's MEE discharge permit regime. Three-tier pricing structure across premium residue-compliant, standard BIS-certified, and economy generic tiers separates Australian export grain operators from Indian domestic wheat farmers from Bangladesh price-sensitive growers. Cost-down pressure on standard-grade selective herbicides accelerates because PLI scheme incentives expand Gujarat technical-grade output. Indian contract farmers show highest price sensitivity; Australian broadacre exporters absorb premium formulations with residue testing bundled.
Supply Chain Analysis
Technical-grade synthesis labor availability constraints in Jiangsu and Shandong chemical parks force relocation to Nantong and Lianyungang integrated waste treatment facilities. Active ingredient production draws from paraquat-restricted Vietnamese reformulation demand, glufosinate technical for Australian grain, and 2,4-D intermediates for Indian wheat-rice belts. Single-source vulnerability concentrates in glyphosate technical from legacy Chinese chemical parks. Distribution runs through agricultural cooperatives in Shandong and smartphone-enabled platforms in Karnataka and East Java.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glyphosate synthesis capacity constraints under China's environmental credit trading system prop pricing power for technical-grade manufacturers who secure discharge permits in relocated chemical parks.
For Market Incumbents: Hedge paraquat substitution risk in Thailand and Vietnam by accelerating microbial safener R&D partnerships and securing BIS pre-certification for Indian technical-grade imports. Backward integration into Gujarat PLI scheme zones reduces exposure to CEA-mandated testing bottlenecks.
For New Entrants and Emerging Players: The mid-tier price gap between Syngenta biologicals-integrated premiums and generic Chinese glyphosate offers entry space for drone-application service bundlers in Vietnam's Mekong Delta. Target unmanned aerial spraying contractor networks with tank-mix-compatible liquid concentrate formulations.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision agriculture platform acquisitions by multinational agrochemical conglomerants seeking recurring revenue lock-in. Five-to-ten year viability favors technical-grade manufacturers with MEE discharge permit secured in relocated Chinese chemical parks. Watch glyphosate-resistant weed population spread in Australian cotton as inflection signal for RNA interference herbicide platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Synthesis | Gujarat PLI scheme zones attract capacity fleeing Chinese environmental credit constraints. |
| Drone Application Platform Partnership | Vietnamese unmanned aerial spraying contractors bundle prescriptions with flight services. |
| Biologicals-Integrated Portfolio Expansion | Syngenta's microbial safeners reduce chemical load per hectare for Australian export grain. |
| Open-Source Farmer Network Development | UPL Limited's direct digital channels bypass distributor markups in Bangladesh and Pakistan. |
| Closed-Loop Water Recycling Investment | Shandong glyphosate manufacturers respond to MEE discharge limits with integrated treatment. |
Research Methodology
Regulatory filings from China's MEE, India's CEA, and Australia's APVMA formed the secondary backbone, cross-referenced with customs data on technical-grade trade flows and agrochemical industry association reports. Primary interviews with formulation plant managers in Jiangsu, procurement leads at Australian grain exporters, Vietnamese drone spraying contractors, and Karnataka agricultural input platform operators combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis across technical-grade synthesis capacity, formulation output, and farmer procurement channel shifts informed the projection framework. Segmentation dimensions modeled include selective versus non-selective chemistry, liquid concentrate versus granule formulation, and drone-compatible versus ground-application delivery. CAGRs derived from fitted growth curves adjusted for PLI scheme capacity additions and paraquat phase-out timelines. Industry-specific inputs incorporated MEE discharge permit allocations and BIS certification backlog estimates.
Underlying measurement precision varies by segment; liquid concentrate and drone-application adoption carry tighter precision than granular formulation demand in frontier markets. Forecasts reflect assumptions on environmental credit trading enforcement consistency and PLI scheme disbursement pacing. Material deviation in glyphosate-resistant weed spread rates or MEE permit issuance velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
United States Nematicides Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Miticides Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Larvicides Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Pest Control Market
Crop Protection
Crop Protection Chemicals Market