
 Middle East and Africa Bonsai Market | 2026-2036
Middle East and Africa Bonsai Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Bonsai Market Foresight
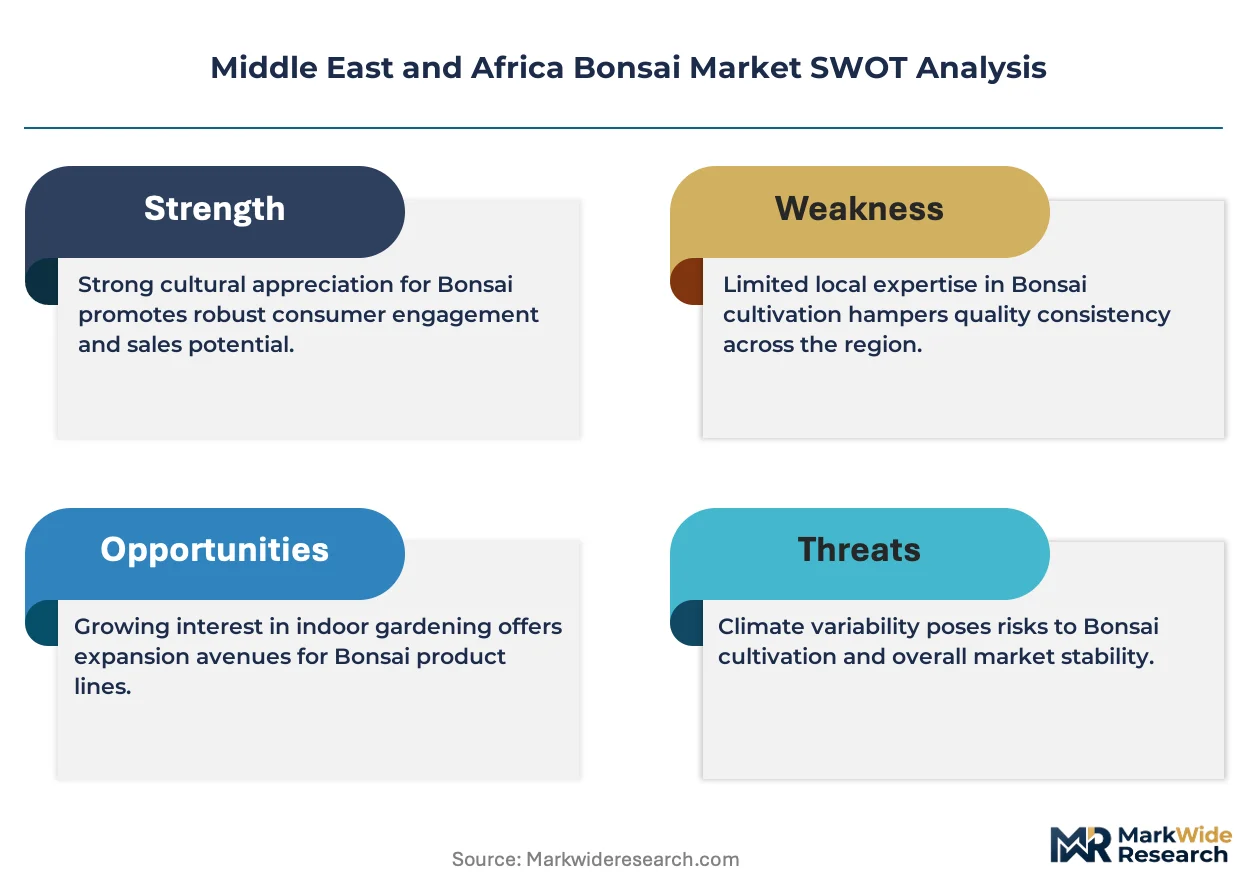
Horticultural expertise in advanced pruning and wiring techniques is rotating toward a narrow cohort of master artisans across the Middle East and Africa, constraining scalable production of museum-grade specimens. Brussel's Bonsai leverages its deep stock of mature training material to sustain export competitiveness into the region. Lodder Bonsai BV anchors European supply relationships that dominate premium import channels. Kaizen Bonsai Ltd. competes through specialized workshop-based education that builds customer loyalty beyond transactional plant sales.
Bonsai denotes woody perennials cultivated in shallow containers through systematic root pruning, branch wiring, and defoliation to achieve miniature yet botanically mature forms; specimens typically require decades of continuous training and specific substrate compositions combining akadama, pumice, and organic matter to maintain root health in constrained volumes. Indoor bonsai dominates volume through ficus and dwarf jade varieties suited to air-conditioned interiors across Gulf states, while outdoor juniper and pine categories command premium pricing among dedicated collectors. The pre-bonsai segment attracts hobbyists seeking lower entry costs, though margin pools concentrate in finished specimens sold through garden centers.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces strict phytosanitary certification under the National Environmental Management Biodiversity Act, while Saudi Arabia's SFDA and national customs authorities regulate pesticide residue thresholds on imported living plant material. These frameworks elevate compliance costs for smaller nurseries but simultaneously protect established distributors with documented supply chain traceability. Stakeholders must monitor evolving biosecurity harmonization talks between Gulf Cooperation Council members to anticipate consolidated import standard shifts.
Market Dynamics
Biosecurity protocol tightening across Gulf Cooperation Council states is restructuring import sourcing for ornamental plants, elevating compliance burdens on smaller distributors while concentrating volume flows through documented supply chains.
Growth Catalysts
- UAE Biosecurity Enforcement:The Ministry of Climate Change and Environment's tightened phytosanitary protocols for imported ornamental plants is filtering out informal importers and consolidating demand around certified nursery networks.
- Residential Landscaping Expansion:Affluent urban households across Dubai, Riyadh, and Johannesburg are commissioning Japanese garden installations that anchor long-term specimen acquisition programs.
- Master Artisan Training Pipelines:Specialized workshop-based education programs in advanced wiring and defoliation techniques are deepening collector engagement and repeat purchase frequency.
Market Restraints
- Akadama Substrate Volatility:Import dependency on Japanese volcanic clay creates margin compression when currency fluctuations or shipping disruptions spike landed costs for premium growing media.
- Artisan Concentration Risk:Museum-grade production capability clusters among a narrow cohort of master practitioners across the region, constraining scalable supply of finished specimens.
- South African Phytosanitary Friction:The National Environmental Management Biodiversity Act's strict certification timelines delay cross-border shipments and elevate working capital requirements for distributors.
Strategic Opportunities
- Saudi Arabia's Emerging Collector Base:Riyadh and Jeddah display underpenetrated demand for outdoor juniper categories as landscape architecture firms integrate specimen bonsai into luxury residential projects.
- Pre-Bonsai Hobbyist Segment:Lower-entry-cost training material attracts first-time buyers seeking hands-on cultivation experience before graduating to premium finished specimens.
- GCC Biosecurity Harmonization:Pending alignment talks between Gulf Cooperation Council customs authorities promise consolidated import standards that would streamline multi-country distribution for compliant operators.
Industry Challenges
- Multi-Decade Cultivation Skill Transfer:Systematic root pruning and branch wiring expertise requires 15-20 year training cycles, creating succession planning gaps as founding artisans age.
- Pesticide Residue Testing Complexity:Saudi Arabia's SFDA and national customs authorities enforce divergent maximum residue limits that force distributors to maintain parallel compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Bonsai Market |
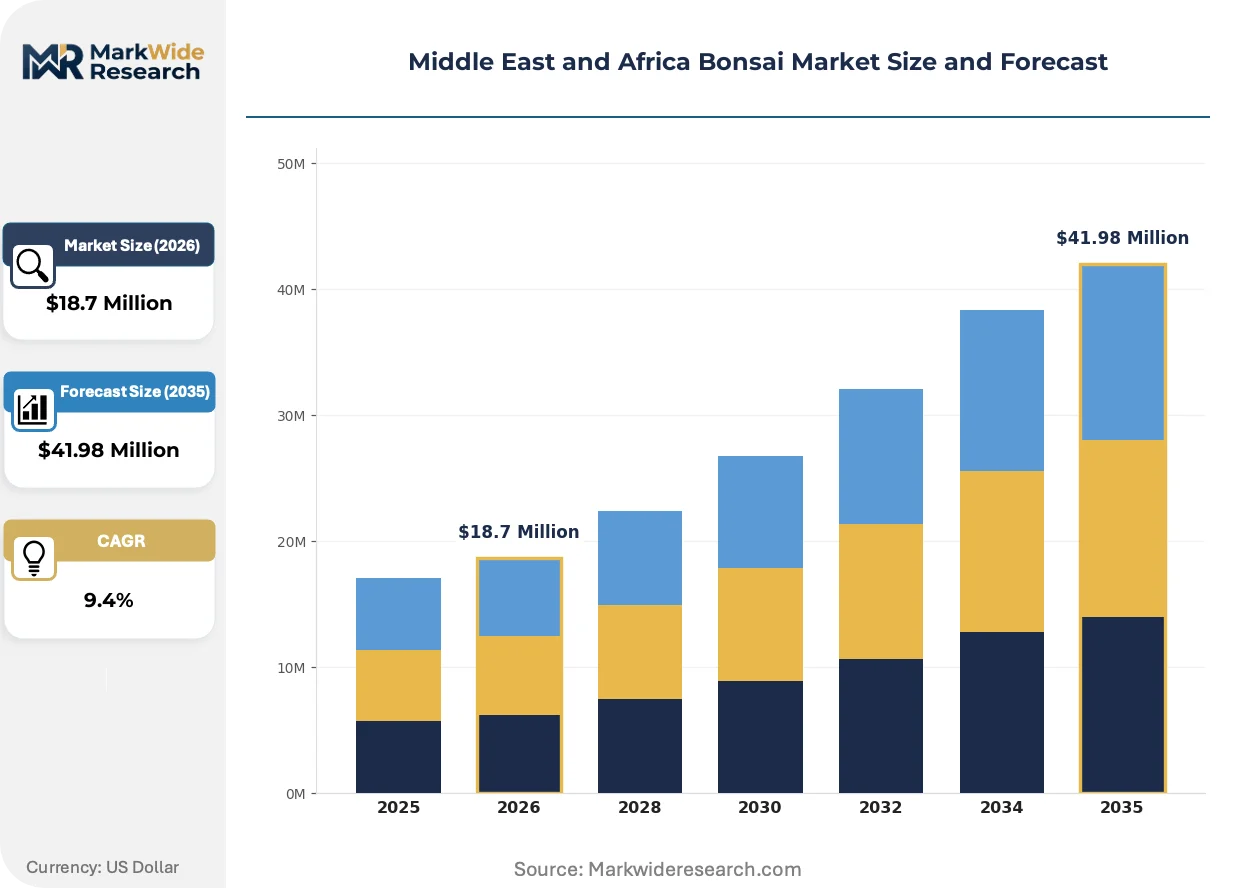
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Bonsai, Outdoor Bonsai, Miniature Bonsai, Pre-bonsai Tree Species: Juniper, Ficus, Pine, Maple Distribution Channel: Online Retail, Garden Centers, Nurseries, Home Improvement Stores Customer Type: Hobbyists, Landscape Professionals, Gift Buyers, Interior Designers |
| Companies Covered | Kaizen Bonsai Ltd., Lodder Bonsai BV, Brussel's Bonsai, Ganga Nursery, Bonsai Network Japan, Dongyi Artificial Plants Co., Limited, Bonsai Direct, The Bonsai Company Ltd., MiniGardens Bonsai NZ Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Bonsai Market Shifts & Advancements
Controlled-environment agriculture techniques are migrating from food production into ornamental horticulture, reshaping how specimens acclimate to Gulf-state interiors. Three developments are compressing cultivation timelines and altering competitive positioning.
LED grow light spectrum tuning is miniaturizing. Precision wavelength arrays now replicate seasonal photoperiod shifts that trigger dormancy breaks in temperate species previously unsuited to Arabian Peninsula interiors. High-net-worth collectors in Abu Dhabi and Doha are retrofitting dedicated climate rooms with these systems, enabling juniper and pine categories to thrive in air-conditioned environments. This technology is compressing the traditional geographic limitation that confined premium outdoor specimens to South Africa and Levantine climates.
Saudi Arabia's SFDA has tightened pesticide residue surveillance on imported living plant material. The industrial consequence is a documentation burden that favors distributors with captive laboratory testing relationships and multi-year supplier audit trails. Premium finished specimens sold through Riyadh garden centers are most affected, with compliant operators now marketing traceability as a competitive differentiator.
Collector purchasing has fragmented across direct-to-consumer digital channels and traditional nursery visits. Established South African garden centers in Gauteng are responding with hybrid appointment systems that combine online specimen viewing with in-person wiring demonstrations. This behavioral shift is most visible among Johannesburg's Japanese garden societies, where members increasingly source pre-bonsai material through specialized forums before commissioning local artisans for finishing work.
Middle East and Africa Bonsai Market Segmentation
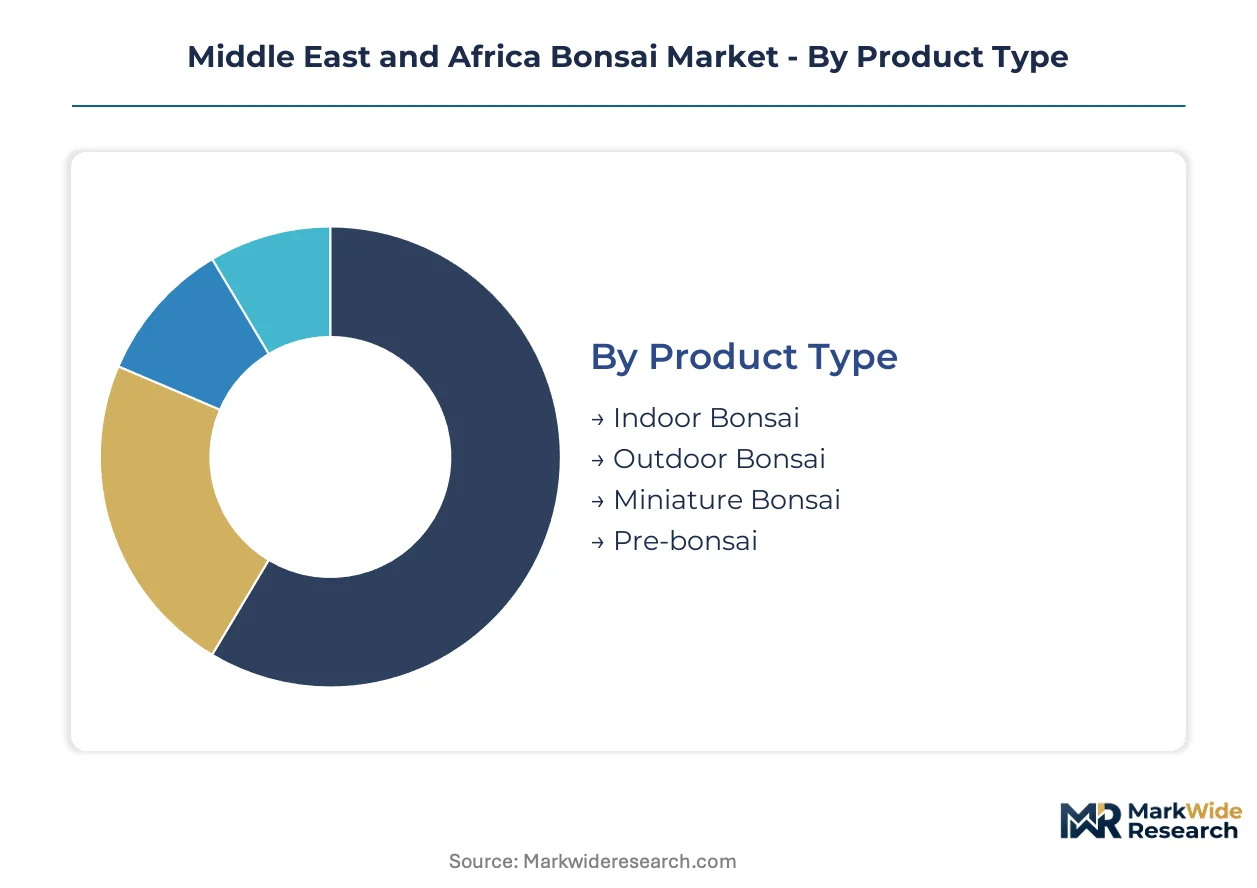
Segmentation in the Middle East and Africa bonsai market reveals distinct procurement behaviors across customer archetypes. Product categories align with environmental constraints and skill levels, while distribution channels fragment between digital convenience and hands-on nursery experiences.
Product Type:
Channel flows diverge sharply: indoor varieties dominate online retail and home improvement stores, while outdoor specimens concentrate in specialized nurseries and garden centers with trained staff.
- Indoor Bonsai:Ficus and dwarf jade varieties tolerate air-conditioned interiors across Gulf states. Demand clusters in Dubai and Abu Dhabi high-rise residences where natural light is limited and climate control is constant.
- Outdoor Bonsai:Juniper and pine specimens require seasonal temperature variation and direct sunlight. Sales concentrate through Johannesburg and Cape Town nursery networks where established Japanese garden societies provide cultivation guidance.
- Miniature Bonsai:Compact specimens under 15 centimeters suit apartment dwellers in Riyadh and Doha seeking desktop ornamentation without space commitment.
- Pre-bonsai:Untrained starter material with established root systems attracts hobbyists entering the cultivation practice. Gauteng province garden centers report strongest turnover for this entry-level category.
By volume, indoor bonsai leads. By growth pace, pre-bonsai is expanding most quickly.
Tree Species:
Cost tiers separate species by cultivation timeline and import dependency, with faster-maturing varieties commanding lower price points and domestically propagable species reducing landed cost volatility.
- Juniper:Temperate conifers requiring winter dormancy periods. South African collectors in Western Cape province prize these for traditional styling compatibility, though Gulf-state buyers increasingly deploy LED grow systems to simulate seasonal triggers.
- Ficus:Tropical evergreen suited to year-round indoor cultivation. Nigerian and Kenyan urban households favor these for low-maintenance tolerance and rapid recovery from pruning errors.
- Pine:Slow-growing specimens demanding decade-long training cycles. Saudi Arabia's emerging collector base in Riyadh drives premium pricing for mature pine specimens imported through documented supply chains.
- Maple:Deciduous species valued for seasonal foliage color variation. Limited heat tolerance restricts outdoor cultivation to high-altitude East African regions and climate-controlled environments.
Margin concentration favors pine for finished specimens, while ficus generates highest transaction frequency.
Distribution Channel:
Customer type dictates channel selection: hobbyists and gift buyers gravitate toward digital platforms, while landscape professionals and interior designers require physical specimen evaluation.
- Online Retail:Digital marketplaces with specimen photography and shipping logistics. Pre-bonsai and miniature categories dominate this channel due to lower per-unit value and reduced transit damage risk.
- Garden Centers:Retail locations combining plant sales with substrate and tool accessories. Johannesburg and Dubai garden centers anchor regional volume through established Japanese garden society relationships.
- Nurseries:Production facilities with on-site artisan expertise. These capture outdoor bonsai and finished specimen sales requiring wiring demonstrations and after-purchase styling guidance.
- Home Improvement Stores:Mass retail channels stocking indoor varieties and basic cultivation supplies. UAE-based chains leverage central procurement to achieve price positioning below specialized competitors.
Nurseries command highest average transaction value. Online retail is gaining share fastest among first-time buyers.
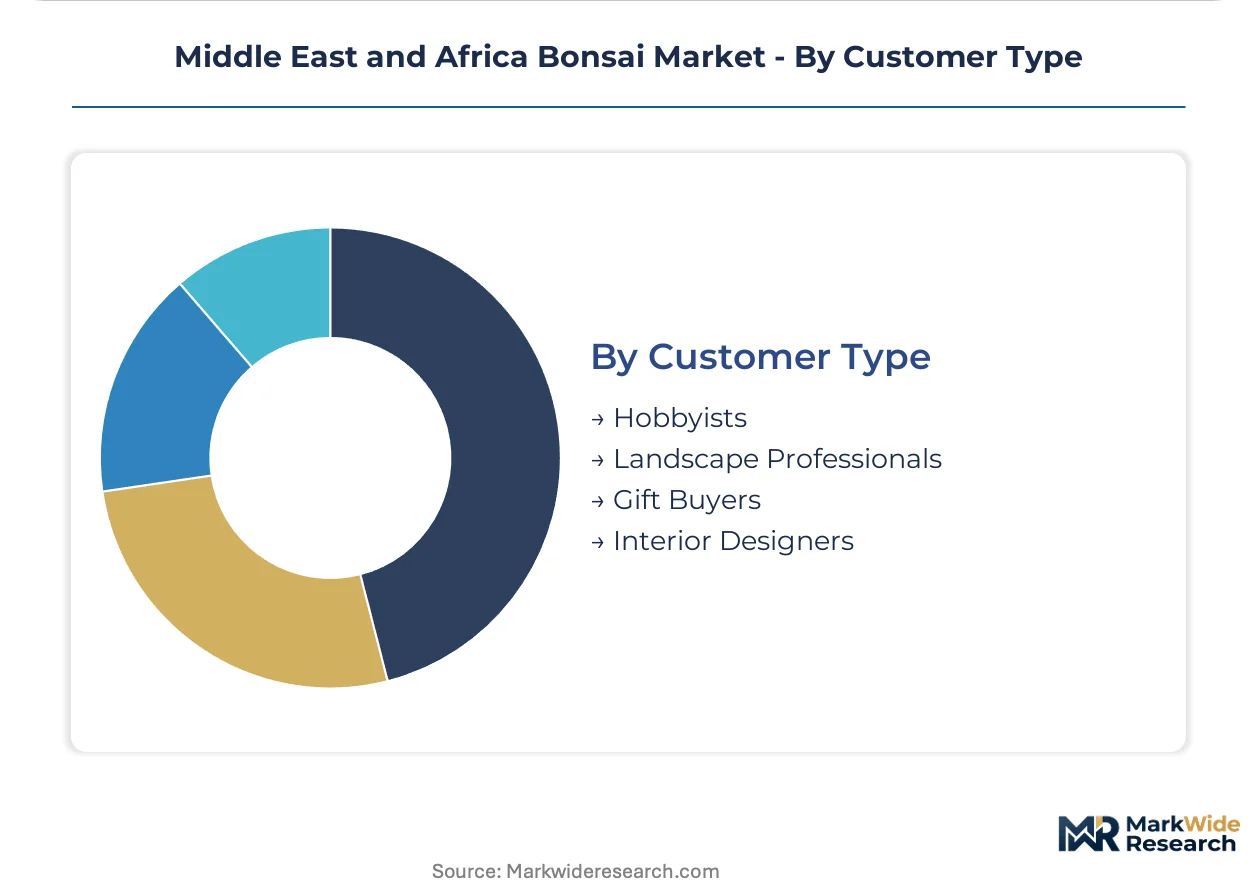
Customer Type:
Application context separates buyers by project scale and expertise depth, from individual hobby cultivation to integrated landscape architecture.
- Hobbyists:Individual practitioners seeking hands-on cultivation experience. This segment drives pre-bonsai volume and workshop-based education revenue across Gauteng and Western Cape provinces.
- Landscape Professionals:Contracted designers specifying specimens for residential and commercial installations. Saudi Arabian luxury residential projects in Riyadh and Jeddah represent expanding demand concentration.
- Gift Buyers:Occasional purchasers seeking ornamental presents. Miniature and indoor varieties dominate this segment through seasonal peaks around religious and cultural celebrations.
- Interior Designers:Commercial space stylists integrating living elements into hospitality and corporate environments. Dubai and Abu Dhabi hotel lobbies anchor specimen acquisition programs with multi-year maintenance contracts.
Landscape professionals generate largest order sizes. Interior designers show steepest expansion trajectory as biophilic design principles penetrate regional commercial architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Africa's established nursery networks while Gulf-state buyers absorb premium import costs for finished specimens. The regional market fragments across temperate cultivation zones and air-conditioned interior demand centers. Regulatory divergence between GCC biosecurity frameworks and South African phytosanitary regimes shapes cross-border trade economics.
United Arab Emirates
Dubai's affluent residential towers and Abu Dhabi's hospitality sector drive specimen acquisition for interior landscaping. MOCCAE's tightened phytosanitary protocols for imported ornamental plants filter informal importers and consolidate volume through certified nursery networks. Al Ain and Dubai garden centers anchor retail distribution with established Japanese garden society relationships.
Saudi Arabia
Riyadh's luxury residential projects and Jeddah's emerging collector base expand demand for outdoor juniper categories in climate-controlled environments. SFDA pesticide residue surveillance on imported living plant material elevates documentation burdens favoring distributors with captive laboratory testing relationships. Landscape architecture firms in the capital integrate specimen bonsai into high-end installations.
South Africa
Gauteng province hobbyists and Western Cape traditional collectors sustain premium bonsai culture through established nursery networks. DALRRD enforces strict phytosanitary certification under NEMBA, delaying cross-border shipments and elevating working capital requirements. Johannesburg Japanese garden societies drive pre-bonsai volume through workshop-based education programs.
Israel
Tel Aviv metropolitan interior designers and Jerusalem residential collectors generate demand for compact ficus varieties suited to Mediterranean climate interiors. The national plant protection authority regulates import pathways for ornamental woody perennials with documentation requirements similar to European standards. Central district nurseries specialize in drought-tolerant species adaptation for regional conditions.
Qatar
Doha's high-net-worth collectors deploy LED grow systems in dedicated climate rooms to cultivate temperate species previously unsuited to Arabian Peninsula conditions. Customs authorities align with emerging GCC biosecurity harmonization frameworks pending consolidated import standards. West Bay district hotels anchor specimen maintenance contracts for lobby installations.
Middle East and Africa Bonsai Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa bonsai market. European and North American suppliers dominate premium finished specimen channels through documented supply chain traceability, while Asian manufacturers compete on pre-bonsai training material volume. The market structures around three archetypes: established export houses with multi-decade cultivation stock, specialized workshop-based educators building customer loyalty, and regional distributors with compliant import documentation capabilities. Competitive moves concentrate on biosecurity certification investments and hybrid digital-physical customer engagement systems.
Among European-based specialists, Lodder Bonsai BV and Kaizen Bonsai Ltd. occupy positions anchoring premium import relationships into Gulf-state markets. Brussel's Bonsai represents North American export competitiveness through deep mature training material inventories. These three exemplify contrasting strategic positions: one emphasizes supply chain documentation compliance, another workshop-based education revenue, the third export scale through established stock reserves.
| Leading Market Players |
|---|
| Kaizen Bonsai Ltd. |
| Lodder Bonsai BV |
| Brussel's Bonsai |
| Ganga Nursery |
| Bonsai Network Japan |
| Dongyi Artificial Plants Co., Limited |
| Bonsai Direct |
| The Bonsai Company Ltd. |
| MiniGardens Bonsai NZ Ltd. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Japanese substrate suppliers lock in akadama access and cost visibility for Gulf-state distributors, insulating premium specimen margins against volcanic clay import volatility while committing working capital years ahead of cultivation completion.
Pricing Analysis
Configured-to-order pricing for museum-grade specimens commands spreads exceeding standard pre-bonsai material by factors reflecting artisan labor amortization across decade-long training cycles. Three-tier pricing structure across premium, standard, and economy levels separates finished juniper installations from workshop-grade material and entry-level ficus starter stock. Price differentiation hinges on phytosanitary certification grade and wiring complexity tier. Cost compression in standard indoor varieties intensifies as UAE home improvement chains centralize procurement. Gift buyers exhibit highest price sensitivity; landscape professionals demonstrate lowest elasticity given project budget insulation.
Supply Chain Analysis
Japan and China anchor akadama substrate and pre-bonsai training material production respectively, while South Africa's Western Cape province concentrates finished specimen cultivation for regional distribution. Japanese volcanic clay, copper training wire, and specialized ceramic containers constitute critical input dependencies. Single-source vulnerability in akadama supply creates exposure to currency fluctuation and shipping disruption. Distribution runs through certified nursery networks in Gauteng and Dubai, with compliant documentation capabilities filtering informal competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Systematic root pruning expertise requires fifteen-to-twenty-year cultivation cycles, concentrating museum-grade production capability among aging master artisans and constraining scalable supply expansion across the Middle East and Africa.
For Market Incumbents: Consolidate artisan training pipelines through apprenticeship formalization and captive workshop infrastructure in Johannesburg and Dubai garden centers. Acquire backward integration into substrate blending facilities to reduce Japanese akadama dependency. Biosecurity harmonization across Gulf Cooperation Council states threatens documentation advantages currently held by established distributors. For New Entrants and Emerging Players: After-sales styling guidance represents a service-layer gap where incumbents under-serve, particularly for first-time hobbyists seeking long-term cultivation support. Target Riyadh's emerging outdoor juniper collector base through climate-controlled cultivation advisory bundled with LED grow system provisioning. Commissioning local artisans for finishing work on imported pre-bonsai material offers a low-capital entry angle. For Investors and Strategic Acquirers: Regional distributors with multi-year SFDA and MOCCAE audit trails present the most defensible acquisition target archetype given compliance barrier elevation. Long-term viability frames around biosecurity certification depth rather than cultivation stock volume. Watch GCC customs authority alignment talks as an inflection indicator for consolidated import standard implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Biosecurity Certification Investment | MOCCAE and SFDA compliance documentation creates defensible positioning against informal import channels. |
| Artisan Training Pipeline Formalization | Johannesburg and Dubai workshop infrastructure addresses succession planning gaps as founding practitioners age. |
| LED Grow System Distribution Partnership | Climate-controlled cultivation technology enables temperate species penetration into Arabian Peninsula interiors. |
| Pre-Bonsai Digital Platform Launch | Hybrid appointment systems combining online specimen viewing with in-person wiring demonstrations capture fragmented purchasing behavior. |
| Substrate Blending Facility Acquisition | In-house akadama-pumice-organic mixture production reduces import dependency and margin compression exposure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade records, nursery association membership directories, and regulatory filing databases. Primary interviews engaged bonsai master artisans, garden center procurement managers, landscape architecture firm principals, and phytosanitary certification officers across the United Arab Emirates, Saudi Arabia, and South Africa. Secondary validation drew from DALRRD enforcement bulletins, GCC customs harmonization working papers, and horticultural substrate import manifests. Bottom-up cultivation stock inventories and top-down regional demand estimation were triangulated against cross-referenced channel shipment data.
Segmentation dimensions modeled include product type, tree species, distribution channel, and customer archetype across the projection horizon. CAGRs were derived from specimen transaction velocity analysis and installed base maintenance contract renewal patterns. Cultivation timeline compression from controlled-environment agriculture adoption and biosecurity compliance cost trajectories constituted industry-specific forecast inputs.
Forecasts assume regulatory continuity in UAE MOCCAE and Saudi SFDA phytosanitary regimes; material policy shifts would require re-modeling of import channel economics and distributor working capital requirements. Recalibration cycles align with material shifts in GCC biosecurity harmonization negotiations and artisan demographic turnover rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market